
 Acrylic Polymer Emulsion Market | 2026-2036
Acrylic Polymer Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Polymer Emulsion Market Analysis
China is reconfiguring acrylic polymer emulsion supply chains through expanded waterborne resin capacity serving domestic coatings producers. BASF SE leverages integrated acrylic acid-to-emulsion production complexes across Asia-Pacific manufacturing zones. Dow Inc. anchors North American supply through proprietary all-acrylic and styrene-acrylic latex technologies for architectural coatings. Arkema SA specializes in high-performance emulsion polymers for pressure-sensitive adhesives and construction sealants.
Acrylic polymer emulsion denotes a stable colloidal dispersion of acrylic resin particles in water, typically synthesized via free-radical emulsion polymerization at 40-60% solids content, functioning primarily as a film-forming binder in coatings, adhesives, and sealant formulations. The paints and coatings category dominates volume consumption as architectural specification shifts from solvent-borne to waterborne systems across residential and commercial building programs. Adhesives and sealants represent the fastest-expanding product type, driven by automotive lightweighting and flexible packaging lamination requirements that demand pressure-sensitive and heat-seal acrylic formulations.
EPA VOC regulations in the United States, REACH chemical registration in Europe, and China's MEE environmental standards collectively mandate reduced solvent content in architectural and industrial coatings, directly accelerating waterborne acrylic emulsion substitution. BIS certification requirements in India and GB standards enforcement through SAMR in China further constrain non-compliant import access and domestic production. Stakeholders must monitor regulatory divergence between jurisdictions as formulation compliance costs diverge and local supply qualifications harden.
Market Dynamics
The architectural coatings sector is undergoing a forced transition from solvent-borne to waterborne systems as VOC regulations tighten across major manufacturing jurisdictions, compressing formulation windows and elevating acrylic emulsion specifications.
Growth Catalysts
- REACH chemical registration:EU Green Deal mandates are accelerating reformulation investments toward low-VOC acrylic systems in European architectural coatings.
- China's building sector:Interior and exterior coating applications are scaling consumption of waterborne acrylic emulsions for residential and commercial construction.
- Automotive lightweighting:Pressure-sensitive adhesive specifications for flexible packaging lamination are expanding demand for heat-seal acrylic formulations.
Market Restraints
- Propylene feedstock volatility:Acrylic acid monomer costs fluctuate with crude oil derivatives, squeezing emulsion producer margins unpredictably.
- Asian supply concentration:Waterborne resin capacity expansion in China creates dependency risk for coatings formulators elsewhere.
- Performance ceiling:Waterborne acrylics still lag solvent-borne systems in certain industrial corrosion resistance applications.
Strategic Opportunities
- India's BIS certification pathway:Import qualification requirements are creating captive supply opportunities for domestic emulsion producers.
- Construction sealant convergence:Hybrid silicone-acrylic formulations are opening specification windows in high-performance building envelopes.
- MEE environmental standards:China's enforcement mechanisms are disqualifying non-compliant imports, hardening local supply positions.
Industry Challenges
- Emulsion polymerization expertise:Free-radical process control and particle size distribution optimization require scarce specialized chemical engineering talent.
- Multi-jurisdiction compliance:Divergent VOC thresholds between EPA, REACH, and GB standards force parallel formulation tracks, elevating R&D overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Polymer Emulsion Market |
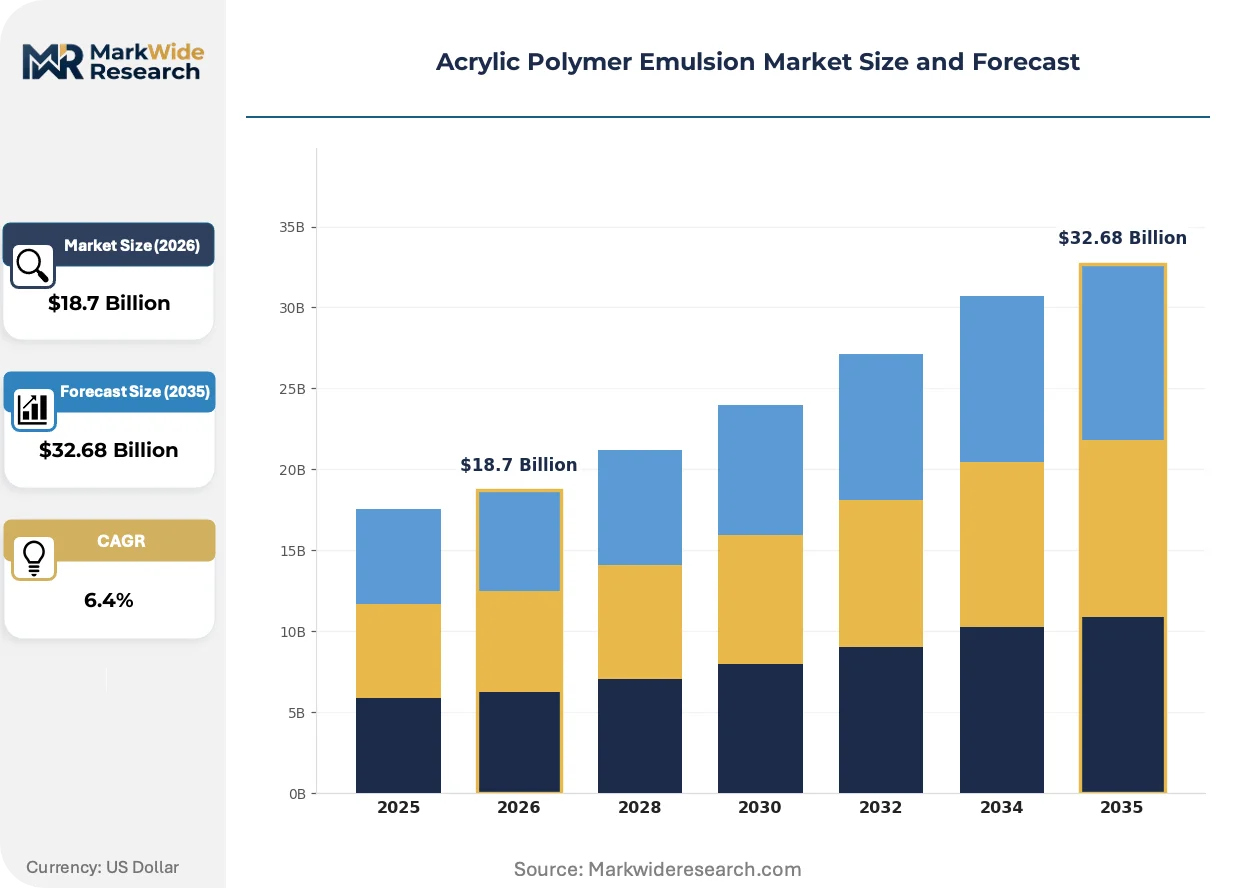
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paints, Coatings, Adhesives, Sealants End Use Industry: Construction, Automotive, Textiles, Consumer Goods Formulation: Waterborne, Solvent-based, High Solid, Powdered Application Area: Interior, Exterior, Industrial, Decorative |
| Companies Covered | Synthomer PLC, Covestro AG, BASF SE, Henkel AG & Co. KGaA, DIC Corporation, Dow Inc., Celanese Corporation, The Lubrizol Corporation, Arkema SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Polymer Emulsion Market Emerging Trajectories
Reformulation pressures are compressing development cycles as coatings manufacturers race to qualify waterborne alternatives ahead of regulatory deadlines across North America, Europe, and Asia-Pacific.
Core-shell acrylic latex technology is collapsing the performance gap between waterborne and solvent-borne coatings in metal protection applications. Automotive refinishing shops in Germany and Japan are adopting these systems for basecoat-clearcoat applications previously reserved for high-solids solvent formulations. The technology is collapsing premium pricing tiers that historically separated architectural from industrial-grade emulsions.
EPA VOC regulations in the United States are mandating reduced solvent content in architectural and industrial coatings through enforceable emissions limits. Coatings manufacturers are responding by qualifying all-acrylic and styrene-acrylic latex binders across residential and commercial building programs. The industrial maintenance segment faces the steepest compliance curve as existing solvent-borne specifications resist direct substitution.
Specification-driven procurement is consolidating buyer power as large construction and automotive OEMs centralize coatings qualification across multinational project portfolios. Regional distributors are losing specification influence to direct technical partnerships between emulsion producers and end-use formulators. This pattern is most pronounced in China's building sector, where state-backed developers mandate pre-qualified waterborne systems at scale.
Acrylic Polymer Emulsion Market Segmentation
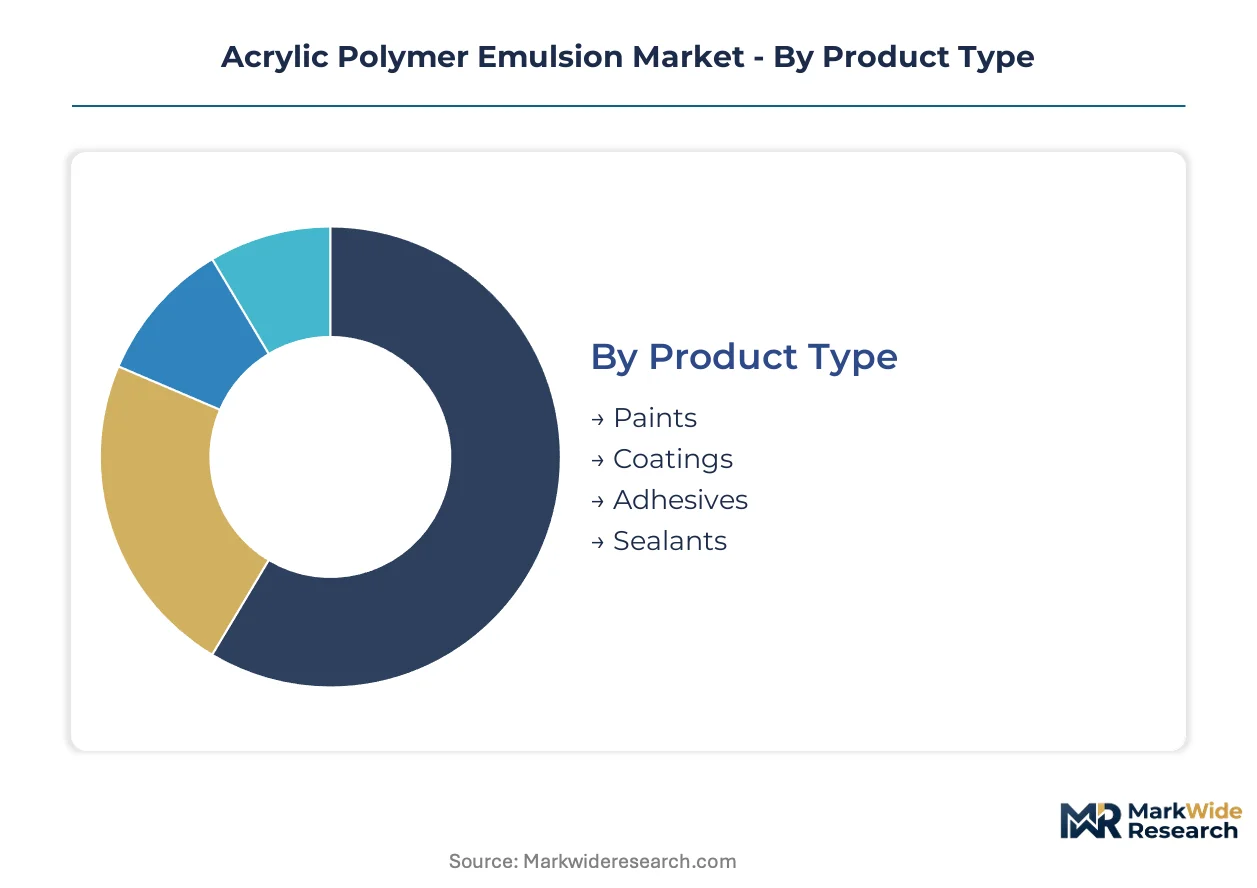
Acrylic polymer emulsion segmentation reveals how formulation chemistry, end-use performance requirements, and application environments create distinct supply-demand configurations across the value chain. Understanding these boundaries helps identify where specification premiums concentrate and where commoditization pressures dominate procurement negotiations.
Product Type:
Mature architectural applications anchor volume, while emerging adhesive technologies command the steepest specification premiums in automotive and packaging laminates.
- Paints:All-acrylic and styrene-acrylic latex binders serve interior and exterior architectural specifications, with waterborne systems displacing alkyd formulations in residential repainting cycles across Germany and Japan. EPA VOC limits in the United States and REACH compliance windows in Europe compress formulation timelines for coatings manufacturers.
- Adhesives:Pressure-sensitive and heat-seal acrylic emulsions enable flexible packaging lamination and automotive lightweighting assemblies. Demand concentrates with German and Japanese automotive refinishing shops adopting basecoat-clearcoat waterborne systems previously reserved for high-solids solvent formulations.
- Coatings:Industrial maintenance and protective applications where core-shell latex technology narrows the performance gap with solvent-borne corrosion resistance.
- Sealants:Construction joint fillers and hybrid silicone-acrylic formulations for high-performance building envelopes in commercial and infrastructure projects.
Paints retain volume leadership; adhesives hold the steepest expansion curve.
End Use Industry:
Construction absorbs the bulk of emulsion tonnage, though automotive specification complexity generates the highest margin capture per kilogram applied.
- Construction:Interior and exterior coating applications scale waterborne acrylic consumption across residential and commercial building programs in China, where state-backed developers mandate pre-qualified systems. BIS certification requirements in India and GB standards enforcement through SAMR constrain non-compliant import access.
- Automotive:Pressure-sensitive adhesive specifications for flexible packaging lamination and refinishing basecoats demand heat-seal acrylic formulations with precise viscosity and solids control. German and Japanese OEM qualification protocols drive technical partnerships between emulsion producers and tier suppliers.
- Textiles:Fabric finishing and nonwoven bonding applications where hand-feel and wash durability specifications vary by end-market.
- Consumer Goods:Label adhesives, DIY coatings, and packaging applications with price-sensitive procurement and shorter qualification cycles.
Construction dominates absolute volume; automotive commands the highest value-per-ton realization.
Formulation:
Waterborne systems capture regulatory tailwinds, while high-solid and powdered alternatives address performance gaps in corrosion-critical and specialty applications.
- Waterborne:Stable colloidal dispersions at 40-60% solids content function as film-forming binders in architectural coatings and adhesives. EPA VOC regulations, REACH chemical registration, and China's MEE environmental standards mandate reduced solvent content, accelerating substitution across North America, Europe, and Asia-Pacific.
- Solvent-based:Residual demand persists in industrial corrosion resistance applications where waterborne acrylics lag performance ceilings, particularly in marine and chemical processing equipment coatings.
- High Solid:Reduced solvent content with maintained performance for compliance-constrained industrial maintenance segments facing steep substitution curves.
- Powdered:Specialty applications requiring transport efficiency and extended shelf stability in remote construction and infrastructure projects.
Waterborne formulations absorb regulatory displacement; high-solid alternatives defend niche industrial positions.
Application Area:
Interior specifications prioritize low-odor and rapid dry-to-touch properties, while exterior and industrial segments demand weathering resistance and substrate adhesion under mechanical stress.
- Interior:Residential and commercial wall coatings where low-VOC emissions and aesthetic finish quality drive specification. Chinese building sector uptake concentrates demand as interior coating applications scale across residential construction.
- Exterior:Facade and cladding systems requiring UV resistance, hydrophobicity, and crack-bridging elasticity across freeze-thaw cycles. European REACH and EU Green Deal compliance push reformulation toward low-VOC acrylic systems with extended durability warranties.
- Industrial:Metal protection, flooring, and equipment coatings where core-shell acrylic latex technology collapses premium pricing tiers between architectural and industrial-grade emulsions.
- Decorative:Specialty finishes, textured coatings, and artisan applications with customized aesthetic specifications and smaller batch requirements.
Exterior applications anchor value-based procurement; industrial coatings are expanding most quickly as waterborne performance thresholds advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE environmental standards in China anchor regulatory momentum across the acrylic polymer emulsion landscape. EPA VOC limits in the United States and REACH chemical registration in Europe create parallel compliance windows that reshape formulation requirements. Construction sector expansion and automotive refinishing specifications concentrate demand in specific national markets.
China
State-backed developers mandate pre-qualified waterborne systems across residential and commercial building programs. MEE enforcement mechanisms disqualify non-compliant imports while GB standards through SAMR harden local supply positions. Yangtze River Delta resin capacity expansion serves domestic coatings producers reconfiguring supply chains.
United States
Architectural coatings manufacturers qualify all-acrylic and styrene-acrylic latex binders under enforceable EPA emissions limits. Industrial maintenance segments face steep compliance curves as existing solvent-borne specifications resist direct substitution. Gulf Coast petrochemical corridors anchor acrylic acid monomer production feeding emulsion complexes.
Germany
Automotive refinishing shops adopt core-shell acrylic latex systems for basecoat-clearcoat applications previously reserved for high-solids solvent formulations. EU Green Deal mandates accelerate reformulation investments toward low-VOC acrylic systems in architectural coatings. Rhine-Ruhr industrial clusters concentrate pressure-sensitive adhesive specifications for flexible packaging lamination.
India
BIS certification requirements create captive supply opportunities for domestic emulsion producers as import qualification barriers harden. Construction sector uptake scales waterborne acrylic consumption across interior and exterior coating applications. Maharashtra and Gujarat industrial corridors attract capacity investments serving regional coatings formulators.
Japan
Automotive OEM qualification protocols drive technical partnerships between emulsion producers and tier suppliers for heat-seal acrylic formulations. METI industrial standards shape pressure-sensitive adhesive specifications in flexible packaging applications. Kansai and Chubu manufacturing zones concentrate refinishing basecoat adoption of waterborne systems.
Acrylic Polymer Emulsion Market Vendor Landscape
Capability concentration sits with integrated petrochemical majors; scale advantage sits with specialized emulsion polymerization houses. The vendor base organizes around three strategic archetypes: backward-integrated acrylic acid producers, latex technology specialists, and hybrid silicone-acrylic formulators. Dominant competitive moves include capacity expansion in Asia-Pacific manufacturing zones and strategic partnerships between resin producers and coatings formulators.
Among European-integrated chemical majors, BASF SE and Covestro AG exemplify the backward-integrated archetype controlling acrylic acid-to-emulsion value chains. Arkema SA occupies a position within the high-performance specialty tier, anchoring pressure-sensitive adhesive and construction sealant applications. Dow Inc. represents North American latex technology leadership through proprietary emulsion polymerization platforms.
| Leading Market Players |
|---|
| Synthomer PLC |
| Covestro AG |
| BASF SE |
| Henkel AG & Co. KGaA |
| DIC Corporation |
| Dow Inc. |
| Celanese Corporation |
| The Lubrizol Corporation |
| Arkema SA |
| Others |
Supply Flow & Price Mechanics
Propylene feedstock volatility determines both pricing tier spreads and supply chain shape in acrylic polymer emulsions, compressing margins at the monomer conversion stage while forcing formulators toward long-term offtake contracts with integrated producers.
Pricing Analysis
Price spreads between Asia-Pacific and North American emulsion grades reflect freight differentials and regional acrylic acid capacity imbalances. Three-tier pricing structure across performance-grade emulsions, commodity architectural binders, and specialty pressure-sensitive adhesive formulations segments buyer portfolios. Pricing pressure stems from Chinese waterborne resin oversupply eroding export quotations. Small-to-mid coatings formulators exhibit acute price sensitivity, while automotive OEMs prioritize specification compliance over unit cost.
Supply Chain Analysis
Upstream acrylic acid production anchors in China, the United States, and Germany, with propylene derivatives feeding integrated emulsion complexes. Feedstock dependencies span crude oil derivatives, caustic soda, and specialty surfactants for particle stabilization. Single-source vulnerability concentrates around Yangtze River Delta resin capacity serving regional coatings clusters. Distribution runs through direct technical partnerships between emulsion producers and large formulators, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylic polymer emulsion incumbents face sustained substitution pressure from polyurethane dispersions in high-performance coatings, requiring defensive repositioning around regulatory-compliant waterborne systems.
For Market Incumbents: Harden supply positions through backward integration into acrylic acid monomer production or captive offtake agreements with Gulf Coast and Rhine-Ruhr petrochemical corridors. Deepen formulation partnerships with automotive OEMs to lock out polyurethane dispersion substitution in refinishing applications. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified domestic supply gap, where import qualification barriers create protected market access. Target construction sealant hybrid formulations as the most penetrable specification tier, leveraging technical service capabilities to displace established European suppliers. For Investors and Strategic Acquirers: Specialty emulsion polymerization houses with pressure-sensitive adhesive expertise represent the most defensible acquisition profile. Monitor automotive lightweighting procurement shifts as the inflection signal for adhesive-grade emulsion demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylic acid supply insulates margin compression from propylene volatility. |
| Green Manufacturing Transition | Low-VOC process investments align with EU Green Deal and EPA compliance windows. |
| Long-term Supply Agreement | Direct partnerships with state-backed Chinese developers secure volume commitments. |
| Joint Venture | Regional production sharing with Indian domestic producers satisfies BIS certification requirements. |
| Capacity Expansion | Yangtze River Delta resin additions serve Asia-Pacific coatings supply chain reconfiguration. |
Methodological Framework
Desk research of customs trade data, SEC chemical sector filings, and ECHA REACH registration databases preceded structured interviews with emulsion plant managers, coatings procurement leads at construction developers, automotive OEM specification engineers, and pressure-sensitive adhesive R&D directors. Primary intelligence combined with ACC and Cefic industry statistics enabled bottom-up and top-down triangulation across volume and value estimates.
Assumptions held fixed include current EPA VOC enforcement intensity, EU Green Deal implementation trajectory, and China's MEE environmental standard adherence. The analytical framework modeled segmentation across formulation chemistry, end-use industry, and application environment throughout the forecast period. CAGRs derived from production capacity expansion announcements, regulatory compliance timeline analysis, and substitution elasticity estimates for solvent-borne systems.
Sensitivities concentrate around propylene feedstock price shocks, automotive OEM qualification protocol changes, and regulatory enforcement divergence between jurisdictions. Cross-checking against customs import-export statistics and regional coatings production surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Smart Polymers Market
Polymers & Resins
Flexible Polymer Foam Market