
 Global PU Films Market | 2026-2036
Global PU Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global PU Films Market Outlook
Direct-to-manufacturer supply agreements is rewriting how PU films move from resin producers to end converters. Covestro AG leverages its backward integration into polyol chemistry to sustain margin control across TPU film grades. Huntsman International LLC anchors North American medical film supply through specialized cast lines certified for healthcare applications.
Polyurethane films are elastomeric sheet materials typically ranging from 12 to 250 micrometers in thickness, manufactured from polyester or polyether polyols chain-extended with diisocyanates to deliver puncture resistance, breathability, and flex fatigue performance for bonding, protection, and barrier applications. Cast film technology dominates high-clarity medical and automotive segments where thickness tolerance below 5% is required, while blown film lines serve cost-sensitive packaging applications with wider gauge variation. Polyester-based PU films command premium positioning in textile laminates for outdoor apparel due to hydrolysis resistance, whereas biodegradable formulations are gaining fastest traction among European consumer goods brands facing EPR obligations.
REACH registration requirements and the EU MDR are forcing reformulation of plasticizers and stabilizers in films destined for European medical and consumer applications. EPA TSCA Section 5 notifications and FDA 21 CFR 177.1680 compliance govern polyurethane food-contact and device-grade film entry into United States markets. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions in both jurisdictions, as these compound how PU film producers select release liners and surface treatments without sacrificing weldability or biocompatibility certification.
Market Dynamics
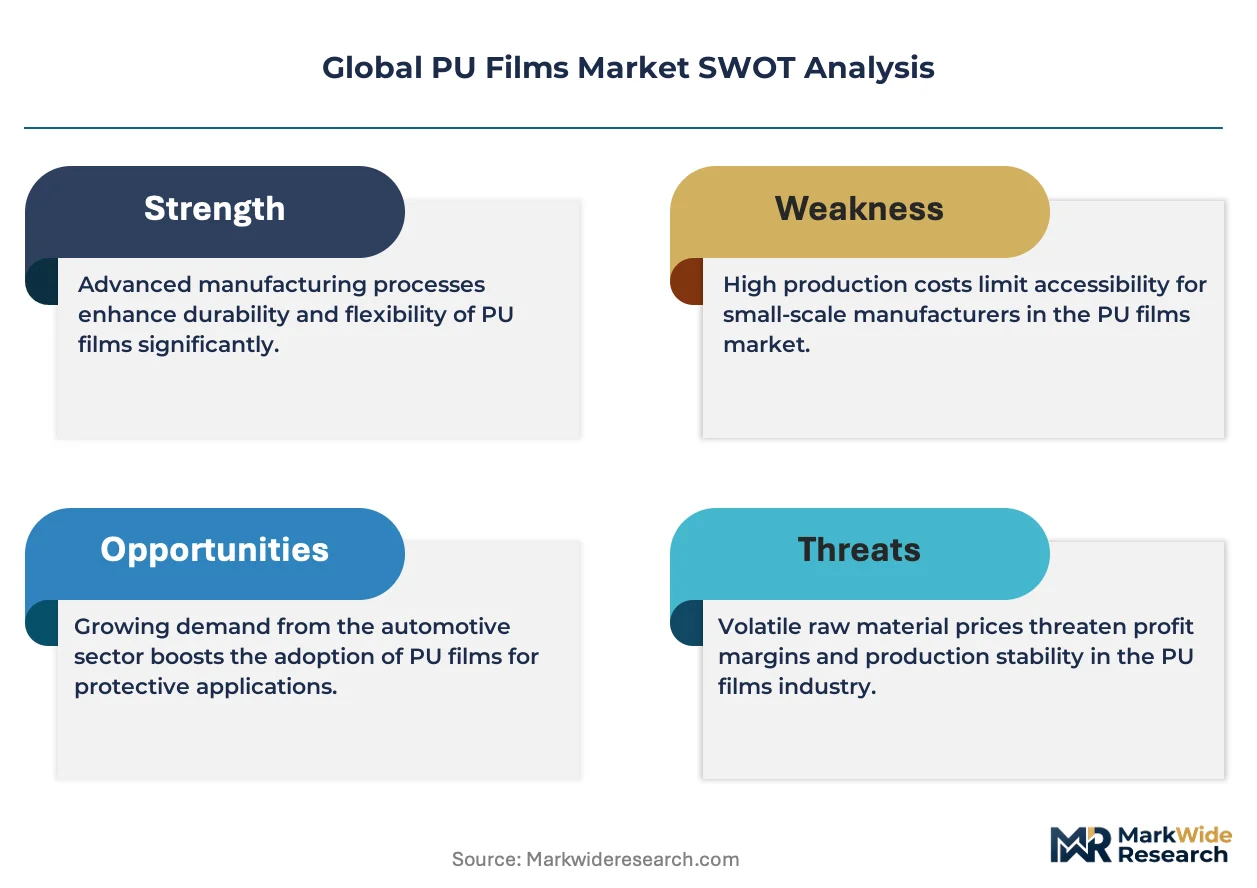
Direct-to-manufacturer supply agreements are compressing distributor margins across the PU films value chain, while REACH and EU MDR compliance costs are forcing reformulation investments that favor integrated resin-to-film producers with captive polyol supply.
Growth Catalysts
- Medical device procurement:German and US wound care manufacturers are expanding polyurethane film specifications for surgical drapes and transparent wound dressings under stricter biocompatibility protocols.
- REACH registration:Material traceability mandates across European supply chains are accelerating consolidation toward producers with certified polymer documentation systems.
- Electric vehicle seating:Chinese automotive interior producers are scaling TPU film consumption for lightweight, recyclable seating solutions in domestic EV programs.
Market Restraints
- Diisocyanate cost volatility:MDI and TDI feedstock price swings compress margin predictability for non-integrated film extruders lacking backward integration into polyol chemistry.
- Supplier concentration:Asia-Pacific polyether polyol production clusters create geographic single-source vulnerability for European and North American film converters.
- Biodegradable performance gap:Current compostable PU formulations exhibit inferior hydrolysis resistance versus polyester-based standards, limiting outdoor textile laminate adoption.
Strategic Opportunities
- India automotive growth:Underpenetrated TPU film usage in domestic two-wheeler seating and interior trim offers expansion potential as PLI scheme incentives localize component supply.
- EPR-driven biodegradable demand:Extended producer responsibility frameworks in France and Germany are creating mandated pull for compostable film alternatives in consumer goods packaging.
- Cast-blown hybrid lines:Technology convergence combining thickness precision with cost efficiency enables mid-tier producers to serve both medical clarity and industrial barrier segments.
Industry Challenges
- ISO 10993 certification timelines:Medical-grade film qualification cycles extending 18-24 months strain working capital for converters entering healthcare supply chains.
- Legacy equipment retrofit costs:Blown film lines require substantial capital reinvestment to meet sub-5% thickness tolerance demands from automotive and medical buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PU Films Market |
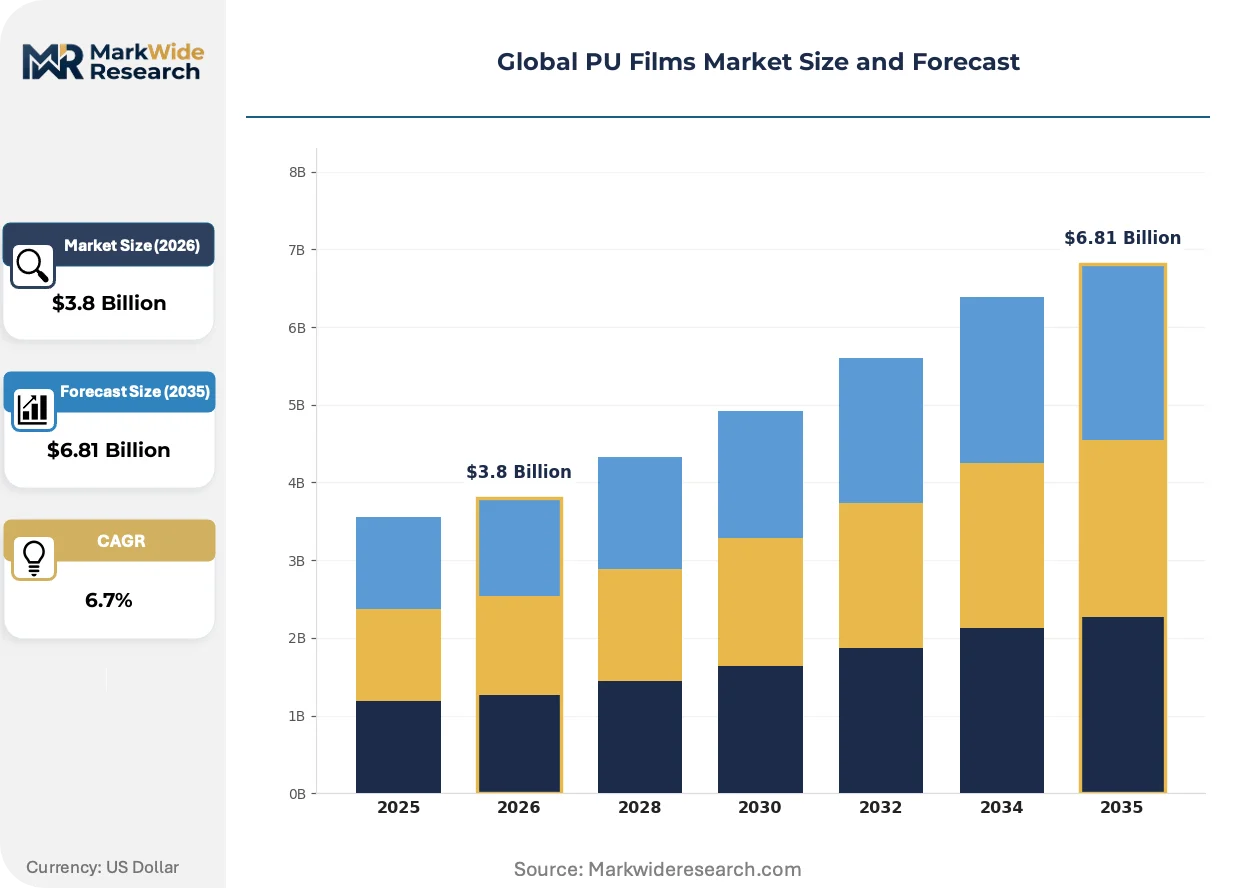
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyether, Biodegradable, TPU Application: Packaging, Automotive, Medical, Textile End User: Manufacturing, Construction, Healthcare, Consumer Goods Technology: Cast Film, Blown Film, Coextruded Film, Others |
| Companies Covered | Covestro AG, SWM International, 3M Company, Avery Dennison Corporation, DingZing Advanced Materials Inc, Huntsman International LLC, The Lubrizol Corporation, BASF SE, Permali Gloucester Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PU Films Market Strategic Shifts
Waterborne PU dispersion coating technologies are disrupting solvent-based lamination processes across textile and automotive applications, while regulatory pressure on per- and polyfluoroalkyl substances is forcing innovation in release liner chemistry.
Reactive hot-melt polyurethane adhesives are eliminating solvent-based lamination in automotive interior assembly. Tier-1 seating suppliers in Germany and the US Midwest are converting assembly lines to eliminate VOC emissions compliance costs. This bonding technology is rendering obsolete conventional solvent-activated film attachment methods that require extended drying cycles and enclosed ventilation infrastructure.
ECHA restrictions on PFAS in food-contact and medical applications are compelling reformulation of release liners and surface treatments. Film producers serving European wound care and surgical drape markets must qualify fluorine-free alternatives without sacrificing weldability or biocompatibility certification. FDA 21 CFR 177.1680 compliance pathways for these reformulated products remain underdeveloped, creating competitive advantage for early movers with validated submission packages.
Automotive OEMs are consolidating film procurement through single-source master service agreements that bundle material supply with die-cutting and logistics services. Tier-2 converters in China and Mexico are losing direct supplier status as seating integrators internalize these functions to capture margin and reduce qualification overhead. This consolidation pattern is most visible in electric vehicle programs where platform standardization accelerates supplier rationalization decisions.
Global PU Films Market Segmentation
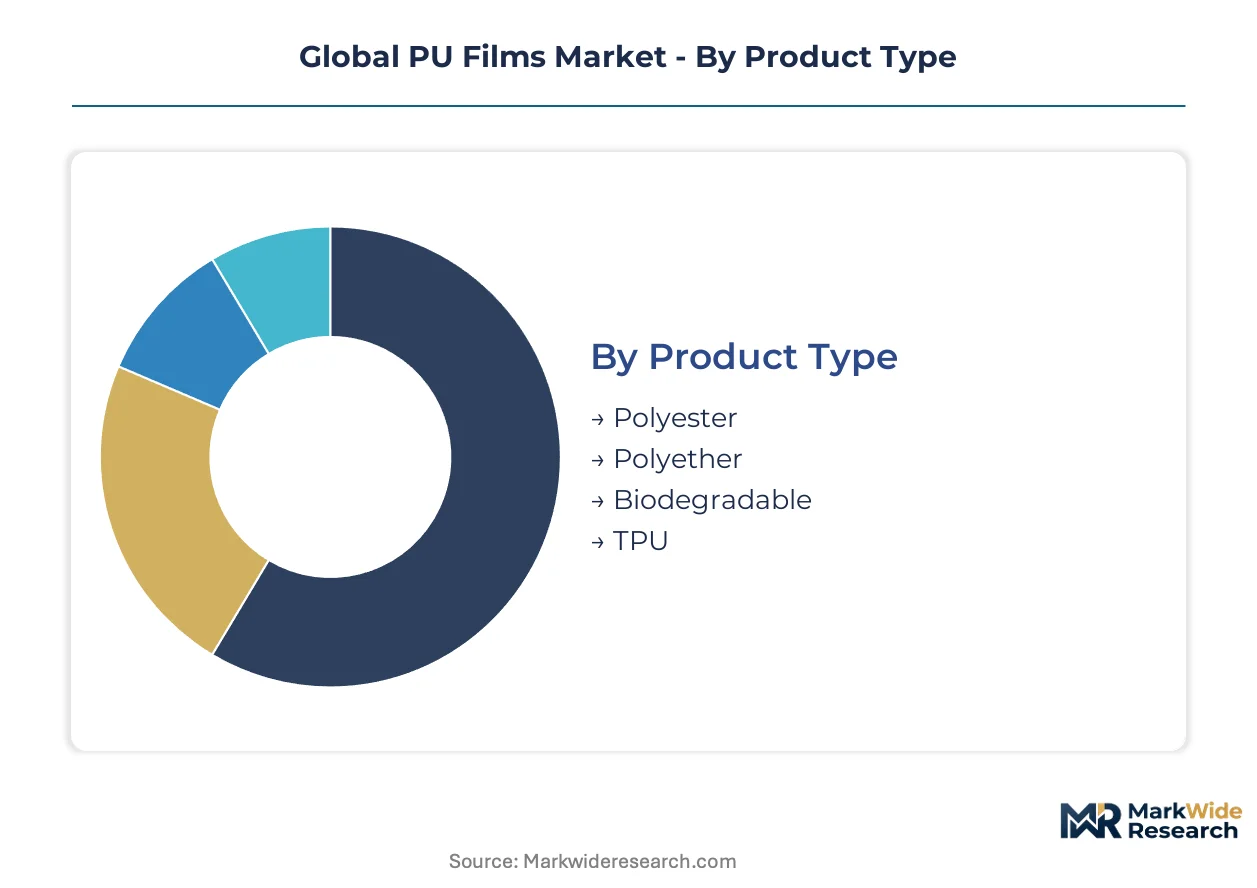
Segmentation in the PU films market reveals divergent margin structures and qualification barriers across chemistry types and conversion technologies. Manufacturers configure production assets around specific thickness tolerances and biocompatibility certifications rather than pursuing universal coverage.
Product Type:
Mature polyester and polyether chemistries dominate current volume, while biodegradable formulations represent an emerging tier reshaped by European regulatory mandates.
- Polyester:Manufactured from aromatic diisocyanates and ester-based polyols, these films deliver superior hydrolysis resistance and mechanical strength for outdoor textile laminates. German and Italian outdoor apparel brands specify polyester PU films for waterproof-breathable membranes under extended warranty programs.
- Polyether:Built on ether-linked polyol backbones, polyether films exhibit lower glass transition temperatures and enhanced low-temperature flexibility for automotive interior applications. Chinese EV seating suppliers are expanding polyether TPU film procurement for recyclable lightweight seat covers.
- Biodegradable:Aliphatic polyester formulations designed for industrial composting face performance gaps in hydrolysis resistance versus conventional grades. French consumer goods brands facing EPR obligations are piloting these films in single-use packaging despite higher unit costs.
- TPU:Thermoplastic polyurethane films span both polyester and polyether chemistries with enhanced melt processability for coextrusion and overmolding operations.
Polyester handles the majority of throughput; biodegradable is expanding most quickly on share as regulatory deadlines approach.
Application:
Application segments separate by certification intensity, with medical and automotive demanding sub-5% thickness tolerance while packaging tolerates wider gauge variation.
- Packaging:Cost-sensitive industrial and consumer packaging applications utilize blown film technology with wider thickness tolerances. European food-contact applications face escalating ECHA scrutiny on PFAS in release liners.
- Automotive:Seating, interior trim, and surface protection films require weldability, fogging resistance, and VOC compliance under OEM specifications. German and US Midwest tier-1 suppliers are converting to reactive hot-melt adhesive bonding to eliminate solvent drying infrastructure.
- Medical:Surgical drapes, wound dressings, and device components demand ISO 10993 biocompatibility certification and FDA 21 CFR 177.1680 compliance. German manufacturers are expanding cast film capacity to serve EU MDR traceability requirements.
- Textile:Lamination films for outdoor apparel, sportswear, and technical textiles prioritize hydrolysis resistance and seam sealing performance.
Medical commands the steepest margin premium; automotive is climbing the fastest as EV platform standardization accelerates material specification consolidation.
End User:
End user concentration varies by capital intensity and qualification cycle length, with healthcare and automotive representing the most defensible customer relationships.
- Manufacturing:Industrial converters and component suppliers purchase PU films for bonding, protection, and process aid applications across electronics and machinery sectors.
- Construction:Waterproofing membranes, vapor barriers, and protective films for building envelope applications specify UV-stabilized grades with extended service life requirements.
- Healthcare:Medical device manufacturers and healthcare distributors drive demand for certified film grades with documented polymer traceability. FDA and EU MDR compliance costs are forcing consolidation toward integrated resin-to-film suppliers.
- Consumer Goods:Apparel, footwear, and personal care brands are sourcing biodegradable alternatives under French and German EPR frameworks.
Healthcare generates the highest customer lifetime value; consumer goods is gaining share fastest as sustainability mandates reshape procurement criteria.
Technology:
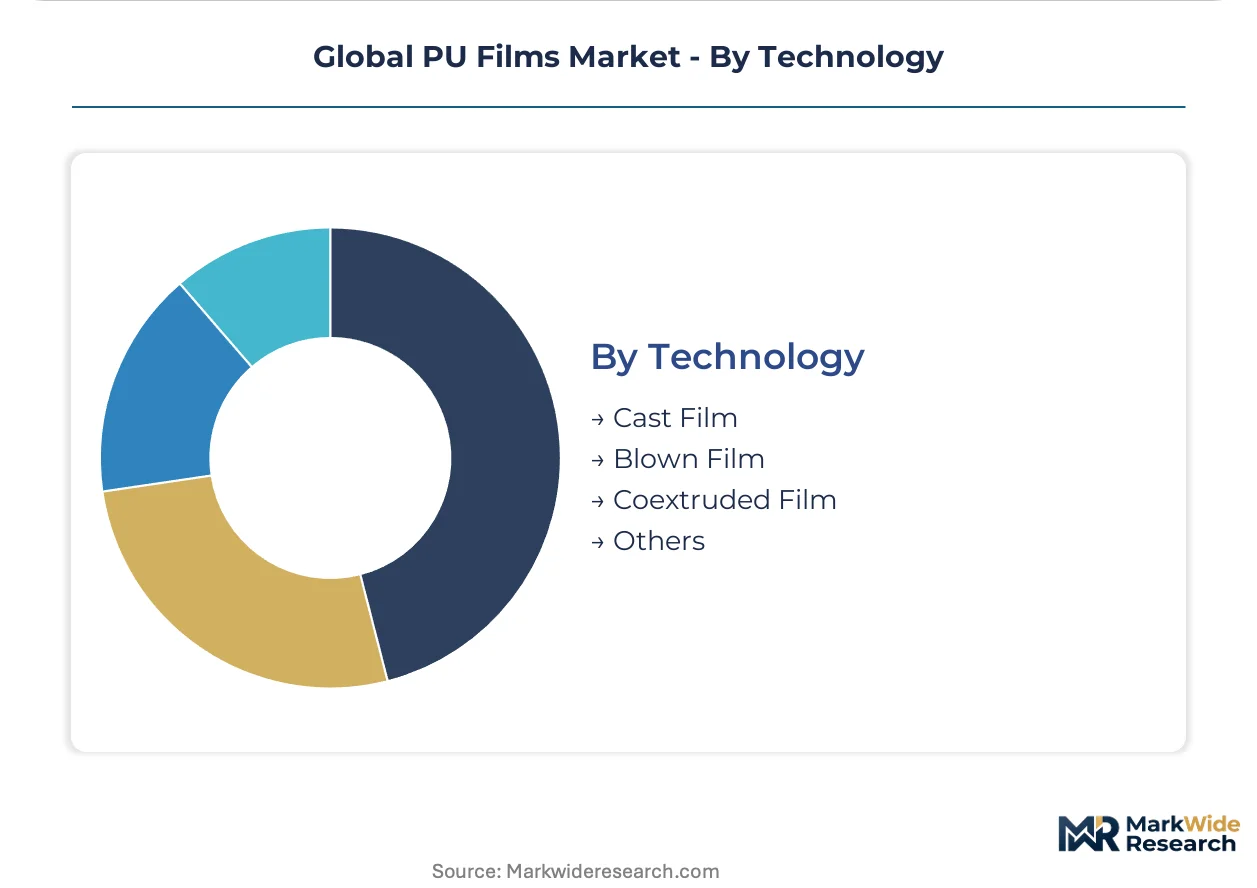
Technology selection determines capital requirements and addressable market scope, with cast film lines requiring precision tooling for medical clarity segments.
- Cast Film:Solvent or solvent-free casting onto release liners achieves sub-5% thickness tolerance and optical clarity for medical and premium automotive applications. German producers operate specialized cast lines certified for healthcare supply chains.
- Blown Film:Tubular extrusion with air cooling serves cost-sensitive packaging and industrial barrier markets with wider gauge acceptance. Legacy blown lines face retrofit costs to meet automotive thickness specifications.
- Coextruded Film:Multi-layer structures combine dissimilar chemistries for functional gradients in adhesion, barrier, or surface properties.
- Others:Calendering and solution coating methods serve niche applications in textile lamination and specialty adhesive films.
Cast film captures the dominant share of value; coextruded technology is advancing fastest as multi-functionality requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration requirements and the EU MDR are tightening material traceability mandates across European supply chains, while Chinese EV programs and US medical device procurement are reshaping demand geography.
Germany
Medical device manufacturers in Baden-Württemberg and Bavaria are expanding cast film capacity for surgical drapes and wound dressings. EU MDR traceability rules favor producers with certified polymer documentation systems. Covestro AG leverages backward integration into polyol chemistry from its Leverkusen operations to sustain margin control across TPU film grades.
United States
Huntsman International LLC anchors North American medical film supply through specialized cast lines certified for healthcare applications in the Midwest. FDA 21 CFR 177.1680 compliance governs polyurethane food-contact and device-grade film entry. EPA TSCA Section 5 notifications compound qualification overhead for converters entering healthcare supply chains.
China
Domestic automotive seating and interior producers in the Yangtze River Delta are scaling TPU film consumption for electric vehicle programs. MIIT dual carbon goals accelerate lightweight, recyclable seating solutions. Polyether polyol production clusters create geographic sourcing concentration for film converters serving domestic OEMs.
France
Consumer goods brands facing EPR obligations are piloting biodegradable PU films in single-use packaging despite higher unit costs. ECHA restrictions on PFAS in food-contact applications are compelling reformulation of release liners. Industrial clusters around Lyon and Paris are testing compostable alternatives under national extended producer responsibility frameworks.
India
Underpenetrated TPU film usage in domestic two-wheeler seating and interior trim offers expansion potential as PLI scheme incentives localize component supply. BIS standards govern material specifications for automotive applications. Manufacturing corridors in Maharashtra and Gujarat are attracting film converters seeking to serve domestic OEMs.
Global PU Films Market Competitive Environment
Integrated resin-to-film producers and specialized cast-line operators split the market between margin-defended premium grades and cost-sensitive industrial volumes. The vendor base concentrates around producers with captive polyol supply or certified healthcare production assets. Three archetypes dominate: backward-integrated chemical conglomerates, medical-grade specialists with ISO 10993 certification infrastructure, and regional converters serving packaging and textile lamination. Competitive moves center on M&A to secure polyol supply and capacity expansion in medical-certified cast film lines.
Among German chemical conglomerates, Covestro AG and BASF SE exemplify the backward-integrated archetype with in-house polyol production. Huntsman International LLC occupies a position among North American medical-grade specialists. DingZing Advanced Materials Inc represents the Asia-Pacific converter tier serving automotive and industrial segments.
| Leading Market Players |
|---|
| Covestro AG |
| SWM International |
| 3M Company |
| Avery Dennison Corporation |
| DingZing Advanced Materials Inc |
| Huntsman International LLC |
| The Lubrizol Corporation |
| BASF SE |
| Permali Gloucester Limited |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in European cast film lines serving medical-grade specifications is compressing supplier flexibility and hardening price posture for ISO 10993-certified grades. German and US converters with captive polyol supply are leveraging feedstock control to defend margin structures against volatile MDI and TDI input costs.
Pricing Analysis
Geographic price spreads between German medical-grade cast film and Chinese blown film packaging grades exceed three-to-one multiples. Three-tier pricing structure across medical-certified, automotive-performance, and industrial-packaging levels separates buyers by certification burden and thickness tolerance requirements. Price differentiation hinges on ISO 10993 biocompatibility tier and REACH documentation completeness. Pricing pressure stems from diisocyanate cost volatility squeezing non-integrated extruders, while medical device manufacturers show lowest price sensitivity due to 18-24 month qualification lock-in.
Supply Chain Analysis
Upstream MDI and polyether polyol production clusters in China, Germany, and the United States anchor global resin availability for film extrusion. Polyol chemistry, diisocyanate feedstocks, and release liner substrates constitute critical input dependencies. Single-source vulnerability concentrates in Asia-Pacific polyether polyol supply serving European and North American converters. Distribution runs through direct-to-manufacturer master service agreements that bundle material supply with die-cutting and logistics, displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global PU films demand sits in early-cycle expansion as electric vehicle platform standardization accelerates material specification consolidation and medical device traceability mandates deepen supplier qualification barriers.
For Market Incumbents: Entrench position through backward integration into polyol chemistry and certified cast line capacity additions in Germany or the US Midwest. Waterborne PU dispersion technologies threaten solvent-based lamination incumbents; reactive hot-melt adhesive bonding expertise represents a defensible capability moat. Priority rests on securing REACH-compliant polymer documentation systems ahead of EU MDR enforcement waves. For New Entrants and Emerging Players: Build out presence in India's underpenetrated two-wheeler seating segment where PLI scheme incentives localize component supply and BIS standards create navigable entry thresholds. Biodegradable film formulations for French and German EPR-driven consumer goods packaging offer white-space penetration with compostable chemistry differentiation. Go-to-market leverage centers on fluorine-free release liner qualification packages addressing ECHA PFAS restrictions. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across medical-certified cast film segments as ISO 10993 qualification infrastructure and sub-5% thickness tolerance tooling demands escalate. Five-to-ten year viability favors integrated resin-to-film producers with captive polyol supply and healthcare-certified production assets. Acquisition targets should display validated FDA 21 CFR 177.1680 submission packages. Signal to monitor: master service agreement consolidation patterns among automotive OEMs bundling material supply with downstream services.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Chemistry | Covestro AG leverages Leverkusen operations to sustain margin control across TPU film grades. |
| Medical-Certified Cast Line Expansion | German manufacturers in Baden-Württemberg are adding capacity to serve EU MDR traceability requirements. |
| Fluorine-Free Release Liner Qualification | ECHA PFAS restrictions in food-contact applications compel reformulation without sacrificing weldability certification. |
| Waterborne PU Dispersion Transition | Tier-1 seating suppliers in Germany and the US Midwest are eliminating VOC emissions compliance costs. |
| Direct-to-Manufacturer Supply Agreements | Automotive OEM consolidation patterns in Chinese EV programs accelerate supplier rationalization decisions. |
Study Parameters
A spread of perspectives from plant managers at integrated resin producers, procurement leads at German medical device OEMs, distribution channel partners serving textile lamination markets, and technical R&D directors at TPU compounders converged on the working assumptions. Primary fieldwork combined with secondary validation from customs and trade data, SEC 10-K filings of listed chemical conglomerates, REACH registration databases, and FDA 510(k) submission records. Bottom-up volume builds across chemistry types, conversion technologies, and end-use applications were triangulated against top-down macroeconomic demand indicators.
Demand-supply balance modeling across the projection horizon incorporated segmentation by chemistry type, application certification intensity, technology precision tier, and regional regulatory cluster. CAGR derivation rested on historical trajectory analysis, capacity utilization signals in cast versus blown film lines, and penetration rate assumptions for biodegradable formulations under EPR frameworks. Industry-specific forecast inputs included electric vehicle production ramp schedules and EU MDR implementation phase timelines.
Stress conditions across diisocyanate price volatility bands, REACH compliance cost escalation scenarios, and PFAS restriction enforcement timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about medical device qualification cycle durations and automotive platform standardization rates. Cross-checking against IHS Markit vehicle production databases and hospital procurement contract databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Jesmonite Market
Specialty Materials
Specialty Silica Market
Specialty Materials
Asia-Pacific Polyether Ether Ketone (Peek) Market
Specialty Materials
Epoxy Encapsulation Material Market
Specialty Materials
Elastic Films Market
Specialty Materials
Asia-Pacific Green Sic Market
Specialty Materials
Spermaceti Wax Market
Specialty Materials
Talc Alternatives Market
Specialty Materials
Polyimide Foam Market
Specialty Materials
Metalized Biaxially Oriented Polypropylene Films Market
Specialty Materials
Conductive Plastics Market
Specialty Materials
United States Neoprene Market
Specialty Materials
Rigid Polyurethane Foams Market
Specialty Materials
Europe Solar Control Window Films Market
Specialty Materials
Melamine Foam Market
Specialty Materials
Global Consumer Foam Market