
 North America Lime Market | 2026-2036
North America Lime Market Size, Share, and Industry Trends Forecast 2026-2036
North America Lime Market Outlook
Bulk-to-bagged packaging conversion is rebalancing procurement patterns across the North America lime market. Carmeuse leverages its Appalachian kiln network to sustain consistent supply to Appalachian steel mills. Graymont anchors western Canadian operations with vertically integrated quarry-to-kiln control. United States Lime & Minerals differentiates through specialized high-purity quicklime grades for chemical customers.
Lime encompasses calcium oxide and calcium hydroxide produced by calcining limestone at temperatures exceeding 900 degrees Celsius, yielding products with calcium content typically ranging from 90 to 98 percent for industrial grades. Quicklime commands the largest share of product type value given its irreplaceable role in steel fluxing and gold recovery circuits. Hydrated lime is gaining share fastest in water treatment applications across the US Sun Belt, where municipal infrastructure upgrades expand alkalinity adjustment demand. Soil stabilization applications in Texas and California highway projects represent a mature but volume-stable outlet for bulk quicklime.
EPA enforcement of National Ambient Air Quality Standards shapes lime demand through mandatory scrubber installations at coal-fired power plants and industrial boilers. OSHA permissible exposure limits for crystalline silica drive workplace handling protocols and dust control investments across quarry and kiln operations. State-level Department of Transportation specifications in California, Texas, and Illinois govern lime stabilization standards for road base construction. Stakeholders must monitor evolving mercury capture regulations and carbon border adjustment mechanisms that could restructure competitive dynamics between domestic kilns and imported material.
Market Dynamics
The North America lime market is being reshaped by EPA enforcement of Mercury and Air Toxics Standards, which mandates flue gas desulfurization systems and locks in structural demand for high-calcium lime reagents across coal-fired power generation and industrial boiler installations.
Growth Catalysts
- Steel fluxing demand:Great Lakes corridor steel manufacturers are expanding lime consumption for slag conditioning operations, creating sustained volume pull from metallurgical-grade quicklime suppliers.
- EPA MATS compliance:The agency's Mercury and Air Toxics Standards continue to require scrubber installations at coal-fired plants, embedding lime reagents into stationary source air pollution control infrastructure.
- Petrochemical processing:The US Gulf Coast corridor concentrates demand for lime in refinery sulfur recovery and chemical processing applications, anchoring regional kiln utilization rates.
Market Restraints
- Natural gas price volatility:Kiln operations depend on natural gas for calcination heat, exposing margins to Henry Hub price swings that compress producer economics during cold-weather demand spikes.
- Quarry reserve depletion:High-calcium limestone deposits in the Appalachian and Ozark regions face gradual quality degradation, forcing longer haul distances or lower-yield extraction.
- Alternative alkali substitution:Sodium-based reagents compete in select flue gas treatment applications, particularly where lime handling logistics prove prohibitive for smaller installations.
Strategic Opportunities
- Carbon capture integration:Direct air capture and post-combustion carbon capture projects in Texas and Louisiana are piloting lime-based sorbent loops, opening a prospective demand vertical.
- Municipal water infrastructure:Sun Belt cities are upgrading alkalinity adjustment capacity, positioning hydrated lime for sustained consumption growth in drinking water treatment.
- IRA clean energy incentives:The Inflation Reduction Act's manufacturing tax credits support domestic lime production for critical mineral processing and battery supply chain applications.
Industry Challenges
- Kiln operator skills shortage:Experienced refractory maintenance and process control technicians are aging out of the workforce faster than training programs replenish technical capacity.
- OSHA silica compliance:Permissible exposure limits for crystalline silica require continuous dust suppression investments and workplace monitoring protocols that elevate operating overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Lime Market |
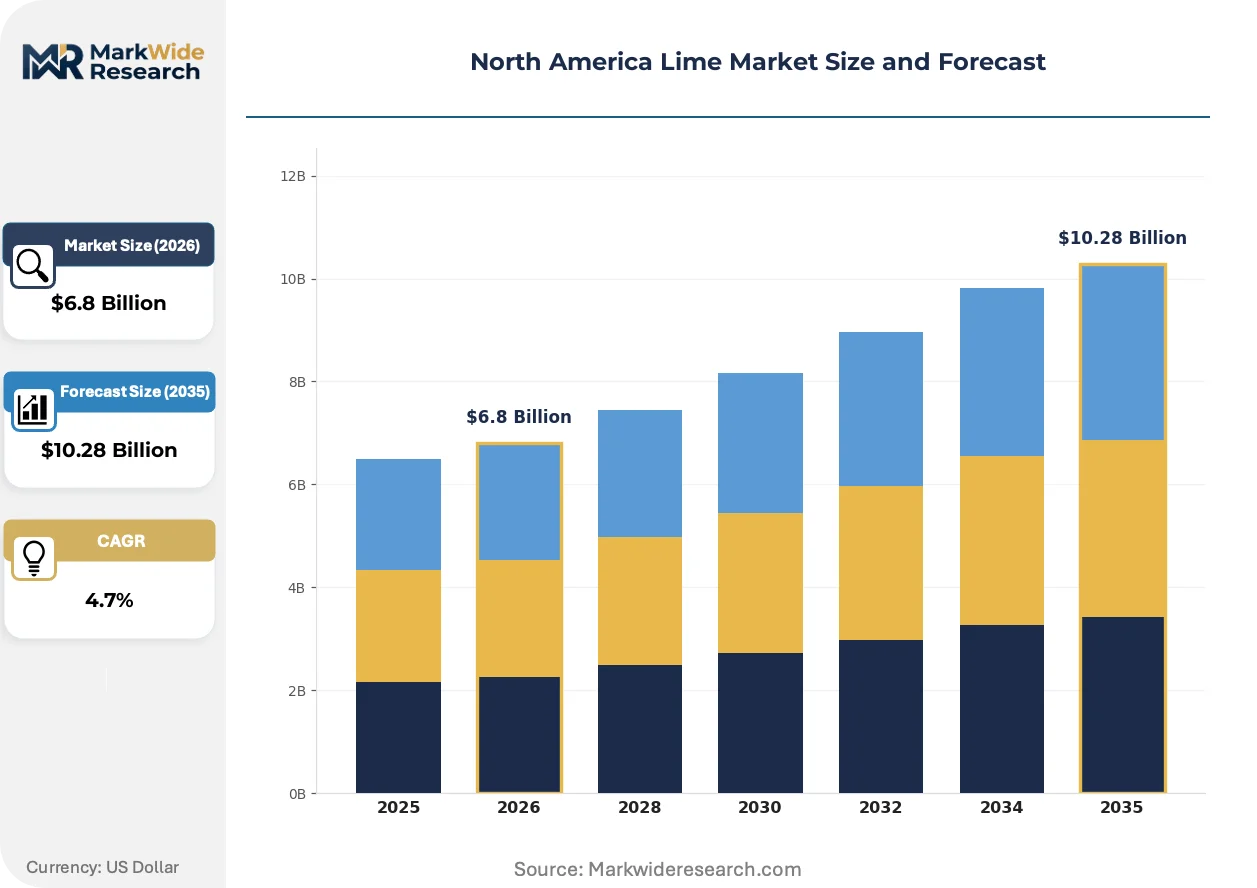
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrated Lime, Quicklime, Refractory Lime, Calcium Carbonate End User: Construction, Agriculture, Water Treatment, Steel Manufacturing Component: Calcium Oxide, Calcium Hydroxide, CaCO3, Slaked Lime Application: Soil Stabilization, Flue Gas Treatment, Sugar Processing, Pulp & Paper |
| Companies Covered | Graymont, Lhoist North America, Carmeuse, United States Lime & Minerals, Mississippi Lime, Cheney Lime & Cement Company, Linwood Mining & Minerals Corporation, Martin Marietta Materials, Pete Lien & Sons, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Lime Market Strategic Shifts
Digital kiln control systems and predictive maintenance platforms are penetrating lime production operations, compressing energy intensity and yield variability while reshaping how producers compete on consistency and specification adherence.
Advanced process control software is integrating real-time temperature profiling and fuel-air ratio optimization into vertical shaft and rotary kiln operations. Mid-scale producers in Ohio and Pennsylvania are adopting these systems to narrow calcium oxide variability bands. The technology is integrating quality assurance directly into combustion management, reducing off-spec batches and reprocessing costs.
EPA's National Ambient Air Quality Standards enforcement is tightening particulate matter thresholds for industrial sources across the United States. This regulatory pressure is accelerating scrubber retrofits at lime-consuming facilities themselves, creating circular demand where lime producers must install their own product in compliance systems. Cement and power generation customers in the Midwest are responding by locking in multi-year lime supply agreements to secure reagent availability during construction windows.
Buyers in the chemical and water treatment segments are consolidating vendor relationships and demanding certified carbon intensity disclosures alongside traditional assay certificates. Long-term contracts with fixed-volume, floating-price mechanisms are displacing spot market purchases for hydrated lime grades. This behavioral shift is most pronounced among municipal water authorities in California and Texas, where procurement departments now require Scope 1-2 emissions documentation as a bid qualification criterion.
North America Lime Market Segmentation
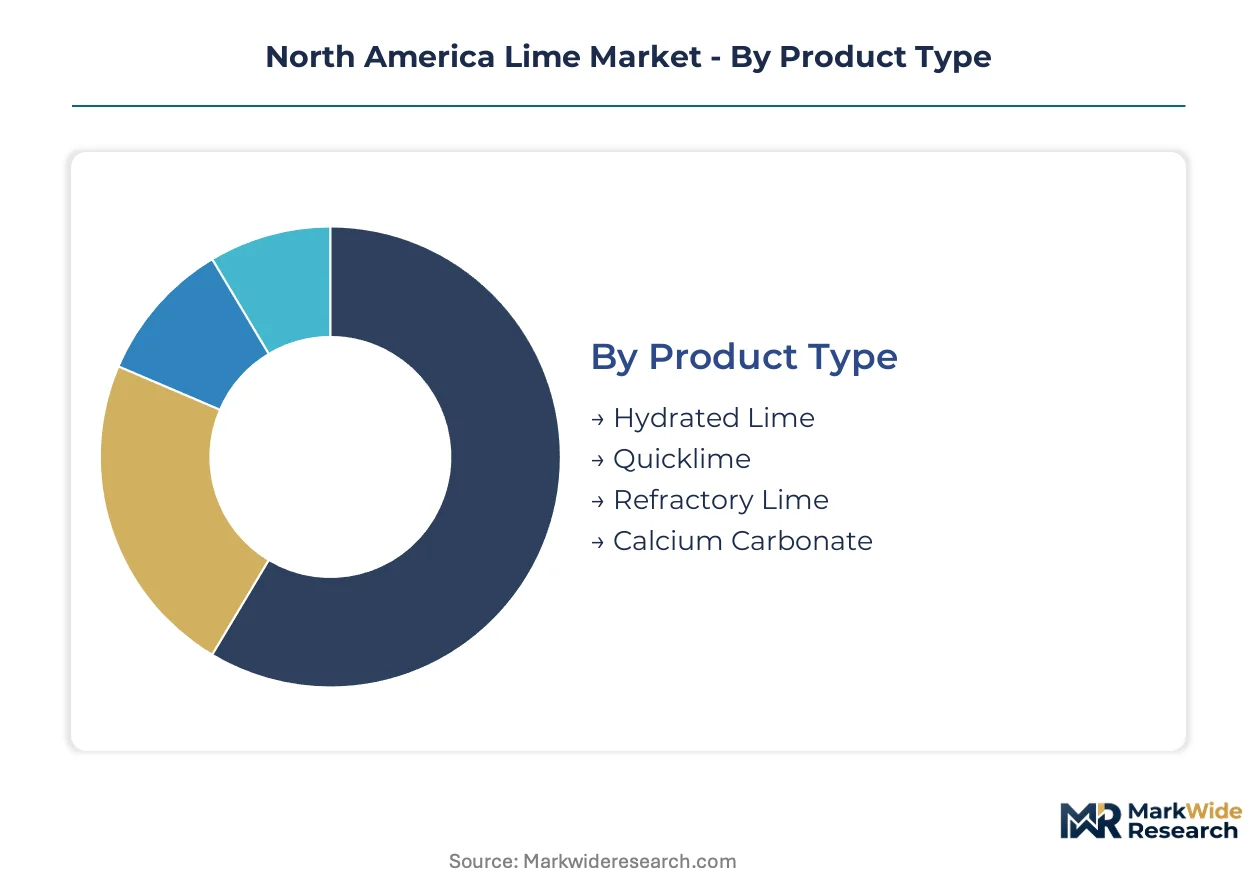
Lime product differentiation determines integration depth across industrial supply chains. Specification requirements vary sharply between embedded metallurgical processes and standalone environmental applications.
Product Type:
Standalone lime products serve discrete processing steps while embedded grades integrate continuously into customer operations.
- Quicklime:Calcium oxide produced at temperatures exceeding 900 degrees Celsius yields 90-98 percent calcium content for industrial grades. Great Lakes corridor steel manufacturers embed quicklime directly into slag conditioning and fluxing operations, creating irreplaceable demand pull from metallurgical-grade suppliers.
- Hydrated Lime:Calcium hydroxide formed through controlled hydration of quicklime delivers superior handling characteristics and precise reactivity control. US Sun Belt municipal water authorities are expanding alkalinity adjustment capacity, positioning hydrated lime for sustained consumption growth in drinking water treatment infrastructure.
- Refractory Lime:High-purity grades engineered for extreme thermal environments in steel and glass manufacturing.
- Calcium Carbonate:Ground limestone products serving filler and neutralization applications across paper and plastics compounding.
Volume placements concentrate in Quicklime; the faster expansion belongs to Hydrated Lime.
End User:
Customer scale and procurement sophistication create divergent margin profiles across end-use segments.
- Steel Manufacturing:Integrated mills and mini-mills in the Great Lakes corridor consume metallurgical-grade quicklime for slag conditioning, desulfurization, and furnace fluxing. EPA MATS compliance at captive power plants reinforces lime demand within steel producer facilities themselves.
- Water Treatment:Municipal authorities and industrial processors deploy hydrated lime for pH adjustment, softening, and disinfection support. Texas and California procurement departments now require Scope 1-2 emissions documentation as a bid qualification criterion.
- Construction:Highway departments in California, Texas, and Illinois govern lime stabilization standards for road base construction.
- Agriculture:Soil amendment applications for pH correction and nutrient availability enhancement across Midwest and Southern crop regions.
Steel Manufacturing commands the largest volume commitments; Water Treatment is climbing the fastest as infrastructure upgrades accelerate.
Component:
Chemical composition determines reactivity profiles and suitability for specific industrial reactions.
- Calcium Oxide:Unslaked quicklime with highest available alkali content per unit mass, preferred where thermal efficiency and reaction kinetics dominate process economics.
- Calcium Hydroxide:Slaked lime offering controlled reactivity and safer handling characteristics for water treatment and chemical processing.
- CaCO3:Calcium carbonate in calcitic or dolomitic forms serving lower-intensity neutralization and filler applications.
- Slaked Lime:Hydrated product variants with engineered particle size distributions for specific suspension and reactivity requirements.
Calcium Oxide anchors volume in heavy industrial use; Calcium Hydroxide is gaining share fastest in environmental and municipal applications.
Application:
Process integration depth varies from continuous consumption loops to discrete project-based deployments.
- Flue Gas Treatment:Scrubber systems at coal-fired power plants and industrial boilers consume high-calcium lime reagents for sulfur dioxide and mercury capture. EPA enforcement of National Ambient Air Quality Standards locks in structural demand across Midwest and Southeast generation assets.
- Soil Stabilization:Highway construction projects in Texas and California deploy bulk quicklime for road base modification and subgrade improvement. State-level Department of Transportation specifications govern acceptance standards and placement protocols.
- Pulp & Paper:Kraft process operations use lime in causticizing loops for pulping chemistry regeneration.
- Sugar Processing:Beet and cane refining operations employ lime for juice purification and pH control.
Soil Stabilization holds the deepest volume base; Flue Gas Treatment shows the steepest expansion trajectory as scrubber retrofits accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States while Canadian and Mexican operations serve cross-border industrial demand. Kiln utilization rates vary sharply between the Great Lakes metallurgical corridor and the Gulf Coast petrochemical belt.
United States
Steel manufacturers in the Great Lakes corridor consume metallurgical-grade quicklime for slag conditioning and fluxing operations. EPA enforcement of Mercury and Air Toxics Standards mandates scrubber installations at coal-fired power plants across the Midwest and Southeast. The US Gulf Coast petrochemical corridor anchors regional kiln demand through refinery sulfur recovery and chemical processing applications.
Canada
Western Canadian operations supply high-calcium lime to Alberta oil sands upgrading and British Columbia mining operations. Provincial environmental regulators enforce particulate matter thresholds that shape scrubber retrofits at lime-consuming facilities. Ontario's manufacturing belt connects to US Great Lakes steel mills through integrated cross-border supply chains.
Mexico
Northern border states host kiln capacity serving maquiladora steel and automotive manufacturing clusters. Mexican federal environmental standards under SEMARNAT align with US EPA frameworks for cross-border industrial facilities. Monterrey and Chihuahua industrial corridors import US lime grades for metallurgical and construction applications.
Appalachian Region
High-calcium limestone deposits in Kentucky, Tennessee, and West Virginia feed kiln networks serving eastern steel and utility markets. State-level Department of Transportation specifications in Kentucky and Tennessee govern lime stabilization standards for highway construction. The Ohio River corridor facilitates barge transport to Midwest manufacturing centers.
Southwest
Texas and California highway departments deploy bulk quicklime for soil stabilization in road base construction projects. Municipal water authorities in Phoenix, Dallas, and Houston expand alkalinity adjustment capacity using hydrated lime. State procurement departments now require Scope 1-2 emissions documentation as a bid qualification criterion.
North America Lime Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the North America lime market. The vendor base clusters around vertically integrated quarry-to-kiln operators and regional packaging specialists serving bulk industrial accounts. Two strategic archetypes dominate: integrated limestone-to-lime producers controlling captive reserves, and toll-processing specialists optimizing logistics for municipal water and construction segments. Capacity expansion and multi-year supply agreements represent the dominant competitive moves as customers lock in reagent availability during scrubber construction windows.
Within the integrated producer tier, Graymont anchors western Canadian and US operations with vertically controlled reserves, while Carmeuse leverages Appalachian kiln density to serve Great Lakes steel mills. United States Lime & Minerals occupies a position among specialized high-purity quicklime suppliers targeting chemical processing customers. These three exemplify how geographic quarry positioning and product grade specialization segment competitive positioning across metallurgical, environmental, and industrial chemical verticals.
| Leading Market Players |
|---|
| Graymont |
| Lhoist North America |
| Carmeuse |
| United States Lime & Minerals |
| Mississippi Lime |
| Cheney Lime & Cement Company |
| Linwood Mining & Minerals Corporation |
| Martin Marietta Materials |
| Pete Lien & Sons, Inc. |
| Others |
Value Chain & Pricing Dynamics
Metallurgical-grade quicklime commands a 15-25 percent premium over construction-grade material, a bifurcation that concentrates pricing power among Appalachian kiln operators serving Great Lakes steel mills while forcing commodity producers into longer haul logistics to compete. This tier divergence embeds directly into supply chain configurations: premium grades move through dedicated bulk rail contracts with assay certificates, while standard grades compete on delivered cost via barge and truck networks.
Pricing Analysis
Cost-down pressure on bulk construction-grade material accelerates because state highway departments in Texas and California consolidate procurement volumes and demand Scope 1-2 emissions documentation as a bid qualification criterion. Three-tier pricing structure across high-purity chemical, metallurgical, and construction grades separates United States Lime & Minerals from Carmeuse and Graymont. Natural gas price volatility at Henry Hub compresses kiln operator margins during cold-weather demand spikes, making chemical processors the least price-sensitive buyers due to specification lock-in, while municipal water authorities exhibit highest sensitivity to delivered cost.
Supply Chain Analysis
High-calcium limestone feedstock rests on Appalachian deposits in Kentucky, Tennessee, and West Virginia, with secondary sourcing from the Ozark plateau in Missouri and Arkansas. Kiln operations draw from natural gas for calcination heat, refractory materials for furnace linings, and diesel fuel for quarry extraction equipment. Single-source vulnerability concentrates in the Ohio River barge corridor, where low-water events disrupt bulk shipment to Midwest manufacturing centers. Distribution runs through vertically integrated quarry-to-kiln networks for premium grades, while toll-processors and regional packaging specialists serve spot market construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reserve depletion in high-calcium Appalachian deposits and aging kiln operator workforce constraints create structural supply scarcity that props pricing across the forecast horizon.
For Market Incumbents: Anchor metallurgical-grade supply relationships through multi-year offtake agreements with Great Lakes steel mills before carbon border adjustment mechanisms restructure import competition. Defend against sodium-based alkali substitution in flue gas treatment by embedding technical service teams at utility scrubber installations. Prioritize refractory maintenance training programs to offset technician attrition.
For New Entrants and Emerging Players: Begin with carbon capture sorbent loop pilot projects in Texas and Louisiana, where direct air capture ventures lack established lime supplier relationships. Target municipal water authorities in Phoenix, Dallas, and Houston with certified low-carbon intensity hydrated lime as procurement departments harden emissions documentation requirements. Pursue toll-processing partnerships with stranded quarry assets rather than greenfield kiln construction.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified construction materials conglomerates seeking vertical integration into high-calcium lime. Long-term viability hinges on kiln operators with captive Appalachian reserves and EPA MATS compliance exposure. Watch carbon border adjustment implementation timelines as the inflection signal for competitive restructuring between domestic and imported material.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Graymont and Carmeuse secure multi-decade limestone supply through quarry acquisitions in Kentucky and Tennessee. |
| Long-term Supply Agreement | Midwest utilities lock in high-calcium lime reagent availability during EPA-mandated scrubber construction windows. |
| Green Manufacturing Transition | Kiln operators invest in oxy-fuel combustion and waste heat recovery to meet California and Texas procurement emissions criteria. |
| Capacity Expansion | Appalachian kiln additions target Great Lakes steel fluxing demand as mini-mill electric arc furnace capacity expands. |
| Joint Venture | Carbon capture developers partner with lime producers to pilot sorbent loop systems in Louisiana petrochemical corridors. |
Study Parameters
Trade databases, EPA enforcement records, and state Department of Transportation procurement filings formed the secondary backbone, cross-referenced with primary interviews involving kiln operations managers, steel mill procurement leads, municipal water authority contract officers, and flue gas treatment system engineers. Bottom-up volume estimates from individual kiln capacity utilization combined with top-down demand segmentation across steel, water treatment, and construction end uses to triangulate market sizing.
Historical trendline analysis of lime consumption per ton of steel produced, per megawatt-hour of coal-fired generation, and per mile of highway construction established baseline demand coefficients. The analytical framework modeled product type, end-use industry, calcium content grade, and regional production hub across the projection horizon. CAGRs derived from regression analysis against industrial production indices, infrastructure spending forecasts, and regulatory compliance timelines. Natural gas price scenarios and limestone reserve quality degradation curves served as key sensitivity inputs.
EPA MATS enforcement intensity, carbon border adjustment implementation, and Appalachian quarry reserve depletion rates are the dominant revision risks to the demand outlook. Forecasts embed assumptions regarding steel production levels, coal plant retirement schedules, and highway appropriations that warrant acknowledgment. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
US Trona Market
Bulk Chemicals
Global Chlorinated Paraffin Wax Market
Bulk Chemicals
Sodium Perborate Market
Bulk Chemicals
Europe Lime Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Oxalic Acid Market
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
Ammonium Sulfate Food Grade Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Copper Sulfate Market
Bulk Chemicals
Castor Oil Derivatives Market