
 North America Laser Diode Market | 2026-2036
North America Laser Diode Market Size, Share, and Industry Trends Forecast 2026-2036
North America Laser Diode Market Intelligence
Direct OEM procurement channels is reconfiguring how laser diode suppliers reach end-users across North America. II-VI Incorporated leverages captive wafer fabrication to control cost structures from substrate through packaged device. Lumentum Holding Inc. anchors telecom and 3D sensing portfolios through sustained R&D spending on vertical-cavity surface-emitting architectures. Coherent Corp. competes across materials processing and instrumentation segments with broad wavelength coverage.
A laser diode is a semiconductor device that converts electrical current into coherent light through stimulated emission, typically operating at wavelengths from ultraviolet to infrared with output powers ranging from milliwatts to hundreds of watts. The component serves as the core energy source in fiber optic communications, precision cutting systems, and diagnostic medical equipment. High-power laser diodes command the largest revenue share due to penetration in industrial metal processing and directed-energy defense programs. Fiber-coupled technology is expanding fastest as beam-delivery architectures simplify integration into OEM systems. GaAs-based devices retain mature dominance in near-infrared applications while InGaN platforms gain share in visible and ultraviolet segments.
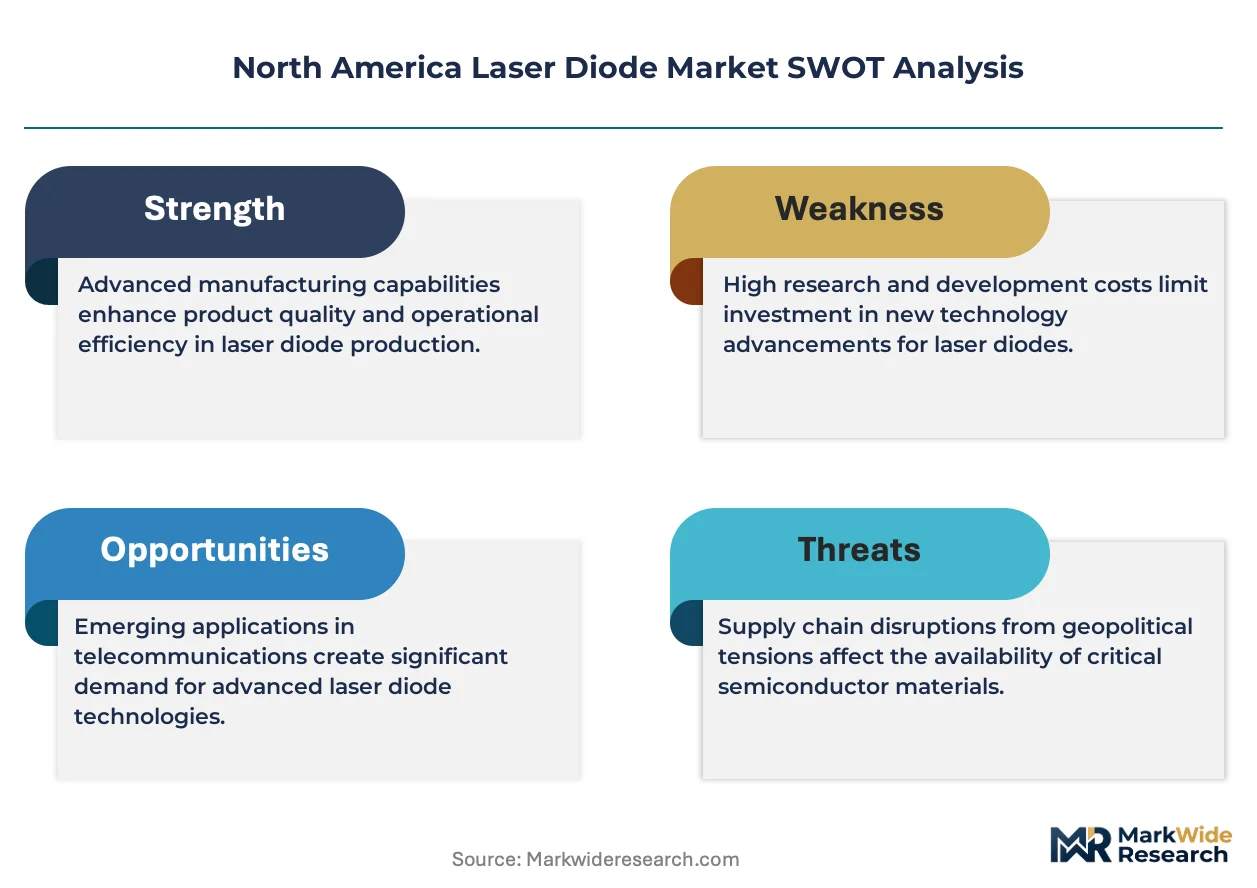
FDA clearance pathways for Class III and Class IV laser medical devices impose substantial clinical validation requirements on manufacturers targeting surgical and therapeutic markets. FCC spectrum allocations shape telecom laser specifications for datacenter interconnect and 5G fronthaul deployments. OSHA workplace safety standards govern industrial laser installation and operator certification across manufacturing facilities. Stakeholders must monitor how NHTSA evolving autonomous vehicle guidelines create new specification requirements for lidar illumination sources.
Market Dynamics
Direct OEM procurement channels are reconfiguring supplier relationships across North America, compressing distributor margins while rewarding manufacturers with captive wafer fabrication and packaged device capabilities. This structural shift is concentrating purchasing power among vertically integrated telecom equipment makers and precision manufacturing OEMs.
Growth Catalysts
- Telecommunications infrastructure deployment:5G fronthaul and datacenter interconnect buildouts are accelerating demand for high-speed optical transceivers. FCC spectrum allocations for millimeter-wave bands are mandating denser fiber backhaul networks.
- FDA Class III/IV device pathways:The medical device classification framework is creating predictable regulatory roadmaps for surgical laser manufacturers. Dermatology and ophthalmology applications are expanding as clinical validation databases mature.
- Directed-energy defense programs:Pentagon procurement for solid-state laser weapons is pulling high-power diode arrays into qualification pipelines. Texas and California defense corridors are anchoring subsystem integration.
Market Restraints
- Gallium arsenide substrate concentration:Limited qualified suppliers for 6-inch GaAs wafers creates input cost volatility. Mining and refining bottlenecks in rare earth co-dopants compound exposure.
- Beam quality limitations:Thermal lensing in high-power bars constrains brightness scaling for metal cutting applications. Fiber-coupled architectures add cost and alignment complexity.
- OSHA workplace safety compliance:Industrial laser installation mandates impose capital burdens on small and mid-sized manufacturing facilities. Operator certification requirements extend deployment timelines.
Strategic Opportunities
- Autonomous vehicle lidar specification:NHTSA evolving guidelines for sensor redundancy are creating new illumination source requirements. Tier-1 automotive suppliers are qualifying 905nm and 1550nm diode platforms.
- InGaN visible/UV platform expansion:Ultraviolet curing and biomedical instrumentation are absorbing shorter-wavelength devices. Mexico maquiladora electronics assembly is absorbing packaged die for consumer applications.
- Silicon photonics convergence:Hybrid integration of III-V lasers with silicon waveguides is collapsing transceiver form factors. Foundry partnerships in Arizona and Oregon are prototyping co-packaged optics.
Industry Challenges
- Compound semiconductor talent scarcity:Epitaxial growth and facet passivation expertise is concentrating at a handful of research institutions. Workforce pipelines from materials science programs are insufficient for capacity expansion.
- FDA 510(k) clearance timelines:Clinical validation for surgical indications extends product development cycles. Predicate device strategies are narrowing as laser-tissue interaction databases mature.
- Legacy system integration friction:Fiber-coupled retrofits into CO2 laser cutting platforms require mechanical and control system re-engineering. Job shop manufacturers face downtime penalties during transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Laser Diode Market |
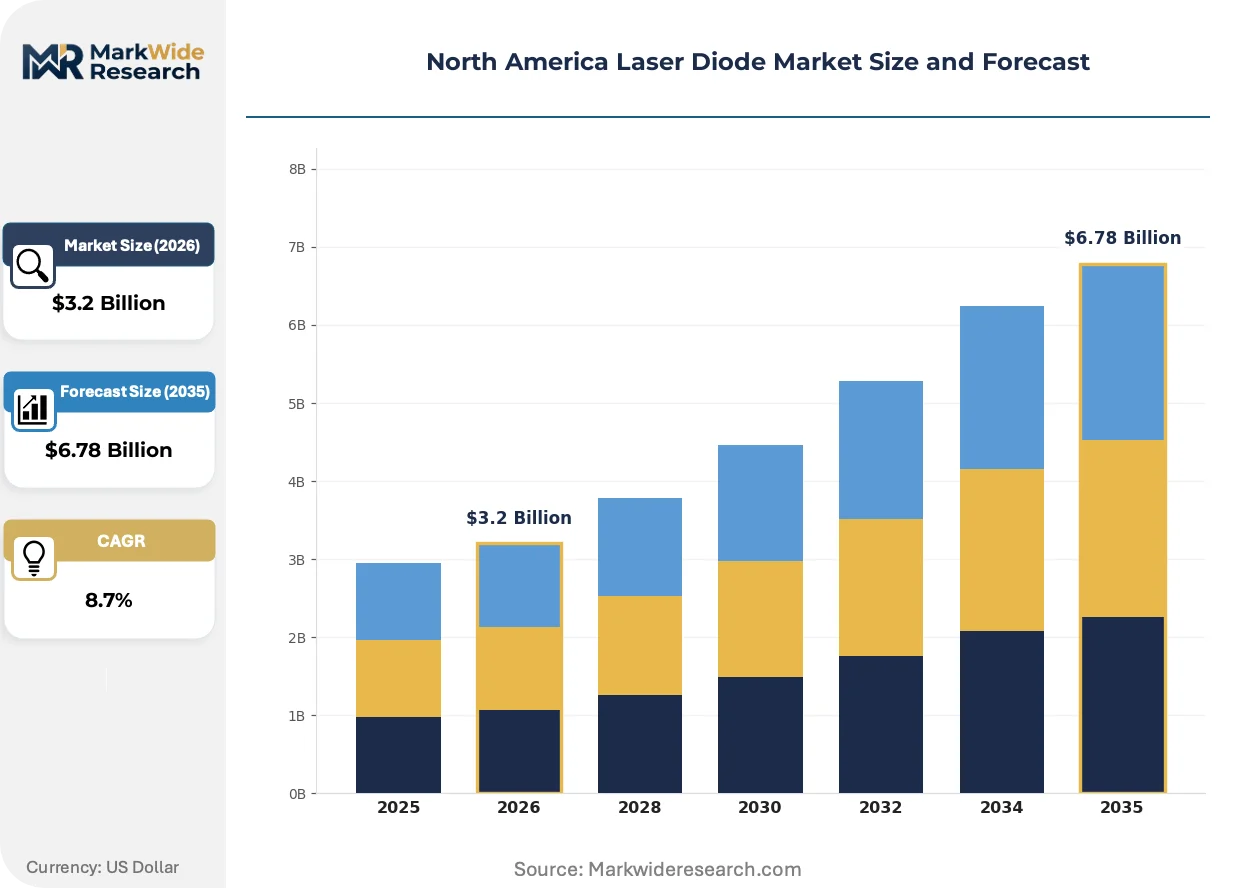
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $6.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Laser Diodes, High-Power Laser Diodes, Modulated Laser Diodes, Tunable Laser Diodes Application: Telecommunications, Industrial Processing, Medical Equipment, Consumer Electronics Technology: InGaN, GaAs, AlGaInP, Fiber Coupled End User: OEMs, Research Institutions, Defense, Healthcare Providers |
| Companies Covered | II-VI Incorporated, Lumentum Holding Inc., Coherent Corp., IPG Photonics Inc., MKS Instruments, Ams-OSRAM AG, Jenoptik AG, Hamamatsu Photonics K.K., Ushio, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Laser Diode Market Strategic Shifts & Innovations
Beam-delivery architectures and materials platforms are undergoing simultaneous transformation. Three developments are compressing traditional technology lifecycles and rewiring competitive positioning.
Vertical-cavity surface-emitting laser technology is hybridizing with edge-emitting platforms in 3D sensing and optical interconnect applications. Apple and automotive lidar developers are adopting multi-junction VCSEL arrays for short-range depth mapping. This convergence is collapsing the historical separation between telecom and consumer illumination sources.
FCC Part 15 unintentional radiator standards are tightening electromagnetic compatibility requirements for laser driver electronics. Manufacturers are redesigning power supply architectures to suppress conducted emissions in industrial environments. Medical device OEMs in Minnesota and Massachusetts are absorbing compliance costs into subsystem pricing.
Consolidated procurement through tier-1 telecom equipment vendors is displacing fragmented distributor networks. Ciena and Juniper are qualifying single-source diode suppliers for multi-year supply agreements. This concentration is most visible in California's Bay Area photonics cluster where direct OEM engineering relationships now dominate vendor selection.
North America Laser Diode Market Segmentation
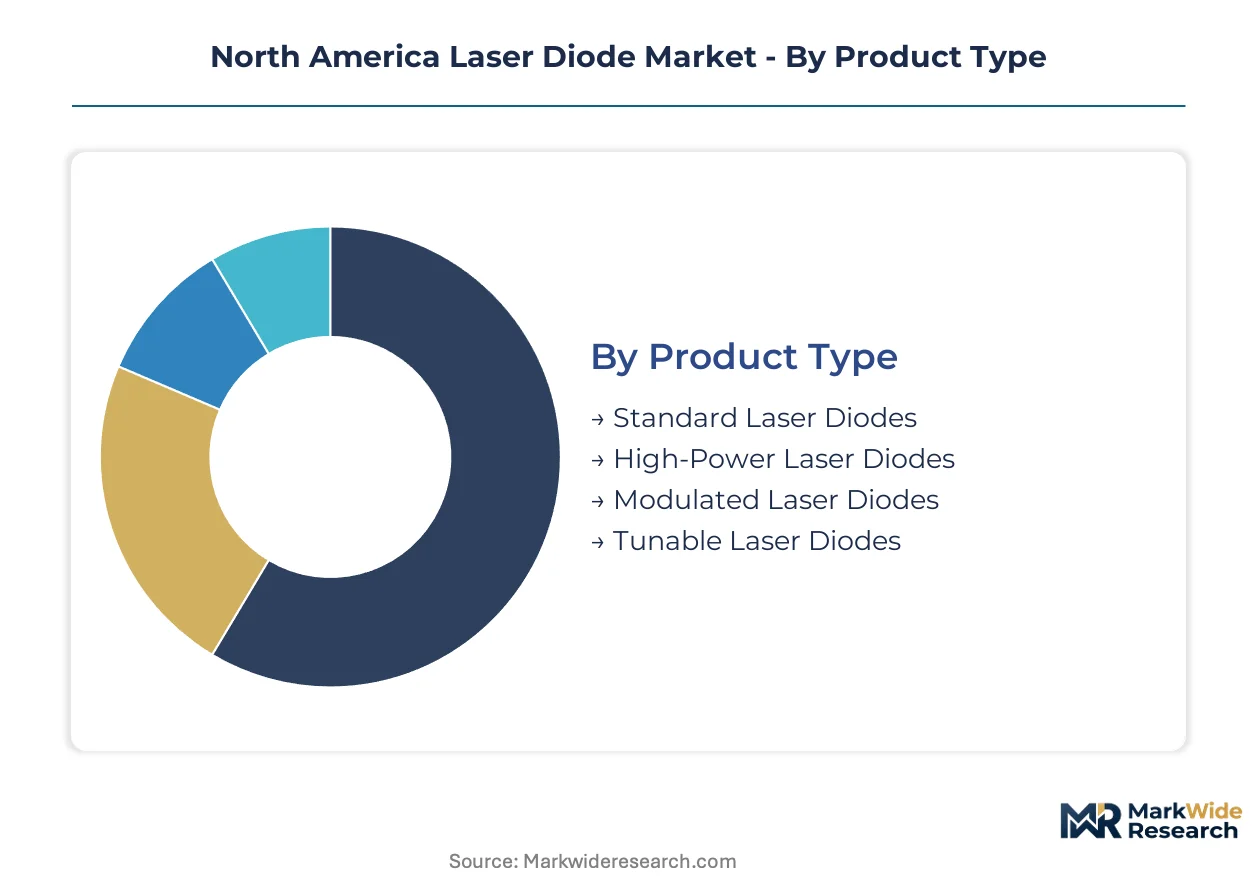
Segmentation reveals how laser diode specifications diverge across power thresholds, wavelength platforms, and procurement channels. Understanding these divides exposes where margin concentrates and which technology transitions threaten incumbent positions.
Product Type:
Mature packaged formats dominate revenue while emerging architectures reshape performance ceilings and integration economics.
- Standard Laser Diodes:Low-to-medium power devices operating from milliwatts to several watts in Fabry-Perot or distributed feedback configurations. Demand concentrates in California's Silicon Valley photonics cluster for datacenter transceivers where FCC spectrum allocations mandate tighter wavelength stability.
- High-Power Laser Diodes:Multi-watt to hundred-watt bars and stacks requiring sophisticated thermal management and facet passivation. Texas defense corridors and Pennsylvania metal fabrication hubs absorb arrays for directed-energy weapons and industrial cutting where OSHA workplace safety standards govern installation protocols.
- Modulated Laser Diodes:Directly modulated sources for 5G fronthaul and access network optics.
- Tunable Laser Diodes:External cavity and sampled grating architectures for reconfigurable optical add-drop multiplexers.
High-Power Laser Diodes handle the majority of throughput; Modulated Laser Diodes are expanding most quickly on share.
Application:
Cost tier separation runs from commodity consumer illumination to qualification-intensive defense subsystems.
- Telecommunications:Optical transceivers for datacenter interconnect, metro networks, and 5G fronthaul requiring precise wavelength control and hermetic packaging. FCC Part 15 electromagnetic compatibility standards and carrier qualification timelines stretch development cycles.
- Industrial Processing:Metal cutting, welding, and additive manufacturing systems where fiber-coupled delivery dominates. OSHA compliance burdens and CO2 laser retrofit friction slow adoption at smaller job shops.
- Medical Equipment:Surgical, therapeutic, and diagnostic devices facing FDA Class III and IV clearance pathways.
- Consumer Electronics:3D sensing, LiDAR, and optical interconnect for smartphones and peripherals.
Telecommunications commands the largest installed base; Medical Equipment is climbing the fastest on regulatory pathway maturation.
Technology:
Volume concentration favors mature III-V platforms while emerging materials extend wavelength reach.
- InGaN:Nitride-based devices spanning violet through green wavelengths for biomedical instrumentation and UV curing systems. Mexico maquiladora electronics assembly absorbs packaged die for consumer display and sensing applications.
- GaAs:Arsenide platforms dominating near-infrared telecom and industrial applications with established epitaxial growth infrastructure. Limited 6-inch wafer supply creates input cost volatility.
- AlGaInP:Phosphide-based red and orange emitters for medical phototherapy and specialty illumination.
- Fiber Coupled:Beam-delivery architectures integrating diode output into fiber pigtails for simplified OEM system integration.
GaAs handles the majority of throughput; InGaN is gaining share fastest on visible and ultraviolet platform expansion.
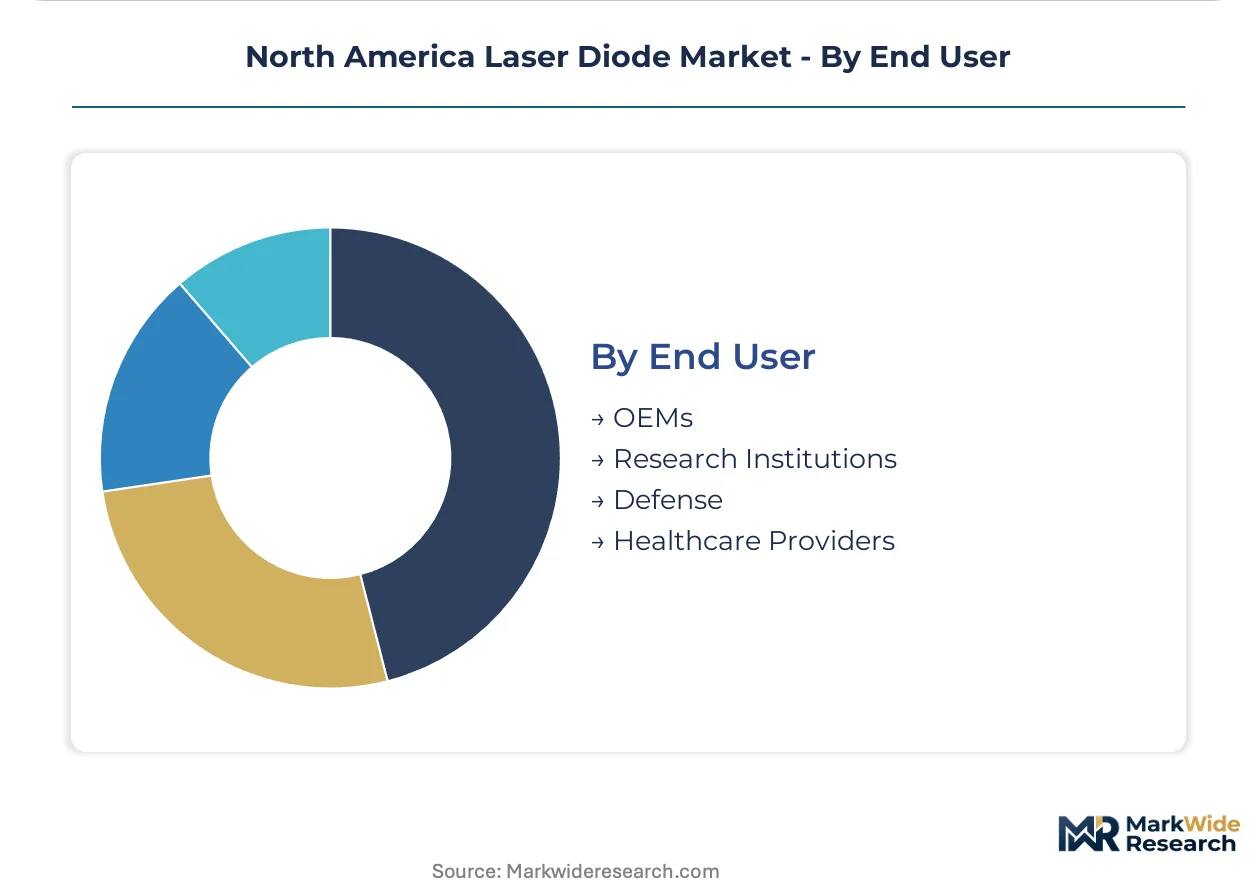
End User:
Customer type determines procurement channel structure and technical support intensity.
- OEMs:Tier-1 telecom equipment vendors and precision manufacturing system builders consolidating purchasing power through direct supplier relationships. Ciena and Juniper qualification programs in California's Bay Area exemplify concentrated vendor selection.
- Research Institutions:National laboratories and university photonics centers requiring custom wavelengths and non-standard packaging.
- Defense:Pentagon programs and prime contractors pulling high-power arrays into qualification pipelines with extended testing horizons.
- Healthcare Providers:Hospital systems and outpatient clinics procuring surgical laser systems through device OEMs rather than direct diode purchase.
OEMs handle the majority of throughput; Defense is expanding most quickly on directed-energy program acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific Coast fiber optic cable landing stations and the I-35 semiconductor corridor anchor North America's laser diode infrastructure, connecting Asian supply chains to domestic packaging and integration facilities.
United States
California's Silicon Valley photonics cluster absorbs standard and modulated laser diodes for datacenter transceivers, while Texas defense corridors pull high-power arrays into Pentagon directed-energy programs. FDA Class III and IV device pathways in Maryland and Minnesota accelerate surgical laser commercialization. OSHA workplace safety standards govern industrial laser installations across Pennsylvania metal fabrication hubs.
Canada
Ontario's automotive supplier network in Waterloo-Toronto corridor qualifies 905nm and 1550nm diode platforms for lidar integration. Health Canada's medical device regulations parallel FDA frameworks, easing cross-border product registrations for Quebec-based photonics firms. British Columbia's clean technology sector deploys fiber-coupled systems for precision manufacturing in Vancouver's industrial suburbs.
Mexico
Baja California and Chihuahua maquiladora electronics assembly plants package InGaN visible and ultraviolet die for consumer display applications. Mexico's proximity to US telecom equipment vendors concentrates back-end integration for 5G fronthaul optics. Guadalajara's emerging photonics cluster serves medical device OEMs seeking FDA-aligned manufacturing partnerships.
North America Laser Diode Market Key Industry Players
On the supply side, the industry is consolidating around vertically integrated compound semiconductor fabricators with captive wafer production and packaged device capabilities. The vendor base separates into three strategic archetypes: defense-focused high-power array specialists, telecom-anchored VCSEL and edge-emitter suppliers, and diversified photonics conglomerates with broad wavelength coverage. Dominant competitive moves include backward integration into epitaxial growth and strategic partnerships with tier-1 telecom equipment vendors for multi-year supply agreements.
Within the diversified photonics tier, II-VI Incorporated, Lumentum Holding Inc., and Coherent Corp. exemplify competing approaches to market positioning. II-VI Incorporated represents the vertically integrated archetype with control from substrate through final packaging. Lumentum Holding Inc. occupies a position concentrated on telecom and 3D sensing architectures. Coherent Corp. anchors the broad-coverage strategy across materials processing and instrumentation segments.
| Leading Market Players |
|---|
| II-VI Incorporated |
| Lumentum Holding Inc. |
| Coherent Corp. |
| IPG Photonics Inc. |
| MKS Instruments |
| Ams-OSRAM AG |
| Jenoptik AG |
| Hamamatsu Photonics K.K. |
| Ushio, Inc. |
| Others |
Cost & Logistics Intelligence
6-inch GaAs wafer concentration in Japan and Germany funnels pricing power toward epitaxial foundries and substrate suppliers, compressing margins for packaged device manufacturers in Texas and California while rewarding captive fabrication at II-VI Incorporated and Coherent Corp.
Pricing Analysis
Three-tier pricing structure across defense-qualified, telecom-grade, and industrial-economy levels separates Pentagon-directed energy arrays from datacenter transceivers and metal-cutting bars. Price differentiation hinges on FDA Class III/IV certification status and hermetic packaging grade. Cost compression in industrial-economy tiers is intensifying because Chinese substrate entrants are eroding legacy supplier premiums. Job shop manufacturers in Pennsylvania exhibit highest price sensitivity; defense primes in Texas show lowest sensitivity due to qualification lock-in.
Supply Chain Analysis
Extended payment terms from Ciena and Juniper are squeezing working capital at tier-2 epitaxial suppliers, accelerating consolidation toward cash-rich conglomerates. Raw material flows draw from Japan for GaAs substrates, China for rare earth co-dopants, and Germany for MOCVD reactor components. Single-source vulnerability concentrates at 6-inch wafer qualification pipelines. Distribution runs through direct OEM procurement channels anchored in California's Bay Area photonics cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America laser diode market is exiting a cyclical trough driven by Pentagon directed-energy procurement acceleration and 5G fronthaul buildout normalization.
For Market Incumbents: Entrench position through backward integration into epitaxial growth capacity and multi-year supply agreements with tier-1 telecom equipment vendors. Threat from silicon photonics convergence demands R&D investment in hybrid III-V integration. Certification investment in FDA 510(k) predicate databases defends medical segment share. For New Entrants and Emerging Players: Establish a beachhead in Mexico maquiladora InGaN packaging for consumer display applications, where FDA-aligned manufacturing partnerships ease cross-border qualification. The most penetrable white space sits in ultraviolet curing systems for biomedical instrumentation. Go-to-market leverage rests on foundry partnerships in Arizona and Oregon prototyping co-packaged optics. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated compound semiconductor fabricators with captive wafer production and packaged device capabilities. Long-term viability favors archetypes controlling substrate through final packaging. Watch NHTSA autonomous vehicle lidar specification finalization as inflection signal for 905nm and 1550nm platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epitaxial Growth | Captive MOCVD capacity insulates margin from Japanese substrate pricing volatility. |
| Multi-Year Telecom Supply Agreement | Ciena and Juniper qualification programs lock out competitor access for 3-5 year windows. |
| FDA 510(k) Predicate Device Expansion | Clinical validation databases in dermatology and ophthalmology accelerate surgical laser commercialization. |
| Hybrid Silicon Photonics Partnership | Foundry alliances in Arizona collapse transceiver form factors for datacenter interconnect. |
| Defense Corridor Subsystem Integration | Texas and California facilities capture Pentagon directed-energy array qualification pipelines. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, FCC spectrum allocation records, and FDA 510(k) clearance databases. Primary interviews engaged epitaxial growth engineers at compound semiconductor foundries, procurement directors at tier-1 telecom equipment vendors, and biomedical engineers at Minnesota surgical laser OEMs. Bottom-up unit demand modeling triangulates against top-down industry revenue estimates from trade associations and customs records.
Forecast inputs span telecommunications infrastructure deployment trajectories, Pentagon budget authorization patterns for directed-energy programs, and NHTSA autonomous vehicle guideline evolution. Segmentation dimensions include power threshold, wavelength platform, application vertical, and procurement channel structure. CAGRs derive from regression analysis of historical shipment data against capital expenditure announcements and carrier network buildout schedules.
Stress conditions across GaAs substrate pricing volatility, FCC spectrum reallocation timing, and FDA 510(k) clearance timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding carrier capex commitment and defense procurement continuity. Macroeconomic contraction, regulatory pathway disruption, or silicon photonics substitution acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Optical Network Hardware Market
Optical Components
Pancake Optical Module Market
Optical Components
Night Vision Tubes Market
Optical Components
Optical Modulators Market
Optical Components
Digital Cinema Lens Market
Optical Components
Faraday Rotator Market
Optical Components
Europe Tunable Laser Market
Optical Components
Fiber Optic Collimating Lens Market
Optical Components
Bio-Optics Market
Optical Components
Optical Position Sensors Market
Optical Components
Spatial Light Modulator Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Optical Lens Edger Market
Optical Components
Global Mask Alignment Systems Market