
 Bio-Optics Market | 2026-2036
Bio-Optics Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Optics Market Outlook
Academic research institutions are unwinding their historical dominance over bio-optics procurement as hospital surgical departments and commercial diagnostic chains gain budget authority. Carl Zeiss AG leverages its century-old glass-making heritage to dominate super-resolution microscopy substrates. Hamamatsu Photonics sustains leadership in photomultiplier tube supply for fluorescence imaging systems. Thermo Fisher Scientific competes through integrated life-science platforms that bundle optical instruments with reagent workflows.
Bio-optics encompasses the design, fabrication, and application of optical instruments and photonic technologies for biological specimen interrogation, typically operating across ultraviolet through near-infrared wavelengths with sub-micron spatial resolution. The field serves clinical diagnostics, surgical navigation, and fundamental biological discovery by converting molecular and cellular light interactions into quantifiable image data. Endoscopy systems command the largest installed base among product categories due to entrenched gastrointestinal screening protocols, while optical coherence tomography represents the fastest-expanding segment as ophthalmology clinics adopt swept-source variants for retinal vasculature mapping. Fluorescence imaging leads technology deployment in research settings, though Raman spectroscopy is displacing traditional histology in intraoperative margin assessment applications.
FDA 510(k) pathways govern commercialization of laser-based surgical instruments in the United States, while the EU MDR imposes clinical evidence requirements on optical diagnostic devices seeking CE marking for European distribution. Japan's PMDA maintains stringent quality system inspections for imported microscopy platforms, creating compliance friction for non-Japanese vendors. Stakeholders must monitor divergence between FDA breakthrough device designation criteria and EU MDR Article 61 clinical performance standards when prioritizing geographic launch sequencing.
Market Dynamics
Hospital surgical departments are consolidating procurement authority over academic institutions, compressing vendor sales cycles and forcing optical instrument manufacturers to reconfigure distribution toward integrated health system contracts.
Growth Catalysts
- EU MDR Article 61:Clinical performance standards for optical diagnostic devices are harmonizing evidence requirements across European hospital networks, accelerating cross-border tender participation.
- Swept-source OCT:Retinal vasculature mapping capabilities are expanding ophthalmology clinic throughput, pulling replacement demand from time-domain systems.
- German precision optics clusters:Concentrated glass-making heritage and metrology infrastructure in Baden-Württemberg and Thuringia are shortening prototype-to-production timelines for fluorescence microscopy platforms.
Market Restraints
- Fluorophore supply concentration:Rare-earth dopant sourcing for laser crystals concentrates among Chinese processors, exposing price volatility to ytterbium and erbium oxide spot markets.
- Technical resolution ceiling:Diffraction limits in visible-light microscopy constrain sub-100nm imaging without electron beam alternatives, capping addressable applications in structural biology.
- Japan PMDA inspection backlog:Quality system audits for imported microscopy platforms extend clearance timelines by 8-14 months versus domestic manufacturers.
Strategic Opportunities
- Intraoperative Raman spectroscopy:Real-time margin assessment during tumor resection is displacing frozen-section histology in breast and brain surgery suites.
- India CDSCO fast-track:Accelerated approval pathways for laser-based surgical devices are opening tender access to government hospital procurement chains.
- AI-embedded OCT:Machine learning segmentation of retinal layers is converging with hardware platforms, enabling technician-operated screening in primary care settings.
Industry Challenges
- Photonics engineering talent scarcity:Specialized expertise in free-space optical design and adaptive optics control resides among aging cohorts in German and Japanese research institutes.
- Legacy hospital IT integration:DICOM-compliant imaging workstations must interface with proprietary PACS architectures, extending deployment timelines and service contract complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Optics Market |
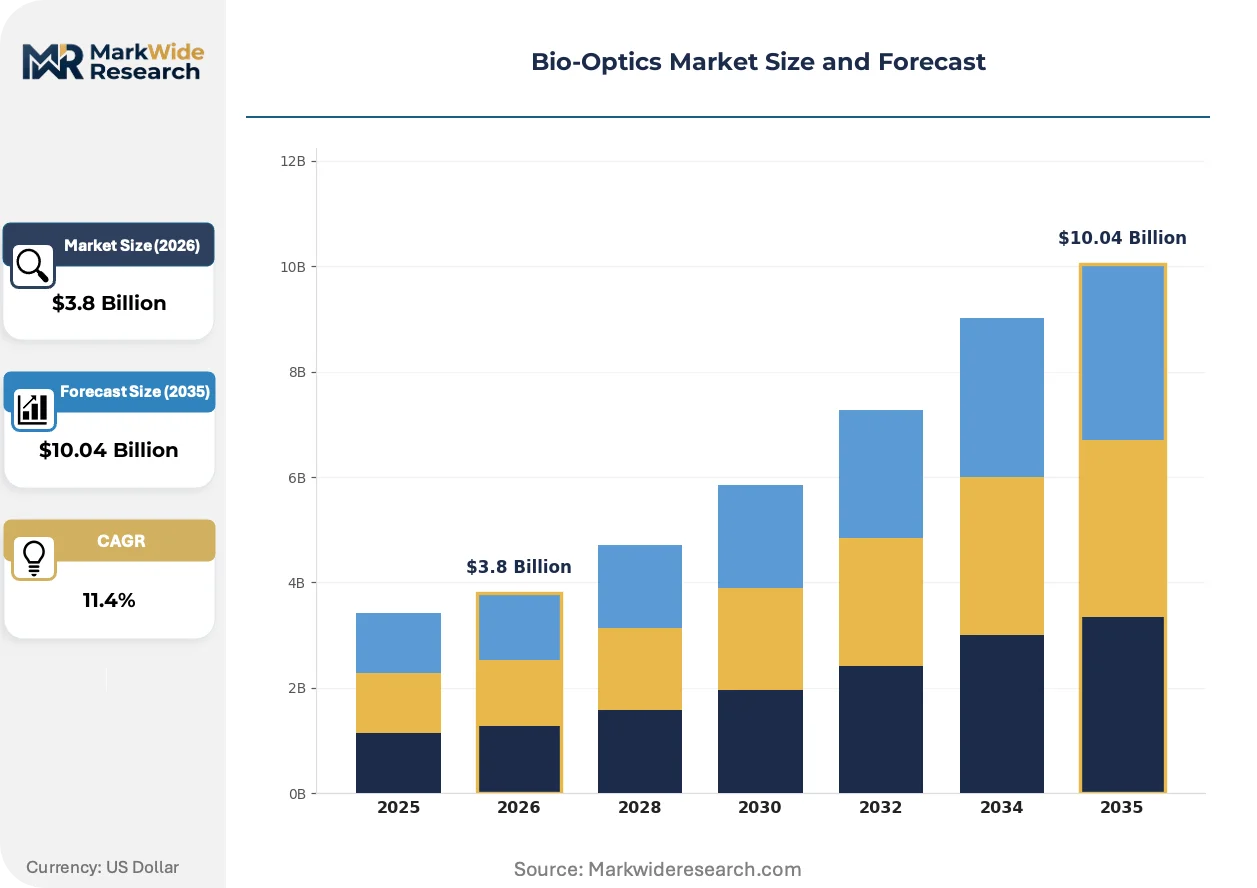
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopy Systems, Microscopes, Optical Coherence Tomography, Imaging Systems Application: Diagnostic Imaging, Surgical Procedures, Research, Therapeutics Technology: Fluorescence Imaging, Raman Spectroscopy, Laser Scanning, Wavefront Sensing End User: Hospitals, Laboratories, Research Institutions, Clinics |
| Companies Covered | Carl Zeiss AG, Olympus Corporation, Hamamatsu Photonics, Thermo Fisher Scientific, Becton Dickinson & Company, Nikon Corporation, Leica Microsystems, IPG Photonics, Oxford Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Optics Market Strategic Shifts
Optical coherence tomography hardware architectures are splitting between premium swept-source systems for academic medical centers and compact spectral-domain units for community ophthalmology practices.
Adaptive optics retinal imaging is bifurcating the high-end microscopy market. Academic vision science departments are deploying deformable mirror systems for single-cell resolution in living human retina. Commercial manufacturers are compressing these architectures into clinic-compatible footprints. This divergence is enabling tiered pricing strategies that separate research-grade performance from diagnostic throughput economics.
EU MDR clinical evidence requirements are reshaping optical diagnostic commercialization timelines. Manufacturers must generate prospective performance data for fluorescence-guided surgery platforms seeking CE marking. Smaller developers are responding by prioritizing FDA 510(k) clearance for US market entry before addressing European notified body demands.
Hospital procurement committees are consolidating vendor relationships around integrated service contracts. Single-source agreements covering OCT systems, maintenance, and disposable supplies are displacing capital-equipment-only purchases in German and French hospital networks. This bundling is most advanced in university hospital consortia with centralized biomedical engineering oversight.
Bio-Optics Market Segmentation
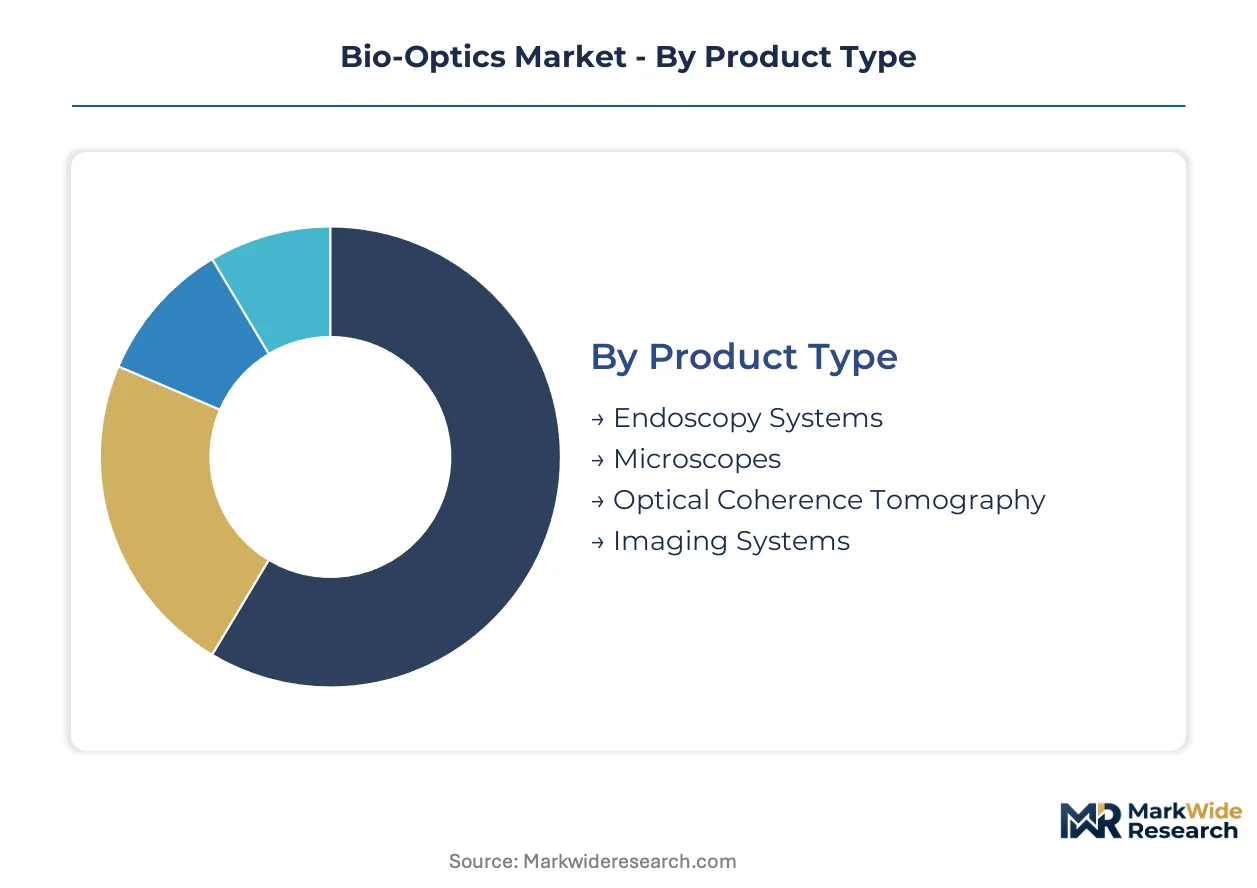
Segmentation in bio-optics reveals how procurement authority, regulatory pathways, and clinical workflows reshape vendor strategies across hardware platforms and service models. Understanding these divisions exposes where budget consolidation and technology substitution are rewriting competitive dynamics.
Product Type:
FDA 510(k) clearance timelines diverge sharply across hardware categories, with laser-integrated systems facing extended documentation requirements versus passive imaging platforms.
- Endoscopy Systems:Flexible fiber-optic and video-based platforms dominate gastrointestinal screening protocols with entrenched reimbursement codes. Hospital procurement committees in Germany and France are consolidating vendor relationships around bundled service contracts covering maintenance and disposable supplies.
- Optical Coherence Tomography:Swept-source variants for retinal vasculature mapping are pulling replacement demand from time-domain systems in ophthalmology clinics. The technology is climbing the fastest as community practices adopt compact spectral-domain units alongside premium academic medical center deployments.
- Microscopes:Super-resolution and adaptive optics variants serve structural biology and vision science research with sub-100nm resolution capabilities.
- Imaging Systems:Integrated fluorescence and Raman platforms support intraoperative margin assessment and real-time tissue characterization.
Established volume favors Endoscopy Systems; emerging adoption favors Optical Coherence Tomography.
Application:
Cost tier separation runs deepest between reimbursed diagnostic protocols and investigational therapeutic applications with uncertain payment pathways.
- Diagnostic Imaging:Non-invasive tissue interrogation using OCT and fluorescence modalities commands predictable reimbursement under established CPT codes. EU MDR Article 61 harmonization is accelerating cross-border tender participation for optical diagnostic devices seeking CE marking.
- Surgical Procedures:Laser-based instruments and fluorescence-guided platforms require FDA 510(k) clearance with clinical performance documentation. Operating room integration demands are forcing vendors to reconfigure distribution toward integrated health system contracts.
- Research:Academic institutions are unwinding historical procurement dominance as funding models shift toward shared core facilities.
- Therapeutics:Photodynamic therapy and laser ablation systems face extended regulatory timelines due to combined device-drug classification complexities.
Reimbursement certainty favors Diagnostic Imaging; margin expansion favors Surgical Procedures.
Technology:
Customer type bifurcation separates high-throughput clinical screening from precision research instrumentation with divergent performance specifications.
- Fluorescence Imaging:Widely deployed across research settings with established fluorophore workflows and photomultiplier tube detection architectures. Supply concentration in rare-earth dopant sourcing for laser crystals exposes price volatility to Chinese processor spot markets.
- Raman Spectroscopy:Real-time molecular fingerprinting is displacing frozen-section histology in breast and brain surgery suites for intraoperative margin assessment. The modality is gaining share fastest as pathology departments seek workflow compression.
- Laser Scanning:Confocal and multiphoton variants enable deep tissue imaging with optical sectioning capabilities for neuroscience applications.
- Wavefront Sensing:Adaptive optics control systems correct for optical aberrations in retinal imaging and astronomical-scale microscopy platforms.
Research penetration favors Fluorescence Imaging; clinical translation favors Raman Spectroscopy.
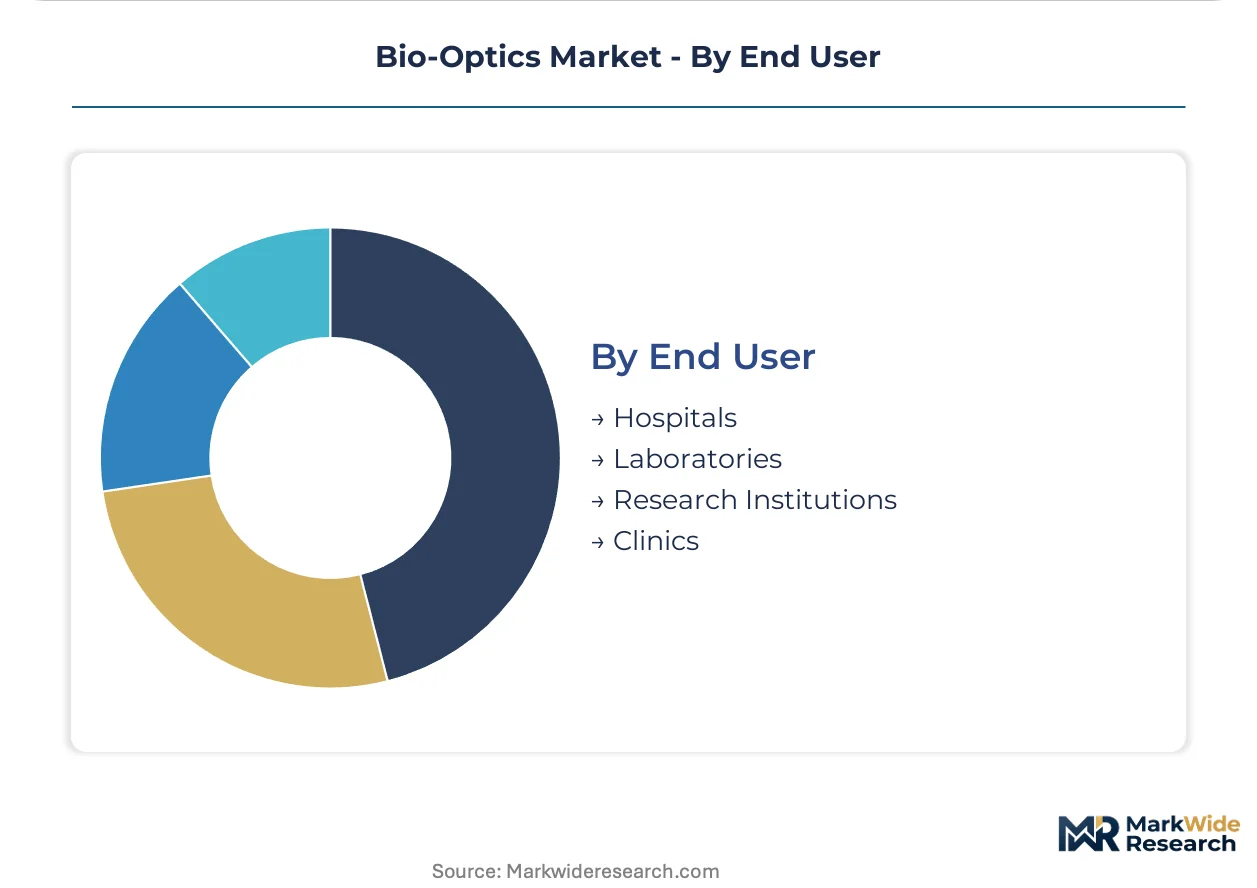
End User:
Geography concentration in German precision optics clusters shapes procurement patterns for European hospital networks and research consortia.
- Hospitals:Surgical departments and diagnostic imaging units are consolidating budget authority over academic institutions, compressing vendor sales cycles. Centralized biomedical engineering oversight in university hospital consortia is driving single-source agreements for integrated service contracts.
- Clinics:Community ophthalmology practices are adopting technician-operated OCT screening with AI-embedded segmentation for primary care settings. India CDSCO fast-track pathways for laser-based surgical devices are opening government hospital procurement access.
- Laboratories:Commercial diagnostic chains are gaining procurement authority alongside hospital networks for high-throughput screening platforms.
- Research Institutions:Aging cohorts of photonics engineering talent in German and Japanese institutes constrain free-space optical design capabilities.
Procurement scale favors Hospitals; workflow innovation favors Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube canal network anchors Central European distribution for precision glass substrates and optical instrument assemblies, connecting German manufacturing clusters to North Sea ports and Mediterranean markets.
United States
Ophthalmology clinic chains and academic medical centers drive swept-source OCT procurement, with hospital surgical departments consolidating vendor relationships. FDA 510(k) pathways govern laser-based surgical instrument commercialization, compressing clearance timelines for fluorescence-guided platforms. Boston and San Diego harbor photonics startups commercializing adaptive optics retinal imaging.
Germany
Carl Zeiss AG and Leica Microsystems anchor precision optics manufacturing serving European hospital networks. EU MDR Article 61 harmonizes clinical evidence requirements for optical diagnostic devices, accelerating cross-border tender participation. Baden-Württemberg and Thuringia concentrate glass-making heritage and metrology infrastructure, shortening prototype-to-production timelines for fluorescence microscopy.
Japan
Hamamatsu Photonics sustains photomultiplier tube supply for fluorescence imaging systems, while academic vision science departments deploy deformable mirror systems. PMDA quality system inspections extend clearance timelines for imported microscopy platforms. Tokyo and Osaka metropolitan areas concentrate aging cohorts of photonics engineering talent in free-space optical design.
India
Government hospital procurement chains are opening to laser-based surgical devices through CDSCO fast-track approval pathways. Community ophthalmology practices adopt technician-operated OCT screening for primary care settings. Maharashtra and Karnataka host emerging diagnostic chains gaining procurement authority alongside hospital networks.
China
Rare-earth dopant processing for laser crystals concentrates among domestic processors, exposing ytterbium and erbium oxide spot market volatility to global instrument manufacturers. NMPA regulations govern imported microscopy platform registration. Yangtze River Delta manufacturing hubs supply optical component assemblies to European and North American system integrators.
Bio-Optics Market Competitive Environment
Concentration sits with heritage optics conglomerates and diversified life-science platforms, while specialized photonics component suppliers occupy narrower verticals. The vendor base stratifies across three tiers: century-old precision glass manufacturers with captive substrate production, integrated instrument platforms bundling hardware with reagent workflows, and component specialists supplying photodetectors and laser sources. Dominant competitive moves include backward integration into rare-earth crystal growth and strategic partnerships compressing hospital procurement cycles.
Among heritage German precision optics manufacturers, Carl Zeiss AG and Leica Microsystems exemplify the substrate-to-system archetype, while Hamamatsu Photonics occupies a position within the photodetector component tier. Thermo Fisher Scientific represents the diversified life-science platform model, bundling optical instruments with consumable workflows. These anchors illustrate how competitive positioning diverges between captive glass-making capabilities and integrated reagent-instrument ecosystems.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Olympus Corporation |
| Hamamatsu Photonics |
| Thermo Fisher Scientific |
| Becton Dickinson & Company |
| Nikon Corporation |
| Leica Microsystems |
| IPG Photonics |
| Oxford Instruments |
| Others |
Value Chain & Pricing Dynamics
Long-term service contracts covering OCT systems, maintenance, and disposable supplies lock in both supply access and price visibility for German and French hospital networks, compressing vendor margins while securing multi-year revenue streams for instrument manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates swept-source OCT systems for academic medical centers from compact spectral-domain units for community practices and basic endoscopy platforms for high-volume screening programs. Price differentiation hinges on resolution specifications and FDA 510(k) clearance tier, with premium systems commanding substantial markups for adaptive optics capabilities. Pricing pressure stems from hospital procurement committee consolidation around bundled agreements, forcing vendors to absorb service costs. Community ophthalmology clinics exhibit highest price sensitivity, while university hospital consortia prioritize performance metrics over unit economics.
Supply Chain Analysis
Rare-earth dopant processing for ytterbium and erbium oxide laser crystals concentrates among Chinese processors, exposing German and Japanese instrument manufacturers to commodity spot market volatility. Optical glass substrate production draws from Baden-Württemberg and Thuringia metrology clusters, while photomultiplier tube assembly rests on Hamamatsu manufacturing capabilities. Single-source vulnerability in fluorophore supply chains threatens production continuity for fluorescence microscopy platforms. Distribution runs through integrated health system contracts rather than capital-equipment-only sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-optics market is climbing out of a procurement cycle trough, with hospital surgical departments regaining capital expenditure authority after pandemic-era budget freezes.
For Market Incumbents: Fortify captive substrate production by backward integration into rare-earth crystal growth, insulating margin structures from Chinese processor spot volatility. Deepen hospital system partnerships through AI-embedded OCT software companions that lock in recurring revenue streams and raise switching costs against emerging competitors. For New Entrants and Emerging Players: Lead with technician-operated OCT screening platforms for India's government hospital procurement chains, where CDSCO fast-track pathways compress regulatory timelines versus established markets. Target community ophthalmology practices in Maharashtra and Karnataka with compact spectral-domain systems priced below premium swept-source alternatives, leveraging local diagnostic chain relationships for distribution. For Investors and Strategic Acquirers: Photonics component specialists with photodetector or laser source expertise represent the most defensible acquisition targets, given aging engineering cohorts in German and Japanese institutes. Monitor FDA breakthrough device designations for fluorescence-guided surgery platforms as the inflection signal for clinical validation maturity and reimbursement pathway clarity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Crystal Growth | Captive ytterbium and erbium oxide supply secures laser source production against Chinese processor volatility. |
| AI-Embedded OCT Software Development | Machine learning segmentation enables technician-operated screening in primary care settings beyond ophthalmology. |
| CDSCO Fast-Track Regulatory Pathway | Accelerated approval opens government hospital procurement chains in Maharashtra and Karnataka to new entrants. |
| EU MDR Article 61 Compliance Investment | Prospective clinical performance data generation enables CE marking for cross-border European tender participation. |
| Hospital System Integrated Service Contracts | Bundled maintenance and disposable agreements displace capital-equipment-only sales in German university hospital consortia. |
Study Parameters
A standing panel of biomedical engineers, hospital purchasing committee chairs, ophthalmology clinic directors, and fluorescence microscopy core facility managers provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation against FDA 510(k) filings, EU MDR notified body documentation, PMDA quality system inspection records, and hospital procurement database extracts. Bottom-up instrument shipment tracking and top-down healthcare capital expenditure analysis triangulated market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including product hardware category, clinical application workflow, underlying photonics technology, and end-user facility type. CAGRs were derived from instrument replacement cycle analysis and adoption curve modeling for emerging modalities. Forecast inputs incorporated swept-source OCT penetration rates and intraoperative Raman spectroscopy displacement of frozen-section histology.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU MDR Article 61 standards, and Japan PMDA inspection protocols; material policy shifts would require re-modeling. Specific risk factors that could revise projections include fluorophore supply disruptions, photonics engineering talent attrition, and divergence between breakthrough device designation criteria and notified body clinical evidence demands. Practitioners should keep alternative scenarios live as hospital procurement consolidation patterns and AI-embedded diagnostic reimbursement frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Co-Packaged Optics Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Diode Laser Module Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Asia-Pacific Tunable Laser Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Erbium Oxide Market
Optical Components
Spatial Light Modulator Market
Optical Components
Photosensitive Glass Market
Optical Components
Optical Film Market
Optical Components
Polarizer Film Market
Optical Components
CMP Polishing Machine Market
Optical Components
Microchannel Plates Market
Optical Components
Global Fiber Bragg Grating Amplifier Market
Optical Components
Photomask Pellicle Market