
 Spatial Light Modulator Market | 2026-2036
Spatial Light Modulator Market Size, Share, and Industry Trends Forecast 2026-2036
Spatial Light Modulator Market Outlook
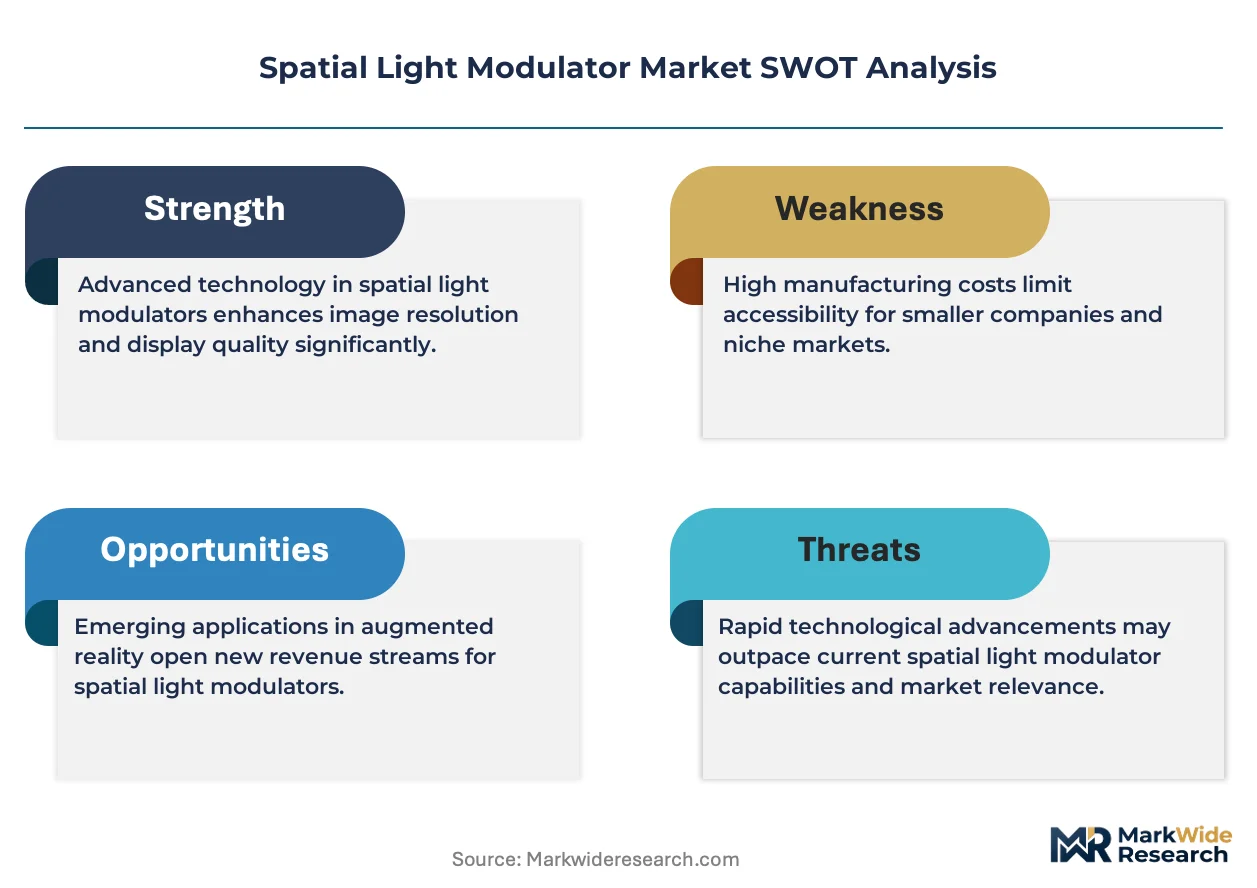
Project finance for semiconductor fabrication equipment is tilting competitive dynamics toward firms with balance-sheet capacity to secure long-term leases on lithography-adjacent tooling. Texas Instruments leverages captive foundry relationships to sustain pricing power in digital light processing chips. Hamamatsu Photonics anchors its position through vertical integration into photodiode and modulator assembly. Jenoptik specializes in precision optics for industrial laser systems, occupying a defensible niche in European manufacturing supply chains.
A spatial light modulator is an optoelectronic device that dynamically manipulates the amplitude, phase, or polarization of light through pixelated arrays, typically achieving resolutions from XGA to 4K with refresh rates exceeding 60 Hz for real-time holographic reconstruction. Its primary commercial purpose centers on wavefront engineering for display projection, optical switching, and structured illumination in microscopy. LCoS architectures command premium positioning in near-eye display applications for augmented reality headsets where pixel density determines image fidelity. MEMS-based micro-mirror technologies lead in high-brightness cinema and venue projection where thermal stability outweighs cost sensitivity. LCD modulators compete aggressively in cost-constrained holography education and research tools where optical throughput requirements remain moderate.
The FCC governs electromagnetic emissions from spatial light modulator drivers in US telecommunications equipment, while the EU RoHS directive restricts hazardous substances in optoelectronic component manufacturing across European supply chains. Japan's METI sets efficiency benchmarks for display technologies that influence LCoS and OLED modulator design priorities for consumer electronics export markets. Stakeholders must monitor divergence between US and EU regulatory timelines for optical device certification to avoid stranded inventory in cross-border distribution channels.
Market Dynamics
Project finance concentration for lithography-adjacent tooling is consolidating competitive positioning around firms with captive foundry access, tilting procurement leverage toward vertically integrated photonics suppliers in Germany and Japan.
Growth Catalysts
- Telecom Infrastructure Buildout:Optical communication networks are expanding adoption of liquid crystal on silicon modulators for wavelength-selective switching in fiber backbone upgrades.
- EU F-Gas Regulation:Tightening fluorinated gas controls are accelerating supply chain reconfiguration toward closed-loop manufacturing processes in European precision optics clusters.
- Precision Optics Clustering:Demand is concentrating in Germany's Jena-Berlin corridor, where captive cleanroom capacity and metrology infrastructure reduce qualification timelines for defense and semiconductor customers.
Market Restraints
- Input Cost Volatility:Indium tin oxide and rare-earth dopant prices fluctuate with Chinese export quotas, compressing margins on high-fill-factor LCoS backplanes.
- Supply Concentration Risk:MEMS foundry capacity for deformable mirror arrays clusters in Taiwan and South Korea, creating single-source vulnerability for aerospace wavefront correction systems.
- Technical Limitation:Thermal drift in high-power laser modulation remains unresolved below 50 millisecond settling times, excluding SLMs from industrial materials processing above kilowatt thresholds.
Strategic Opportunities
- Underpenetrated Geographies:India's semiconductor packaging ecosystem under PLI scheme incentives offers captive demand for inspection-grade structured illumination modulators.
- Technology Convergence:Integration of photonic integrated circuits with silicon photonics modulators is opening chip-scale LiDAR architectures for automotive qualification pipelines.
- Regulatory Tailwind:Japan's METI efficiency benchmarks for display technologies are mandating higher pixel density in near-eye systems, favoring LCoS over OLED microdisplays.
Industry Challenges
- Skill Gap in Photonics Assembly:Active alignment of MEMS micro-mirror arrays requires sub-micron precision that outstrips available technician training pipelines in North American manufacturing zones.
- Certification Timeline Compression:FCC electromagnetic emissions testing for telecom-grade SLM drivers extends qualification cycles by 8-14 months, straining working capital for mid-cap suppliers.
- Integration Complexity:Legacy microscopy platforms in European research institutions use proprietary camera interfaces that resist firmware adaptation for modern holographic reconstruction workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spatial Light Modulator Market |
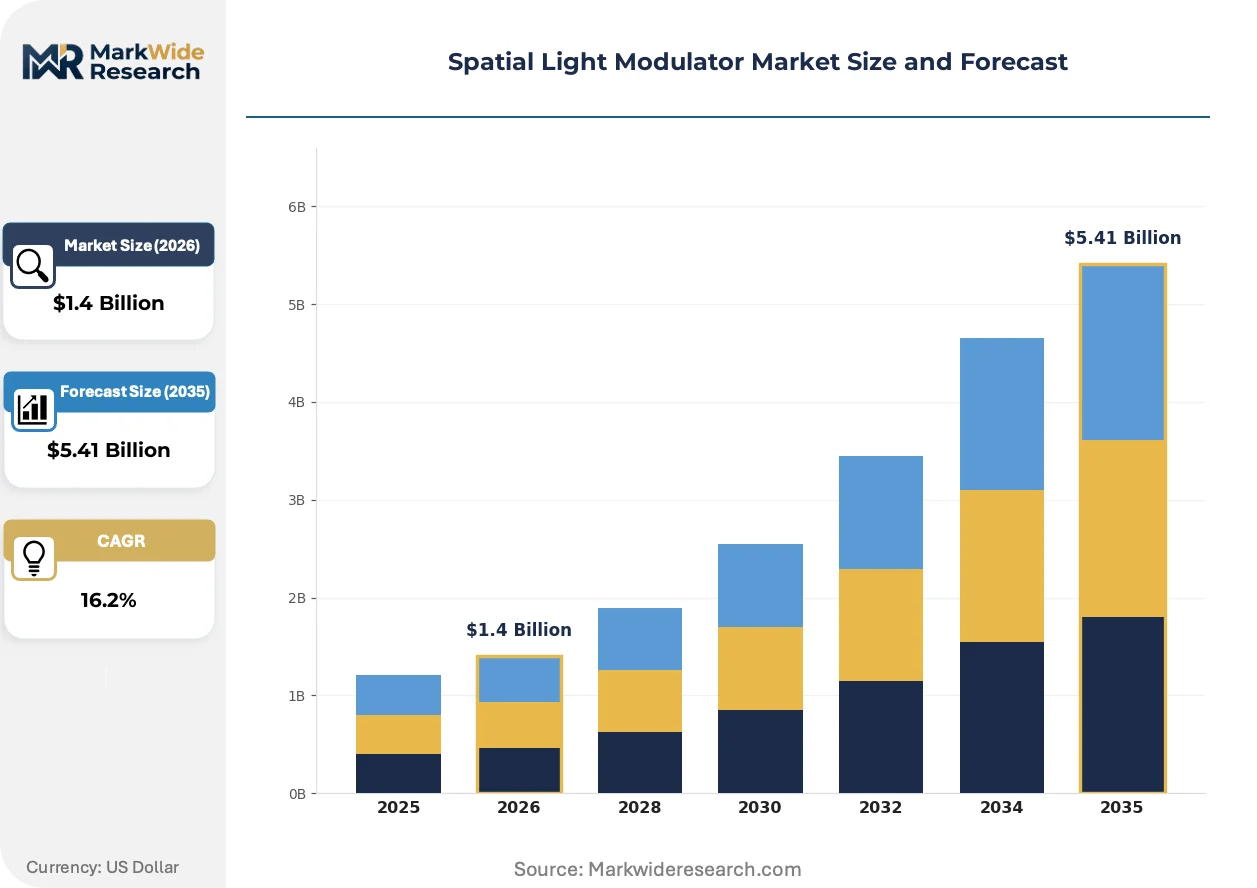
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DLP, LCD, LCoS, OLED Application: Projectors, Displays, Optical Communication, Holography End User: Consumer Electronics, Automotive, Aerospace, Defense Technology: Digital Light Processing, Liquid Crystal Display, Micro-mirror, MEMS |
| Companies Covered | Santec Corporation, Jenoptik, Hamamatsu Photonics, Barco, Texas Instruments, HOLOEYE Photonics, Meadowlark Optics, Kopin Corporation, Thorlabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spatial Light Modulator Market Strategic Shifts
Wavefront engineering architectures are fragmenting across application-specific optimization, with thermal management and pixel density emerging as the primary axes of technical differentiation.
Phase-only modulation is migrating from academic holography setups into industrial metrology systems. Semiconductor wafer inspection toolmakers are adopting ferroelectric liquid crystal SLMs for sub-wavelength defect detection. The shift is compressing addressable market boundaries between research-grade and production-grade modulator tiers.
Europe's F-Gas Regulation is tightening supply chain accountability for fluorinated greenhouse gases used in liquid crystal precursor synthesis. Manufacturers must now document cradle-to-gate emissions for RoHS compliance in optoelectronic components. German precision optics suppliers are responding by qualifying alternative nematic mixtures from domestic chemical synthesis partners.
Buyer consolidation in augmented reality hardware is compressing supplier qualification cycles from 18 months to 9 months. Tier-one headset manufacturers are unbundling reference design licensing from component procurement, forcing modulator vendors to absorb NRE costs upfront. This pattern is most visible in California and Shenzhen consumer electronics supply chains.
Spatial Light Modulator Market Segmentation
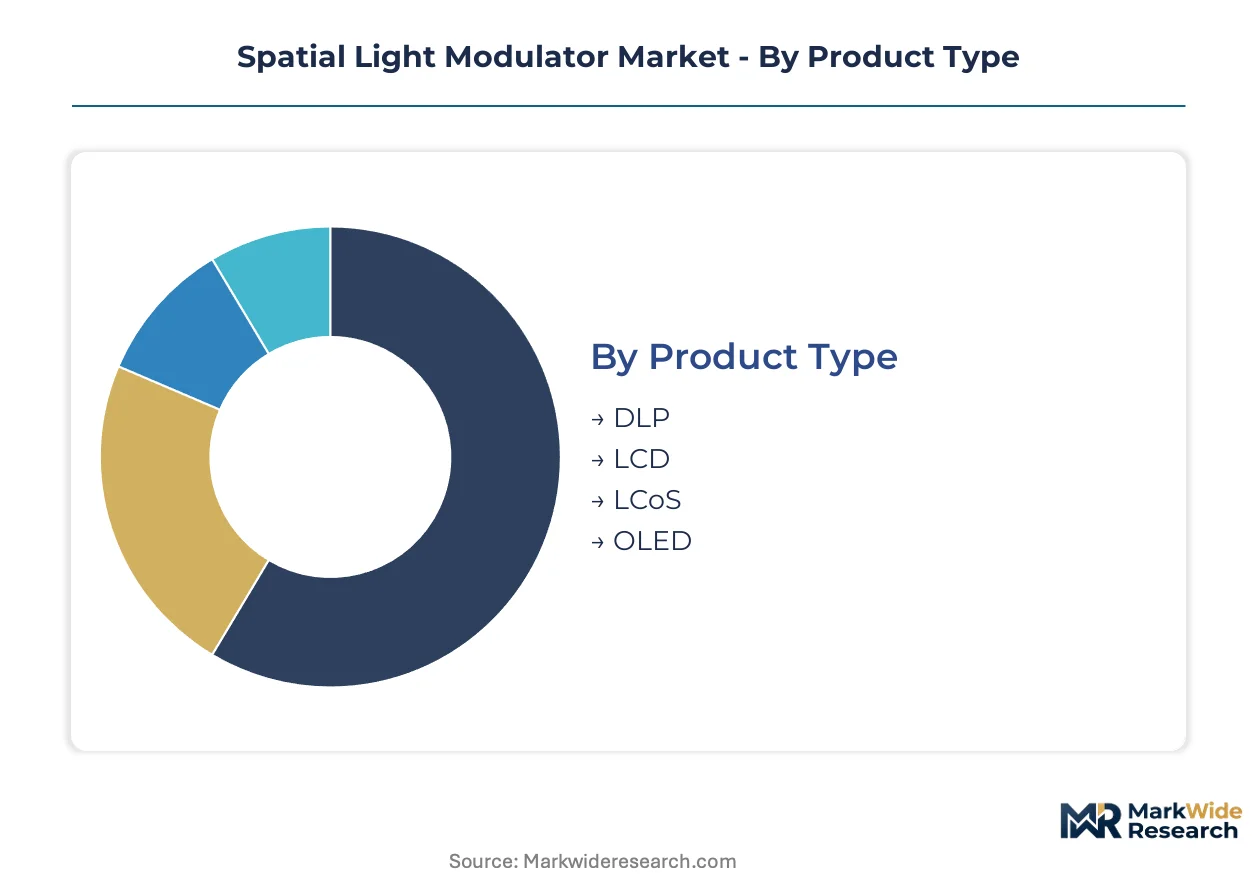
Segmentation in spatial light modulators reveals how technical specifications and application requirements fragment procurement patterns. Different end-uses impose incompatible demands on refresh rates, thermal budgets, and optical throughput that reshape vendor specialization strategies.
Product Type:
After-sales service intensity varies sharply across product architectures, with MEMS-based arrays requiring active alignment recalibration and liquid crystal systems demanding periodic cell replacement.
- LCoS:Liquid crystal on silicon architectures achieve pixel densities exceeding 3,000 PPI through CMOS backplane integration. Demand concentrates in augmented reality near-eye displays where California and Shenzhen headset manufacturers prioritize fill factor over switching speed. Thermal drift compensation requires firmware updates that extend vendor service relationships.
- DLP:Digital light processing employs aluminum micro-mirror arrays tilted electrostatically for binary modulation. Cinema and venue projection in North American multiplex chains drives volume, with Texas Instruments' captive foundry relationships constraining second-source availability. Mirror hinge fatigue necessitates field service protocols every 4,000 operating hours.
- LCD:Transmissive liquid crystal panels modulate amplitude through polarization rotation at lower cost points. Educational holography systems in European university labs absorb volume where optical throughput requirements remain moderate.
- OLED:Organic electroluminescent arrays enable direct emission modulation without external illumination. Emerging microdisplay applications in Japanese medical visualization equipment favor self-emissive architectures for contrast ratio.
LCoS holds the largest share; momentum sits with OLED as self-emissive architectures gain share fastest in medical and defense applications.
Application:
Cost tier stratification separates qualification-intensive production systems from research-grade tools with relaxed environmental specifications.
- Optical Communication:Wavelength-selective switching in fiber backbone infrastructure demands sub-millisecond response times for dynamic channel allocation. Germany's Jena precision optics cluster supplies telecom-grade LCoS modulators with hermetic sealing for undersea cable repeaters.
- Projectors:High-brightness cinema and corporate presentation systems prioritize thermal stability over pixel density. MEMS micro-mirror arrays from Taiwanese foundries dominate this segment where lumen output determines competitive positioning.
- Displays:Near-eye and head-up display systems require angular resolution matching human visual acuity. Automotive HUD qualification pipelines in Stuttgart and Detroit impose vibration resistance standards exceeding consumer electronics benchmarks.
- Holography:Phase-only modulation for wavefront engineering serves semiconductor wafer inspection and academic research. Ferroelectric liquid crystal SLMs from Japanese suppliers address sub-wavelength defect detection in Korean memory fab expansion projects.
Optical Communication holds the largest share; momentum sits with Holography as industrial metrology adoption accelerates.
End User:
Customer type fragmentation separates volume procurement with extended payment terms from low-volume defense contracts with cost-plus structures.
- Consumer Electronics:AR headset and smartphone accessory manufacturers drive the steepest volume expansion. California-based platform holders compress supplier qualification cycles from 18 months to 9 months, forcing modulator vendors to absorb NRE costs upfront.
- Defense:Aerospace wavefront correction for directed energy and surveillance systems demands ITAR-compliant supply chains. German and Israeli precision optics houses maintain captive cleanroom capacity for classified programs with multi-year procurement horizons.
- Automotive:LiDAR and HUD integration requires AEC-Q100 qualification for thermal cycling resistance. Stuttgart OEMs specify MEMS scanners from Bosch and Continental supply bases with 15-year lifetime requirements.
- Aerospace:Satellite optical communication and space-based sensing impose radiation-hardening constraints. European Space Agency qualification protocols in the Netherlands limit vendor pools to heritage suppliers with flight-proven track records.
Consumer Electronics holds the largest share; momentum sits with Automotive as chip-scale LiDAR architectures approach series production.
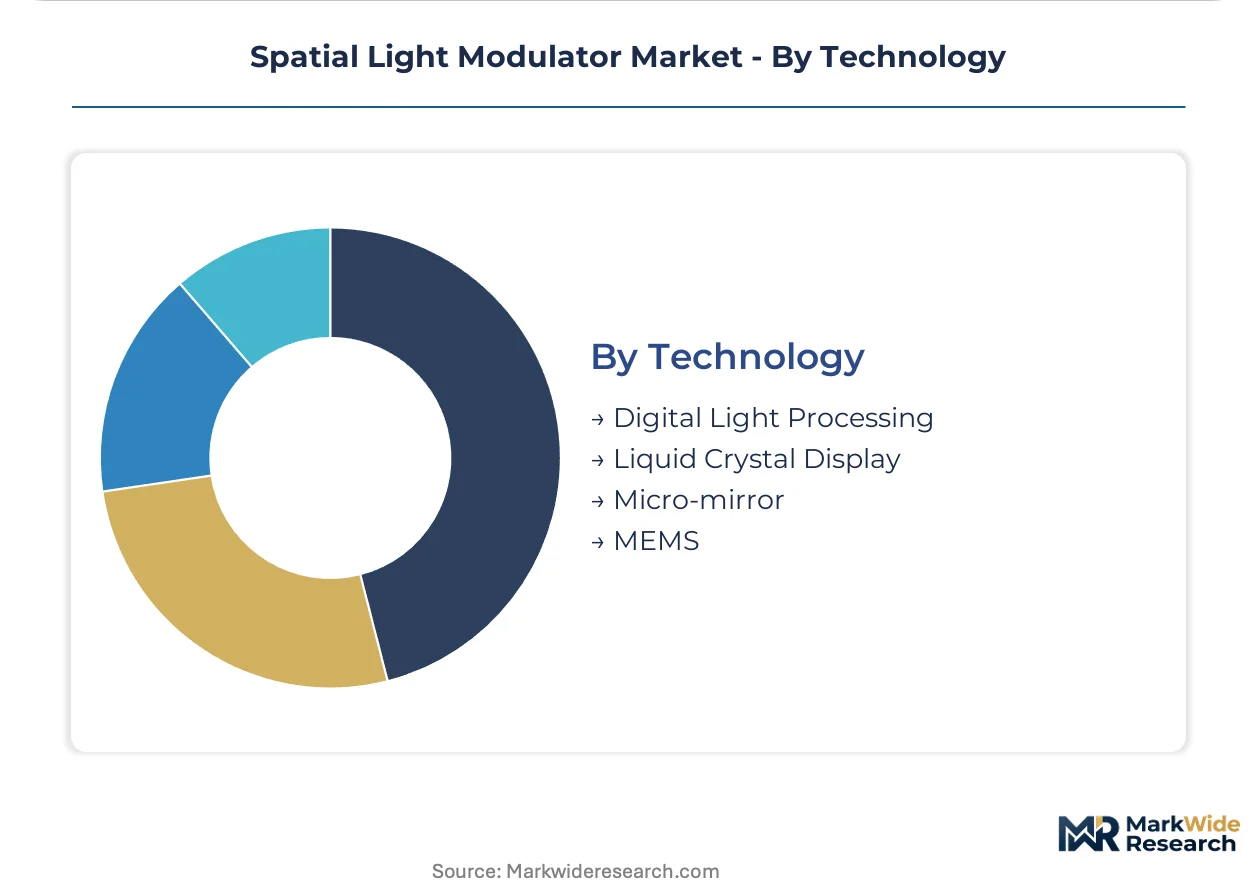
Technology:
Supply concentration in foundry capacity shapes competitive access, with captive MEMS fabrication in Japan and Taiwan constraining second-source availability.
- MEMS:Micro-electromechanical systems achieve mechanical beam steering through electrostatic comb drives. Taiwanese foundry concentration for deformable mirror arrays creates single-source vulnerability for aerospace wavefront correction.
- Digital Light Processing:Binary mirror tilt modulation enables high-contrast projection with mature manufacturing economics. Texas Instruments' proprietary process control sustains pricing power in cinema and education markets.
- Liquid Crystal Display:Nematic and ferroelectric phases offer continuous phase modulation at moderate switching speeds. EU F-Gas Regulation compliance costs are accelerating supply chain reconfiguration toward closed-loop precursor synthesis.
- Micro-mirror:Piezoelectric and electrothermal actuation variants address niche scanning applications. Medical OCT systems in Japanese and German diagnostic equipment favor resonant scanning architectures for acquisition speed.
Digital Light Processing holds the largest share; momentum sits with MEMS as photonic integrated circuit co-packaging enables chip-scale form factors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI efficiency benchmarks for display technologies are redirecting capital toward LCoS fabrication capacity. Germany's EU F-Gas Regulation compliance costs are accelerating closed-loop manufacturing investments in liquid crystal precursor synthesis. India's PLI scheme for semiconductor packaging is creating captive demand for inspection-grade structured illumination systems.
United States
Defense aerospace wavefront correction programs and telecom infrastructure buildouts drive procurement concentration. FCC electromagnetic emissions testing extends SLM driver qualification cycles by 8-14 months, straining working capital for mid-cap suppliers. California's AR headset manufacturers compress supplier qualification timelines from 18 months to 9 months.
Germany
Precision optics for industrial laser systems and semiconductor wafer inspection tools anchor demand volumes. EU F-Gas Regulation tightening controls fluorinated greenhouse gases in liquid crystal precursor synthesis, forcing supply chain reconfiguration. The Jena-Berlin corridor consolidates captive cleanroom capacity and metrology infrastructure for defense and semiconductor customers.
Japan
Medical visualization equipment and photonic integrated circuit development command premium positioning. METI efficiency benchmarks mandate higher pixel density in near-eye display systems, favoring LCoS architectures over OLED microdisplays. Hamamatsu Photonics anchors vertical integration into photodiode and modulator assembly from domestic fabrication bases.
South Korea
Memory fab expansion projects and automotive LiDAR qualification pipelines absorb production volumes. MEMS foundry capacity for deformable mirror arrays concentrates in Taiwanese and Korean facilities, creating single-source vulnerability for aerospace applications. Seoul-based suppliers are qualifying ferroelectric liquid crystal SLMs for sub-wavelength defect detection tools.
India
Semiconductor packaging ecosystem growth under PLI scheme incentives generates inspection-grade modulator demand. The country's national electronics regulator enforces EMC compliance for telecom equipment imports, aligning with FCC and EU RoHS timelines. Karnataka and Telangana are emerging as captive demand centers for structured illumination in automated optical inspection systems.
Spatial Light Modulator Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated photonics suppliers with captive foundry access and lithography-adjacent tooling capacity. Three strategic archetypes dominate: precision optics houses with cleanroom infrastructure, semiconductor fabricators leveraging CMOS backplane integration, and MEMS foundry operators controlling deformable mirror array supply. Competitive moves center on strategic partnerships for photonic integrated circuit co-packaging and geographic expansion into underpenetrated automotive qualification pipelines.
Among Japanese precision optics specialists, Hamamatsu Photonics and Santec Corporation exemplify the vertically integrated archetype through in-house production of photodiode and modulator components. Texas Instruments represents the semiconductor-fabricator model with captive foundry relationships sustaining pricing power in digital light processing. German GmbH-structured players including Jenoptik and HOLOEYE Photonics occupy positions in European industrial laser and holography supply chains, with Jena-based cleanroom capacity reducing qualification timelines for defense customers.
| Leading Market Players |
|---|
| Santec Corporation |
| Jenoptik |
| Hamamatsu Photonics |
| Barco |
| Texas Instruments |
| HOLOEYE Photonics |
| Meadowlark Optics |
| Kopin Corporation |
| Thorlabs |
| Others |
Value Chain & Pricing Dynamics
Jena's precision optics cluster anchors European supply capacity for hermetically sealed LCoS modulators, concentrating pricing leverage among German suppliers with captive cleanroom infrastructure. Taiwan's MEMS foundry dominance for deformable mirror arrays feeds downstream cost compression in aerospace wavefront correction tiers. Buyers in California's AR headset supply chains face compressed qualification timelines that force upfront NRE absorption, reshaping contract structures toward performance-based milestones.
Pricing Analysis
Certification level (ITAR/FCC-grade versus commercial CE-marked) creates the primary spread between defense-aerospace and consumer electronics procurement. Three-tier pricing structure across ITAR-compliant, telecom-grade, and educational-research levels separates qualification-intensive production systems from cost-constrained holography tools. Pricing pressure stems from indium tin oxide and rare-earth dopant volatility tied to Chinese export quota fluctuations. Consumer electronics manufacturers exhibit highest price sensitivity, while defense programs with cost-plus structures tolerate premium positioning for ITAR compliance.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for photodiode and CMOS backplane sourcing. Manufacturing concentrates in Germany, Taiwan, and Japan, with Jena-Berlin corridor cleanrooms and Taiwanese MEMS foundries anchoring capacity. Raw material dependencies center on liquid crystal precursors, indium tin oxide sputtering targets, and aluminum micro-mirror substrates. Single-source vulnerability persists for aerospace-grade deformable mirror arrays. Distribution runs through precision optics distributors in Stuttgart and direct OEM contracts in California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active alignment technician scarcity constrains MEMS micro-mirror production scaling, with sub-micron precision requirements outstripping North American training pipeline capacity. Foundry access and metrology infrastructure emerge as the binding constraints on competitive positioning.
For Market Incumbents: Build captive cleanroom moats in the Jena-Berlin corridor to defend against Asian MEMS foundry expansion. Secure long-term lithography-adjacent tooling leases before project finance concentration tilts procurement leverage. Invest in closed-loop liquid crystal precursor synthesis to preempt EU F-Gas Regulation compliance cost escalation. Absorb NRE costs for AR headset reference designs to lock in 9-month qualification cycles before buyer consolidation hardens. For New Entrants and Emerging Players: Build out inspection-grade structured illumination capabilities for India's semiconductor packaging ecosystem under PLI scheme incentives. Target Karnataka and Telangana captive demand centers where automated optical inspection modulator supply remains thin. Pursue chip-scale LiDAR co-packaging partnerships with Stuttgart automotive OEMs as AEC-Q100 qualification pipelines mature. Lead with firmware-adaptable holographic reconstruction interfaces to bypass legacy microscopy platform resistance in European research institutions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision optics houses with multi-year defense service contracts and thermal drift compensation firmware updates. Five-to-ten year viability favors vertically integrated suppliers with photodiode-to-modulator assembly control and heritage ESA flight-proven track records. Target acquisition archetype: German GmbH-structured players with Jena cleanroom capacity and ITAR-compliant supply chains. Watch for inflection when Japan's METI efficiency benchmarks mandate LCoS pixel density thresholds that disqualify OLED microdisplay alternatives in near-eye systems.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Integrated Circuit Co-packaging | Enables chip-scale LiDAR form factors for Stuttgart automotive qualification pipelines. |
| Closed-loop Liquid Crystal Precursor Synthesis | Secures EU F-Gas Regulation compliance for Jena-Berlin corridor manufacturing. |
| ITAR-compliant Cleanroom Capacity Expansion | Captures multi-year defense procurement horizons with cost-plus contract structures. |
| Firmware-adaptable Holographic Interfaces | Resolves legacy microscopy platform integration friction in European research institutions. |
| Active Alignment Technician Training Programs | Addresses sub-micron precision skill gaps constraining MEMS micro-mirror production scaling. |
Study Parameters
Cross-validation between primary interviews with precision optics R&D directors and secondary analysis of ESA qualification protocols anchors the qualitative findings. The study combines field discussions with MEMS foundry operations managers, telecom equipment procurement leads, and augmented reality hardware platform engineers against SEC filings, customs trade data, and METI efficiency benchmark disclosures. Bottom-up triangulation across product architecture segments and top-down validation against regional cluster capacity data ensures consistency.
Calibration against historical capacity utilization rates and foundry expansion announcements shapes the analytical framework across the projection horizon. Segmentation dimensions include modulator technology (LCoS, DLP, LCD, OLED), application tier (optical communication, holography, projection, display), and end-user qualification intensity (defense ITAR, automotive AEC-Q100, consumer electronics). CAGRs derive from weighted average of demand elasticity estimates and supply-side capacity constraints. Industry-specific inputs encompass EU F-Gas Regulation compliance cost trajectories and PLI scheme incentive absorption rates.
Stress conditions across indium tin oxide price volatility, Taiwanese foundry utilization thresholds, and FCC certification timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding METI benchmark adoption timing and defense procurement continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
Optical Position Sensors Market
Optical Components
Ring Laser Gyroscope Market
Optical Components
Optical Dome Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Global Optical Measurement Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
South Korea Optical Detector Market
Optical Components
Optical Amplifier Market
Optical Components
US Optical Sensors Market
Optical Components
Ring Panel Filters Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Mobile Optical Pluggable Market