
 Laser Diode Market | 2026-2036
Laser Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Diode Market Intelligence
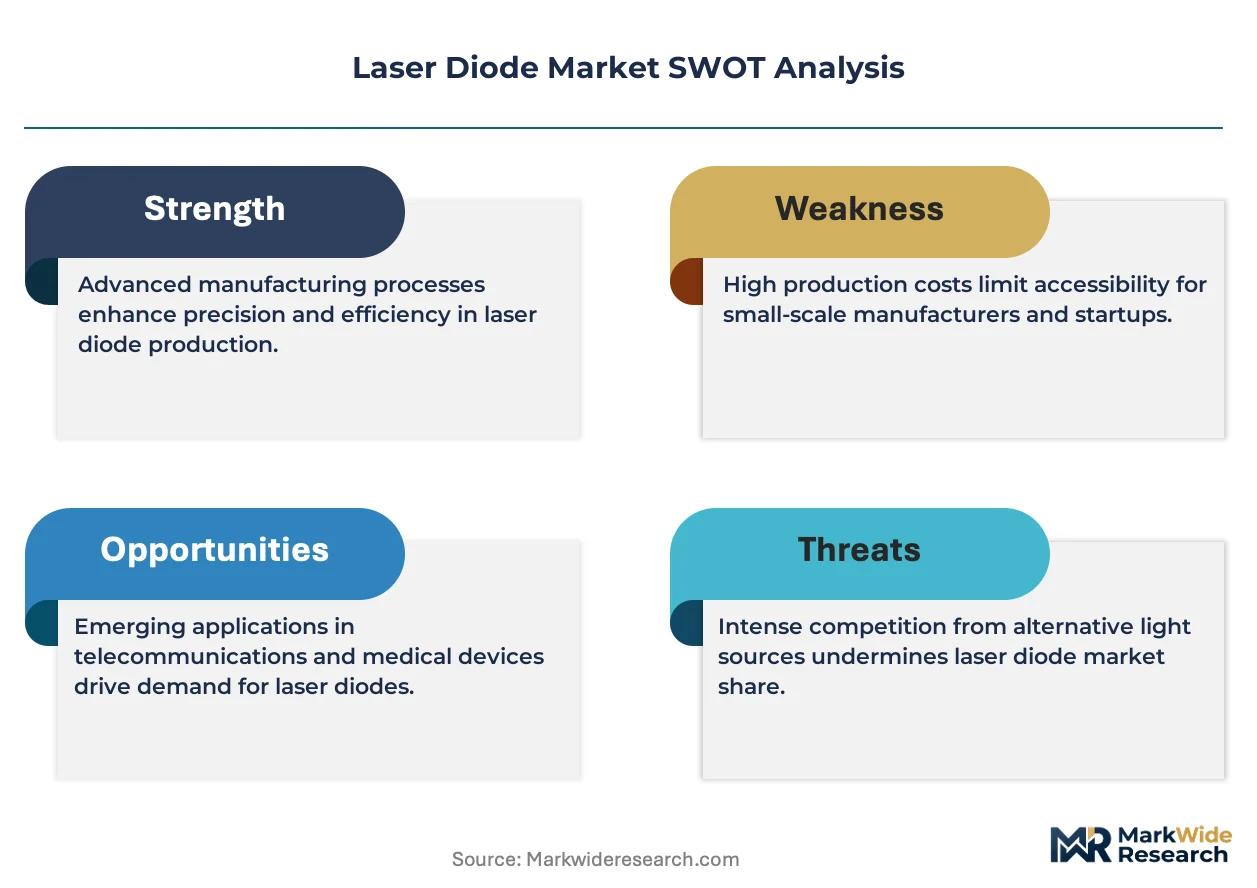
Telecom carrier procurement is consolidating around fewer qualified vendors with vertical integration capabilities. Coherent Corp. leverages captive crystal growth to secure gallium arsenide supply chains against raw material volatility. Jenoptik AG anchors European defense and industrial laser diode demand through Jena-based manufacturing. Nichia Corporation dominates blue and ultraviolet emitter segments where Japanese material science expertise creates process barriers.
A laser diode is a semiconductor device that converts electrical current into coherent light through stimulated emission at specific wavelengths determined by the compound semiconductor junction material, typically operating at power outputs from milliwatts to hundreds of watts depending on cavity design. Edge emitting and vertical cavity technologies command differentiated margin pools, with fiber coupled architectures gaining share in materials processing where thermal management constraints favor packaged solutions. Gallium arsenide substrates retain volume leadership in optical communication, while indium gallium nitride emitters expand in sensing technology applications driven by shorter wavelength requirements.
REACH and RoHS frameworks restrict hazardous substances in semiconductor manufacturing across Europe, while FDA device classification rules govern laser diode integration into medical devices in the United States. The EU AI Act and CSRD disclosure requirements are adding compliance layers for laser systems deployed in automated industrial environments. Stakeholders must monitor divergence between European chemical safety standards and emerging national semiconductor subsidy conditions when siting fabrication capacity.
Market Dynamics
Telecom infrastructure procurement is consolidating around vertically integrated suppliers with captive gallium arsenide crystal growth capabilities, compressing vendor lists and reshaping competitive economics across optical communication segments.
Growth Catalysts
- Data center interconnect expansion:Hyperscale cloud operators in Ashburn, Frankfurt, and Singapore are scaling 800G coherent transceiver deployments, pulling demand for high-power 1550nm edge-emitting diodes.
- F-Gas Regulation phase-down:The EU's hydrofluorocarbon restrictions are accelerating dry etching process adoption in semiconductor fabrication, favoring laser diode-based material removal systems over chemical approaches.
- Indium gallium nitride emitter maturation:Shorter wavelength capabilities are unlocking automotive lidar and biomedical sensing applications where silicon photodetectors offer superior responsivity.
Market Restraints
- Gallium arsenide substrate concentration:Six-inch wafer supply concentrates among three Japanese and German suppliers, exposing procurement costs to raw metal volatility and export licensing friction.
- Thermal management physics:Power scaling beyond 10W in edge-emitting architectures requires exotic submount materials or microchannel coolers, inflating bill-of-materials complexity.
- RoHS substance restrictions:Lead-free solder mandates complicate hermetic packaging for high-reliability defense and space applications, extending qualification timelines.
Strategic Opportunities
- India electronics manufacturing incentives:PLI scheme subsidies for semiconductor packaging are attracting diode module assembly investments targeting domestic telecom and defense procurement.
- Photonic integrated circuit convergence:Silicon nitride platforms are absorbing discrete laser functions, creating attach opportunities for III-V gain chips rather than complete packaged sources.
- EU Green Deal industrial retrofit mandates:Energy efficiency directives are displacing gas lasers in precision cutting applications across Italian and Polish manufacturing clusters.
Industry Challenges
- Compound semiconductor process engineering scarcity:MOCVD reactor operation and facet coating expertise concentrates among aging workforces in Jena, Tokyo, and Albuquerque facilities.
- Medical device laser classification timelines:FDA 510(k) pathways for Class IIIb and IV diode systems require 18-24 month validation cycles, compressing product refresh rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Diode Market |
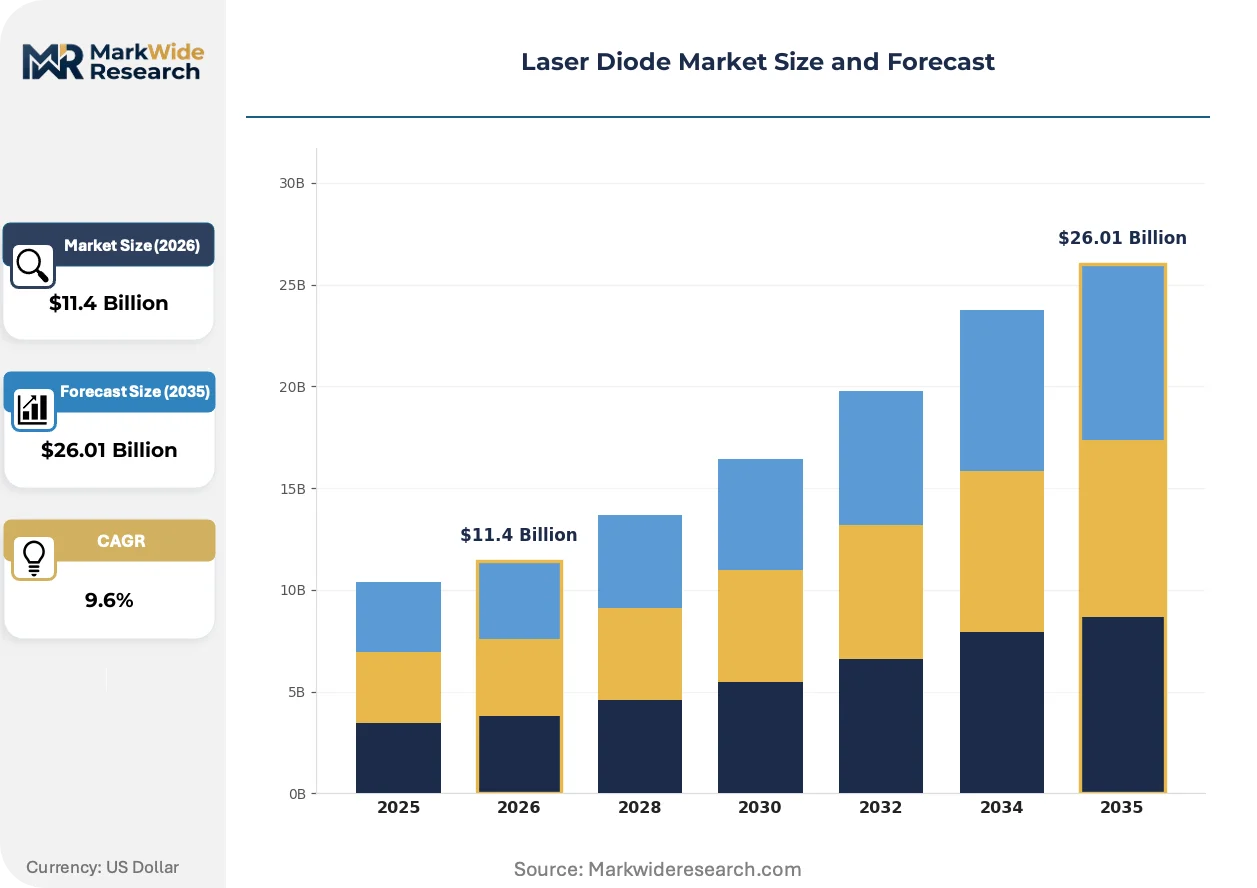
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $26.01 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon, Gallium Arsenide, Indium Gallium Nitride, Gallium Phosphide End User: Telecommunications, Consumer Electronics, Medical Devices, Industrial Automation Application: Optical Communication, Healthcare Imaging, Laser Printing, Sensing Technology Technology: Fiber Coupled, Surface Emitting, Edge Emitting, Vertical Cavity |
| Companies Covered | Jenoptik AG, TRUMPF SE + Co. KG, Coherent Corp., OSRAM Opto Semiconductors GmbH, Hamamatsu Photonics K.K., Lumentum Holdings Inc., Nichia Corporation, Sumitomo Electric Industries, Ltd., IPG Photonics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Diode Market Strategic Shifts & Innovations
Active beam combining architectures and heterogeneous integration platforms are compressing the traditional separation between emitter manufacturing and subsystem assembly, redrawing value capture boundaries across the supply chain.
Vertical cavity surface emitting laser technology is consolidating market position in short-reach optical interconnects. Data center operators are standardizing on multi-mode fiber links below 500 meters, displacing edge-emitting alternatives in spine-leaf architectures. This consolidation is enabling foundry-scale manufacturing economics previously unavailable to discrete diode suppliers.
The EU AI Act's risk classification framework is reshaping industrial laser system compliance requirements. Automated manufacturing cells incorporating high-power diodes now face mandatory conformity assessment procedures, extending deployment timelines. German automotive OEMs are responding by pre-qualifying laser welding stations against anticipated enforcement thresholds.
Carrier procurement departments are compressing vendor qualification cycles from 24 months to 12 months for qualified optical transceiver suppliers. This acceleration favors incumbent relationships with established reliability data, marginalizing new entrants in 400G and 800G module competitions. The phenomenon is most visible in North American hyperscale contracts where single-source awards now predominate.
Laser Diode Market Segmentation
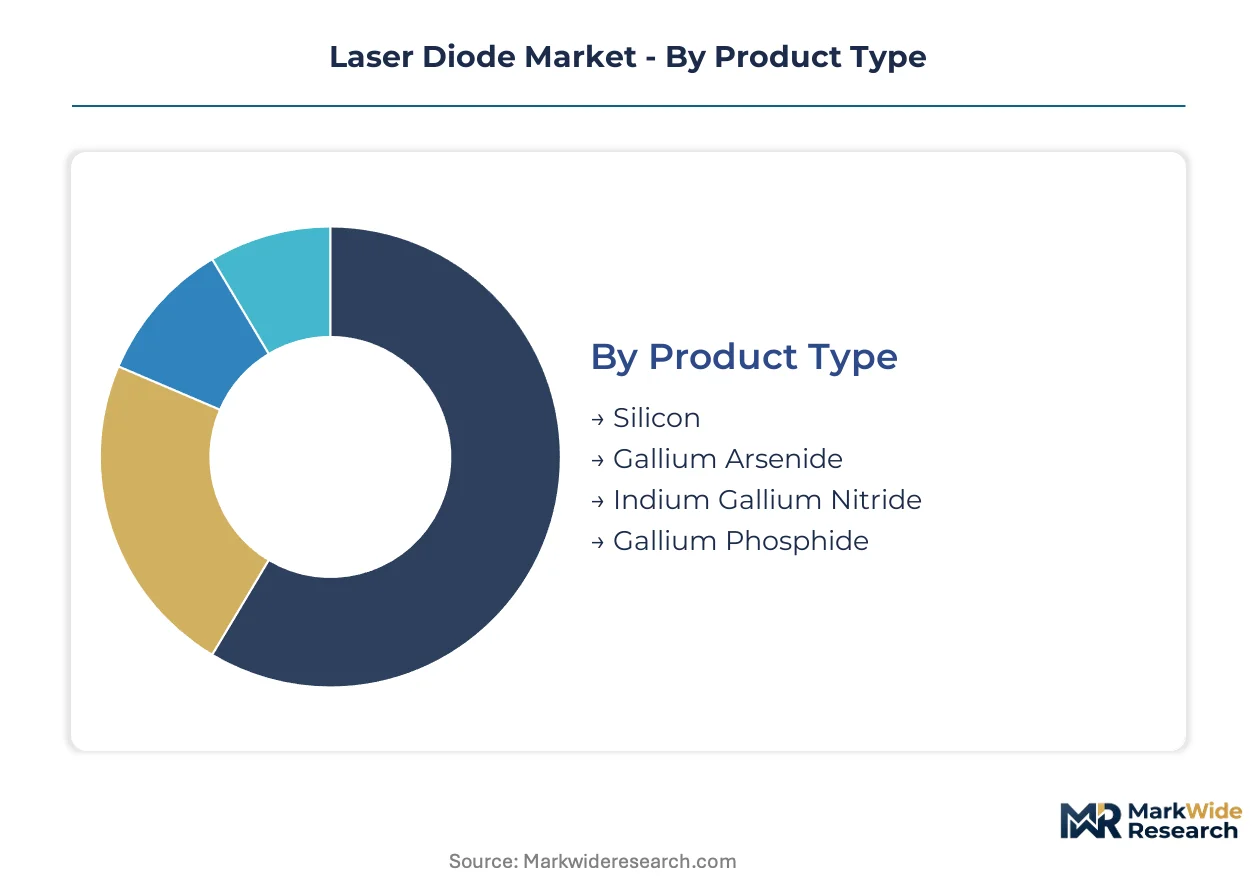
Technology migration cycles and substrate material constraints reshape procurement priorities across laser diode categories. Compound semiconductor junction engineering determines wavelength precision, thermal performance, and qualification pathways for each segment cluster.
Product Type:
Upgrade cycles in telecom infrastructure and sensing modules are pulling procurement toward substrates with superior electron mobility and wavelength tunability.
- Silicon:Silicon-based photonic integration enables cost-efficient waveguide coupling for short-reach data center interconnects. Foundry-scale manufacturing in Taiwan and Singapore is absorbing silicon laser functions into larger CMOS flows, though direct emission efficiency remains inferior to III-V compounds.
- Gallium Arsenide:Dominates 850nm to 1550nm emission bands through direct bandgap properties that enable high-efficiency stimulated emission. Captive crystal growth capabilities at Coherent Corp. and Jenoptik AG insulate supply chains against germanium and gallium metal price volatility.
- Indium Gallium Nitride:Shorter wavelength emitters for automotive lidar and biomedical fluorescence excitation. Japanese substrate expertise creates process barriers that concentrate high-brightness blue and UV production.
- Gallium Phosphide:Visible spectrum emission for laser projection and optical data storage applications. Limited commercial scale restricts deployment to niche industrial and consumer display segments.
Volume placements concentrate in Gallium Arsenide; the faster expansion belongs to Indium Gallium Nitride.
End User:
Customer procurement maturity and qualification timelines separate segments by contract structure and vendor relationship intensity.
- Telecommunications:Carrier procurement departments compress vendor lists around vertically integrated suppliers with captive substrate capabilities. Single-source awards now predominate in North American hyperscale 400G and 800G module competitions.
- Consumer Electronics:High-volume, price-sensitive demand for laser projection and sensing modules. Module assembly is migrating toward India PLI-subsidized facilities serving domestic smartphone and wearable manufacturers.
- Medical Devices:FDA 510(k) pathways for Class IIIb and IV diode systems impose 18-24 month validation cycles. German precision optics clusters supply surgical and diagnostic equipment OEMs with hermetically packaged sources.
- Industrial Automation:EU AI Act conformity assessment procedures extend deployment timelines for automated manufacturing cells incorporating high-power diodes. German automotive OEMs pre-qualify laser welding stations against anticipated enforcement thresholds.
Contract value concentrates in Telecommunications; Medical Devices exhibits the steepest expansion trajectory as surgical robotics and point-of-care diagnostics proliferate.
Application:
Performance requirements and thermal management constraints differentiate margin capture across use cases.
- Optical Communication:Hyperscale operators in Ashburn, Frankfurt, and Singapore scale 800G coherent transceiver deployments, pulling demand for high-power 1550nm edge-emitting diodes with hermetic packaging.
- Healthcare Imaging:Confocal microscopy and optical coherence tomography systems demand wavelength stability within 0.1nm. Swiss and German precision optics houses qualify sources against ISO 13485 medical device standards.
- Laser Printing:Mature demand for xerographic and additive manufacturing exposure systems. Replacement cycles extend as page-volume growth stagnates in developed economies.
- Sensing Technology:Indium gallium nitride emitters unlock automotive lidar and biometric authentication where silicon photodetectors offer superior responsivity at shorter wavelengths.
Revenue concentration sits with Optical Communication; Sensing Technology is climbing the fastest on autonomous vehicle and industrial metrology demand.
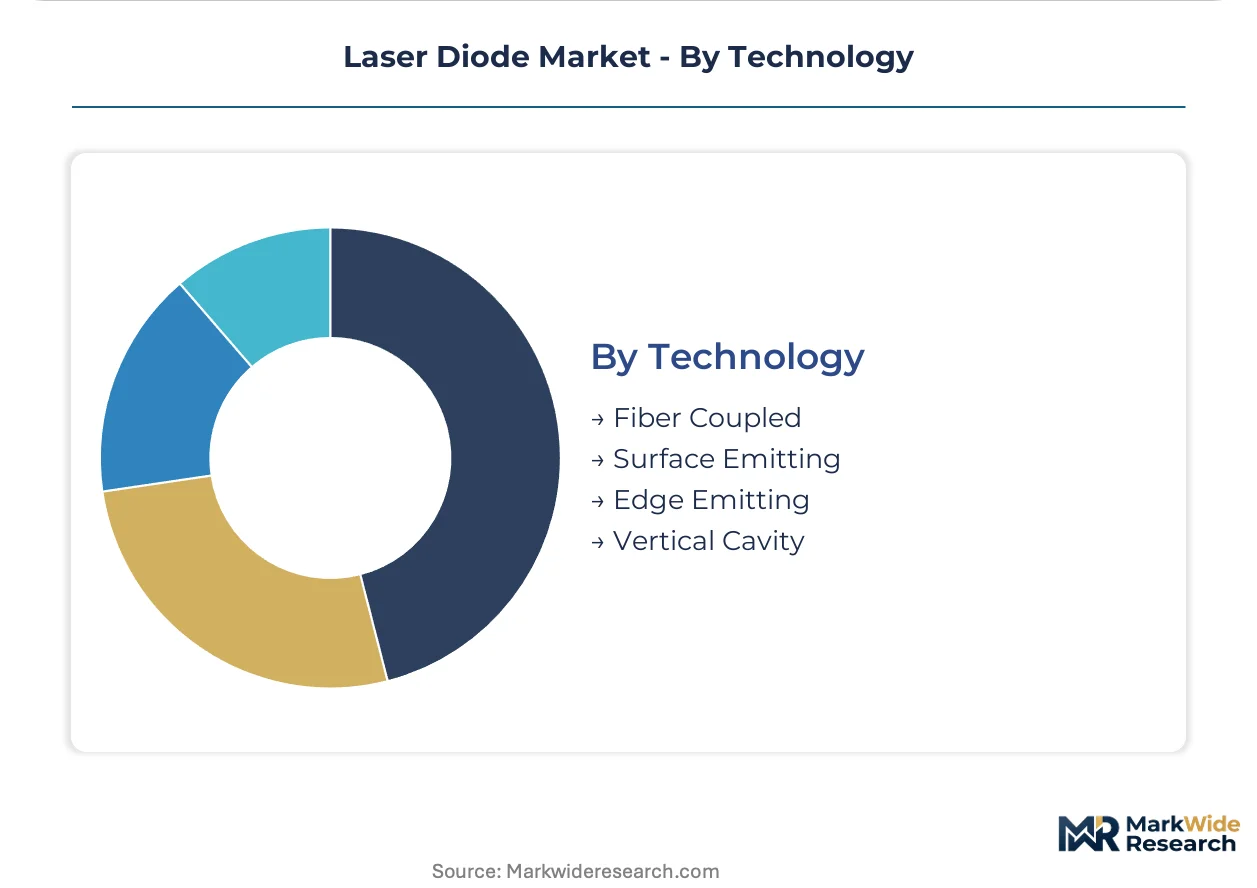
Technology:
Packaging architecture and beam geometry determine integration complexity and subsystem value capture.
- Fiber Coupled:Packaged solutions with integrated thermal management dominate materials processing where power scaling beyond 10W requires exotic submount materials or microchannel coolers.
- Surface Emitting:Two-dimensional array configurations enable parallel optical interconnects. VCSEL derivatives consolidate in short-reach data center spine-leaf architectures below 500 meters.
- Edge Emitting:Established technology for high-brightness, single-mode emission in telecom and industrial cutting applications. Facet coating expertise concentrates among aging workforces in Jena and Tokyo facilities.
- Vertical Cavity:Foundry-scale manufacturing economics emerge as data center operators standardize on multi-mode fiber links, displacing edge-emitting alternatives in high-volume applications.
Deployment volume favors Vertical Cavity; Fiber Coupled commands premium positioning in power-scaled industrial systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for laser diodes concentrates in precision optics clusters where substrate fabrication and module assembly co-locate. Carrier procurement in telecommunications and automotive lidar programs in sensing applications pull volume toward established manufacturing corridors.
United States
Hyperscale data center operators in Ashburn and the Pacific Northwest scale 800G coherent transceiver deployments. FDA device classification rules govern laser diode integration into surgical systems and diagnostic equipment. Albuquerque facilities concentrate compound semiconductor process engineering expertise for defense and space applications.
Germany
Automotive OEMs pre-qualify laser welding stations against EU AI Act conformity thresholds for automated manufacturing cells. The F-Gas Regulation accelerates dry etching process adoption favoring laser diode-based material removal. Jena and Berlin precision optics clusters anchor European defense and industrial laser diode demand through captive manufacturing.
Japan
Substrate expertise in gallium arsenide and indium gallium nitride creates process barriers for high-brightness blue and UV emitters. METI industrial policy supports domestic semiconductor fabrication capacity expansion. Tokyo and Nagoya facilities concentrate aging workforces with MOCVD reactor operation and facet coating expertise.
China
MIIT standards and dual carbon goals shape industrial laser adoption in precision cutting and materials processing applications. Yangtze River Delta manufacturing clusters absorb silicon photonic integration functions into larger CMOS flows. Domestic module assembly targets telecom infrastructure and consumer electronics sensing modules.
India
PLI scheme subsidies for semiconductor packaging attract diode module assembly investments serving domestic telecom and defense procurement. TRAI spectrum policy shapes optical communication infrastructure deployment timelines. Gujarat and Karnataka electronics manufacturing corridors concentrate assembly operations for smartphone and wearable laser sensing modules.
Laser Diode Market Key Industry Players
German and Japanese producers anchor one tier; American specialists hold process integration advantages in optical communication. The vendor base stratifies around substrate capabilities, with captive crystal growth distinguishing qualified suppliers from module assemblers. Three archetypes dominate: vertically integrated compound semiconductor fabricators, photonic subsystem integrators, and foundry-scale VCSEL manufacturers. Competitive moves center on backward integration into gallium arsenide supply chains and strategic partnerships for silicon photonic integration.
Among German fabricators, Jenoptik AG and TRUMPF SE + Co. KG occupy positions in precision optics and industrial laser systems respectively. Coherent Corp. exemplifies the vertically integrated archetype through captive supply of critical substrate materials. These three entities represent distinct competitive vectors: defense-industrial anchoring, high-power materials processing, and telecom-optical communication integration.
| Leading Market Players |
|---|
| Jenoptik AG |
| TRUMPF SE + Co. KG |
| Coherent Corp. |
| OSRAM Opto Semiconductors GmbH |
| Hamamatsu Photonics K.K. |
| Lumentum Holdings Inc. |
| Nichia Corporation |
| Sumitomo Electric Industries, Ltd. |
| IPG Photonics Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between hermetically sealed defense-qualified emitters and commodity VCSELs manifests in both pricing power and supply chain sourcing strategies. REACH-compliant packaging and FDA 510(k) validation cycles command 3-4x material premiums over consumer-grade alternatives, while captive gallium arsenide crystal growth insulates qualified vendors from spot metal volatility.
Pricing Analysis
Volume-vs-margin splits sharply between foundry-scale VCSEL production and fiber-coupled industrial systems. Three-tier pricing structure across defense-qualified, telecom-grade, and consumer-grade levels reflects certification depth and thermal management complexity. Pricing pressure stems from carrier procurement consolidation around single-source awards in 800G transceiver competitions. Hyperscale cloud operators exhibit lowest price sensitivity; smartphone module assemblers in India face acute cost compression.
Supply Chain Analysis
Reverse-logistics flows for refurbished MOCVD reactors and reclaimed gallium substrates concentrate in German and Japanese facilities. Six-inch wafer fabrication concentrates in Japan, Germany, and the United States. Raw material dependencies draw from germanium metal markets, high-purity arsine gas, and indium tin oxide coatings. Single-source vulnerability runs through three dominant substrate suppliers. Distribution runs through vertically integrated subsystem integrators and specialized photonics distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation and EU AI Act conformity requirements erect compliance moats that favor incumbents with established certification infrastructure and Jena-based process engineering depth.
For Market Incumbents: Deepen captive gallium arsenide crystal growth capabilities to secure substrate supply against export licensing friction. Expand hermetic packaging qualification capacity for defense and space applications where RoHS lead-free mandates extend validation timelines. Threat substitution from silicon photonic integration platforms demands accelerated III-V gain chip attach partnerships. For New Entrants and Emerging Players: Direct-to-manufacturer digital procurement channels offer white-space entry around replacement diode modules for legacy industrial laser systems. Target India's PLI-subsidized packaging corridors for telecom and defense module assembly. Photonic integrated circuit attach opportunities for discrete gain chips present the most penetrable vector against entrenched packaged-source competition. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by telecom subsystem integrators seeking backward integration into compound semiconductor fabrication. Long-term viability favors vertically integrated fabricators with Jena or Tokyo-based MOCVD expertise and established carrier qualification relationships. Monitor EU AI Act enforcement thresholds and F-Gas Regulation phase-down timelines as demand inflection signals for dry etching laser systems.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gallium Arsenide Crystal Growth | Insulates Coherent Corp. and Jenoptik AG from raw metal price volatility and export licensing friction. |
| Hermetic Packaging Qualification Expansion | Extends defense and space market access despite RoHS lead-free solder mandate complications. |
| Silicon Photonic Integration Partnerships | Positions III-V gain chip suppliers for attach opportunities as Taiwan foundries absorb laser functions. |
| India PLI Scheme Module Assembly Investment | Captures domestic telecom and defense procurement flows through Gujarat and Karnataka corridors. |
| EU AI Act Pre-Qualification Programs | Enables German automotive OEMs to deploy automated laser welding cells ahead of enforcement thresholds. |
Research Approach
Independent corroboration across MOCVD reactor operators, carrier procurement directors, and precision optics manufacturing heads underwrites the qualitative findings. Primary fieldwork encompassed compound semiconductor fabrication executives, telecom transceiver procurement leads, and FDA regulatory affairs specialists. Secondary validation drew from SEC 10-K filings, ECHA REACH registration databases, EU Official Journal regulatory texts, and hyperscaler capex disclosures. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Rate-of-change decomposition across technology migration cycles, substrate material constraints, and regulatory compliance timelines structured the analytical framework. Segmentation dimensions spanned compound semiconductor junction material, packaging architecture, end-use industry, and regional manufacturing cluster. CAGRs derived from fitted diffusion curves against historical qualification cycle data and announced capacity expansion timelines. Forecast inputs incorporated F-Gas Regulation phase-down schedules and MIIT dual carbon policy implementation.
The model holds under steady regulatory enforcement and stable germanium metal supply conditions; deviation in export licensing regimes or EU AI Act implementation timelines would shift deployment trajectories. Forecasts reflect documented assumptions regarding carrier procurement consolidation and VCSEL foundry-scale economics. Practitioners should monitor EU F-Gas Regulation enforcement intensity and India PLI scheme disbursement rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Light Projector Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
EPON ONU Market
Optoelectronics
Vertical Cavity Surface Emitting Laser (Vcsels) Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Laser Projection Market
Optoelectronics
IT & Telecom Optoelectronics Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Optoelectronics Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Green Laser Diode Market