
 Digital Cinema Lens Market | 2026-2036
Digital Cinema Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Cinema Lens Market Analysis
Leasing and subscription-based equipment financing is reshaping competitive dynamics in the digital cinema lens sector. Cooke Optics Limited leverages its British manufacturing heritage to sustain premium positioning among feature film cinematographers. ARRI GmbH anchors German engineering credibility through integrated camera-lens ecosystem control. Canon Inc. competes across multiple price tiers with in-house optical glass production and broadcast-to-cinema technology transfer.
A digital cinema lens is a precision-engineered optical system designed for Super 35 and full-frame image sensors, typically achieving T-stop ratings from T1.5 to T22 with minimal breathing and consistent color rendition across focal lengths. These instruments translate director and cinematographer creative vision into captured moving images with standardized flange depths and gear ring configurations for follow-focus systems. Zoom lenses command the largest revenue share in the product type dimension due to production efficiency demands from streaming episodic content. Feature films remain the dominant application category, though television production represents the fastest-growing segment as platform-funded series multiply production volume. Rental houses concentrate capital expenditure in modular lens systems that serve diverse camera body mounts without full fleet duplication.
The EU Green Deal and REACH chemical regulations constrain coating material formulations and manufacturing waste protocols for European lens producers. FDA oversight of medical imaging crossover optics and FCC equipment authorization requirements for wireless lens control systems create dual compliance pathways for manufacturers serving adjacent markets. Stakeholders must monitor sensor format fragmentation between full-frame and emerging large-format standards as this divergence determines future R&D allocation and inventory risk across the value chain.
Market Dynamics
Streaming platform procurement cycles are compressing rental house inventory turnover, forcing manufacturers to prioritize full-frame sensor compatibility and modular mount systems over legacy Super 35-only designs.
Growth Catalysts
- EU Green Deal energy efficiency mandates:European manufacturers are redesigning coating processes and reducing manufacturing waste to meet REACH chemical regulations and carbon reduction targets.
- Episodic television production volume:South Korean streaming content creators are driving demand for premium zoom lenses with consistent color rendition across extended shooting schedules.
- Full-frame sensor proliferation:Camera operators require optical systems covering larger image circles without breathing or vignetting artifacts.
Market Restraints
- Optical glass supply concentration:Japanese and German specialty glass producers control critical low-dispersion and high-index material supply chains.
- REACH coating formulation constraints:ECHA restrictions on fluorinated compounds limit anti-reflective coating durability and performance characteristics.
- Manual cinema lens substitution threat:High-end photographic autofocus lenses with de-clicked aperture rings compete for entry-level production budgets.
Strategic Opportunities
- Wireless lens control integration:FCC equipment authorization pathways enable seamless focus-iris-zoom synchronization with camera body metadata systems.
- Medical imaging crossover optics:FDA oversight of surgical camera systems creates dual-market certification efficiencies for precision optical manufacturers.
- Subscription-based equipment financing:Rental houses in Germany and the United States are adopting leasing structures that accelerate fleet refresh cycles.
Industry Challenges
- Large-format standardization delays:Sensor format fragmentation between full-frame and emerging larger image circles forces inventory risk across incompatible lens mounts.
- Precision assembly skill scarcity:Master opticians capable of hand-collimating cinema lenses to sub-micron tolerances are retiring faster than training programs replace them.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Cinema Lens Market |
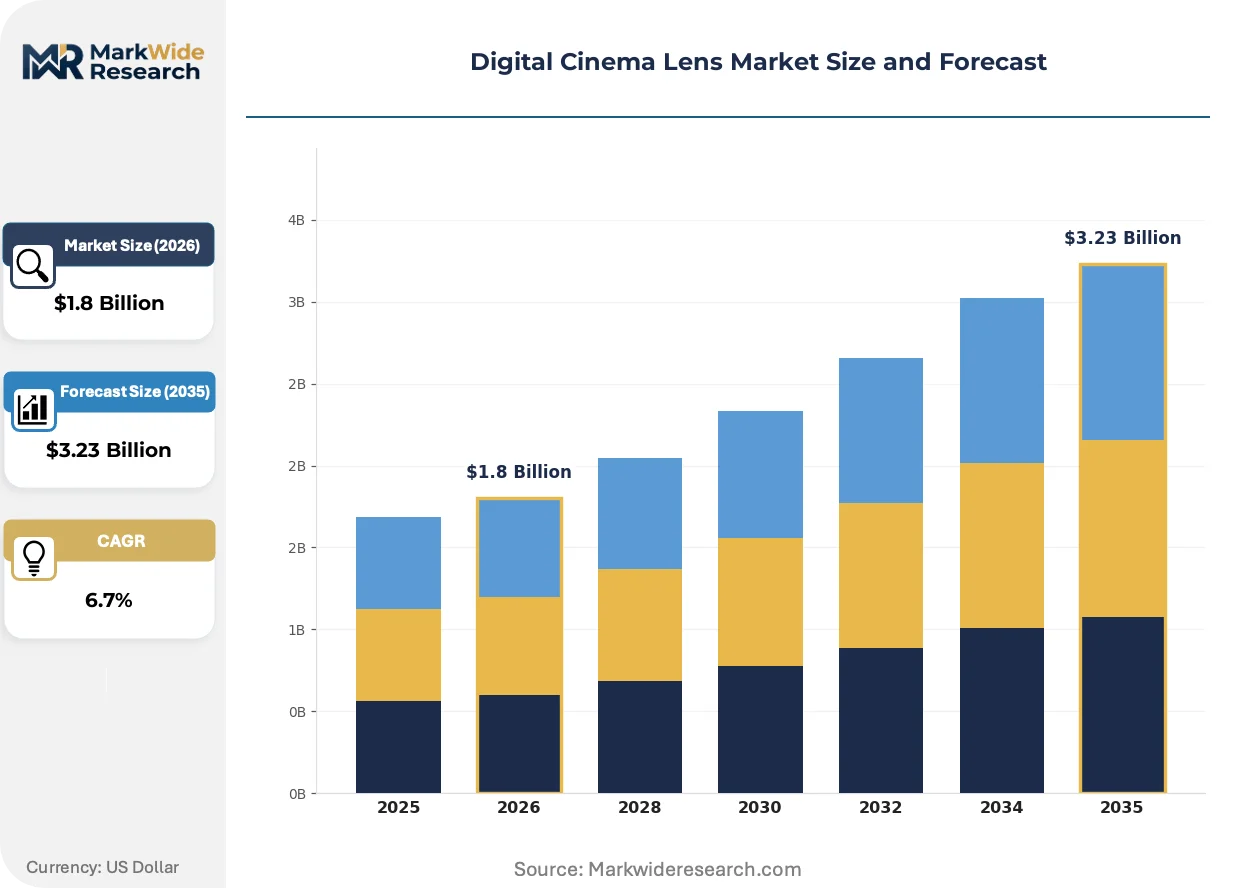
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wide-Angle, Telephoto, Standard, Zoom End User: Film Studios, Independent Filmmakers, Rental Houses, Education Institutions Technology: Digital, Analog, Hybrid, Modular Application: Feature Films, Documentaries, Television Production, Commercials |
| Companies Covered | ZEISS AG, ARRI GmbH, Canon Inc., Cooke Optics Limited, Fujifilm Corporation, Angenieux, Panavision Inc., Leica Camera AG, Samyang Optics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Cinema Lens Market Emerging Trajectories
Optical engineering priorities are pivoting toward sensor-format flexibility and wireless ecosystem integration, displacing fixed-mount legacy designs that dominated theatrical production for decades.
Precision mechanical focus systems are migrating from fixed-gear cinema housings toward servo-integrated units with metadata output. Streaming episodic crews in South Korea and the United States are adopting these systems for rapid focal transitions during high-volume shooting schedules. This migration from purely mechanical to hybrid electro-mechanical control is compressing rental house training requirements while expanding lens utility across documentary and commercial applications.
REACH chemical regulations and EU Green Deal carbon accounting are forcing coating suppliers to reformulate anti-reflective stacks without perfluorinated compounds. German and British manufacturers must validate new deposition processes against legacy durability benchmarks. European lens producers are responding by vertically integrating coating operations to protect proprietary formulations from supply disruption.
Production equipment procurement is consolidating under platform-funded studio mandates. Netflix, Disney+, and Amazon Studios are specifying approved lens lists that rental houses must maintain for original content eligibility. This specification-driven procurement is most visible in Los Angeles and London, where rental inventory decisions now precede cinematographer creative input.
Digital Cinema Lens Market Segmentation
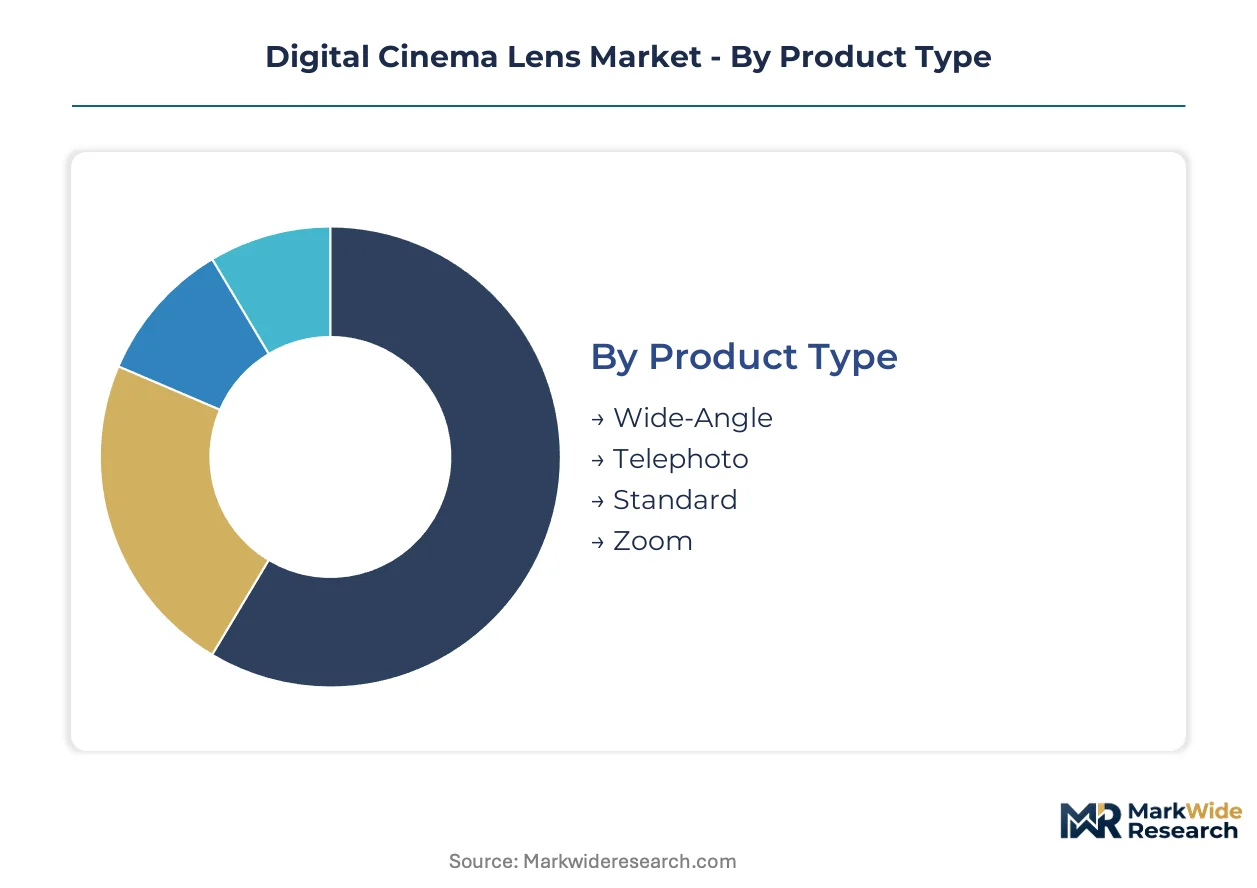
Digital cinema lens procurement varies sharply across production scales and technical requirements. Streaming platforms, rental houses, and independent creators each demand distinct optical specifications and financing structures.
Product Type:
Wide-angle through telephoto focal ranges serve distinct shot compositions and sensor coverage needs.
- Zoom:Variable focal length systems with parfocal stability maintain sharp focus across magnification changes. South Korean episodic television producers favor these for schedule efficiency on platform-funded series.
- Standard:Fixed focal length optics near 50mm equivalent deliver natural perspective with minimal distortion. Feature film cinematographers specify these for dialogue sequences requiring consistent character rendering.
- Wide-Angle:Short focal lengths below 35mm equivalent capture expansive fields of view.
- Telephoto:Long focal lengths compress spatial relationships and isolate subjects.
Established volume favors Zoom; emerging adoption favors Standard.
End User:
Capital deployment patterns separate institutional procurement from individual acquisition.
- Rental Houses:Fleet operators prioritize modular mount compatibility and full-frame coverage to serve diverse camera bodies without duplication. German and United States leasing structures accelerate refresh cycles.
- Film Studios:Platform-owned production entities maintain approved lens lists for original content eligibility.
- Independent Filmmakers:Owner-operators balance purchase price against residual rental income potential.
- Education Institutions:Training programs require durable mechanical designs withstand student handling.
Revenue concentration sits with Rental Houses; steepest expansion trajectory belongs to Film Studios.
Technology:
Control interface architecture determines ecosystem integration depth.
- Digital:Servo-integrated focus-iris-zoom systems output lens metadata to camera bodies. Streaming crews in South Korea and the United States adopt these for rapid shot transitions.
- Hybrid:Mechanical gearing with electronic position encoding bridges traditional and modern workflows.
- Analog:Purely mechanical focus and aperture control persists in heritage-oriented productions.
- Modular:Interchangeable mount and control modules adapt single optical cores to multiple camera systems.
Deployment scale favors Digital; flexibility premiums accrue to Modular.
Application:
Content format dictates optical performance priorities and crew workflow patterns.
- Television Production:Episodic schedules demand consistent color rendition across extended shooting calendars. South Korean streaming creators drive premium zoom specifications.
- Feature Films:Theatrical releases prioritize T-stop speed and minimal breathing for creative control.
- Commercials:High-day-rate productions accept premium rental fees for specialized optics.
- Documentaries:Run-and-gun crews favor lightweight zooms with broad focal range coverage.
Budget allocation dominance favors Feature Films; platform investment flows fastest into Television Production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and REACH chemical regulations are forcing European coating suppliers to reformulate anti-reflective stacks without perfluorinated compounds. United States rental houses are adopting subscription-based financing structures that compress equipment refresh cycles. South Korean streaming platforms are driving premium zoom lens specifications for episodic production.
United States
Streaming platform procurement mandates from Netflix, Disney+, and Amazon Studios are consolidating rental house inventory decisions under approved lens lists. FCC equipment authorization requirements govern wireless lens control systems for focus-iris-zoom synchronization. Los Angeles rental operators maintain modular lens fleets to serve diverse camera body mounts without duplication.
Germany
ARRI GmbH anchors integrated camera-lens ecosystem control through German engineering credibility. ECHA restrictions on fluorinated compounds limit anti-reflective coating durability for manufacturers serving adjacent medical imaging markets. Munich and Berlin rental houses concentrate capital expenditure in full-frame compatible systems.
South Korea
Platform-funded episodic television creators are driving demand for premium zoom lenses with consistent color rendition across extended shooting schedules. MFDS oversight of medical imaging crossover optics creates dual-market certification pathways for precision optical manufacturers. Seoul production clusters adopt servo-integrated digital control systems for rapid focal transitions.
United Kingdom
Cooke Optics Limited leverages British manufacturing heritage to sustain premium positioning among feature film cinematographers. REACH compliance costs are accelerating vertical integration of coating operations to protect proprietary formulations. London rental inventory decisions increasingly precede cinematographer creative input under studio mandates.
Japan
Specialty optical glass producers control critical low-dispersion and high-index material supply chains for precision cinema optics. METI industrial standards influence manufacturing protocols for lens systems serving broadcast-to-cinema technology transfer. Tokyo-based manufacturers compete across multiple price tiers with in-house optical glass production capabilities.
Digital Cinema Lens Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered price-performance segments. The vendor base fragments between heritage optics houses with century-long manufacturing pedigrees and diversified electronics conglomerates leveraging broadcast technology transfer. Three strategic archetypes dominate: integrated camera-lens ecosystem providers, standalone precision optics specialists, and diversified imaging conglomerates. Competitive moves concentrate on backward integration into coating operations and modular mount system development to reduce inventory risk.
Among heritage British and German precision optics houses, Cooke Optics Limited and ARRI GmbH exemplify the standalone specialist archetype through manufacturing pedigree and ecosystem integration respectively. Canon Inc. occupies a diversified conglomerate position spanning multiple price tiers. ZEISS AG and Leica Camera AG represent German optical engineering credibility in premium cinema applications. Fujifilm Corporation and Angenieux exemplify broadcast-to-cinema technology transfer strategies.
| Leading Market Players |
|---|
| ZEISS AG |
| ARRI GmbH |
| Canon Inc. |
| Cooke Optics Limited |
| Fujifilm Corporation |
| Angenieux |
| Panavision Inc. |
| Leica Camera AG |
| Samyang Optics |
| Others |
Supply Flow & Price Mechanics
Munich and Berlin manufacturing clusters anchor European coating capacity, with their REACH compliance investments translating into premium pricing power over Asian competitors lacking equivalent environmental certification. German lens producers leverage this regulatory moat to command spreads of 15-25 percent above comparable optics from non-EU sources, while rental houses absorb these premiums through subscription-based fleet financing structures that amortize upfront costs.
Pricing Analysis
Certification level (REACH/FDA-grade) creates the primary spread between European heritage manufacturers and Asian volume producers. Three-tier pricing structure across premium, standard, and economy levels segments buyers by production scale and content destination, with streaming platform-approved lists commanding brand premiums independent of optical performance metrics. Pricing pressure stems from high-end photographic lens substitution threatening entry-tier cinema margins. Independent filmmakers exhibit highest price sensitivity, while platform-funded studios prioritize approved-list compliance over unit cost.
Supply Chain Analysis
Export-control restrictions on precision optical manufacturing equipment limit technology transfer to emerging production hubs, constraining supply expansion outside established centers. Japan and Germany control critical low-dispersion glass and high-index material flows, with coating chemical formulations drawing from concentrated European specialty chemical producers. Single-source vulnerability concentrates in master optician labor pools capable of sub-micron collimation. Distribution runs through rental house networks and direct studio procurement rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital cinema lens sector faces high-growth disruption as full-frame sensor proliferation and wireless ecosystem integration reshape hardware procurement cycles. EU Green Deal carbon accounting and REACH chemical phase-outs accelerate consolidation among coating-capable manufacturers.
For Market Incumbents: Pre-empt photographic lens crossover threats by accelerating servo-integrated digital control roadmaps and securing platform-approved list status with Netflix, Disney+, and Amazon Studios. Backward integration into captive coating operations protects proprietary formulations from ECHA supply disruptions. Modular mount system development reduces rental house inventory duplication risk and deepens ecosystem lock-in.
For New Entrants and Emerging Players: Southeast Asian rental house networks remain underpenetrated by full-frame compatible modular systems, offering white-space expansion outside saturated Los Angeles and London markets. Documentary and commercial production segments tolerate shorter heritage pedigrees and accept hybrid electro-mechanical control architectures. Go-to-market positioning should emphasize lightweight zoom configurations for run-and-gun crews over premium prime lens competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified imaging conglomerates with underutilized cinema lens divisions lacking platform ecosystem integration. Long-term viability hinges on wireless control protocol adoption and coating operation ownership. The signal to watch is sensor format standardization between full-frame and large-format circles, with convergence accelerating inventory value recovery and divergence fragmenting addressable markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Coating Operation Acquisition | Captive supply of REACH-compliant anti-reflective stacks protects German manufacturers from ECHA reformulation mandates. |
| Wireless Control Protocol Development | FCC-authorized focus-iris-zoom synchronization enables ARRI and Cooke ecosystem integration with camera body metadata systems. |
| Modular Mount System Expansion | Interchangeable PL/EF/LPL modules reduce rental house fleet duplication across incompatible camera bodies. |
| Platform Approved List Certification | Netflix and Disney+ procurement mandates convert lens selection from cinematographer preference to studio compliance requirement. |
| Medical Imaging Crossover Certification | FDA and MFDS surgical camera approvals create dual-market revenue streams for precision optics manufacturers. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with rental house fleet managers, cinematographers, and platform procurement officers, combined with secondary validation against SEC filings, customs trade records, and ECHA regulatory submissions. Bottom-up triangulation across manufacturer shipment data and top-down reconciliation with streaming platform content spend estimates anchored volume and value outputs.
Forecast inputs span product type, technology architecture, application format, and end-user procurement model across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macro production volume indicators. Full-frame sensor adoption curves and REACH chemical phase-out timelines constitute cinema-specific forecast variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by photographic lens manufacturers into de-clicked cinema variants would shift outcomes. Material shifts in sensor format standardization or ECHA fluorinated compound restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
North America Tunable Laser Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Optical Modulators Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Microchannel Plates Market
Optical Components
Optical Cross Connect Market
Optical Components
Europe Tunable Laser Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Silicon Photonics Market
Optical Components
Optical Waveguide Market
Optical Components
North America Optical Film Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Silicon Photonics Wafer Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Electro Optical System Market