
 Europe Tunable Laser Market | 2026-2036
Europe Tunable Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tunable Laser Market Foresight
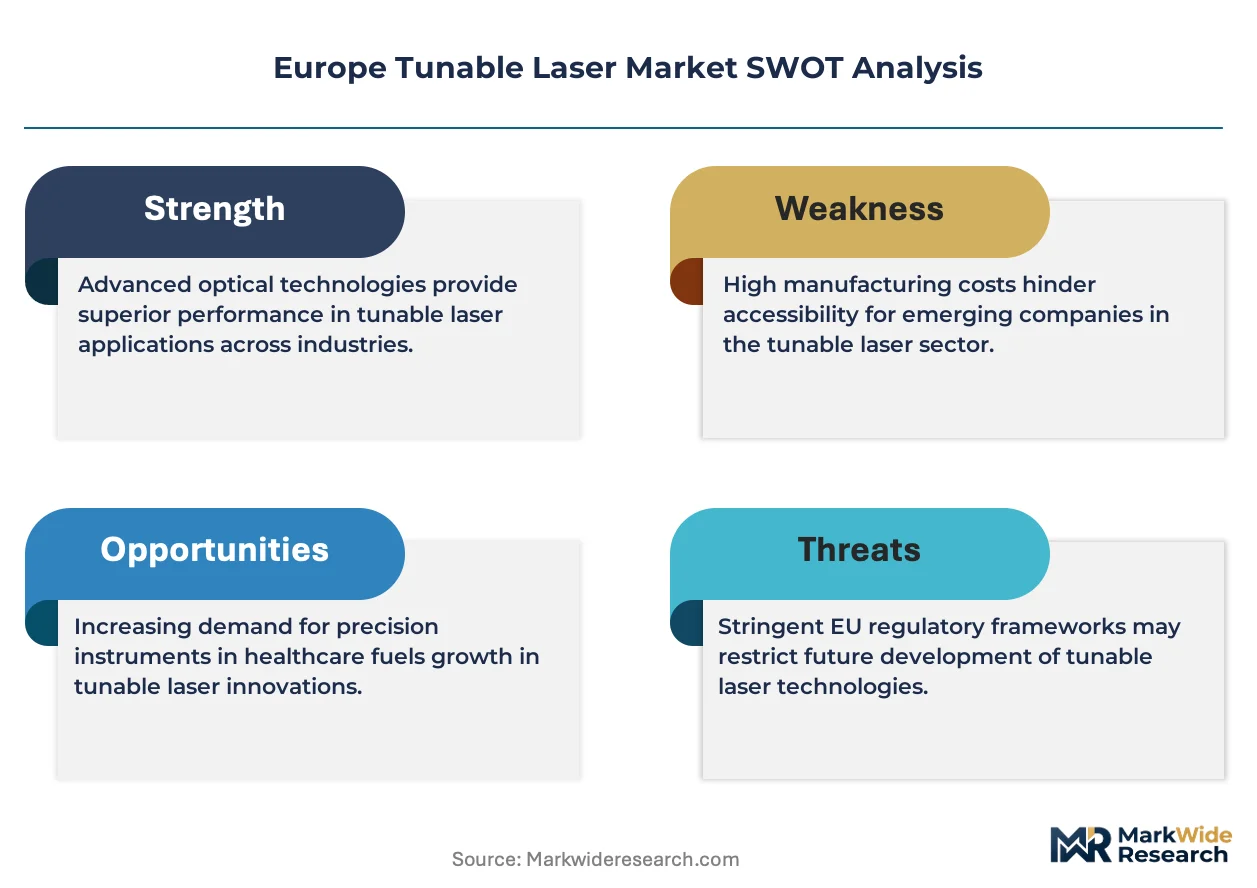
German photonics foundries is broadening output of external-cavity diode architectures for sensing and spectroscopy. TOPTICA Photonics AG leverages vertical integration across crystal growth and coating operations to control delivery timelines. HÜBNER Photonics anchors its position through specialized packaging for defense-qualified tunable sources. Sacher Lasertechnik GmbH competes in narrow-linewidth external-cavity designs for atomic physics laboratories.
A tunable laser emits coherent light across a selectable wavelength range, typically achieved through grating-tuned external cavities, temperature-current control of diode gain media, or optical parametric oscillation, with linewidth specifications often below 1 MHz for precision spectroscopy. Fiber laser architectures dominate volume in telecommunications test equipment due to compatibility with erbium-doped fiber amplifier chains, while solid-state platforms command premium positioning in medical device OEM supply chains for their pulse-energy stability. Diode laser segments lead unit shipments across industrial sensing deployments where cost-per-channel economics determine procurement decisions.
CE marking requirements under the EU Medical Device Regulation constrain design verification cycles for tunable sources destined for ophthalmic and dermatological equipment. REACH compliance on rare-earth dopants and RoHS substance restrictions affect supply qualification for fiber and solid-state gain media manufactured outside the European Economic Area. The EU AI Act's emerging transparency obligations for automated inspection systems will shape R&D allocation decisions across component suppliers and system integrators. Stakeholders must track how ECHA substance-of-very-high-concern listings impact crystal and coating material sourcing before committing to multi-year platform designs.
Market Dynamics
The EU Green Deal's binding decarbonization mandates are forcing industrial laser buyers to prioritize energy efficiency in equipment procurement, compressing payback-period requirements and favoring architectures with superior wall-plug efficiency over legacy platforms.
Growth Catalysts
- Telecom Infrastructure Expansion:Wavelength-division multiplexing deployment across Germany and France is pulling demand for test-grade tunable sources compatible with erbium-doped fiber amplifier chains.
- REACH Compliance Premium:RoHS substance restrictions on rare-earth dopants are creating preference for suppliers with qualified non-Asian coating and crystal supply chains.
- Photonics Cluster Density:Munich-Jena corridor concentration enables rapid prototype-to-production cycles for external-cavity diode architectures targeting sensing applications.
Market Restraints
- Rare-Earth Supply Concentration:Fiber and solid-state gain media sourcing depends on qualified supply from outside the European Economic Area, exposing buyers to ECHA substance-of-very-high-concern listing volatility.
- CE Marking Friction:EU Medical Device Regulation verification cycles extend time-to-revenue for ophthalmic and dermatological equipment integrators by 8-14 months.
- Diode Cost Floor:Temperature-current control architectures face input cost pressure from III-V epitaxy wafer pricing, limiting margin expansion in industrial sensing segments.
Strategic Opportunities
- AI Act Inspection Systems:Emerging transparency obligations for automated quality control are redirecting R&D allocation toward integrated spectroscopy modules in German automotive supply chains.
- Defense Packaging Specialization:Qualified ruggedized housing demand from European defense procurement is outpacing domestic foundry capacity, creating white space for certified subsystem suppliers.
- Atomic Physics Research:Narrow-linewidth external-cavity designs for quantum sensing and optical clock applications command 3-4x pricing multiples over telecom-grade equivalents.
Industry Challenges
- Multi-Year Platform Risk:Crystal and coating material sourcing commitments collide with evolving ECHA restricted substance lists, forcing design-stage hedging against future compliance gaps.
- Packaging Talent Scarcity:Hermetic sealing and thermal management expertise for defense-qualified sources concentrates in legacy optoelectronics hubs, constraining foundry expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tunable Laser Market |
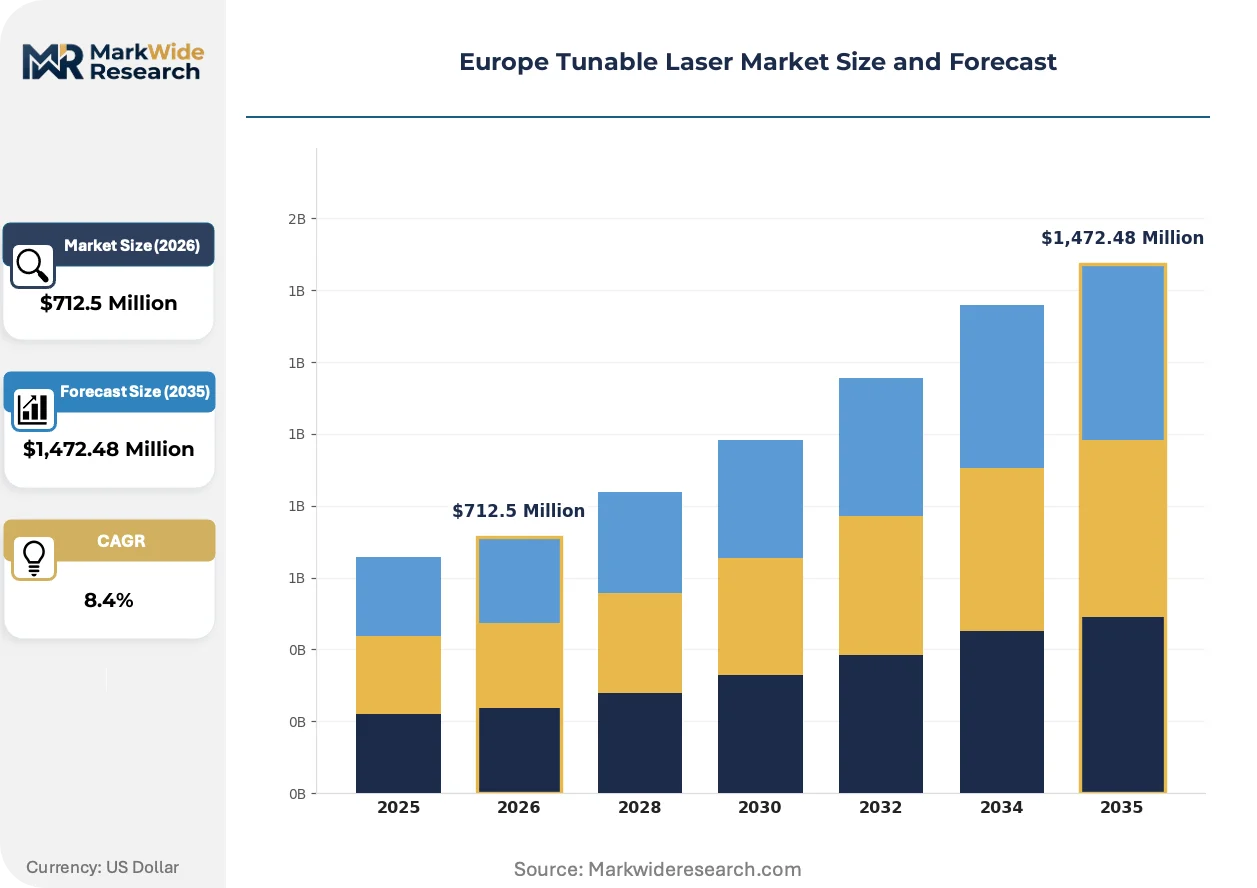
| Market Size in 2026 | $712.5 Million |
| Market Size in 2035 | $1,472.48 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diode Lasers, Fiber Lasers, Solid-State Lasers, Gas Lasers End User: Telecommunications, Industrial Manufacturing, Medical Devices, Research Institutions Application: Spectroscopy, Material Processing, Communication, Sensing Technology: Optical Amplification, Frequency Doubling, Wavelength Tuning, Pulse Generation |
| Companies Covered | TOPTICA Photonics AG, HÜBNER Photonics, Sacher Lasertechnik GmbH, Yenista Optics S.A., LUMIBIRD, EKSPLA, Keysight Technologies, Coherent, Lumentum Operations LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tunable Laser Market Shifts & Advancements
Architectural convergence between fiber and solid-state platforms is compressing the traditional performance-cost tradeoff, while regulatory compliance obligations are becoming product differentiation vectors rather than mere cost centers.
External-cavity diode lasers with integrated grating-tuned feedback are rewriting the economics of precision spectroscopy. Atomic physics laboratories and quantum sensing startups across France and Germany are adopting these architectures at replacement-cycle pace. The technology is rewriting supplier margin structures by collapsing the historical premium commanded by bulk solid-state alternatives.
The EU AI Act's transparency requirements for automated inspection systems are mandating traceable calibration chains for laser-based measurement equipment. Industrial OEMs must now document wavelength stability and linewidth specifications to audit standards. Medical device and automotive segments are responding by pre-qualifying tunable sources with embedded metrology logging.
Service unbundling is separating hardware procurement from calibration and recertification contracts. System integrators in the Netherlands and Switzerland are disaggregating these components to optimize OpEx treatment. Defense and semiconductor metrology verticals are driving this pattern, with buyers preferring multi-vendor service architectures over single-source captive support.
Europe Tunable Laser Market Segmentation
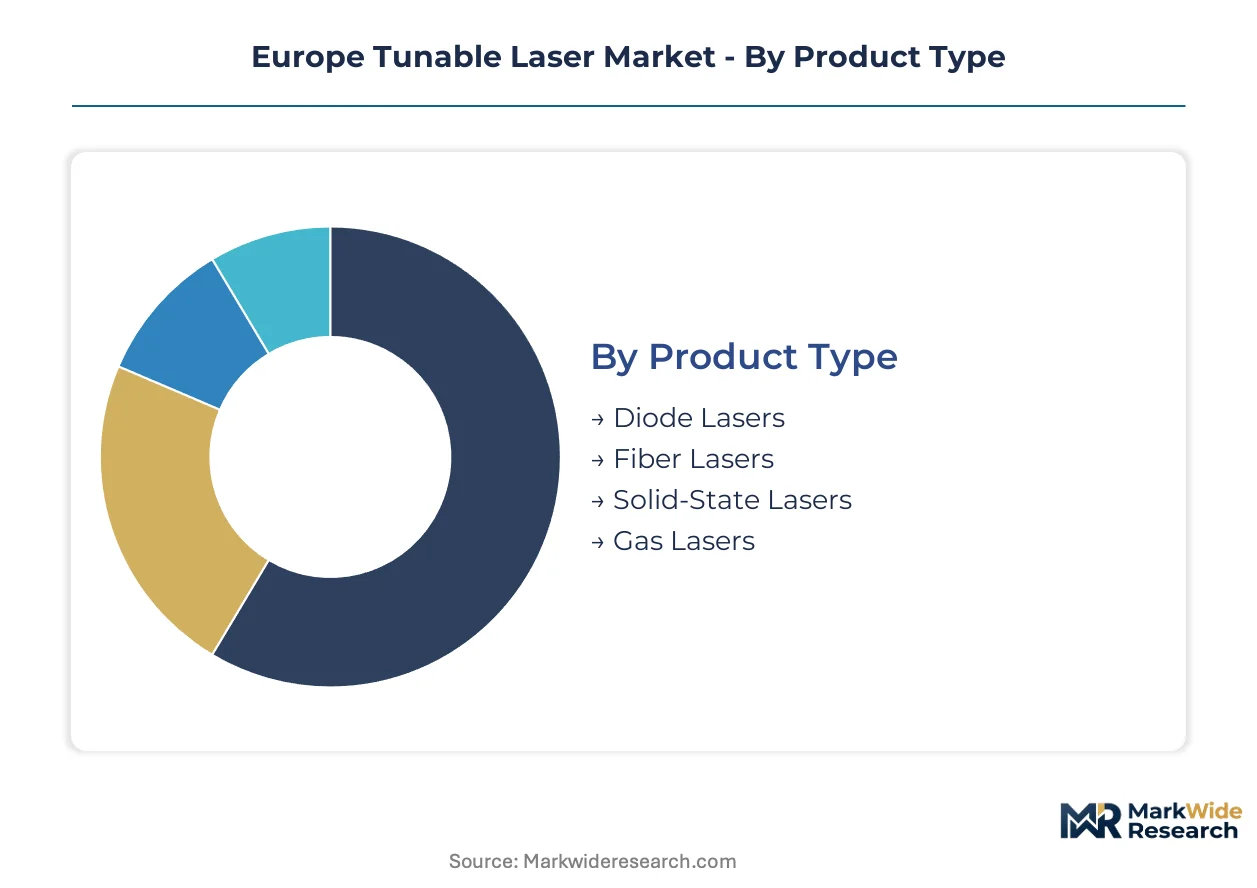
Segmentation in the Europe Tunable Laser Market reveals distinct procurement patterns across product architectures and end-use verticals. Upgrade cycles vary dramatically between telecom test equipment and medical device OEM supply chains.
Product Type:
Replacement timelines diverge sharply across gain media technologies, with fiber architectures refreshing on 5-7 year cycles while diode platforms turn over every 3-4 years in industrial sensing deployments.
- Diode Lasers:Temperature-current controlled III-V epitaxy devices dominate unit shipments in industrial sensing. German automotive suppliers specify these for cost-per-channel economics in production-line metrology. REACH compliance on gallium arsenide substrates constrains supplier qualification.
- Fiber Lasers:Erbium-doped and ytterbium-doped silica fiber architectures command volume in telecommunications test equipment. Compatibility with erbium-doped fiber amplifier chains drives specification in France and Germany. Rare-earth dopant sourcing outside the European Economic Area exposes buyers to ECHA substance-of-very-high-concern volatility.
- Solid-State Lasers:Nd:YVO4 and Ti:sapphire platforms serve medical device OEMs requiring pulse-energy stability for ophthalmic surgery systems.
- Gas Lasers:CO2 and excimer architectures retain niche positioning in high-precision material processing applications.
Fiber lasers sit at the top of the volume ranking, with diode lasers climbing the fastest on industrial automation demand.
End User:
Margin structures compress toward commodity levels in telecommunications while medical and research verticals sustain premium positioning through qualification barriers.
- Telecommunications:Infrastructure operators in Germany and France deploy wavelength-division multiplexing systems requiring test-grade tunable sources. Erbium-doped fiber amplifier chain compatibility determines procurement specifications. Volume concentration enables supplier consolidation.
- Industrial Manufacturing:German automotive supply chains integrate laser-based measurement equipment under EU AI Act transparency obligations. Automated quality control systems demand traceable calibration chains with embedded metrology logging.
- Medical Devices:CE marking under EU Medical Device Regulation extends verification cycles by 8-14 months for ophthalmic and dermatological equipment. Pulse-energy stability commands premium pricing in solid-state platform specifications.
- Research Institutions:Atomic physics laboratories in the Munich-Jena corridor specify narrow-linewidth external-cavity designs for quantum sensing and optical clock applications.
Telecommunications generates the highest absolute volume, though medical devices deliver superior margin per unit.
Application:
Application-driven specification splits between precision measurement requirements and throughput-oriented processing tasks.
- Spectroscopy:Grating-tuned external-cavity diode architectures rewrite economics for atomic physics and environmental monitoring. Integrated feedback systems collapse historical premiums commanded by bulk solid-state alternatives.
- Material Processing:Pulsed solid-state and fiber platforms serve cutting and welding applications in German manufacturing. EU Green Deal energy efficiency mandates favor architectures with superior wall-plug efficiency.
- Communication:Wavelength-division multiplexing test equipment demands tunable sources with C-band and L-band coverage. French and German telecom infrastructure expansion drives specification volume.
- Sensing:Industrial automation and defense applications specify ruggedized packaging with hermetic sealing. Qualified housing demand outpaces domestic European foundry capacity.
Spectroscopy applications are expanding most quickly on quantum sensing investment, while material processing retains the largest installed base.
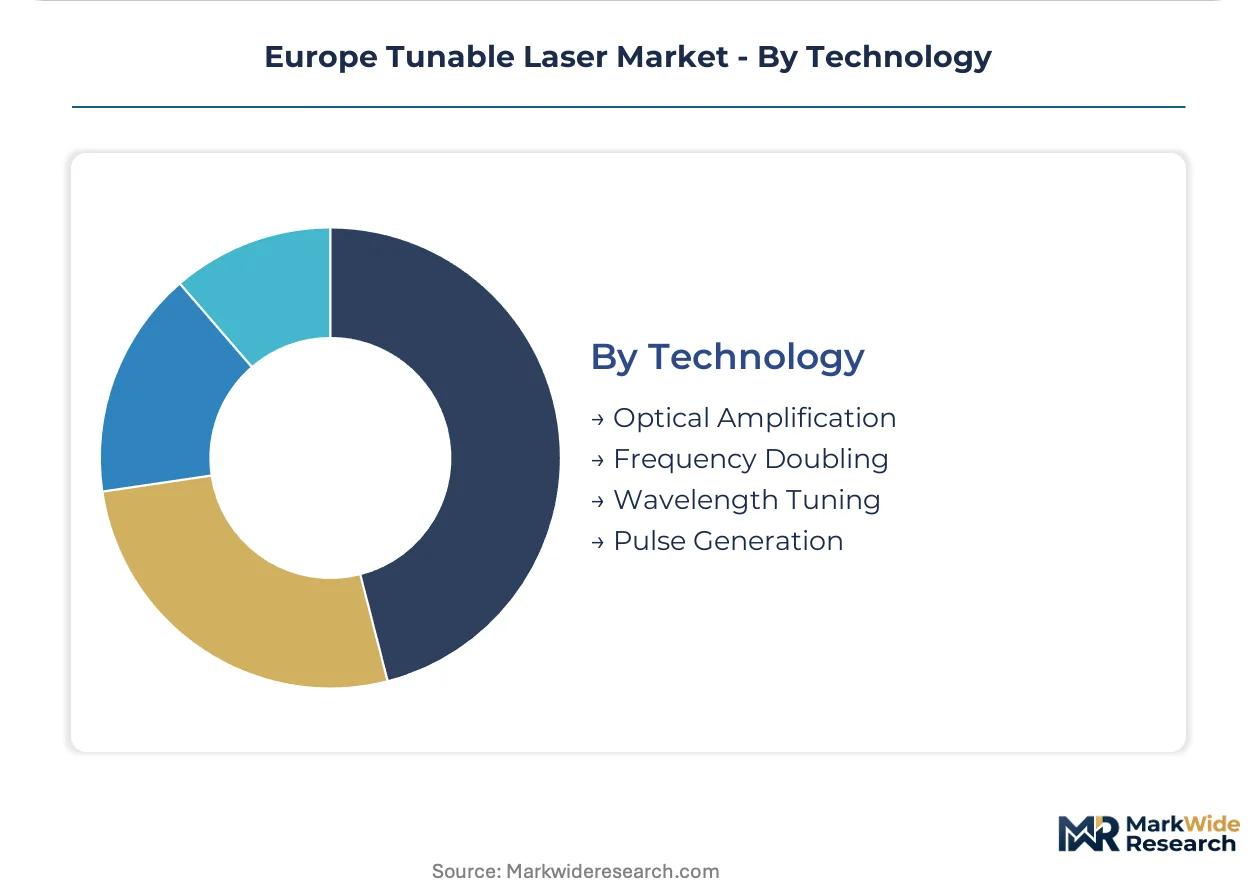
Technology:
Technology selection tracks the performance-cost tradeoff between precision specifications and manufacturing scalability.
- Optical Amplification:Erbium-doped fiber amplifiers dominate telecommunications signal conditioning. Spontaneous emission noise specifications determine system-level performance floors.
- Frequency Doubling:Nonlinear crystal conversion enables visible and UV output from infrared pump sources. BBO and LBO crystal sourcing faces REACH compliance scrutiny.
- Wavelength Tuning:Grating-based external-cavity feedback provides narrow-linewidth output across selectable ranges. Piezoelectric actuator precision determines tuning speed and resolution.
- Pulse Generation:Q-switching and mode-locking architectures serve material processing and medical applications. Pulse-energy stability differentiates premium solid-state platforms.
Wavelength tuning leads technology investment on spectroscopy demand, with optical amplification maintaining the broadest deployment footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance costs and ECHA substance restrictions are creating divergent production incentives across European jurisdictions, with some national regimes accelerating qualification timelines while others impose additional verification burdens.
Germany
Telecommunications infrastructure operators in Bavaria and North Rhine-Westphalia are deploying wavelength-division multiplexing systems requiring test-grade tunable sources. EU Green Deal decarbonization mandates under the national implementation framework prioritize energy-efficient laser architectures in industrial procurement. The Munich-Jena photonics corridor concentrates external-cavity diode fabrication for sensing and spectroscopy applications.
France
Atomic physics laboratories in the Paris-Saclay cluster and Grenoble area are adopting narrow-linewidth external-cavity designs for quantum sensing and optical clock research. ANSM oversight of medical device laser applications intersects with EU Medical Device Regulation CE marking requirements. The Île-de-France region anchors defense-qualified packaging demand that outpaces domestic foundry capacity.
United Kingdom
Research institutions in Cambridge and Oxford are specifying tunable sources for precision spectroscopy in environmental monitoring applications. Post-Brexit divergence from REACH substance restrictions creates parallel qualification tracks for crystal and coating materials. The Southeast England technology belt hosts system integrators disaggregating hardware procurement from calibration service contracts.
Switzerland
Swissmedic regulation of ophthalmic laser equipment shapes design verification cycles for medical device OEMs in the Basel-Zurich corridor. Industrial automation suppliers specify ruggedized tunable sources for automated quality control under emerging EU AI Act transparency obligations. The country's precision manufacturing heritage supports hermetic sealing expertise for defense-qualified housing.
Netherlands
Telecommunications test equipment distributors in the Randstad region are unbundling service contracts from hardware procurement to optimize operational expenditure treatment. The national implementation of RoHS substance restrictions affects rare-earth dopant sourcing for fiber laser gain media. Eindhoven's high-tech systems sector integrates laser-based measurement equipment into semiconductor metrology workflows.
Europe Tunable Laser Market Competitive Landscape
German producers anchor one tier of the market structure; French and Swiss specialists hold differentiated positions in adjacent segments. The vendor base concentrates around photonics clusters with legacy optoelectronics manufacturing heritage, creating moderate consolidation in external-cavity architectures alongside fragmentation in diode laser commoditized segments. Three archetypes dominate: vertically integrated crystal-to-system suppliers, defense-qualified packaging specialists, and narrow-linewidth research-grade fabricators. Capacity expansion in precision coating operations and strategic partnerships for rare-earth supply security represent the dominant competitive moves.
Within the vertically integrated tier, TOPTICA Photonics AG exemplifies control over crystal growth and coating operations to manage delivery timelines. HÜBNER Photonics occupies a position in specialized packaging for defense-qualified sources. Sacher Lasertechnik GmbH represents narrow-linewidth external-cavity design capabilities targeting atomic physics laboratories. These three German entities collectively illustrate how geographic clustering around the Munich-Jena corridor reinforces competitive positioning through rapid prototype-to-production cycles.
| Leading Market Players |
|---|
| TOPTICA Photonics AG |
| HÜBNER Photonics |
| Sacher Lasertechnik GmbH |
| Yenista Optics S.A. |
| LUMIBIRD |
| EKSPLA |
| Keysight Technologies |
| Coherent |
| Lumentum Operations LLC |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in the Munich-Jena corridor anchor supply-side discipline through captive coating operations and long-dated crystal sourcing contracts, insulating premium-tier pricing from commodity volatility while compressing margins in diode laser segments where third-party epitaxy wafer costs dominate input structures.
Pricing Analysis
Distributor margins on external-cavity diode architectures absorb 15-25 point markups before reaching atomic physics laboratories and quantum sensing startups, while direct-to-OEM channels for telecommunications test equipment command volume discounts that collapse channel economics. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and linewidth specification, with CE-marked medical device sources commanding 40-60 point premiums over industrial sensing equivalents. Pricing pressure stems from III-V epitaxy wafer input costs in temperature-current controlled diode segments, where German automotive suppliers drive procurement decisions on cost-per-channel metrics. Medical device OEMs exhibit lowest price sensitivity due to pulse-energy stability requirements and extended verification cycles, while industrial automation buyers prioritize total cost of ownership under EU Green Deal energy efficiency mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from German and French telecommunications infrastructure operators, while specialized distributors serve research institutions requiring application engineering support. Geographic concentration centers on Germany for external-cavity fabrication and hermetic packaging, with rare-earth dopant supply drawing from qualified sources outside the European Economic Area. Critical inputs span III-V epitaxy wafers, nonlinear crystals for frequency conversion, and precision piezoelectric actuators for grating-tuned feedback systems. Single-source vulnerability concentrates in BBO and LBO crystal supply for frequency doubling architectures, where REACH compliance scrutiny on coating materials constrains supplier qualification. Distribution runs through photonics cluster networks in the Munich-Jena corridor, enabling rapid prototype-to-production cycles for sensing and spectroscopy applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Tunable Laser Market functions as a stable compounder underpinned by EU Green Deal decarbonization mandates that lock in replacement-cycle demand for energy-efficient architectures across industrial and telecommunications verticals.
For Market Incumbents: To counter margin compression in diode laser segments from III-V epitaxy wafer pricing volatility, prioritize backward integration into crystal growth operations and captive coating facilities. Defend positioning in narrow-linewidth external-cavity architectures through R&D allocation toward integrated grating-tuned feedback systems for quantum sensing applications. CE marking investment under EU Medical Device Regulation creates qualification barriers that protect premium-tier pricing in ophthalmic and dermatological equipment supply chains. For New Entrants and Emerging Players: The 3-4x pricing multiple gap between telecom-grade and atomic physics-grade narrow-linewidth sources offers white-space entry through specialized packaging for defense-qualified applications. Target under-served demand in ruggedized hermetic housing for European defense procurement, where domestic foundry capacity constraints create supply bottlenecks. Penetration accelerates through partnership with established photonics cluster fabricators for rapid prototype validation before scaling to production volumes. For Investors and Strategic Acquirers: Defense electronics conglomerates represent the most active acquirer category in this space, seeking qualified subsystem suppliers for ruggedized tunable source integration. Long-term viability centers on 5-10 year compound growth from EU AI Act transparency obligations driving automated inspection system deployment. Acquisition target archetype: narrow-linewidth external-cavity fabricators with existing atomic physics laboratory relationships and transferable packaging expertise for defense qualification. Monitor ECHA substance-of-very-high-concern listing announcements as inflection indicators for crystal and coating material sourcing risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth | TOPTICA Photonics AG controls delivery timelines through in-house production of nonlinear crystals for frequency conversion. |
| Defense Packaging Specialization | HÜBNER Photonics anchors positioning through qualified ruggedized housing for European defense procurement programs. |
| CE Marking Pathway Investment | Medical device OEMs extend time-to-revenue cycles by 8-14 months under EU Medical Device Regulation verification requirements. |
| AI Act Compliance Integration | German automotive suppliers pre-qualify tunable sources with embedded metrology logging for automated quality control transparency. |
| Rare-Earth Supply Security Partnership | Fiber laser manufacturers hedge ECHA substance volatility through long-dated sourcing contracts outside the European Economic Area. |
Research Methodology
Direct dialogue with photonics foundry operations managers, telecommunications test equipment procurement leads, medical device OEM regulatory affairs directors, and atomic physics laboratory instrumentation specialists grounded qualitative assessment, cross-referenced against ECHA substance restriction filings, EU Medical Device Regulation guidance documents, SEC 10-K disclosures from listed component suppliers, and trade flow data for rare-earth dopant imports. Bottom-up unit demand estimates from end-use verticals reconciled with top-down market sizing through iterative triangulation.
Segment-level value outputs across the projection horizon reflect modeled interactions between product architecture, end-use vertical, and application requirements, with fiber laser, diode laser, solid-state laser, and gas laser categories further split by technology type including optical amplification, frequency doubling, wavelength tuning, and pulse generation. CAGRs derived from regression analysis of historical replacement cycles, EU Green Deal implementation timelines, and telecommunications infrastructure deployment schedules in Germany and France.
Caveats apply where ECHA substance-of-very-high-concern listing announcements, REACH compliance scope expansions, or III-V epitaxy wafer supply disruptions could materially shift the outlook for fiber and solid-state gain media availability. Periodic stress-testing of base assumptions against regulatory publication calendars and rare-earth trade flow data is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
South Korea Optical Detector Market
Optical Components
Fiber Optic Plates (FOP) Market
Optical Components
Ring Laser Gyroscope Market
Optical Components
Optical Instruments and Lenses Market
Optical Components
Microchannel Plates Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
Optical Film Market
Optical Components
Europe Optical Film Market
Optical Components
Global Optical Network Hardware Market
Optical Components
Optical Transceiver Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
Liquid Lenses Market
Optical Components
Optical Isolator Market
Optical Components
Optical Position Sensors Market