
 Optical Lens Edger Market | 2026-2036
Optical Lens Edger Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Lens Edger Market Intelligence
Independent opticians is rotating toward digital lens edgers as optical retail chains consolidate in-house finishing capacity. Nidek Co. Ltd. leverages vertical integration across diagnostic and edging platforms to sustain technology leadership in Asian markets. Essilor International S.A. anchors global supply through captive lens production networks that drive bundled equipment placements. Coburn Technologies Inc. specializes in mid-market automated systems that compete on total cost of ownership for regional laboratories.
An optical lens edger is a precision machining device that cuts, grinds, and bevels ophthalmic lens blanks to match frame dimensions using diamond-coated wheels or CNC-guided waterjet streams operating at tolerances below 0.05 millimeters. Digital lens edgers now dominate premium installations because their 3D frame tracing and freeform surfacing integration command the highest margin pools in the equipment hierarchy. Waterjet technology segments are gaining fastest among independent practices seeking reduced tooling changeover, while CNC grinding remains the volume backbone across high-throughput optical laboratories.
FDA 510(k) clearance pathways shape product development timelines for equipment sold into United States vision care clinics, while CE marking under the EU MDR and ISO 13485 quality management standards govern European market access for ophthalmic device manufacturers. Japan's PMDA and METI coordinate domestic type approval processes that filter which automated edging platforms reach Japanese optical retail chains. Stakeholders must monitor how dual carbon goals in China's GB standards and evolving EPA energy efficiency guidelines in North America reshape equipment design requirements for the next replacement cycle.
Market Dynamics
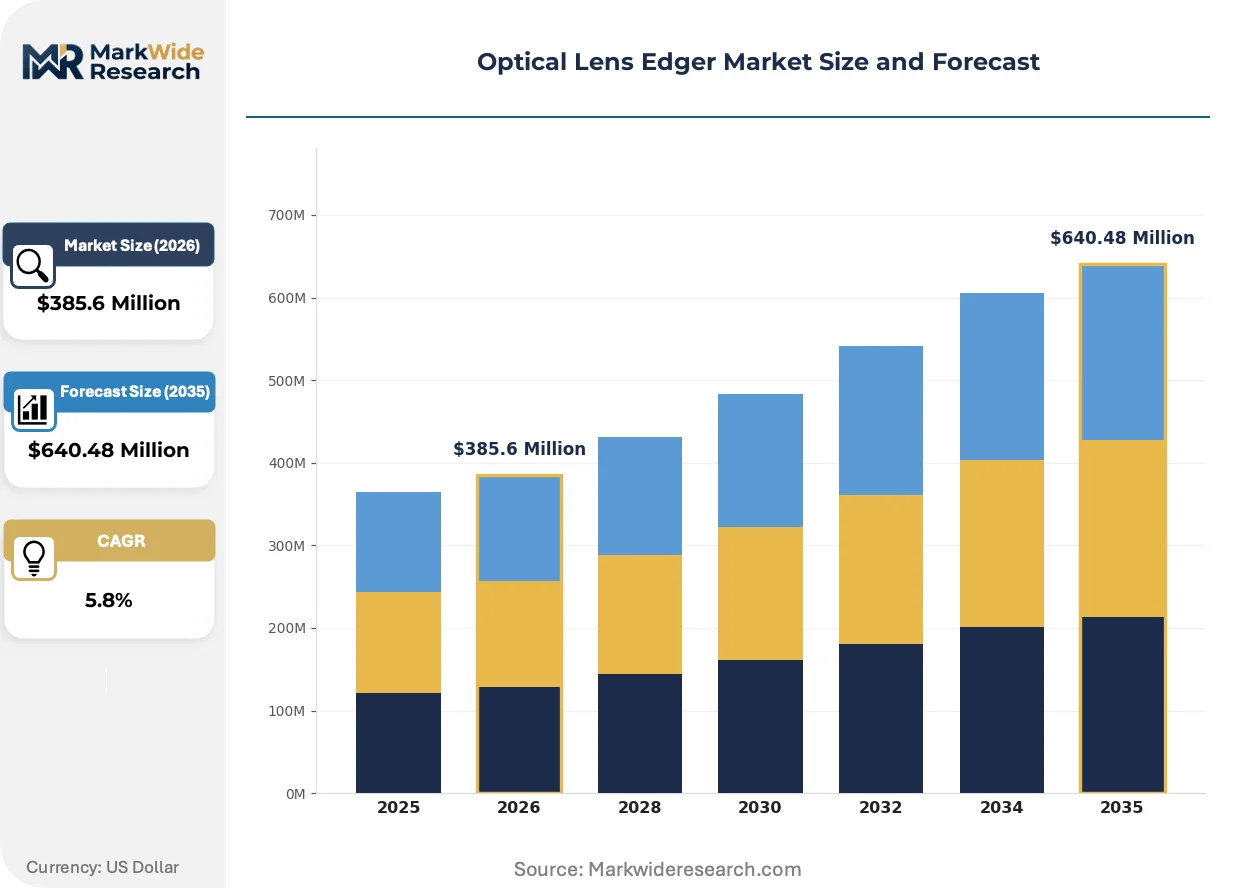
Digital edging platforms are compressing replacement cycles as independent opticians abandon mechanical systems to capture freeform lens margins, while regulatory precision mandates under FDA 510(k) and EU MDR extend equipment validation timelines.
Growth Catalysts
- Freeform surfacing integration:Digital edgers with integrated freeform capabilities command premium positioning as independent practices seek to differentiate against consolidated retail chains.
- EU MDR precision standards:Tightened CE marking requirements for ophthalmic equipment are filtering out legacy mechanical systems and accelerating certified digital platform adoption across European laboratories.
- Japan's vision care infrastructure:Dense networks of optical retail chains in metropolitan Tokyo and Osaka sustain replacement demand for automated edging systems with sub-0.05 millimeter tolerances.
Market Restraints
- Diamond wheel supply concentration:Precision abrasive tooling for CNC grinding platforms concentrates among Japanese and German suppliers, exposing laboratories to input cost volatility and extended lead times.
- FDA 510(k) pathway friction:Premarket notification requirements for automated ophthalmic devices extend product development timelines by 12-18 months for equipment targeting United States clinics.
- Waterjet technical limitations:Reduced material versatility for high-index polycarbonate and Trivex lens substrates constrains waterjet adoption in premium lens processing segments.
Strategic Opportunities
- India's underpenetrated independent sector:Fragmented optician networks in tier-2 and tier-3 cities present whitespace for mid-market automated systems as domestic lens manufacturing scales under PLI scheme incentives.
- Cloud-connected predictive maintenance:IoT-enabled edgers with remote diagnostics and automated consumables replenishment are creating recurring revenue streams for equipment vendors.
- China's dual carbon alignment:GB standards for energy-efficient ophthalmic equipment are favoring next-generation digital platforms with reduced power consumption and closed-loop coolant systems.
Industry Challenges
- Freeform programming expertise gap:Laboratories face acute shortages of technicians capable of operating integrated surfacing-edging workflows and troubleshooting complex optical path calculations.
- Legacy system integration complexity:Hybrid environments combining mechanical edgers with new digital platforms require custom middleware development and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Lens Edger Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Lens Edger, Semi-Automatic Lens Edger, Automatic Lens Edger, Digital Lens Edger Technology: CNC Grinding, Waterjet Technology, Diamond Cutting, Laser Engraving, Ultrasonic Cutting Application: Optical Retail Stores, Optical Laboratories, Vision Care Clinics, Eyewear Manufacturers End User: Optometrists, Dispensing Technicians, Ophthalmic Laboratories, Independent Opticians |
| Companies Covered | Nidek Co. Ltd., Essilor International S.A., Topcon Corporation, Coburn Technologies Inc., Huvitz Corp., Luneau Technology Operations SAS, Mei Srl, Santinelli International, Shanghai Supore Instruments Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Lens Edger Market Strategic Shifts & Innovations
Waterjet cutting architectures are gaining traction in independent practices seeking operational flexibility, while regulatory precision mandates and shifting procurement models reshape competitive positioning across equipment tiers.
Waterjet lens edging is supplanting conventional diamond wheel grinding in mid-volume independent optician practices. Solo practitioners and small multi-location groups in Germany and the United States are adopting waterjet systems to eliminate tooling changeover delays and reduce consumables inventory. This technology is supplanting mechanical grinding as the default choice for practices prioritizing operational simplicity over maximum throughput.
EU MDR Class IIa device classification is tightening post-market surveillance obligations for ophthalmic equipment manufacturers. CE marking technical documentation now requires extended clinical evidence and risk management files, compressing margins for mid-tier equipment vendors. Japanese optical laboratories are responding fastest by consolidating supplier relationships toward vertically integrated platform providers with established notified body partnerships.
Equipment-as-a-service financing is displacing capital purchase models among cash-constrained independent opticians. Third-party leasing through specialized medical equipment financiers is capturing share from traditional distributor credit programs in France and Italy. This shift is most visible among practices aged 5-15 years post-establishment, where owners prioritize preserving working capital for inventory and digital retail upgrades.
Optical Lens Edger Market Segmentation
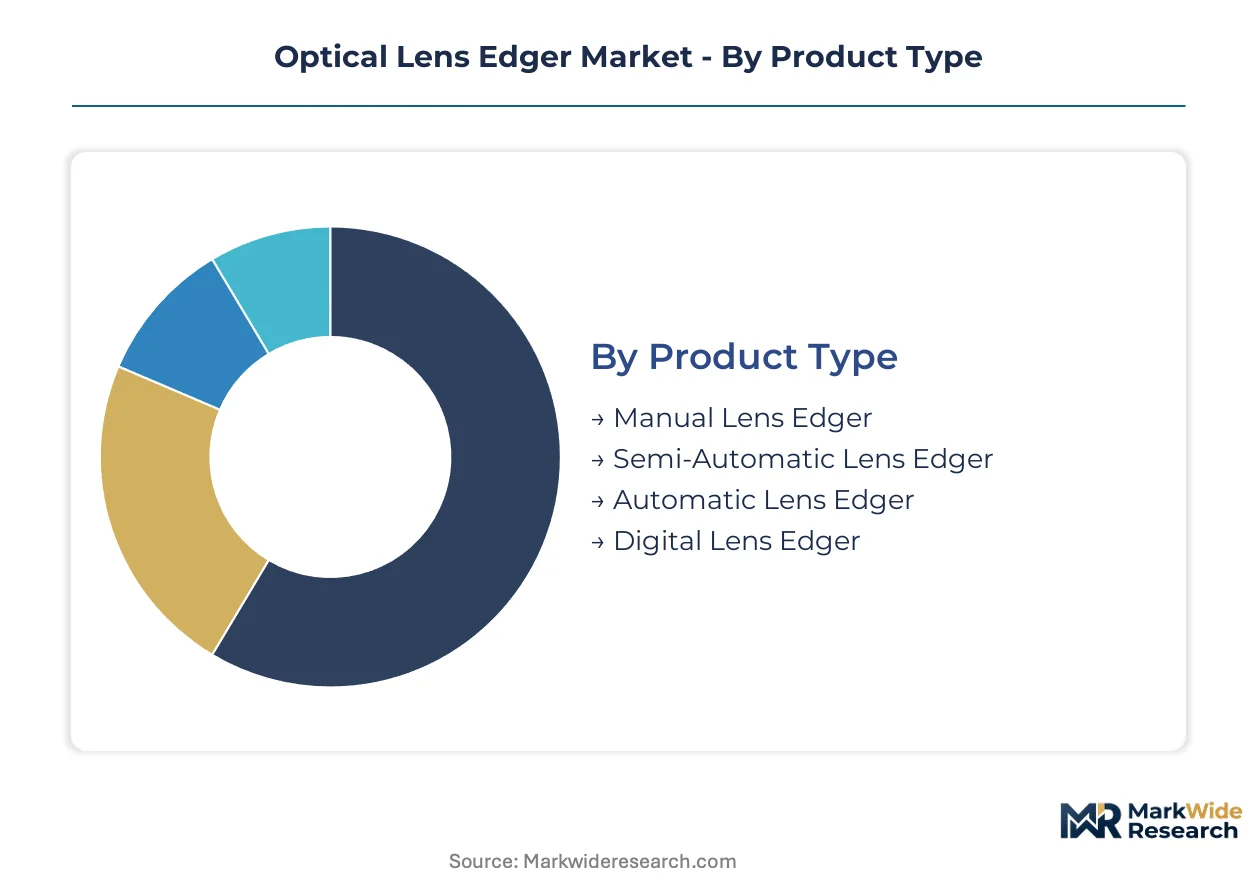
Segmentation in optical lens edgers reveals how margin pools concentrate around precision capabilities and workflow integration. Equipment tiers separate practices capable of freeform surfacing from those limited to conventional finishing, while technology choices determine consumables economics and technician skill requirements.
Product Type:
Premium positioning and recurring service revenue cluster around digitally integrated platforms that command the highest equipment margins.
- Manual Lens Edger:Hand-operated grinding systems with mechanical tracing arms remain confined to ultra-low-volume rural practices and vocational training facilities. Demand in India's tier-3 cities persists where capital constraints block automated upgrades.
- Semi-Automatic Lens Edger:Motorized grinding with manual frame tracing bridges mechanical and digital workflows. Small independent opticians in Italy and Spain retain these systems for basic single-vision processing where freeform margins are unattainable.
- Automatic Lens Edger:Programmable cycle control with automated beveling dominates high-throughput optical laboratories serving retail chains. German and Japanese laboratories favor these for standardized production runs where setup efficiency outweighs customization flexibility.
- Digital Lens Edger:CNC-guided platforms with 3D frame tracing and direct freeform surfacing integration capture the steepest expansion trajectory. Independent opticians in Germany, Japan, and the United States adopt these to differentiate against consolidated retail chains through premium lens customization.
The dominant share belongs to Automatic Lens Edger, while Digital Lens Edger is closing the gap fastest.
Technology:
Equipment selection here determines tooling inventory costs, substrate versatility, and maintenance complexity for laboratory operations.
- CNC Grinding:Diamond-coated wheel systems with multi-axis positioning deliver sub-0.05 millimeter tolerances across all lens indices. High-throughput laboratories in Japan and Germany depend on CNC grinding for polycarbonate and Trivex processing where waterjet performance lags.
- Waterjet Technology:High-pressure abrasive streams eliminate tooling changeover and reduce consumables inventory for mid-volume practices. Solo practitioners in the United States and Germany adopt waterjet systems to simplify operations despite limitations on high-index materials.
- Diamond Cutting:Precision abrasive wheels for specialized bevel profiles and rimless mounting configurations serve premium eyewear manufacturers. Swiss and Italian luxury frame producers specify diamond cutting for aesthetic edge finishing.
- Laser Engraving:Non-contact surface marking for lens identification and branding integrates with edging workflows. Eyewear manufacturers in South Korea deploy laser systems for traceability compliance under domestic quality standards.
- Ultrasonic Cutting:High-frequency vibration cutting for brittle materials and specialized coatings addresses niche applications. Limited adoption concentrates in research laboratories testing next-generation lens substrates.
CNC Grinding retains the largest installed base, though Waterjet Technology is gaining share fastest among independent practices prioritizing operational simplicity.
Application:
Procurement authority and replacement frequency vary sharply across these settings, shaping vendor sales strategies and service contract structures.
- Optical Retail Stores:In-store finishing systems enable same-day service and reduced inventory holding. Consolidated chains in Japan and the United States centralize edging capacity while independents invest in compact digital platforms.
- Optical Laboratories:Centralized production facilities processing thousands of lenses daily require maximum throughput and minimal downtime. Regional laboratories in Germany and the United States compete on turnaround speed through automated platform investments.
- Vision Care Clinics:Integrated diagnostic and finishing workflows support premium positioning in medical-oriented practice models. Clinics in the United States leverage FDA-cleared digital platforms to capture freeform lens margins.
- Eyewear Manufacturers:In-house edging for custom and prototype production demands flexible tooling and rapid changeover. Italian and French luxury producers maintain captive edging for quality control over rimless and specialty mountings.
Optical Laboratories command the dominant procurement volume, while Vision Care Clinics are expanding equipment budgets fastest.
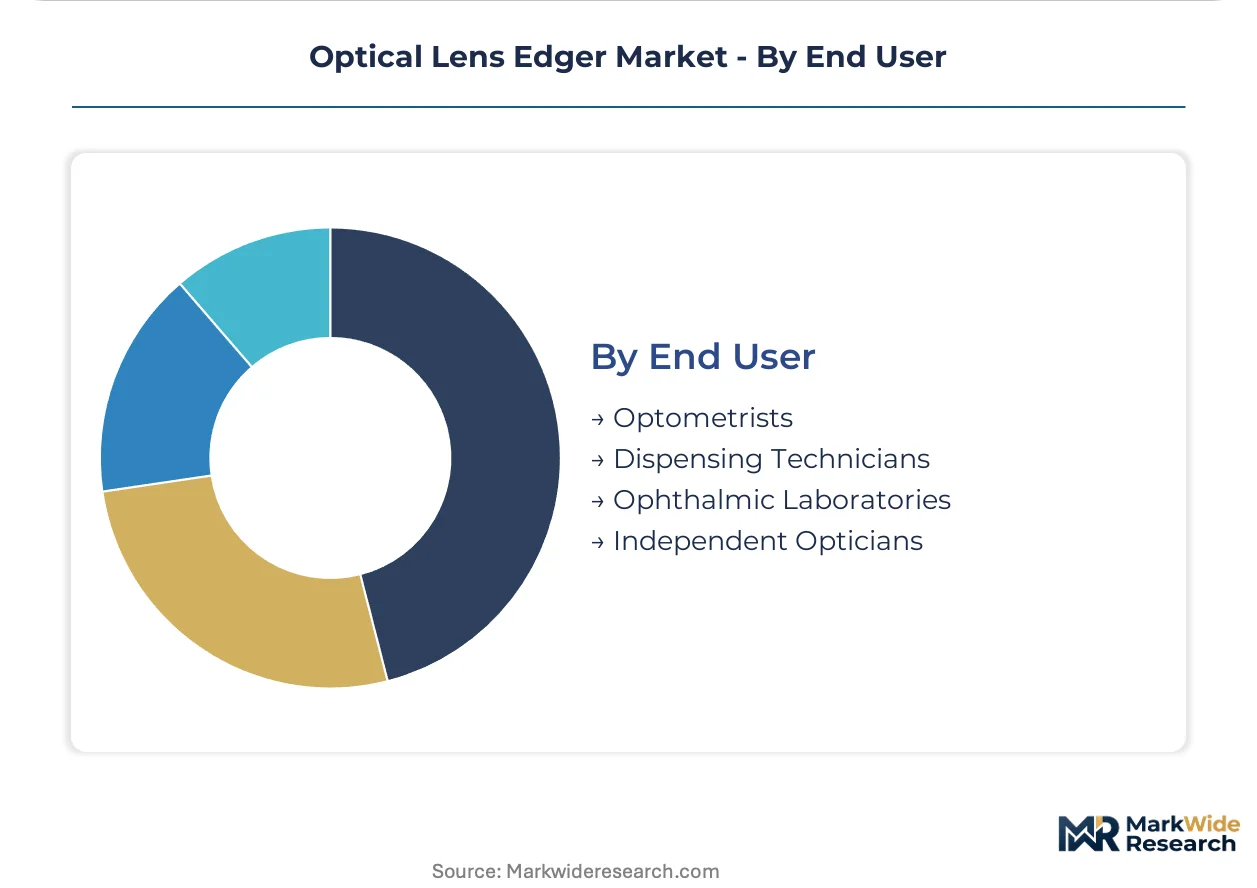
End User:
Technical sophistication and purchasing autonomy diverge significantly across these operator categories, driving tiered product positioning.
- Optometrists:Clinically trained practitioners with diagnostic authority often delegate equipment decisions to practice managers. Optometrists in the United States and Japan favor integrated diagnostic-edging platforms that reinforce medical positioning.
- Dispensing Technicians:Frontline operators handling frame fitting and lens verification require intuitive interfaces and minimal training burden. Technician workflows in German optical retail chains drive demand for touchscreen-controlled automated systems.
- Ophthalmic Laboratories:Specialized facilities with dedicated maintenance staff prioritize throughput metrics and service response times. Japanese laboratories maintain strict supplier relationships with vendors offering METI-coordinated type approvals.
- Independent Opticians:Owner-operators with capital constraints and differentiation needs evaluate total cost of ownership and margin capture potential. Independent opticians across France and Italy are shifting toward equipment-as-a-service financing to preserve working capital.
Ophthalmic Laboratories represent the largest end-user segment by unit volume, while Independent Opticians are driving the steepest demand expansion for digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision equipment exports supply optical laboratories across Western Europe and North America, while Japanese manufacturers dominate premium digital platform shipments to Asian vision care networks.
United States
Consolidated retail chains and independent opticians drive replacement demand for FDA 510(k)-cleared digital edgers with freeform integration. The EPA's evolving energy efficiency guidelines shape equipment specifications for the next replacement cycle. California and Texas host the densest concentrations of high-throughput optical laboratories serving multi-state retail networks.
Germany
Advanced vision care infrastructure supports premium equipment upgrades across independent optician networks and centralized laboratories. CE marking under the EU MDR tightens precision standards for ophthalmic equipment entering German facilities. The Munich-Stuttgart corridor anchors European demand for sub-0.05 millimeter tolerance automated systems.
Japan
Dense metropolitan optical retail chains in Tokyo and Osaka sustain replacement cycles for automated edging platforms. METI and PMDA coordinate domestic type approval processes that filter equipment reaching Japanese practitioners. The Nagoya-Osaka industrial belt concentrates precision machining expertise for diamond-coated wheel production.
China
Domestic lens manufacturing scales under PLI scheme incentives, expanding demand for mid-market automated systems in tier-2 and tier-3 cities. GB standards for energy-efficient ophthalmic equipment favor digital platforms with reduced power consumption. The Yangtze River Delta clusters optical equipment assembly operations serving both domestic and export markets.
India
Fragmented independent optician networks in tier-2 and tier-3 cities present whitespace for automated system penetration as domestic lens production expands. BIS certification requirements shape equipment import specifications for regional laboratories. Maharashtra and Gujarat host emerging ophthalmic manufacturing zones under production-linked incentive frameworks.
Optical Lens Edger Market Key Industry Players
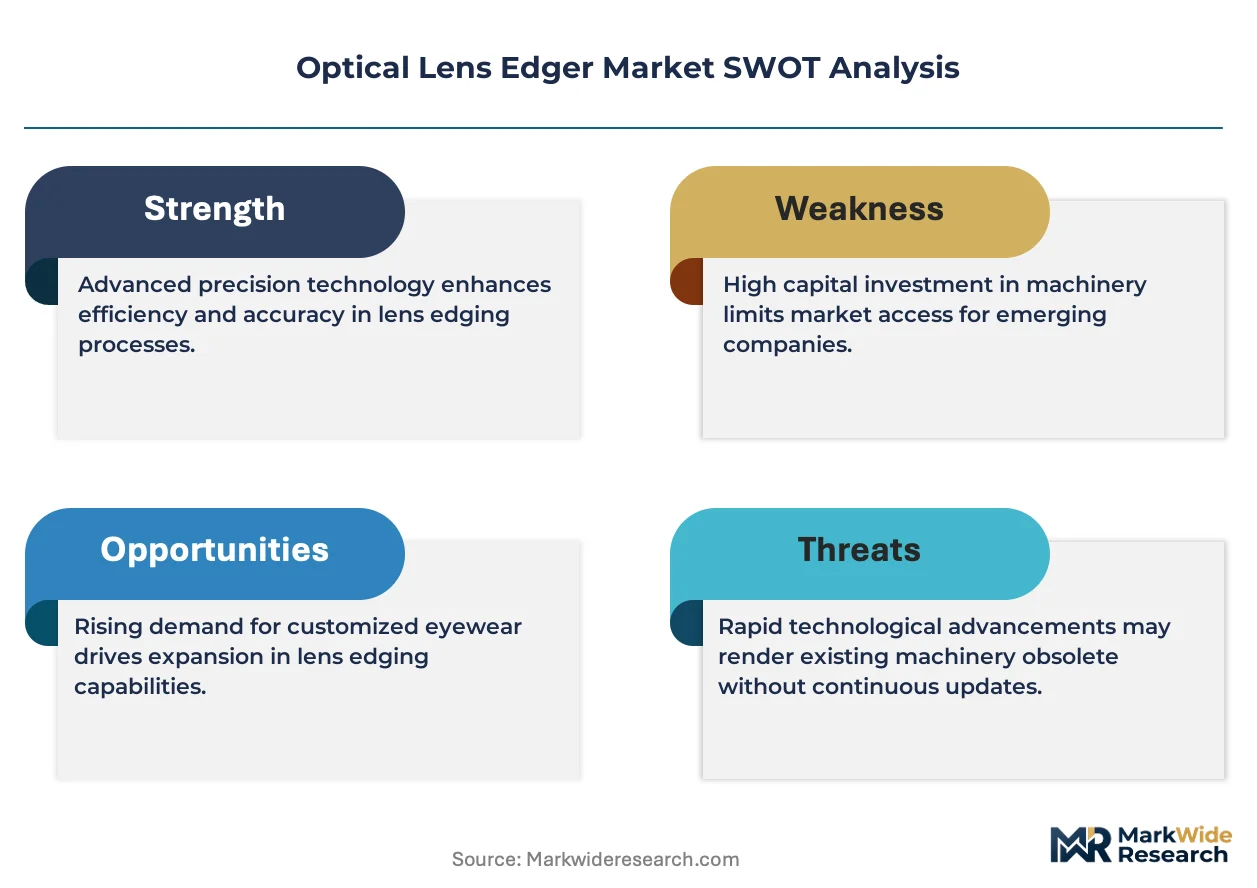
Player mix skews toward vertically integrated ophthalmic platform specialists and mid-market automation focused fabricators. The vendor base separates into three tiers: premium integrated diagnostic-edging platform providers, mid-market automated system specialists, and regional mechanical equipment suppliers. Consolidation pressures favor archetypes with captive lens production networks and established notified body partnerships. Competitive moves concentrate on backward integration into precision consumables and cloud-connected service model expansion.
Among Japanese precision equipment specialists, Nidek Co. Ltd. and Topcon Corporation exemplify the vertically integrated archetype spanning diagnostic and edging platforms. Essilor International S.A. occupies a position representing captive lens production networks that drive bundled equipment placements. Coburn Technologies Inc. sits within the mid-market automation tier competing on total cost of ownership metrics. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning across premium and standard equipment tiers.
| Leading Market Players |
|---|
| Nidek Co. Ltd. |
| Essilor International S.A. |
| Topcon Corporation |
| Coburn Technologies Inc. |
| Huvitz Corp. |
| Luneau Technology Operations SAS |
| Mei Srl |
| Santinelli International |
| Shanghai Supore Instruments Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Sixty-day diamond wheel lead times from Japanese suppliers concentrate input cost volatility among mid-market laboratories, compressing margins for equipment vendors lacking captive abrasive production or long-term supply agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CNC-guided digital platforms with freeform integration from semi-automatic motorized systems and legacy manual edgers. Price differentiation hinges on FDA 510(k) certification tier and after-sales service bundling, with CE marking under EU MDR adding compliance premiums for European-bound shipments. Pricing pressure stems from equipment-as-a-service financing displacing capital purchases among cash-constrained independent opticians. Independent opticians in France and Italy exhibit highest price sensitivity, while Japanese optical retail chains prioritize precision tolerances over acquisition cost.
Supply Chain Analysis
Yokohama-Osaka shipping lanes and Rhine-Ruhr inland waterways constitute critical logistics chokepoints for precision ophthalmic equipment moving between Asian manufacturing hubs and European laboratory networks. Geographic supply concentration centers on Japan, Germany, and China for diamond-coated wheels, CNC control systems, and lens blank substrates respectively. Raw material dependencies include synthetic diamond abrasives, high-grade aluminum alloys for machine frames, and specialized optical polymers for lens processing. Single-source vulnerability runs through Japanese diamond wheel suppliers exposed to seismic disruption risk. Distribution runs through authorized dealer networks with regional service depots in metropolitan optical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital edging platforms are disrupting replacement cycles as EU MDR precision mandates filter legacy mechanical systems from European laboratories, creating compressed upgrade windows for vendors with notified body partnerships.
For Market Incumbents: Shield market position by deepening backward integration into diamond abrasive production to neutralize input cost volatility from Japanese suppliers, while accelerating cloud-connected predictive maintenance deployments to capture recurring revenue streams. Waterjet technology entrants from mid-market automation specialists threaten CNC grinding incumbents in independent practice segments. For New Entrants and Emerging Players: Cloud-enabled remote diagnostics capabilities represent the most pronounced service-layer gap where established vendors under-serve tier-2 and tier-3 independent opticians. Target India's fragmented optician networks in emerging manufacturing zones under PLI scheme incentives, leveraging equipment-as-a-service financing to bypass capital constraints. Partner with domestic lens manufacturers for bundled platform placements. For Investors and Strategic Acquirers: Long-term, this sits as a medical-device consolidation play because regulatory precision mandates under FDA 510(k) and EU MDR are filtering sub-scale competitors and concentrating procurement authority among vertically integrated platform providers. Acquisition targets should exhibit captive consumables production and established notified body relationships. Monitor METI type approval timelines as inflection indicator for Japanese market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa compliance filters legacy mechanical systems from European laboratory procurement. |
| Cloud-Connected Predictive Maintenance | IoT-enabled edgers with remote diagnostics create recurring revenue streams for equipment vendors. |
| Backward Integration into Diamond Abrasives | Captive synthetic diamond wheel production neutralizes supply concentration risk from Japanese suppliers. |
| Equipment-as-a-Service Financing | Third-party leasing preserves working capital for independent opticians prioritizing inventory over capex. |
| Freeform Surfacing Integration | Direct CNC-guided platform integration commands premium positioning against consolidated retail chains. |
Research Approach
Desk research of FDA 510(k) device filings, EU MDR technical documentation, and METI type approval records preceded structured interviews with optical laboratory directors, ophthalmic equipment procurement managers, and independent optician owner-operators across Germany, Japan, and the United States. Secondary validation drew from ISO 13485 quality management audits, customs trade data for precision ophthalmic equipment, and SEC filings from publicly traded vision care equipment manufacturers. Bottom-up demand modeling triangulated against top-down market sizing from national optical industry associations.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling spanning equipment type, technology architecture, application setting, and end-user sophistication tier. CAGRs were derived from replacement cycle compression rates and regulatory mandate timing. Industry-specific forecast inputs include freeform lens adoption curves and equipment-as-a-service financing penetration assumptions.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways, EU MDR Class IIa device classification, and Japan's PMDA-METI coordination framework; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as China's GB standards for energy-efficient ophthalmic equipment and evolving EPA guidelines reshape equipment design requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Ring Panel Filters Market
Optical Components
Display Optical Film Market
Optical Components
Global Tunable Filter Market
Optical Components
Spatial Light Modulator Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Photomask Pellicle Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Raman Amplifier Market
Optical Components
Photointerrupter Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Optical Sensor Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Package Shell for Optical Communication Modules Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Japan Lithium Niobate Modulator Market