
 Fiber Optic Collimating Lens Market | 2026-2036
Fiber Optic Collimating Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Collimating Lens Market Foresight
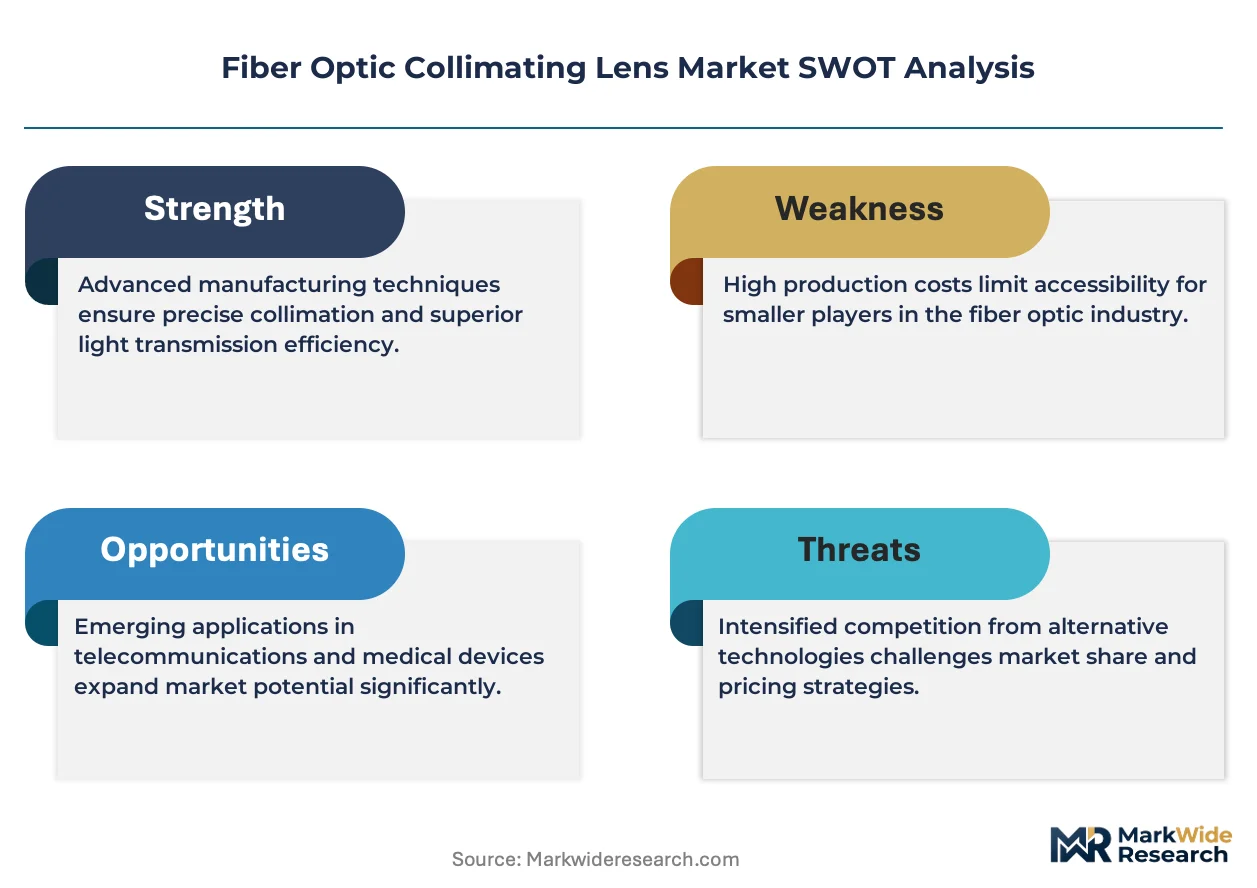
The premium aspheric collimating lens segment is consolidating around sub-micron surface figure tolerances, while commodity-grade plastic lenses compete on volume pricing for consumer electronics. Thorlabs Inc leverages its vertically integrated metrology capabilities to sustain dominance in research-grade assemblies. Coherent anchors its position through captive crystal growth and polishing operations for high-power fiber laser systems. Edmund Optics differentiates by controlling regional distribution hubs across North America, Europe, and Asia.
A fiber optic collimating lens transforms divergent light from an optical fiber into a parallel beam, typically achieving wavefront errors below lambda over four at 1550 nanometers for telecom-grade devices. These lenses enable efficient coupling between fibers, detectors, and free-space optical elements in systems where alignment precision determines signal integrity. Aspheric lenses command the dominant share due to their single-element aberration correction, while quartz substrates represent the fastest-growing material category as ultraviolet and high-power applications expand. Sensing applications are gaining structural importance as LiDAR and distributed acoustic sensing deployments multiply, though telecommunications retains the deepest margin pools through long-term supply agreements with tier-one telecom companies.
The US Federal Communications Commission shapes demand through broadband infrastructure subsidy programs that mandate domestic content thresholds for funded fiber deployments. Europe's ECHA enforces REACH substance restrictions that constrain lead-oxide glass formulations traditionally used in high-index collimating lenses, pushing manufacturers toward alternative crown glass compositions. China's MIIT imposes GB standards for optical component reliability that foreign suppliers must certify against for 5G equipment qualification. Stakeholders must monitor how diverging regulatory timelines for per- and polyfluoroalkyl substance restrictions across these jurisdictions will reshape material qualification pipelines and supplier certification costs.
Market Dynamics
Telecom carriers are consolidating supplier bases for 5G backhaul fiber-to-the-home rollouts, compressing procurement timelines and elevating surface-figure tolerance requirements above lambda over ten for qualified vendors.
Growth Catalysts
- 5G Backhaul Buildouts:China's MIIT GB standards for optical reliability are accelerating domestic qualification of precision collimating assemblies for base station fiber links.
- REACH Material Substitution:ECHA enforcement against lead-oxide glass is redirecting R&D budgets toward crown glass alternatives with equivalent refractive indices.
- LiDAR Sensor Integration:Automotive tier-one suppliers are specifying quartz-collimator subassemblies for 1550-nanometer long-range detection modules.
Market Restraints
- Raw Material Concentration:Synthetic fused silica precursor supply concentrates among three Japanese chemical conglomerates, creating input cost volatility for UV-grade lens manufacturers.
- Sub-Micron Metrology Bottleneck:Interferometric surface measurement equipment lead times extend to twenty-six weeks, constraining capacity expansion for aspheric polishers.
- Polymer Substitution Threat:Molded plastic collimators from consumer electronics supply chains are displacing glass in cost-sensitive datacom transceiver applications below ten gigabits per second.
Strategic Opportunities
- Underpenetrated Medical Imaging:OEMs in Germany and Switzerland are qualifying fiber-coupled OCT systems requiring sub-lambda wavefront correction for ophthalmic diagnostics.
- Quantum Key Distribution:National laboratory procurement programs in the US and Netherlands are sourcing polarization-maintaining collimator assemblies for entangled photon sources.
- India PLI Incentive:The country's production-linked incentive scheme for telecom equipment is attracting lens module assembly investments serving domestic 5G equipment manufacturers.
Industry Challenges
- Coating Process Migration:Ion-beam sputtering technicians with dielectric thin-film expertise command premium wages in Shenzhen and Boston metro clusters, constraining yield ramp rates.
- Multi-Jurisdiction Certification:Simultaneous FCC part 15, CE marking, and MIIT GB testing for telecom-grade collimators extends qualification timelines by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Collimating Lens Market |
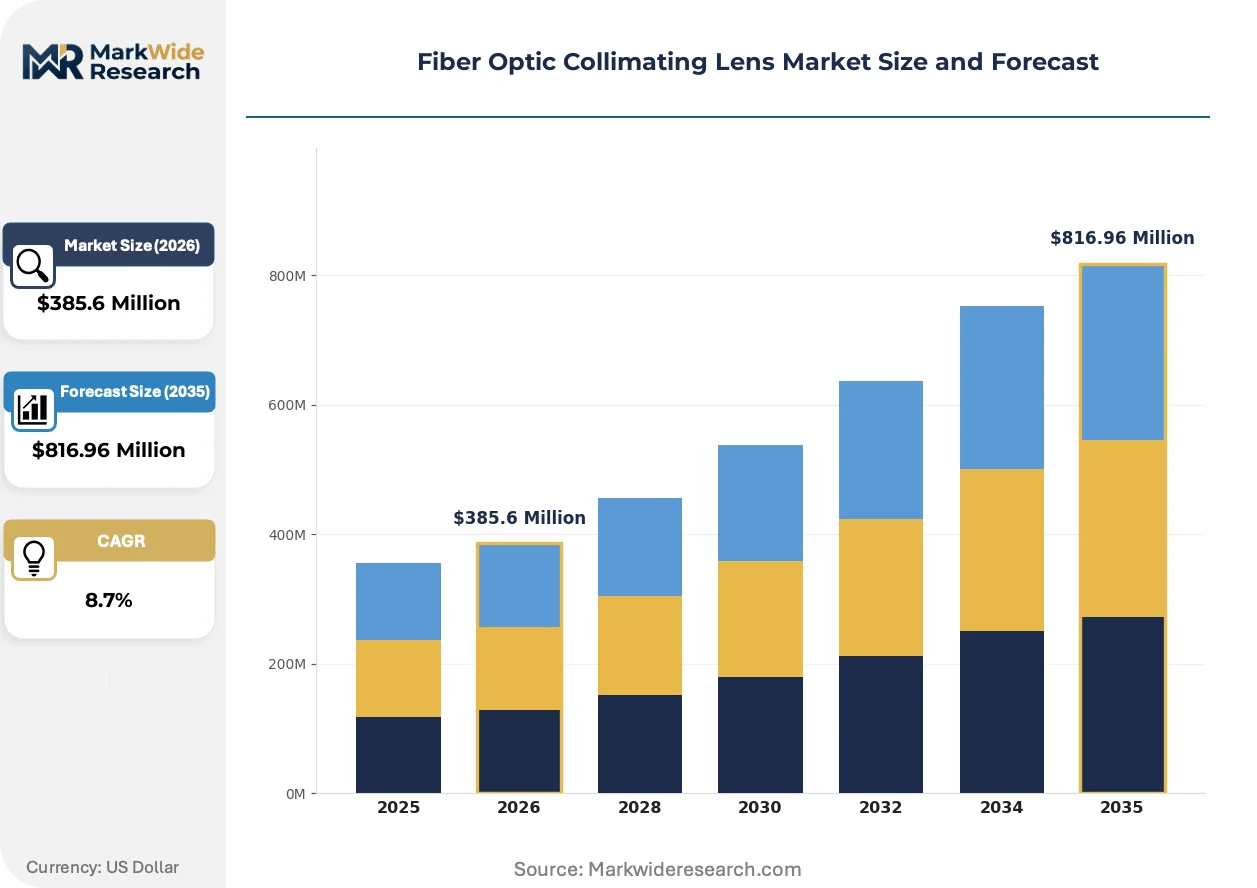
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Aspheric, Convex, Concave, Cylindrical Material: Glass, Plastic, Silicon, Quartz Application: Telecommunications, Sensing, Medical Devices, Consumer Electronics End User: Telecom Companies, Research Institutions, Healthcare Providers, Electronics Manufacturers |
| Companies Covered | AMS Technologies AG, IPG Photonics Corporation, Coherent, Thorlabs Inc, Edmund Optics, Fabrinet, Gooch & Housego, OZ Optics Ltd, LightPath Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Collimating Lens Market Shifts & Advancements
Active alignment automation and deterministic polishing algorithms are compressing the performance gap between research-grade and volume-manufactured aspheric collimators.
Freeform surface metrology is unifying formerly separate grinding and polishing process steps into continuous deterministic correction loops. Equipment suppliers in Rochester, New York and Jena, Germany are installing these platforms for telecom lens manufacturers. The technology is unifying quality control with fabrication, collapsing final inspection from hours to minutes per optic.
Europe's ECHA is expanding per- and polyfluoroalkyl substance restrictions into optical coating chemistries previously exempt under REACH annexes. German and French lens coaters are reformulating anti-reflection stacks to eliminate fluorinated precursors. High-power fiber laser collimators for materials processing applications face the steepest reformulation costs due to damage-threshold requirements.
Telecom carriers are consolidating optical component vendors from twelve to four qualified suppliers per fiber-to-the-home deployment region. Procurement teams at Verizon, Deutsche Telekom, and China Mobile now mandate in-line process data sharing rather than batch certificate review. The practice is most visible in China's Yangtze River Delta cluster, where MIIT auditors verify supplier traceability systems before 5G equipment qualification.
Fiber Optic Collimating Lens Market Segmentation
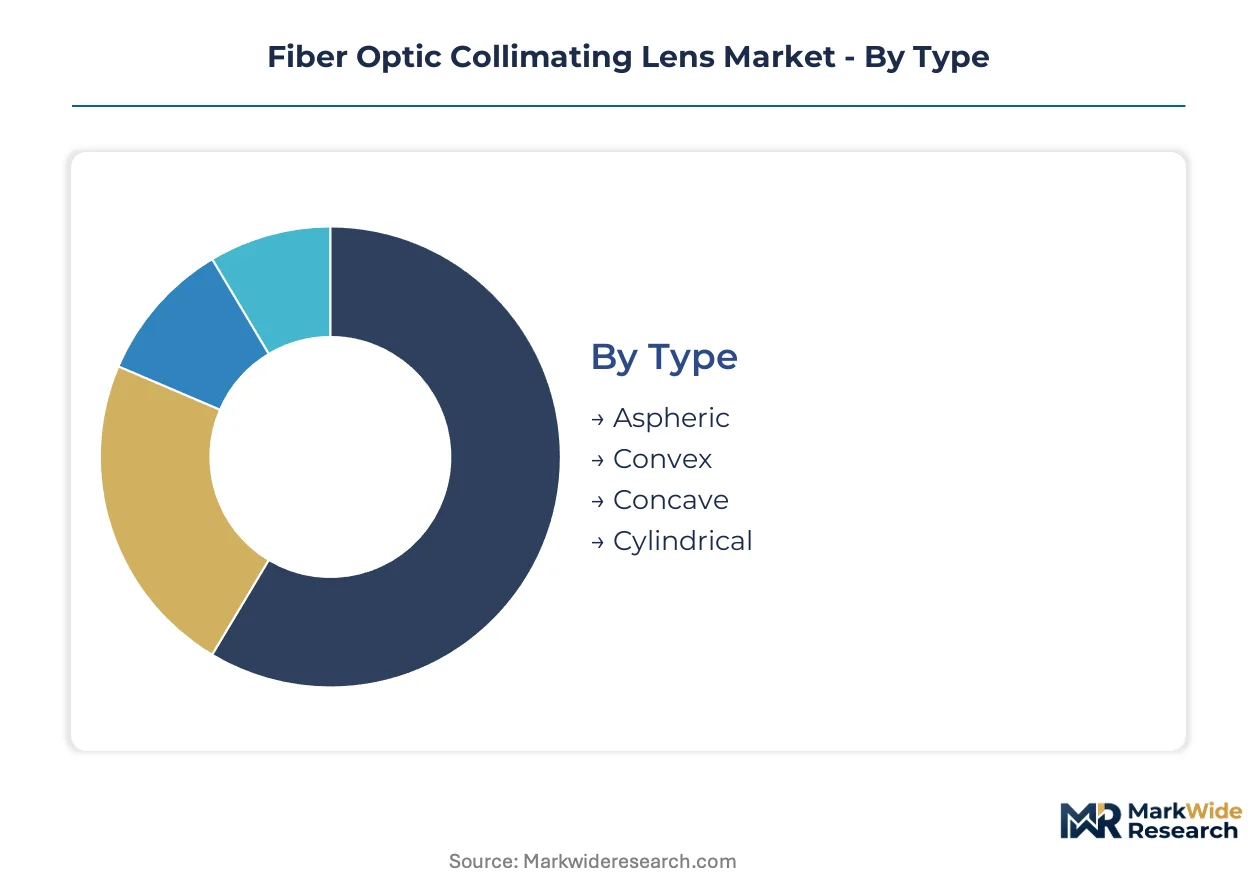
Collimating lens selection hinges on integration depth—standalone assemblies for test benches demand different specifications than embedded subsystems in transceiver modules. Procurement teams weight surface figure tolerance against volume pricing tiers when matching lens categories to deployment contexts.
Type:
Standalone collimators dominate laboratory and test equipment, while embedded variants integrate into sealed transceiver housings with active alignment.
- Aspheric:Single-element designs correct spherical aberration without multi-lens stacks, achieving wavefront errors below lambda over four at 1550 nanometers. Telecom carriers in China specify these for 5G backhaul fiber links where signal integrity determines base station performance.
- Convex:Spherical convex surfaces provide cost-effective collimation for multi-mode fiber applications with relaxed alignment tolerances. Datacom transceiver manufacturers in Shenzhen embed these in short-reach modules below ten gigabits per second where plastic substitution pressure intensifies.
- Concave:Diverging beam expansion for beam expander subassemblies and telescope front-ends in free-space optical communication links.
- Cylindrical:Anamorphic correction for diode laser collimation and line-generating optics in machine vision systems.
Volume placements concentrate in convex designs for cost-sensitive datacom; the faster expansion belongs to aspheric assemblies as telecom tolerance requirements tighten.
Material:
Cost tiers separate UV-grade synthetic fused silica from molded polymer alternatives, with crown glass formulations occupying the mid-range for telecom reliability.
- Glass:Crown and flint glass compositions offer thermal stability and chemical resistance for outdoor fiber terminal deployments. ECHA REACH enforcement against lead-oxide formulations is redirecting German and French manufacturers toward alternative high-index crown glasses for long-haul telecommunications.
- Quartz:Synthetic fused silica transmits deep ultraviolet and withstands kilowatt-level fiber laser powers without thermal lensing. Automotive LiDAR suppliers specify quartz collimators for 1550-nanometer long-range detection modules where laser safety margins dominate design choices.
- Plastic:Molded acrylic and polycarbonate lenses serve consumer electronics and disposable medical sensors at unit costs below glass by an order of magnitude.
- Silicon:MEMS-compatible substrates for photonic integrated circuits and silicon photonics transceivers in hyperscale datacenter interconnects.
Glass retains the deepest volume in telecom infrastructure; quartz is climbing the fastest as high-power and UV applications multiply.
Application:
Application maturity varies—telecommunications commands established qualification protocols while medical and sensing segments build device-specific certification pipelines.
- Telecommunications:Fiber-to-the-home and 5G backhaul deployments consume precision collimators in volume, with carriers consolidating qualified supplier bases from twelve to four vendors per region. FCC broadband subsidy programs with domestic content thresholds shape procurement in the United States.
- Sensing:Distributed acoustic sensing for pipeline monitoring and LiDAR for autonomous navigation drive specification of polarization-maintaining and wide-bandwidth collimator assemblies.
- Medical Devices:Fiber-coupled OCT systems for ophthalmic diagnostics require sub-lambda wavefront correction, with German and Swiss OEMs qualifying specialized supply chains.
- Consumer Electronics:Gesture recognition and face authentication modules in smartphones employ molded plastic collimators at million-unit scales.
Telecommunications maintains the largest placement volumes; sensing applications are gaining share fastest as infrastructure monitoring and automotive LiDAR deployments accelerate.
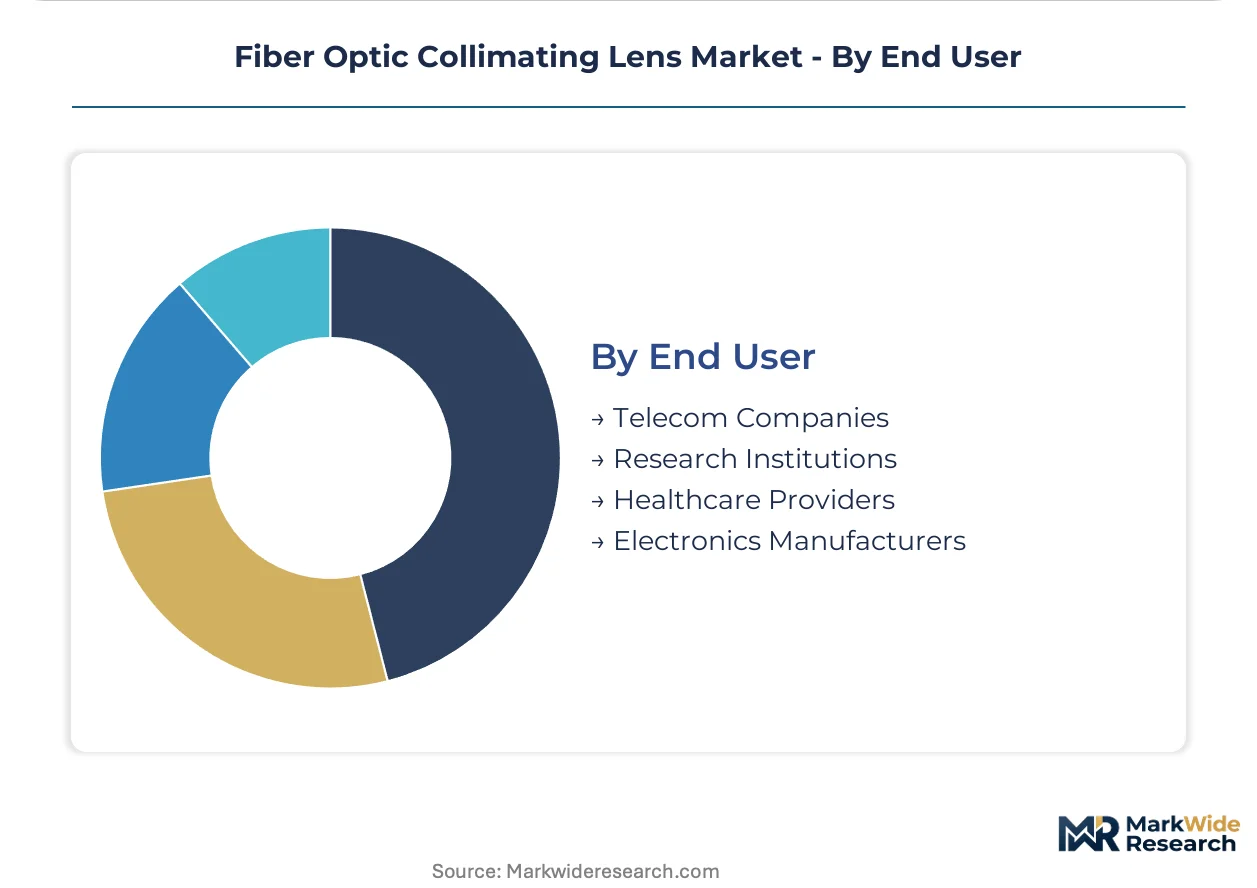
End User:
Customer type determines contract structure—telecom carriers demand multi-year supply agreements with process data sharing, while research institutions prioritize specification flexibility.
- Telecom Companies:Verizon, Deutsche Telekom, and China Mobile mandate in-line process data sharing rather than batch certificate review, with qualification timelines extending eight to fourteen months for multi-jurisdiction certification. India's PLI scheme for telecom equipment is attracting lens module assembly investments serving domestic 5G manufacturers.
- Electronics Manufacturers:Datacom transceiver and consumer device OEMs drive plastic collimator volumes through high-velocity procurement with compressed lead times.
- Research Institutions:National laboratories in the United States and Netherlands source polarization-maintaining collimator assemblies for quantum key distribution and entangled photon source experiments.
- Healthcare Providers:Hospital systems and diagnostic chains specify fiber-coupled surgical and imaging systems requiring sterilization-compatible lens materials.
Electronics manufacturers generate the highest shipment volumes; research institutions are expanding procurement fastest as quantum and advanced sensing programs scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the highest concentration of fiber optic collimating lens assembly operations, with the Yangtze River Delta and Greater Boston forming secondary precision manufacturing clusters. Regulatory divergence across major economies is fragmentating qualification protocols and reshaping supplier geographic footprints.
United States
Verizon and other carriers are consolidating qualified supplier bases for fiber-to-the-home rollouts under FCC broadband infrastructure subsidy programs that mandate domestic content thresholds. The FCC shapes procurement timelines through funded deployment mandates. Greater Boston hosts precision polishing and metrology equipment suppliers serving telecom and research-grade lens manufacturers.
China
MIIT GB standards for optical component reliability are accelerating domestic qualification of precision collimating assemblies for 5G base station fiber links. China's MIIT imposes certification requirements that foreign suppliers must satisfy for 5G equipment qualification. The Yangtze River Delta cluster hosts the densest concentration of lens module assembly investments serving domestic telecom equipment manufacturers.
Germany
ECHA REACH enforcement against lead-oxide glass formulations is redirecting R&D budgets toward crown glass alternatives with equivalent refractive indices for long-haul telecommunications. ECHA substance restrictions constrain traditional high-index glass chemistries. Jena hosts equipment suppliers installing freeform surface metrology platforms for telecom lens manufacturers.
Japan
Synthetic fused silica precursor supply concentrates among chemical conglomerates, creating input cost volatility for UV-grade lens manufacturers serving high-power fiber laser and semiconductor applications. METI industrial policy supports domestic materials science capabilities in optical substrates. The Osaka-Kobe corridor maintains specialized polishing and coating operations for telecom-grade components.
India
The country's production-linked incentive scheme for telecom equipment is attracting lens module assembly investments serving domestic 5G equipment manufacturers. TRAI spectrum allocation policies are accelerating fiber infrastructure deployment timelines. Maharashtra and Gujarat host emerging precision optics assembly operations targeting export markets.
Fiber Optic Collimating Lens Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered supply positions. The vendor base organizes around three strategic archetypes: vertically integrated crystal growers controlling upstream material supply, precision optics specialists with captive metrology capabilities, and contract manufacturers serving high-volume telecom procurement. Consolidation pressures are intensifying as carriers reduce qualified suppliers per region from twelve to four vendors. Dominant competitive moves include deterministic polishing technology licensing and regional distribution hub expansion.
Among Germany-based precision optics houses, AMS Technologies AG exemplifies the vertically integrated archetype with upstream material control. Thorlabs Inc and Edmund Optics occupy positions on the research-grade and distribution-optimized vectors respectively, with the former representing captive metrology capabilities and the latter anchoring multi-regional logistics networks. Coherent sits within the high-power laser specialization tier, reflecting crystal growth and polishing integration for fiber laser systems.
| Leading Market Players |
|---|
| AMS Technologies AG |
| IPG Photonics Corporation |
| Coherent |
| Thorlabs Inc |
| Edmund Optics |
| Fabrinet |
| Gooch & Housego |
| OZ Optics Ltd |
| LightPath Technologies |
| Others |
Supply & Pricing Matrix
Sub-micron surface figure tolerance certification divides the market into qualified telecom suppliers and commodity-grade assemblers, with this bifurcation creating divergent pricing power and procurement structures across the supply base. Premium aspheric collimators command sustained margins through multi-year carrier agreements, while plastic lens manufacturers compete on volume throughput for consumer electronics procurement.
Pricing Analysis
Wavefront error performance at 1550 nanometers anchors value-based pricing, with lambda-over-four specifications sustaining premium positioning against lambda-over-ten alternatives. Three-tier pricing structure across premium, standard, and economy levels separates qualified telecom vendors from datacom specialists and consumer-grade molders. Cost compression in plastic collimators is intensifying because Shenzhen-based transceiver manufacturers are consolidating molded lens suppliers below ten gigabits per second. Electronics manufacturers exhibit the highest price sensitivity, while research institutions prioritize specification flexibility over unit economics.
Supply Chain Analysis
Synthetic fused silica precursor supply rests on Japanese chemical conglomerates, creating concentrated dependency for UV-grade and high-power lens manufacturers. Raw material sourcing draws from Japan, China, and Germany for optical substrates, precision polishing equipment, and metrology systems respectively. Single-source vulnerability in interferometric surface measurement equipment constrains capacity expansion for aspheric polishers. Distribution runs through regional hubs in Greater Boston, the Yangtze River Delta, and Jena serving telecom carriers, datacom OEMs, and research institutions respectively.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interferometric metrology equipment lead times constitute the binding capacity constraint, propping pricing for qualified suppliers while excluding marginal entrants from telecom procurement pools.
For Market Incumbents: Anchor market position through captive control over upstream synthetic fused silica supply and deterministic polishing technology licensing to tier-two assemblers. Plastic substitution in datacom transceivers threatens volume positioning below ten gigabits per second, requiring certification investment in MIIT GB standards for 5G equipment qualification to defend telecom margins.
For New Entrants and Emerging Players: Launch via contract manufacturing partnerships serving India's PLI scheme for telecom equipment, leveraging domestic assembly cost structures against established Chinese suppliers. Medical imaging in Germany and Switzerland offers the most penetrable white space, with fiber-coupled OCT systems requiring sub-lambda wavefront correction creating specification barriers for incumbent commodity producers.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated precision optics specialists given REACH material substitution mandates accelerating R&D consolidation. Long-term viability favors archetypes controlling captive crystal growth and polishing operations for high-power fiber laser systems. Ion-beam sputtering technician wage inflation in Shenzhen and Boston metro clusters signals margin compression inflection for coaters lacking automation.
| Strategic Initiative | Industry Significance |
|---|---|
| Deterministic Polishing Technology Licensing | Equipment suppliers in Rochester and Jena compress final inspection from hours to minutes per optic. |
| REACH-Compliant Crown Glass Formulation | German and French manufacturers redirect R&D budgets away from lead-oxide glass alternatives. |
| Active Alignment Automation Deployment | Telecom carriers mandate in-line process data sharing rather than batch certificate review. |
| Regional Distribution Hub Expansion | Edmund Optics anchors multi-regional logistics networks across North America, Europe, and Asia. |
| Quartz Collimator Subassembly Integration | Automotive LiDAR suppliers specify 1550-nanometer modules for long-range detection applications. |
Research Methodology
Trade databases, customs records, and SEC filings formed the secondary backbone, supplemented by primary interviews with telecom procurement managers, precision optics plant engineers, metrology equipment suppliers, and ECHA regulatory affairs specialists. Bottom-up triangulation across supplier shipment data and top-down validation against carrier deployment announcements anchored volume estimates. Primary fieldwork captured process data sharing requirements and qualification timeline compression across multi-jurisdiction certification protocols.
Historical trendline analysis established baseline growth patterns across the projection horizon, with segmentation modeling incorporating lens type, material substrate, application vertical, and end-user procurement structure. CAGRs were derived through regression analysis against carrier capex cycles and 5G backhaul deployment trajectories. Forecast inputs included MIIT GB certification timelines, FCC broadband subsidy program disbursement schedules, and ECHA substance restriction phase-in dates.
Regulatory enforcement variance, raw material supply disruption, and polymer substitution acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding carrier supplier consolidation rates and deterministic polishing technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Europe Optical Imaging Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Electro Optical System Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Optical Amplifier Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Optical Transceiver Market
Optical Components
Optical Sensor Market
Optical Components
Optical Encoder Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Photointerrupter Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market
Optical Components
Ring Panel Filters Market
Optical Components
Global Optical Imaging System Market