
 North America Sensor Market | 2026-2036
North America Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sensor Market Outlook
ISO 26262 functional safety certification is bifurcating the supplier base into qualified automotive-tier vendors and general-purpose component makers. Honeywell International, Inc. leverages its aerospace heritage to dominate high-reliability pressure and temperature sensing for industrial and transportation applications. Analog Devices, Inc. anchors its position through deep MEMS fabrication expertise and signal-conditioning integration that sustains premium positioning in precision measurement segments.
A sensor is a transducer device that detects physical, chemical, or biological stimuli and converts them into measurable electrical signals, typically operating across parameters such as sensitivity measured in mV/V per unit input, response time in milliseconds, and operating temperature ranges from -40°C to +150°C for industrial grades. Its primary purpose is to enable real-time monitoring, feedback control, and data acquisition across automated systems. Pressure sensors command the largest product-type revenue pool due to pervasive deployment in automotive, HVAC, and process industries, while image sensors extract the fastest expansion from machine vision and autonomous navigation demand. MEMS technology leads unit volume by enabling miniaturized, low-cost batch fabrication of accelerometers, gyroscopes, and microphones for consumer and automotive end users.
The U.S. National Highway Traffic Safety Administration enforces FMVSS performance criteria that dictate sensor reliability thresholds for passenger vehicles, while FDA device regulations in healthcare constrain biocompatibility and accuracy standards for wearable and implantable sensors. Canada's Standards Association and Mexico's national metrology body add compliance layers for cross-border equipment certification. Stakeholders must monitor how EPA emissions rules and emerging state-level autonomous vehicle statutes in California and Arizona reshape sensor specification requirements across the value chain.
Market Dynamics
The North America sensor market is undergoing a structural reconfiguration as ISO 26262 functional safety certification bifurcates suppliers into qualified automotive-tier vendors and general-purpose component makers, compressing margins for non-certified producers while locking in premium positions for qualified suppliers.
Growth Catalysts
- Electric powertrain expansion:Automotive OEMs in Michigan and Ohio are accelerating sensor procurement for battery management systems and motor control, creating sustained demand for high-temperature pressure and current sensors.
- FMVSS automated vehicle guidance:NHTSA performance criteria are tightening reliability thresholds for passenger vehicle sensors, mandating redundant sensing architectures that expand unit volumes per vehicle platform.
- MEMS fabrication scaling:Arizona and Texas fabs are anchoring batch production of miniaturized accelerometers and gyroscopes, reducing unit costs for consumer and automotive end users.
Market Restraints
- Automotive-grade silicon wafer supply concentration:Specialty substrates for high-temperature sensor operation face supply bottlenecks concentrated among a limited base of North American foundry partners.
- CMVSS compliance friction:Canada's updates to safety standards create cross-border certification complexity for suppliers serving integrated U.S.-Canada automotive supply chains.
- Optical sensor input cost volatility:Rare earth elements and precision glass substrates used in lidar and image sensors experience price swings that compress margin predictability.
Strategic Opportunities
- Mexico manufacturing integration:Underpenetrated sensor assembly and test capacity in Baja California and Chihuahua offers cost-advantaged production proximity to U.S. automotive clusters.
- EPA emissions monitoring mandates:Industrial sensor deployment for continuous emissions monitoring at power generation and chemical processing facilities is expanding under tightening environmental enforcement.
- Silicon photonics convergence:Integration of optical and electronic sensing on single chips is opening new application spaces in medical diagnostics and telecommunications infrastructure.
Industry Challenges
- ISO 26262 certification timeline compression:The 18-24 month qualification cycle for automotive functional safety is creating bottlenecks for suppliers racing to secure OEM platform wins.
- Legacy industrial protocol integration:Fieldbus and 4-20mA interface requirements in process industries are complicating the deployment of digital-native MEMS and wireless sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sensor Market |
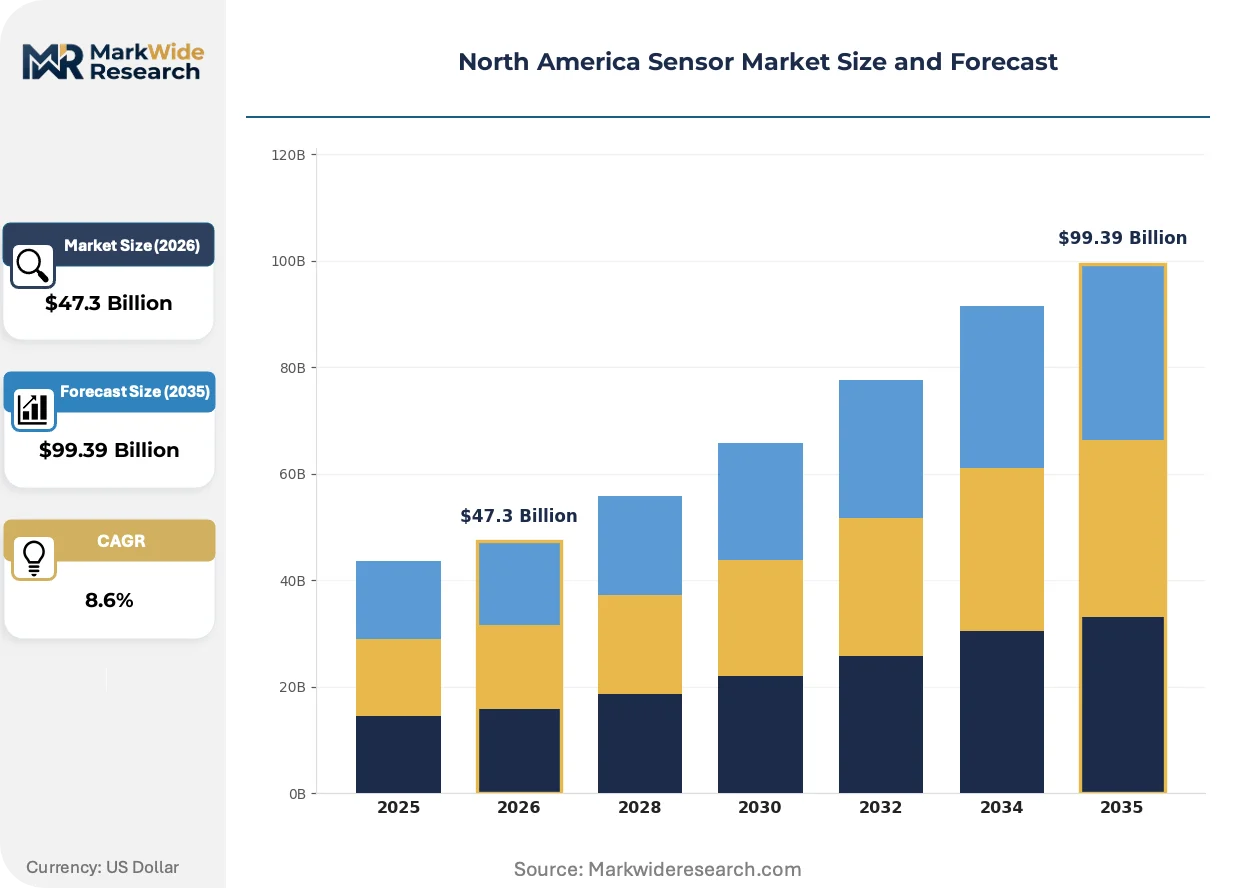
| Market Size in 2026 | $47.3 Billion |
| Market Size in 2035 | $99.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Proximity Sensors, Pressure Sensors, Image Sensors Technology: Analog, Digital, MEMS, Optical End User: Automotive, Healthcare, Industrial Automation, Consumer Electronics Application: Environmental Monitoring, Building Automation, Home Automation, Safety Systems |
| Companies Covered | Honeywell International, Inc., Analog Devices, Inc., Robert Bosch GmbH, Infineon Technologies AG, STMicroelectronics, Continental AG, TE Connectivity, NXP Semiconductors, Banner Engineering Corp., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sensor Market Strategic Shifts
Sensor architecture across North America is pivoting from discrete component supply toward integrated sensing modules that embed signal conditioning, edge processing, and connectivity, compressing the traditional value chain and reshaping supplier relationships.
Edge AI inference at the sensor node is fragmenting the traditional signal processing chain. Automotive ADAS platforms in Arizona and Michigan are deploying accelerometers and image sensors with on-chip neural network accelerators that reduce central processor load. This capability is compressing the market for standalone microcontroller-based sensor hubs.
Canada's CMVSS updates and NHTSA automated vehicle guidance are converging toward harmonized reliability testing protocols. Tier-1 suppliers are redesigning pressure and temperature sensors to meet dual-jurisdiction requirements from the outset. The industrial segment faces the steepest compliance cost increases as legacy product lines require redesign.
Specification-driven procurement is consolidating buyer power among automotive OEMs and cloud infrastructure operators. Long-term supply agreements with volume commitments are displacing spot-market purchasing for MEMS and optical sensors. Texas and Arizona data center clusters exhibit the most concentrated demand for environmental and power monitoring sensors.
North America Sensor Market Segmentation
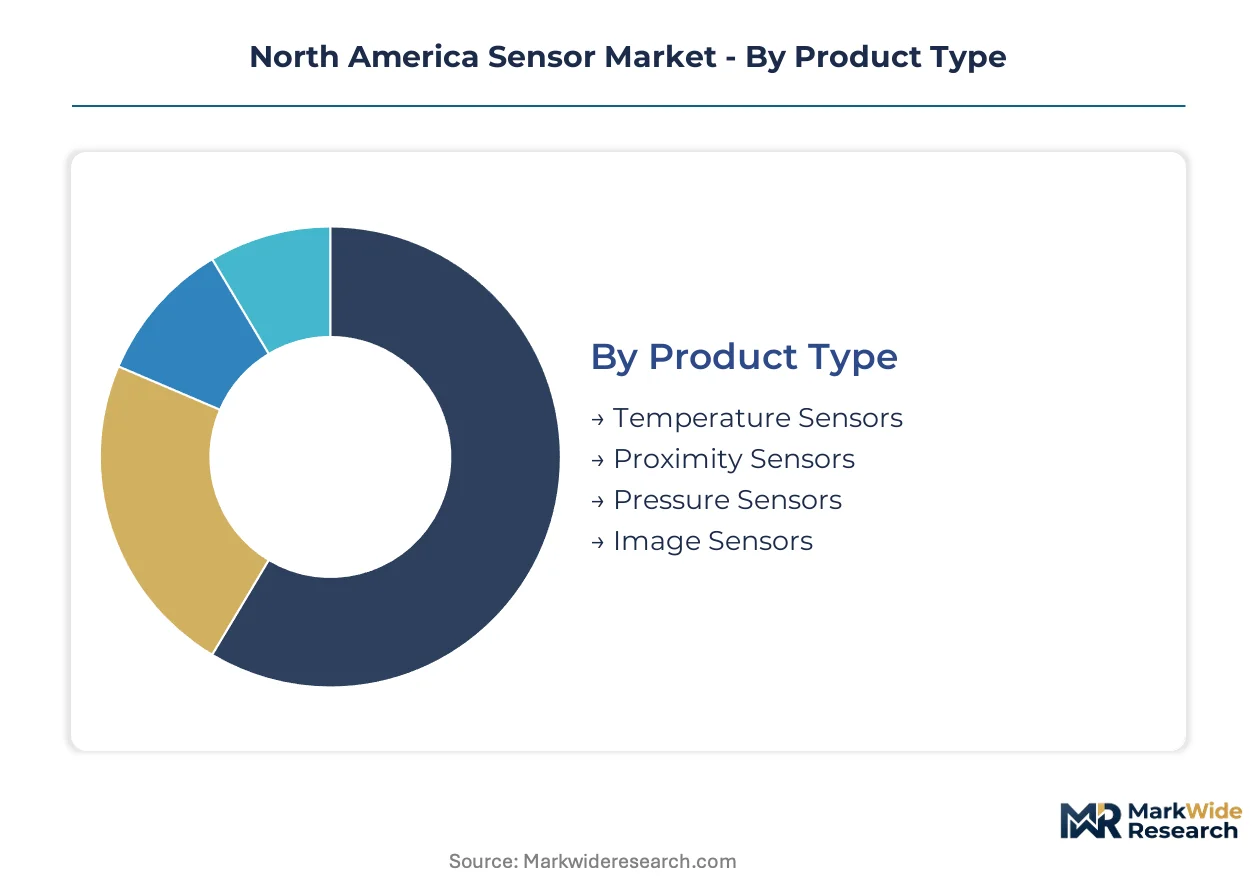
Sensor procurement across North America flows through distinct channel configurations that vary by technical complexity and certification requirements. Understanding these pathways reveals where margin pools concentrate and which segments command strategic attention from suppliers and distributors.
Product Type:
Pressure sensors and image sensors move through authorized automotive-tier distribution channels requiring ISO 26262 documentation, while temperature and proximity variants flow more freely through industrial distributors and direct OEM contracts.
- Pressure Sensors:Piezoresistive and capacitive transducers measure fluid and gas pressure across ranges from vacuum to 10,000 psi with millisecond response times. Michigan and Ohio automotive OEMs anchor demand for high-temperature variants in battery thermal management and brake systems, with NHTSA FMVSS reliability mandates forcing redundant sensor architectures per vehicle platform.
- Image Sensors:CMOS and CCD arrays convert optical signals into digital data with resolutions spanning VGA to 8K and frame rates exceeding 120 fps. Arizona and Texas machine vision clusters and autonomous vehicle testbeds concentrate demand, driven by lidar fusion requirements and ADAS platform proliferation.
- Temperature Sensors:Thermocouples, RTDs, and thermistors span -200°C to +1750°C measurement ranges with varying accuracy grades.
- Proximity Sensors:Inductive, capacitive, and ultrasonic variants detect object presence without physical contact in industrial and consumer applications.
Pressure sensors dominate installed base across automotive and process industries. Image sensors are where expansion concentrates.
Technology:
Cost tiering separates these segments sharply: MEMS and analog technologies compete on unit economics at high volumes, while optical and digital variants capture premium positioning through performance differentiation.
- MEMS:Micro-electromechanical systems integrate mechanical elements, sensors, actuators, and electronics on silicon substrates through batch fabrication. Arizona and Texas fabs anchor production, with automotive accelerometers and consumer microphones driving unit volume scale.
- Optical:Photodiodes, phototransistors, and fiber-optic transducers leverage semiconductor light detection with precision wavelength selectivity. Lidar and medical imaging applications in California and Massachusetts concentrate demand, constrained by rare earth element supply volatility.
- Analog:Continuous voltage or current output signals require external ADC conversion but offer simplicity and low latency.
- Digital:Built-in ADCs and serial interfaces enable direct microcontroller communication with reduced noise susceptibility.
MEMS technology commands highest unit shipments. Optical is climbing the fastest as silicon photonics converges sensing and communication functions.
End User:
Customer type dictates procurement patterns: automotive buyers enforce long-term supply agreements with volume commitments, while healthcare and industrial purchasers prioritize regulatory documentation and field service support.
- Automotive:OEMs and Tier-1 suppliers demand AEC-Q100 qualified devices with -40°C to +150°C temperature ratings and zero defect ppm targets. Michigan, Ohio, and Ontario assembly plants concentrate procurement, with electric powertrain expansion sustaining demand for current and position sensors.
- Industrial Automation:Factory automation and process control systems require ruggedized sensors with IP67+ sealing and 4-20mA or fieldbus connectivity. Texas and Louisiana petrochemical corridors anchor demand, driven by EPA emissions monitoring mandates and predictive maintenance adoption.
- Healthcare:FDA-regulated devices and wearables constrain biocompatibility and accuracy standards for patient monitoring and diagnostic equipment.
- Consumer Electronics:Smartphone, wearable, and smart home manufacturers prioritize miniaturization, power efficiency, and cost minimization at massive scale.
Automotive end users dominate revenue concentration. Healthcare is where margin expansion concentrates.
Application:
Geographic clustering shapes deployment patterns: environmental monitoring concentrates in EPA-enforced industrial corridors, while building and home automation spreads across residential construction hotspots.
- Safety Systems:Fire detection, gas leak monitoring, and intrusion detection sensors integrate with emergency response protocols and building management systems. California and Arizona smart city initiatives and stringent fire codes drive specification intensity, with redundant sensing architectures mandated for critical infrastructure.
- Environmental Monitoring:Air quality, water quality, and emissions sensors provide continuous regulatory compliance data. Texas and Ohio power generation and chemical processing facilities anchor demand, with EPA enforcement tightening deployment requirements.
- Building Automation:HVAC, lighting, and occupancy sensors optimize commercial building energy consumption.
- Home Automation:Smart thermostats, security cameras, and voice assistants integrate consumer-grade sensing into residential environments.
Safety systems dominate specification intensity and certification burden. Environmental monitoring is gaining share fastest under tightening regulatory enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA automated vehicle guidance and EPA emissions enforcement are reshaping procurement patterns across North America. Federal incentive programs for domestic semiconductor fabrication are accelerating fab construction in the U.S. Southwest. Cross-border automotive supply chains between Michigan, Ontario, and northern Mexico are tightening certification requirements for tier-1 suppliers.
United States
Arizona and Texas fabs anchor MEMS and optical sensor production for automotive and consumer applications. NHTSA FMVSS reliability mandates are forcing redundant sensor architectures per vehicle platform. Michigan and Ohio OEMs are expanding electric powertrain sensor procurement for battery thermal management systems.
Canada
Transport Canada's CMVSS updates are creating cross-border certification complexity for integrated U.S.-Canada automotive supply chains. Ontario assembly plants concentrate procurement of AEC-Q100 qualified devices for Tier-1 suppliers. Toronto and Montreal clusters are emerging for industrial automation sensor distribution serving resource extraction and process industries.
Mexico
Baja California and Chihuahua offer underpenetrated sensor assembly and test capacity with cost-advantaged proximity to U.S. automotive clusters. Mexico's national metrology body adds compliance layers for cross-border equipment certification. Nuevo León and Mexico City Metro are attracting contract manufacturers serving Texas and California OEMs.
North America Sensor Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with aerospace and automotive heritage alongside specialized semiconductor fabricators with deep MEMS expertise. Market structure concentrates around qualified automotive-tier vendors holding ISO 26262 certification and general-purpose component makers facing margin compression. Two strategic archetypes dominate: integrated industrial technology conglomerates leveraging cross-sector sensing platforms, and precision semiconductor specialists commanding premium positioning through fabrication scale. Competitive moves center on capacity expansion in U.S. Southwest fab corridors and strategic partnerships securing automotive platform wins.
Among diversified industrial technology conglomerates, Honeywell International, Inc. and Analog Devices, Inc. exemplify the integrated archetype. Honeywell occupies a position leveraging aerospace heritage into high-reliability industrial and transportation applications. Analog Devices sits within the precision measurement segment through MEMS fabrication expertise and signal-conditioning integration. Robert Bosch GmbH represents the European industrial conglomerate model with established North American automotive supply relationships. These three anchors demonstrate how cross-sector platform breadth and specialized fabrication depth create divergent competitive positions in a bifurcating supplier base.
| Leading Market Players |
|---|
| Honeywell International, Inc. |
| Analog Devices, Inc. |
| Robert Bosch GmbH |
| Infineon Technologies AG |
| STMicroelectronics |
| Continental AG |
| TE Connectivity |
| NXP Semiconductors |
| Banner Engineering Corp. |
| Others |
Value Chain & Pricing Dynamics
Twenty-four-month ISO 26262 certification lead times concentrate pricing power among qualified automotive-tier suppliers while compressing margins for general-purpose component makers competing on spot-market terms. Arizona and Texas fab proximity to Michigan OEM clusters reinforces geographic cost advantages that non-certified producers cannot replicate.
Pricing Analysis
Certification level creates the primary spread between automotive-grade and industrial-tier sensor pricing. Three-tier pricing structure across AEC-Q100 qualified, ISO-compliant industrial, and uncertified commercial grades stratifies the market. Cost compression in commercial-grade MEMS accelerometers is intensifying because Arizona fab capacity expansions are flooding consumer electronics channels. Automotive OEMs exhibit lowest price sensitivity due to zero-defect ppm requirements and long-term supply agreement structures.
Supply Chain Analysis
Strait of Malacca transit routes for rare earth elements and precision glass substrates expose optical sensor production to logistics chokepoint risks. Taiwan, South Korea, and the United States anchor semiconductor wafer supply for MEMS fabrication. Specialty silicon-on-insulator substrates, rare earth phosphors, and hermetic packaging ceramics constitute critical input dependencies. Tariff exposure on Chinese-processed rare earths threatens margin stability. Distribution runs through authorized automotive-tier channels requiring ISO 26262 documentation or industrial distributors serving process automation buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric powertrain sensor penetration sits at early-cycle expansion stages as Michigan and Ohio OEMs accelerate battery management system procurement. ADAS platform proliferation sustains demand tailwinds through the projection horizon.
For Market Incumbents: Secure AEC-Q100 qualification lock-in through capacity expansion in Arizona and Texas fab corridors before 18-24 month certification timelines create bottlenecks for competitors. Defend against silicon photonics convergence threats by deepening signal-conditioning integration that sustains premium positioning in precision measurement segments.
For New Entrants and Emerging Players: Lead with Mexico assembly and test capacity in Baja California and Chihuahua to exploit underpenetrated production proximity to U.S. automotive clusters. Target EPA emissions monitoring mandates in Texas and Ohio petrochemical corridors where industrial sensor deployment is expanding under tightening enforcement. Pursue direct OEM contracting bypassing established distribution channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core sensing divisions facing margin compression from ISO 26262 bifurcation. Five-to-ten year viability hinges on MEMS fabrication scale and automotive platform win concentration. Watch NHTSA automated vehicle guidance evolution as inflection indicator for redundant sensor architecture demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Certification Investment | Locks in automotive-tier supplier status and excludes general-purpose competitors from Michigan OEM procurement. |
| Arizona-Texas Fab Capacity Expansion | Captures federal semiconductor incentive programs and anchors MEMS production for electric powertrain demand. |
| Mexico Manufacturing Integration | Exploits cost-advantaged assembly proximity to U.S. automotive clusters in Michigan and Ohio. |
| Silicon Photonics Convergence R&D | Opens medical diagnostics and telecommunications application spaces beyond traditional sensing markets. |
| Long-term Automotive Supply Agreements | Displaces spot-market purchasing and consolidates buyer power among OEMs and cloud infrastructure operators. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive OEM procurement directors, Tier 1 supplier platform engineers, MEMS fabrication operations managers, and industrial automation system integrators. Secondary validation drew from NHTSA FMVSS guidance documents, EPA emissions enforcement databases, SEC 10-K filings of diversified industrial conglomerates, and vehicle production data from IHS Markit. Bottom-up sensor unit demand estimates triangulated against top-down market value reconstructions.
Across the analysis window, the quantitative framework modeled volume and value trajectories through product type, technology tier, end-user industry, and regional production cluster segmentation. CAGRs derived from historical shipment correlations with automotive production indices and semiconductor fab capacity utilization rates. Electric vehicle sensor content-per-vehicle assumptions and ADAS platform penetration curves served as primary forecast inputs.
Forecasts assume regulatory continuity in NHTSA automated vehicle guidance and EPA emissions enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as CMVSS harmonization negotiations and state-level autonomous vehicle statutes in California and Arizona evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Thermistor Temperature Sensor Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Motorcycle Sensors Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Global Industrial Temperature Controller Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Distance Measurement Sensor Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
Mexico Digital Thermometer Market