
 Series Reactor Market | 2026-2036
Series Reactor Market Size, Share, and Industry Trends Forecast 2026-2036
Series Reactor Market Insights
Direct procurement from original equipment manufacturers is tilting toward integrated solution providers across the series reactor supply chain. ABB leverages its electromagnetic design heritage to sustain premium positioning in high-voltage installations. Siemens anchors European demand through utility partnerships and grid modernization frameworks. TBEA dominates domestic sourcing in China through captive manufacturing scale and state-backed transmission projects.
A series reactor is an inductive component inserted into electrical power systems to limit fault currents, suppress harmonics, and stabilize voltage under transient conditions, typically constructed from copper or aluminum windings around laminated iron or air-core magnetic structures rated for specific inductance values and thermal endurance classes. The device serves primarily to protect downstream equipment and improve power quality in transmission and distribution networks. Fixed series reactors maintain baseline demand from legacy transmission infrastructure, while variable series reactors capture expanding margin pools as grid operators seek dynamic compensation for intermittent renewable loads. Iron-core technology leads volume shipments due to cost efficiency, though air-core designs extend into high-frequency harmonic filtering applications where magnetic saturation risks disqualify ferromagnetic alternatives.
FERC Order 1920 in the United States mandates transmission planning reforms that elevate series reactor deployment for congestion management, while China's GB/T 1094.6 standards enforce stricter loss limits and thermal performance testing for grid-connected inductive equipment. India's CEA technical standards for substation apparatus similarly tighten short-circuit withstand requirements, shaping supplier qualification protocols across South Asian procurement cycles. Stakeholders must monitor how evolving interconnection standards for inverter-based resources redefine reactor specification thresholds in procurement tenders.
Market Dynamics
Variable reactor architectures are displacing fixed inductive installations as grid operators confront voltage instability from solar and wind intermittency, forcing suppliers to reengineer electromagnetic cores for dynamic response ranges.
Growth Catalysts
- Renewable penetration mandates:State utilities across India prioritize harmonic filtering capacity in transmission upgrade corridors, expanding reactor procurement for grid stabilization.
- FERC Order 1920:United States transmission planning reforms mandate congestion management solutions that elevate series reactor deployment across interconnection queues.
- Copper winding demand:Power utilities in Southeast Asia expand investments in inductive components as aluminum alternatives face thermal performance limitations in tropical climates.
Market Restraints
- Laminated steel cost volatility:Grain-oriented electrical steel prices fluctuate with energy-intensive smelting economics, compressing margin pools for iron-core reactor fabricators.
- Supplier concentration in China:Captive manufacturing scale for state-backed transmission projects limits export availability, constraining procurement flexibility for non-domestic utilities.
- Air-core thermal dissipation limits:High-frequency harmonic filtering applications face physical constraints on continuous duty cycles, restricting addressable market scope.
Strategic Opportunities
- India's CEA technical standards:Tightened short-circuit withstand requirements for substation apparatus create qualification barriers that favor established electromagnetic design houses.
- Digital twin integration:Convergence of finite element modeling with real-time thermal monitoring enables predictive maintenance contracts for reactor fleets.
- Integrated solution provision:Direct procurement from original equipment manufacturers tilts toward bundled offerings combining reactors with capacitor banks and control systems.
Industry Challenges
- GB/T 1094.6 compliance timelines:China's stricter loss limits and thermal performance testing extend product certification cycles for grid-connected inductive equipment.
- Legacy substation integration:Retrofitting variable reactors into fixed-reactor infrastructure requires custom bushing configurations and protection relay recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Series Reactor Market |
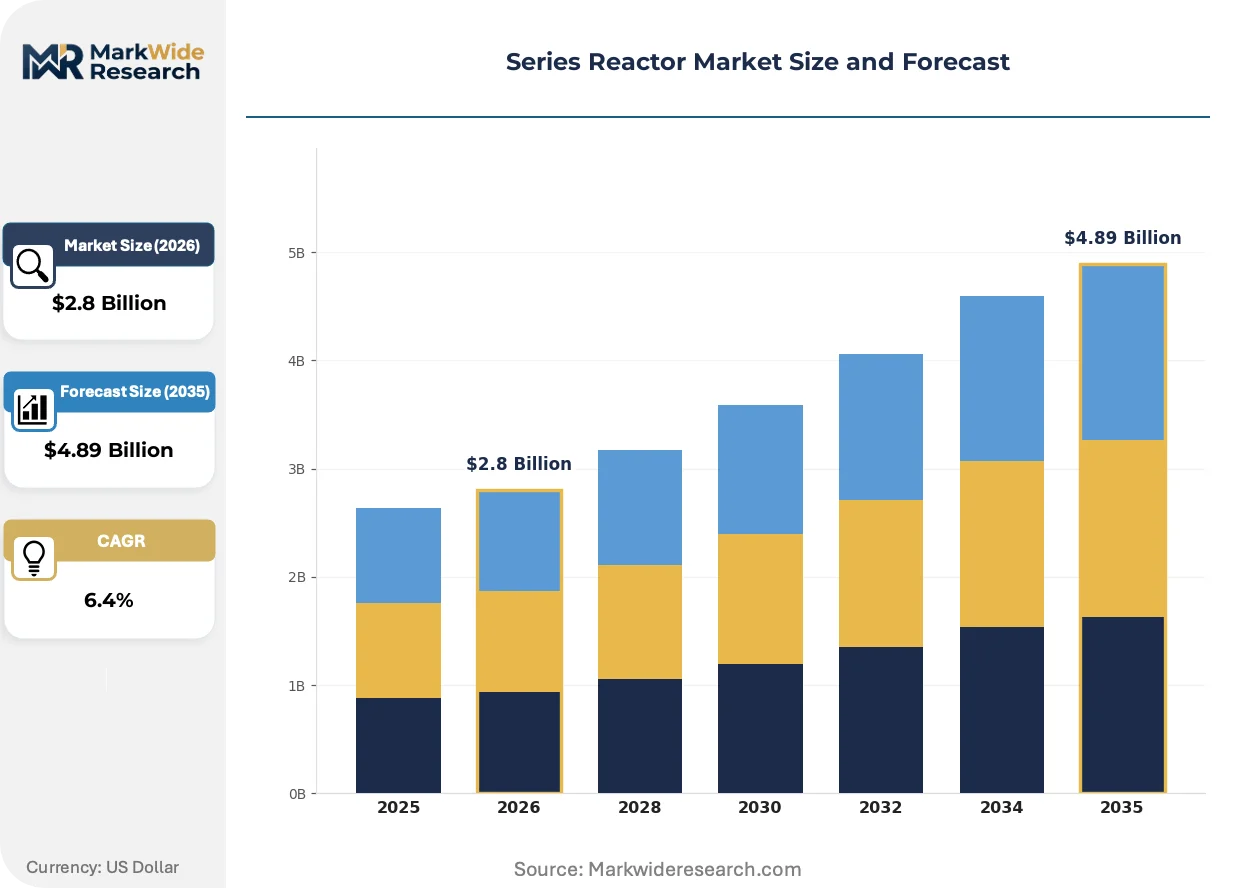
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Series Reactor, Variable Series Reactor, Smoothing Reactor, Switching Reactor End User: Power Utilities, Industrial Equipment, Renewable Energy, Transmission Networks Technology: Magnetic Technology, Air-Core Technology, Iron-Core Technology, Composite Technology Application: Voltage Regulation, Power Factor Correction, Harmonic Filtering, Load Balancing |
| Companies Covered | Changji Electric, ZhongJing, Hada Electric, Shrihans Electricals Pvt. Ltd., Ningbo Ville, ABB, Siemens, General Electric, TBEA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Series Reactor Market Trends and Innovations
Electromagnetic design methodologies are converging with power electronics control systems, collapsing traditional boundaries between passive compensation and active grid stabilization architectures.
Amorphous metal core laminations are collapsing the efficiency gap between conventional grain-oriented steel and premium nano-crystalline alternatives. European transmission operators pilot these cores in 400kV installations to meet loss reduction targets. The technology is collapsing total cost-of-ownership calculations that previously favored cheaper ferromagnetic materials.
China's GB standards for reactor efficiency are tightening product certification requirements through mandatory third-party thermal runaway testing. Domestic manufacturers must demonstrate 150% overload endurance for 60-second intervals. High-voltage product categories face the steepest compliance ramps, with provincial grid companies now excluding uncertified suppliers from tender participation.
Utility engineering departments now specify reactor procurement through framework agreements spanning 5-7 year horizons rather than spot purchasing. Siemens anchors European demand through these utility partnerships, bundling maintenance protocols with equipment supply. Germany's transmission system operators pioneered this model, which has propagated to Scandinavian and Benelux procurement offices seeking lifecycle cost predictability.
Series Reactor Market Segmentation
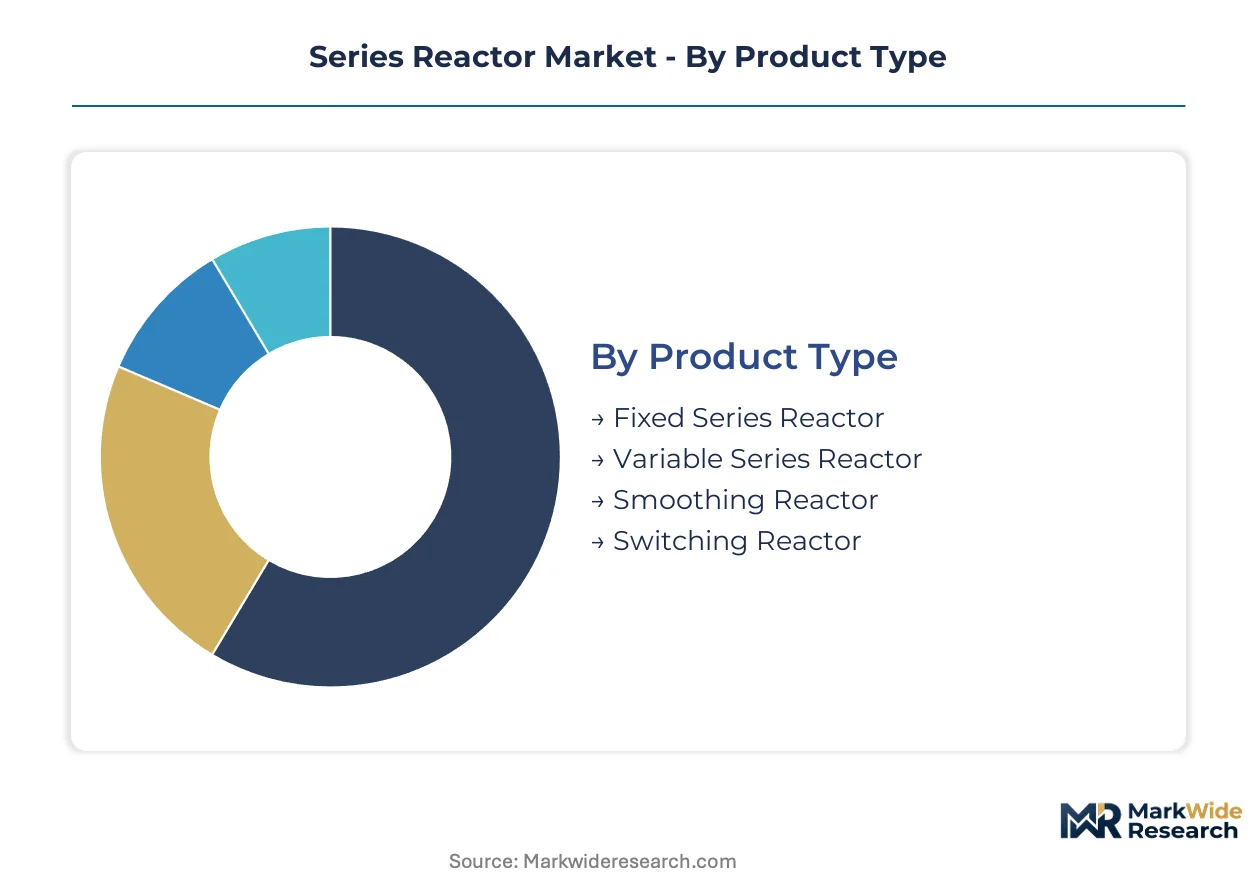
Series reactor procurement patterns diverge sharply across installation contexts, with replacement cycles stretching 25-30 years for transmission infrastructure versus 8-12 years for renewable integration projects. Understanding these temporal rhythms helps suppliers align inventory and certification investments with actual demand velocity.
Product Type:
Fixed reactors turn over slowest due to embedded base in legacy grids, while variable architectures refresh fastest as operators retrofit dynamic compensation capability.
- Fixed Series Reactor:Static inductive components with fixed tap configurations dominate installed transmission corridors across India and Southeast Asia. State utilities in Maharashtra and Tamil Nadu prioritize these units for baseline fault current limiting in 132kV and 220kV substations where load profiles remain predictable.
- Variable Series Reactor:Magnetically controllable designs with continuously adjustable inductance capture procurement momentum from solar and wind interconnection projects. Grid operators in Gujarat and Rajasthan specify these for voltage ride-through compliance where irradiance and wind speed fluctuations demand real-time reactive compensation.
- Smoothing Reactor:DC-side inductive components suppress current ripple in HVDC converter stations and industrial rectifier installations.
- Switching Reactor:Transient-rated units limit inrush currents during capacitor bank energization and breaker operations.
Fixed series reactors dominate installed base. Variable series reactors are where expansion concentrates.
End User:
Power utilities anchor volume procurement through centralized transmission planning, while renewable developers drive specification innovation at the grid edge.
- Power Utilities:State-owned transmission companies in India and provincial grid operators in China execute bulk procurement through 5-7 year framework agreements. These customers specify iron-core designs for 400kV backbone networks and enforce CEA and GB/T 1094.6 compliance through mandatory third-party testing protocols.
- Renewable Energy:Solar park developers and wind farm operators demand compact, air-core harmonic filtering solutions for inverter-dominated generation profiles. Projects in Karnataka and Madhya Pradesh specify these for IEEE 519 compliance where power electronic conversion introduces high-frequency distortion.
- Industrial Equipment:Steel mills, cement plants, and chemical facilities procure medium-voltage units for motor starting and arc furnace flicker mitigation.
- Transmission Networks:Independent system operators and regional transmission organizations acquire congestion management assets under FERC-jurisdictional planning processes.
Power utilities command procurement volume. Renewable energy is climbing the fastest.
Technology:
Iron-core fabrication achieves lowest unit cost at scale, while air-core construction commands premium positioning where magnetic saturation risks disqualify ferromagnetic alternatives.
- Iron-Core Technology:Laminated grain-oriented electrical steel wound with copper or aluminum conductors delivers cost efficiency for 50/60Hz fundamental frequency applications. Manufacturers in China leverage captive steel supply and automated winding lines to serve domestic state-backed transmission projects at price points air-core alternatives cannot match.
- Air-Core Technology:Self-supporting helical winding structures eliminate core losses and magnetic saturation constraints for high-frequency harmonic filtering. European TSOs specify these for 400kV installations where amorphous metal core laminations meet loss reduction targets.
- Magnetic Technology:Saturable reactor designs with DC bias control enable dynamic inductance variation for specialized compensation schemes.
- Composite Technology:Hybrid constructions combining ferromagnetic and air-core elements optimize thermal and electromagnetic performance for niche medium-frequency applications.
Iron-core technology dominates shipment volume. Air-core technology is gaining share fastest in premium filtering segments.
Application:
Voltage regulation commands baseline demand across all grid voltage classes, while harmonic filtering expands most quickly alongside inverter-based resource penetration.
- Voltage Regulation:Reactive power absorption and generation to maintain bus voltage within statutory limits represents the foundational use case. Indian state utilities deploy series reactors alongside shunt capacitors for voltage profile management in radial distribution feeders extending into agricultural load centers.
- Harmonic Filtering:Tuned and broadband inductive branches isolate distortion from power electronic loads and distributed generation inverters. Installation rates accelerate in Tamil Nadu and Gujarat where solar penetration exceeds 15% of instantaneous generation and IEEE 519 enforcement tightens.
- Power Factor Correction:Inductive elements balance capacitive reactive injection to maintain displacement power factor near unity.
- Load Balancing:Phase-current equalization in unbalanced distribution networks and railway traction supply systems.
Voltage regulation anchors functional demand. Harmonic filtering is where specification innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 1920 mandates transmission planning reforms across the United States, elevating series reactor deployment for congestion management while China's GB/T 1094.6 standards enforce stricter loss limits for grid-connected inductive equipment worldwide.
United States
Independent system operators procure congestion management assets under FERC-jurisdictional planning processes. The Federal Energy Regulatory Commission mandates transmission planning reforms that elevate series reactor deployment across interconnection queues. ERCOT and PJM territories in Texas and the Mid-Atlantic concentrate procurement for renewable integration projects.
China
Provincial grid operators execute bulk procurement through state-backed transmission projects under tightening GB standards. The GB/T 1094.6 standard enforces stricter loss limits and thermal performance testing for grid-connected inductive equipment. Yangtze River Delta manufacturing clusters supply captive production scale for domestic infrastructure buildouts.
India
State utilities prioritize harmonic filtering capacity in transmission upgrade corridors across Maharashtra and Tamil Nadu. The Central Electricity Authority technical standards tighten short-circuit withstand requirements for substation apparatus. Gujarat and Rajasthan grid operators specify variable reactors for voltage ride-through compliance where solar and wind fluctuations demand real-time reactive compensation.
Germany
Transmission system operators pilot amorphous metal core laminations in 400kV installations to meet loss reduction targets. The EU Green Deal framework accelerates grid modernization investments across interconnected networks. Bavaria and Baden-Württemberg industrial zones anchor European demand through utility partnerships bundling maintenance protocols with equipment supply.
Japan
Power utilities expand grid stabilization investments as renewable penetration rises across islanded transmission networks. METI oversees technical standards for substation apparatus integration with inverter-based resources. Kanto and Kansai metropolitan corridors concentrate demand for harmonic filtering solutions where power electronic conversion introduces high-frequency distortion.
Series Reactor Market Competitive Landscape
Integrated solution providers and specialized electromagnetic design houses split the market along capability lines. The vendor base organizes into three strategic archetypes: captive manufacturers serving state-backed transmission programs, premium-tier design houses leveraging electromagnetic heritage, and regional fabricators competing on cost-adjusted delivery timelines. Consolidation pressures favor backward integration into core material supply and framework agreements spanning 5-7 year procurement horizons.
Among China-based fabricators, Changji Electric and TBEA occupy positions within the captive manufacturing tier serving domestic state-backed transmission projects. Siemens anchors European demand through utility partnerships and grid modernization frameworks. ABB exemplifies the premium-tier electromagnetic design house leveraging heritage positioning in high-voltage installations.
| Leading Market Players |
|---|
| Changji Electric |
| ZhongJing |
| Hada Electric |
| Shrihans Electricals Pvt. Ltd. |
| Ningbo Ville |
| ABB |
| Siemens |
| General Electric |
| TBEA |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Rotterdam container freight corridors transmit cost volatility from grain-oriented electrical steel mills directly into delivered pricing for European utilities, compressing margin pools for iron-core fabricators while amplifying price differentiation between captive Chinese supply and premium-tier electromagnetic design houses.
Pricing Analysis
Chinese-sourced reactors trade at 30-40% discounts to European-manufactured equivalents before freight and certification add-ons. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal performance class and third-party testing pedigree. Cost compression in the economy tier intensifies as provincial grid companies consolidate procurement through framework agreements. Renewable developers exhibit highest price sensitivity, while transmission system operators prioritize lifecycle cost predictability over upfront capital outlay.
Supply Chain Analysis
Export-control regimes restricting amorphous metal core technology limit technology transfer from Japanese and German specialty steel producers to emerging fabricators. Manufacturing gravity centers on China, India, and Germany for laminated core winding, with copper conductor supply anchored in Chile and Zambia mining operations. Single-source vulnerability concentrates in grain-oriented electrical steel from Yangtze River Delta mills. Distribution runs through original equipment manufacturer direct contracts for utilities and EPC contractor channels for renewable integration projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from diverging procurement rhythms between 25-30 year transmission replacement cycles and 8-12 year renewable refresh schedules, creating niche positioning for specialized harmonic filtering suppliers.
For Market Incumbents: Harden electromagnetic design heritage through captive amorphous metal core supply agreements, insulating premium positioning from commodity steel volatility. Deepen backward integration into copper winding facilities in India to defend margin structure against aluminum substitution pressure. Prioritize CEA and GB/T 1094.6 certification maintenance as qualification barriers rise.
For New Entrants and Emerging Players: Establish a beachhead in air-core harmonic filtering for solar park developers in Gujarat and Rajasthan, where IEEE 519 compliance mandates outstrip incumbent capacity. Target digital twin integration services for reactor fleet predictive maintenance as utilities shift from spot purchasing to lifecycle contracts. Lead with finite element modeling capabilities rather than manufacturing scale.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized electromagnetic component divisions and stranded utility relationships. Long-term viability hinges on exposure to renewable interconnection growth rather than legacy transmission replacement. Monitor FERC Order 1920 implementation velocity as congestion management procurement inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Metal Core Adoption | European TSOs pilot 400kV installations to meet EU Green Deal loss reduction targets. |
| Digital Twin Integration | Convergence of finite element modeling with thermal monitoring enables predictive maintenance contracts. |
| Framework Agreement Expansion | Siemens anchors European demand through 5-7 year utility partnerships bundling maintenance protocols. |
| CEA Certification Investment | Tightened short-circuit withstand requirements favor established electromagnetic design houses in India. |
| Variable Reactor Retrofit Programs | Grid operators in Gujarat and Rajasthan specify dynamic compensation for voltage ride-through compliance. |
Research Methodology
A standing panel of utility planning officers, EPC contractor procurement leads, electromagnetic design engineers, and aftermarket service heads provided ongoing calibration against secondary validation from FERC filings, CEA technical standards documentation, GB/T certification registries, and customs trade data for grain-oriented electrical steel. Bottom-up shipment data from reactor fabricators triangulated with top-down transmission investment forecasts from regional grid operators.
Scenario-bracketing framed projections across renewable penetration trajectories and raw material cost bands throughout the forecast period. Segmentation dimensions modeled include product architecture, end-user procurement type, core technology, and application function. CAGRs derived from regression analysis of historical shipment correlations with transmission capital expenditure cycles and inverter-based resource interconnection queues.
Stress conditions across copper price volatility, laminated steel supply disruptions, and regulatory certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Material shifts in FERC Order 1920 implementation scope or GB standard revision timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Shunt Reactor Market
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
DC-DC Converter Market
Power Systems
AC Voltage Transducer Market
Power Systems
Asia-Pacific IGBT and Super Junction MOSFET Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
HVDC Converters Market
Power Systems
EV Power Module Market
Power Systems
Converter Modules Market
Power Systems
Thyristor Market
Power Systems
Global Synchronous Motor Market
Power Systems
Voltage Regulators Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
Global Battery Thermal Management System Market
Power Systems
Asia-Pacific Uninterruptible Power Supply (UPS) Market
Power Systems
Battery Pack High-Voltage Wiring System Components Market