
 Optical Position Sensors Market | 2026-2036
Optical Position Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Position Sensors Market Intelligence
REACH compliance is decoupling component sourcing from legacy Asian supply chains for European optical position sensor vendors. Hamamatsu Photonics K.K. leverages its vertical integration in photodiode manufacturing to sustain cost advantages in high-precision displacement modules. Micro-Epsilon Messtechnik GmbH anchors its competitive position through specialized capacitive-optical hybrid designs for extreme temperature environments. Sensata Technologies Inc. competes primarily on automotive channel control, embedding sensors directly into tier-one supplier assembly programs.
Optical position sensors detect and measure linear or angular displacement using light-based detection principles, typically achieving resolutions below one micrometer through interferometric or triangulation methods. These devices convert optical signals into electrical outputs to enable closed-loop control in automated machinery, robotics, and precision manufacturing systems. Reflective sensors currently occupy the largest product category due to their adaptability in dirty industrial environments, while laser-based technology segments command premium pricing through superior accuracy in semiconductor wafer inspection. Displacement sensors represent the fastest-growing product type as machine tool builders demand nanometer-level feedback for additive manufacturing calibration.
FDA device traceability requirements and EU CE marking under the Machinery Directive are tightening calibration documentation standards for sensors deployed in medical and industrial equipment. Japan's METI energy efficiency benchmarks and China's GB standards for industrial automation equipment are converging on minimum accuracy specifications that favor LED and laser technologies over infrared alternatives. Stakeholders must monitor how evolving cybersecurity mandates for connected factory devices reshape sensor firmware architectures and certification pathways.
Market Dynamics
Laser interferometry is compressing displacement measurement tolerances in semiconductor lithography and precision machine tools, forcing sensor architectures toward multi-axis optical encoders with embedded signal processing.
Growth Catalysts
- EU Green Deal energy mandates:Industrial automation retrofits across Germany, France, and Italy are mandating sensor upgrades that improve motor efficiency and reduce standby power consumption in factory equipment.
- Additive manufacturing calibration:Machine tool builders deploying metal 3D printers require nanometer-level z-axis feedback, creating pull-through demand for chromatic confocal displacement sensors in build chamber monitoring.
- China's GB standards convergence:National standardization for industrial automation equipment is elevating minimum accuracy specifications, favoring LED and laser-based position sensing over legacy infrared alternatives in eastern manufacturing provinces.
Market Restraints
- Photodiode supply concentration:Captive production of high-sensitivity avalanche photodiodes concentrates in Japanese and German component houses, exposing non-integrated sensor vendors to allocation risk during capacity crunches.
- Inductive and magnetic encoders:These substitutes capture cost-sensitive factory automation applications below 10-micron accuracy requirements, compressing addressable volume for entry-level optical products.
- REACH substance restrictions:ECHA regulatory friction on lead-containing optical glass and certain semiconductor dopants is forcing reformulation of legacy sensor designs, extending qualification timelines for European market entry.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Contract manufacturers establishing smartphone and semiconductor assembly capacity in Tamil Nadu and Karnataka represent greenfield sensor deployment with limited incumbent vendor relationships.
- Capacitive-optical hybrid architectures:Convergence of triangulation and capacitive sensing enables single-module operation across extreme temperature swings, opening aerospace engine monitoring and geothermal drilling applications previously closed to pure optical solutions.
- Cybersecurity certification pathways:IEC 62443 and national variants for connected factory devices are creating first-mover advantage for sensor vendors embedding secure boot and encrypted fieldbus interfaces ahead of mandatory compliance deadlines.
Industry Challenges
- Multi-physics simulation expertise:Design of interferometric sensors requires simultaneous optimization of thermal drift, vibration immunity, and optical path stability, creating acute talent scarcity in optomechanical engineering pools.
- ISO/IEC 17025 calibration infrastructure:Metrology laboratories capable of traceable sub-micrometer displacement certification remain limited, extending customer qualification cycles and delaying revenue recognition for high-precision product lines.
- Legacy PLC integration friction:Brownfield factory floors running proprietary fieldbus protocols demand custom gateway development, fragmenting engineering resources across one-off connectivity projects rather than scalable platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Position Sensors Market |
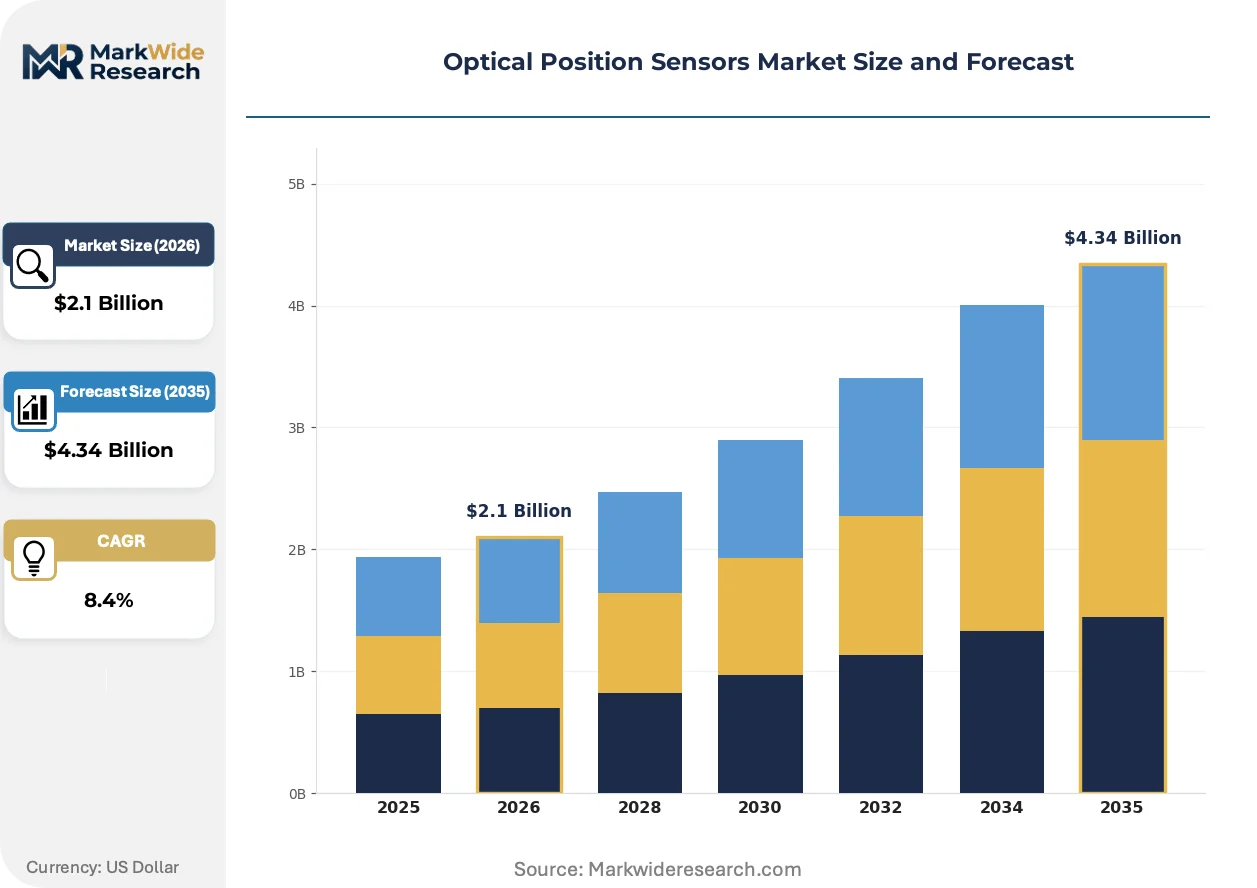
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reflective Sensors, Through-Beam Sensors, Proximity Sensors, Displacement Sensors Technology: LED, Laser, Infrared, CCD End User: Automotive, Aerospace, Robotics, Industrial Equipment Installation: Embedded, Surface-Mounted, Panel-Mounted, Modular |
| Companies Covered | Hamamatsu Photonics K.K., Micro-Epsilon Messtechnik GmbH, Opto Diode Corporation, Panasonic Holdings Corporation, Sensata Technologies Inc., ams-OSRAM AG, Keyence Corporation, Siemens AG, First Sensor AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Position Sensors Market Strategic Shifts & Innovations
Optical position sensing is bifurcating into two development tracks: commodity reflective sensors optimizing cost-per-axis in high-volume logistics, and premium interferometric systems embedding edge computing for real-time error compensation in precision manufacturing.
Chromatic confocal technology is overtaking laser triangulation in semiconductor wafer inspection applications where transparent film stacks and high-aspect-ratio features create multipath interference. Leading foundries in Taiwan and South Korea are standardizing on multi-channel confocal probes for inline metrology, compressing the market for conventional point laser sensors in sub-50nm process nodes. This displacement is accelerating vendor consolidation around specialists with captive optical design and MEMS fabrication capabilities.
Japan's METI energy efficiency benchmarks are tightening standby power requirements for industrial equipment, mandating sensor architectures that power down non-critical optical channels during idle periods. Equipment builders serving automotive and electronics assembly must redesign control loops to accommodate wake-on-motion protocols, favoring sensors with integrated wake-up comparators over discrete photodiode arrangements. The regulation is concentrating procurement among vendors offering firmware-configurable power states rather than fixed-consumption legacy designs.
Buyers in China's eastern manufacturing corridor are consolidating vendor relationships around full-stack automation suppliers capable of integrating position sensing with servo drives and motion controllers. This channel compression is marginalizing standalone sensor distributors and forcing pure-play optical specialists to embed their modules into partner servo platforms or develop direct field service capabilities. The shift is most visible in Suzhou and Shenzhen, where smart factory capital expenditure favors single-source accountability for precision motion subsystems.
Optical Position Sensors Market Segmentation
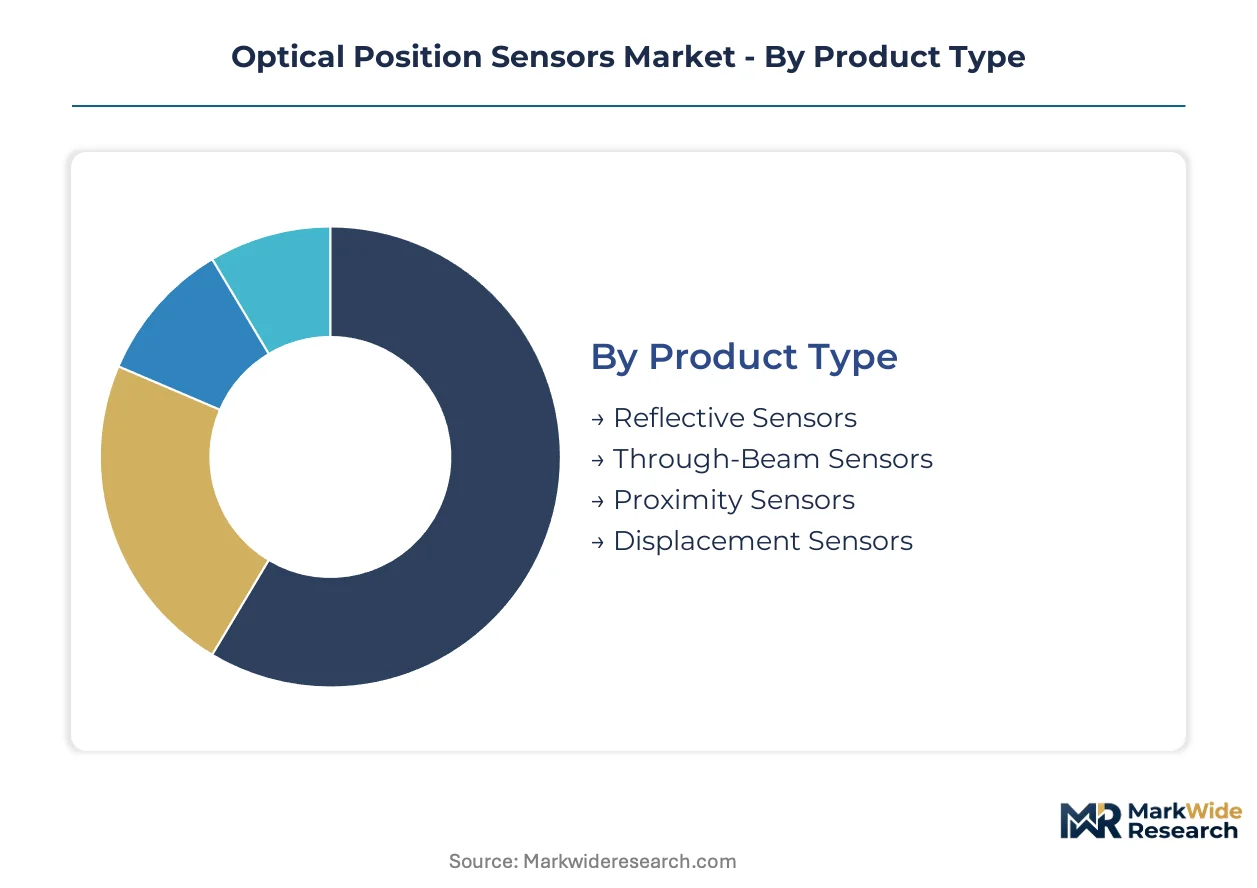
Optical position sensor architectures fragment across precision requirements, environmental tolerance, and integration depth. Buyers select configurations based on contamination exposure, measurement range, and control system compatibility rather than unit cost alone.
Product Type:
Customization intensity spans from standardized reflective modules to application-specific displacement probes engineered for nanometer resolution.
- Reflective Sensors:These devices emit and detect reflected light to determine object presence or distance without target contact. Demand concentrates in German automotive assembly lines and Chinese logistics hubs where dust tolerance and flexible mounting outweigh absolute precision requirements.
- Displacement Sensors:Interferometric and confocal variants achieve sub-micron accuracy for machine tool feedback. Machine tool builders in Japan and Taiwan deploying metal additive manufacturing systems drive procurement of chromatic confocal probes for z-axis build chamber monitoring.
- Through-Beam Sensors:Paired emitter-receiver configurations deliver reliable object detection across long sensing distances in packaging machinery.
- Proximity Sensors:Short-range detection modules dominate conveyor system applications with limited space for sensor mounting.
Leading the category by volume: Reflective Sensors. Growing fastest: Displacement Sensors.
Technology:
Cost tiers separate commodity LED emitters from premium laser sources requiring active thermal management and precision optics.
- Laser:Coherent light sources enable triangulation and interferometric methods with superior beam collimation. Semiconductor wafer inspection equipment in South Korea and Taiwan standardizes on laser-based systems for sub-50nm process node metrology.
- LED:Solid-state emitters offer lower cost and reduced power consumption for industrial automation with moderate accuracy requirements. EU Green Deal energy mandates accelerate LED adoption across French and Italian motor control retrofits seeking standby power reduction.
- Infrared:Longer wavelength operation penetrates certain contaminants but faces displacement by visible-spectrum alternatives under tightening accuracy standards.
- CCD:Charge-coupled device imagers support multi-point position sensing in vision-guided robotics applications.
Dominating procurement value: Laser. Expanding most quickly: LED.
End User:
Application maturity varies from established automotive channel programs to emerging robotics integration with unconsolidated vendor relationships.
- Industrial Equipment:Machine tools, packaging lines, and material handling systems constitute the installed base volume. German and Japanese factory automation retrofits under METI and EU efficiency benchmarks drive sensor upgrade cycles.
- Robotics:Collaborative and precision assembly robots demand multi-axis optical encoders with embedded signal processing. China's eastern manufacturing corridor concentrates smart factory capital expenditure around full-stack motion subsystems.
- Automotive:Tier-one supplier integration programs embed position sensing into powertrain and chassis assembly with long-term supply agreements.
- Aerospace:Extreme temperature and vibration specifications favor capacitive-optical hybrid architectures for engine monitoring and flight control surfaces.
Highest shipment volume: Industrial Equipment. Steepest expansion trajectory: Robotics.
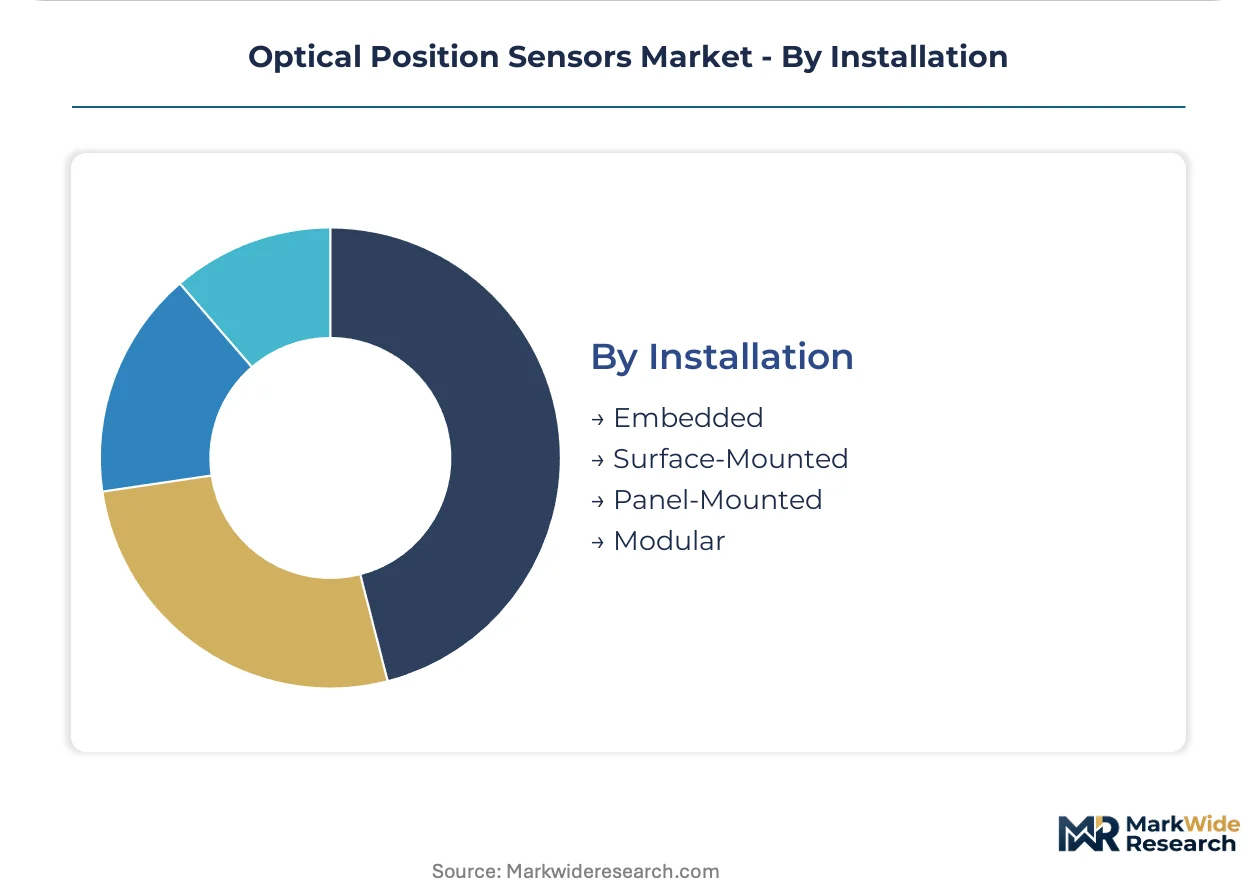
Installation:
Integration depth determines engineering resource allocation from plug-and-play modular units to custom-embedded designs with firmware co-development.
- Embedded:Sensors integrated directly into OEM equipment during original design capture lifetime supply agreements. Automotive tier-one programs in Germany and Japan favor embedded architectures for powertrain position feedback.
- Modular:Standardized mechanical and electrical interfaces enable rapid replacement without system redesign. China's smart factory deployments in Suzhou and Shenzhen prefer modular configurations to minimize maintenance downtime.
- Surface-Mounted:External attachment methods suit retrofit applications and legacy equipment upgrades with limited internal space.
- Panel-Mounted:Front-face installation provides operator visibility and manual adjustment access in machine tool operator stations.
Capturing largest unit volume: Embedded. Gaining share fastest: Modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's eastern manufacturing corridor operates as a concentrated tax-incentive zone where smart factory capital expenditure drives sensor procurement. Germany's industrial automation clusters and Japan's precision equipment bases anchor demand in mature economies. India's PLI scheme for electronics manufacturing is creating greenfield deployment opportunities with limited incumbent vendor relationships.
Germany
Machine tool builders in Bavaria and Baden-Württemberg demand nanometer-level displacement sensors for additive manufacturing calibration. EU Green Deal energy efficiency mandates under ECHA and REACH compliance frameworks accelerate sensor retrofits across automotive assembly lines. Stuttgart and Munich industrial clusters concentrate procurement of laser-based encoders for precision motion subsystems.
China
Smart factory investments in Suzhou and Shenzhen dominate capital expenditure for full-stack automation systems. GB standards for industrial automation equipment elevate minimum accuracy specifications, favoring LED and laser technologies over legacy infrared alternatives. The Yangtze River Delta manufacturing belt concentrates demand for reflective sensors in logistics and displacement probes in semiconductor equipment.
Japan
Robotics manufacturers in Nagoya and Osaka expand procurement of laser-based displacement sensors for precision assembly lines. METI energy efficiency benchmarks tighten standby power requirements, mandating sensor architectures with wake-on-motion protocols. The Chubu and Kansai industrial corridors anchor global supply of high-sensitivity avalanche photodiodes for captive sensor production.
United States
Semiconductor wafer inspection equipment in Arizona and Texas standardizes on chromatic confocal technology for sub-50nm process node metrology. FDA device traceability requirements tighten calibration documentation standards for sensors deployed in medical equipment. The Southwest semiconductor fabrication cluster drives premium pricing for interferometric systems with embedded signal processing.
India
Contract manufacturers establishing smartphone and semiconductor assembly capacity in Tamil Nadu and Karnataka represent greenfield sensor deployment. The PLI scheme for electronics manufacturing attracts first-mover vendors without established distributor relationships. Bengaluru and Chennai industrial zones concentrate demand for modular sensor configurations to minimize maintenance downtime in emerging smart factory installations.
Optical Position Sensors Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered technology segments. The market structure concentrates around three archetypes: vertically integrated photonics houses with captive component supply, specialized displacement sensor engineers with hybrid sensing architectures, and diversified industrial automation conglomerates embedding sensors into motion control platforms. Strategic moves center on M&A to acquire MEMS fabrication capabilities and capacity expansion in avalanche photodiode production.
Among Japanese precision equipment manufacturers, Hamamatsu Photonics K.K. and Keyence Corporation exemplify the vertically integrated archetype with in-house photodiode production. German specialists Micro-Epsilon Messtechnik GmbH occupy a position representing hybrid sensing convergence. Sensata Technologies Inc. anchors the automotive channel integration tier. These three named entities collectively illustrate how geographic clustering around industrial corridors shapes competitive positioning without mandating uniform strategic approaches.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| Micro-Epsilon Messtechnik GmbH |
| Opto Diode Corporation |
| Panasonic Holdings Corporation |
| Sensata Technologies Inc. |
| ams-OSRAM AG |
| Keyence Corporation |
| Siemens AG |
| First Sensor AG |
| Others |
Cost & Logistics Intelligence
Laser-LED bifurcation separates premium interferometric modules from commodity reflective sensors, with each tier commanding distinct supply chain configurations. Short-lead-time premiums for avalanche photodiode-integrated encoders coexist with spot-market discounting for standardized LED-based proximity switches, while REACH-compliant component sourcing adds qualification overhead that concentrates procurement among vendors with captive European distribution.
Pricing Analysis
Lead-time compression commands 15-40% premiums for multi-axis optical encoders with embedded signal processing, while spot inventory of reflective sensors trades at distressed levels. Three-tier pricing structure across premium interferometric, standard laser-triangulation, and economy LED-reflective levels segments buyers by calibration documentation requirements. Cost compression in entry-level reflective modules intensifies as inductive encoders capture sub-10-micron factory automation, squeezing margins for non-integrated vendors. Contract manufacturers in China's eastern corridor exhibit highest price sensitivity, whereas German machine tool builders prioritize traceable ISO/IEC 17025 certification over unit cost.
Supply Chain Analysis
Refurbishment flows for high-precision displacement probes create secondary market liquidity that caps pricing power for new equipment sales. Captive avalanche photodiode production concentrates in Japan and Germany, with assembly of finished sensors distributed across China, Mexico, and Eastern Europe. Critical inputs include GaAs photodiode substrates, precision optical glass, and MEMS fabrication capacity. Single-source vulnerability in Japanese photodiode supply exposes non-integrated vendors to allocation risk during capacity crunches. Distribution runs through tier-one automation distributors in mature markets and direct OEM relationships in emerging manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Avalanche photodiode fabrication capacity constraints prop pricing power for vertically integrated vendors, while non-integrated specialists face margin compression from component allocation risk and extended qualification timelines.
For Market Incumbents: To counter inductive encoder substitution in cost-sensitive factory automation below 10-micron accuracy, deepen backward integration into photodiode manufacturing and anchor channel control through embedded automotive tier-one programs. Prioritize capacity addition in Germany and Japan to secure REACH-compliant supply for European industrial retrofits. For New Entrants and Emerging Players: India's PLI scheme for electronics manufacturing opens a window for modular sensor deployment in Tamil Nadu and Karnataka contract manufacturing, where limited incumbent distributor relationships reduce switching costs. Target white-space in capacitive-optical hybrid architectures for aerospace engine monitoring, leveraging direct field service capabilities as differentiation against full-stack automation suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with MEMS fabrication specialists given chromatic confocal displacement sensor standardization in semiconductor wafer inspection. Long-term viability favors acquisition targets with captive optical design capabilities and established IEC 62443 cybersecurity certification pathways. Monitor avalanche photodiode utilization rates as inflection indicator for component allocation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photodiode Manufacturing | Captive supply of high-sensitivity avalanche photodiodes insulates against Japanese and German allocation crunches. |
| Cybersecurity Certification Program | IEC 62443 compliance creates first-mover advantage ahead of mandatory connected factory device mandates. |
| Capacitive-Optical Hybrid Architecture Development | Extends addressable market into aerospace engine monitoring and geothermal drilling applications. |
| Direct Field Service Capability Buildout | China's smart factory consolidation around full-stack suppliers demands single-source accountability for motion subsystems. |
| Geographic Manufacturing Footprint Expansion | India's PLI scheme attracts greenfield sensor deployment with limited incumbent vendor relationships. |
Research Approach
Document review covered regulatory filings with ECHA, METI efficiency benchmarks, and GB standardization documents, complemented by interviews with plant engineers at German automotive assembly lines, procurement leads at Japanese robotics manufacturers, OEM technical directors in China's eastern manufacturing corridor, and metrology laboratory managers. Secondary validation drew from customs trade data, SEC filings of listed automation vendors, and IEC certification registries. Bottom-up unit demand estimates triangulated against top-down industrial automation capex projections.
Historical capacity utilization patterns cross-referenced against panel input from component suppliers and equipment builders informed the analytical framework. Segmentation dimensions modeled include product type, technology tier, end-use industry, installation configuration, and regional regulatory cluster. CAGRs derived from slope-log regression of normalized adoption curves, with inputs including machine tool builder order backlogs, semiconductor wafer inspection equipment shipments, and smart factory capital expenditure indices.
Caveats apply where photodiode supply disruptions, REACH substance restriction expansions, or cybersecurity mandate acceleration could materially shift the outlook. Forecasts embed assumptions regarding GB standards convergence timelines and EU Green Deal retrofit pacing. Practitioners should monitor avalanche photodiode lead times and chromatic confocal probe adoption rates in Taiwan and South Korean foundries for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Europe Optical Imaging Market
Optical Components
ROADM WSS Component Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market
Optical Components
Europe Scintillator Market
Optical Components
Diode Laser Module Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Photointerrupter Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Spectroradiometers Market
Optical Components
Polarizer Film Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Photomask Pellicle Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
Optical Lens Edger Market