
 Multi-Junction Solar Cell Market | 2026-2036
Multi-Junction Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Junction Solar Cell Market Insights
Space-rated cell refurbishment and aftermarket qualification testing is reconfiguring margin pools away from virgin wafer supply toward lifecycle service contracts. Spectrolab leverages decades of flight heritage and captive epitaxial growth capacity to dominate GEO satellite programs. AZUR SPACE Solar Power GmbH anchors European supply security through its III-V manufacturing base in Heilbronn. Emcore Corporation specializes in radiation-tolerant designs for defense and intelligence payloads.
Multi-junction solar cells stack semiconductor layers of varying bandgaps—typically InGaP, GaAs, and Ge—to capture segmented portions of the solar spectrum, achieving conversion efficiencies above 47% under concentrated illumination for space and terrestrial power generation. The III-V product type commands premium pricing due to molecular beam epitaxy complexity and limited qualified suppliers. Aerospace application demand outpaces power generation as satellite constellation deployments accelerate, while government end users fund early-stage heterojunction technology development through defense procurement channels.
NASA's technology readiness level requirements and ESA's ECSS-E-ST-20-08C standards shape cell qualification protocols, extending development timelines but creating barriers against unproven entrants. The FAA's commercial space launch licensing framework indirectly governs power system reliability expectations for orbital payloads. Stakeholders must track how emerging ISO 24115 space sustainability standards integrate end-of-life power degradation metrics into mission design criteria.
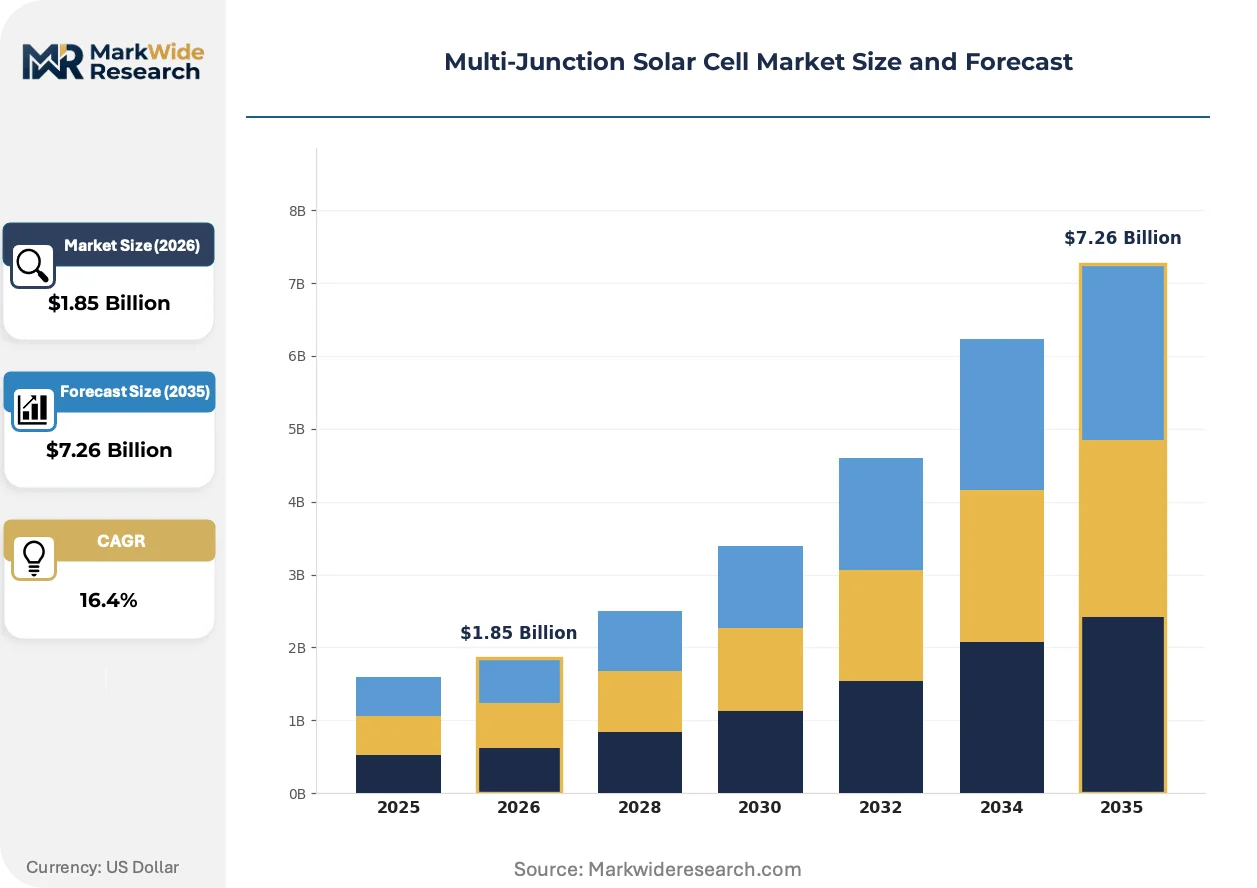
Market Dynamics
III-V epitaxial wafer supply concentration and NASA's escalating efficiency benchmarks are compressing development timelines while fragmenting procurement authority between prime contractors and national space agencies.
Growth Catalysts
- LEO Constellation Deployment:Satellite operators in the United States are procuring radiation-hardened cells for broadband constellations. Launch frequency schedules from Cape Canaveral and Vandenberg drive volume commitments.
- Concentrated Photovoltaic Research:Germany's Fraunhofer ISE and Japan's NEDO fund terrestrial CPV demonstrations using multi-junction architectures. Public-private partnerships accelerate technology transfer from space to ground applications.
- ECSS-E-ST-20-08C Qualification:ESA's standardization of cell testing protocols reduces supplier requalification costs for European primes. Harmonized requirements enable cross-border procurement within EU member states.
Market Restraints
- Germanium Substrate Pricing:Limited qualified ingot suppliers in China and Russia create input cost volatility. Ge wafer thickness specifications for space-grade cells constrain substitution options.
- Molecular Beam Epitaxy Bottleneck:MOCVD reactor availability concentrates in Heilbronn, Germany and Albuquerque, New Mexico. Equipment lead times extend 18-24 months for new capacity.
- GaAs Wafer Diameter Constraints:150mm remains the practical maximum for III-V epitaxy. Silicon solar's 300mm scale economies are structurally inaccessible to multi-junction architectures.
Strategic Opportunities
- India Space Program Expansion:ISRO's SSLV deployment schedule creates demand for domestically qualified cells. PLI scheme eligibility for space-grade semiconductor manufacturing attracts foreign joint ventures.
- ISO 24115 Integration:End-of-life power degradation metrics in emerging space sustainability standards favor vendors with predictive degradation models. Mission design criteria now embed power margin requirements.
- Perovskite Tandem Convergence:Research consortia in Switzerland and South Korea are stacking perovskite top cells on silicon bottom cells. Two-terminal architectures promise cost reduction while preserving efficiency gains.
Industry Challenges
- Radiation-Hardening Expertise Gap:Displacement damage dose modeling requires specialized nuclear engineering talent. Universities in the United States and Germany produce insufficient graduates for defense and civil space demand.
- Qualification Timeline Compression:NASA technology readiness level progression from TRL 4 to TRL 9 demands 5-7 years of flight heritage accumulation. New entrants face structural exclusion from prime contractor approved vendor lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Junction Solar Cell Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated, III-V, Organic, InGaP Application: Aerospace, Satellite, Power Generation, Research End User: Government, Commercial, Residential, Industrial Technology: Photovoltaic, Thin-Film, Heterojunction, Bifacial |
| Companies Covered | Spectrolab, AZUR SPACE Solar Power GmbH, Canadian Solar, Trina Solar, JinkoSolar Holding, SHARP CORPORATION, Umicore, Emcore Corporation, SolAero Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Junction Solar Cell Market Trends and Innovations
Digital twin integration across epitaxial growth and cell fabrication is compressing development cycles while enabling predictive qualification for mission-specific radiation environments.
Metamorphic buffer layer engineering is digitizing cell design workflows by enabling lattice-mismatched III-V combinations previously excluded from production. Satellite manufacturers in Japan and the United States are adopting these architectures for next-generation bus designs. The technology is digitizing yield optimization protocols, reducing iteration cycles from months to weeks through in-situ monitoring feedback.
REACH substance restriction reviews are scrutinizing indium and gallium supply chain due diligence requirements for space hardware placed on the European market. Industrial consequence includes mandatory conflict mineral reporting extending to III-V feedstocks. German and French primes are restructuring supplier qualification to preempt regulatory exclusion from EU-funded missions.
Long-term power purchase agreements for orbital energy services are displacing traditional equipment sale contracts. Satellite operators in the United States now procure kilowatt-hours rather than cells, transferring degradation risk to manufacturers. This model concentrates in geostationary satellite programs where 15-year mission lifetimes dominate total cost of ownership calculations.
Multi-Junction Solar Cell Market Segmentation
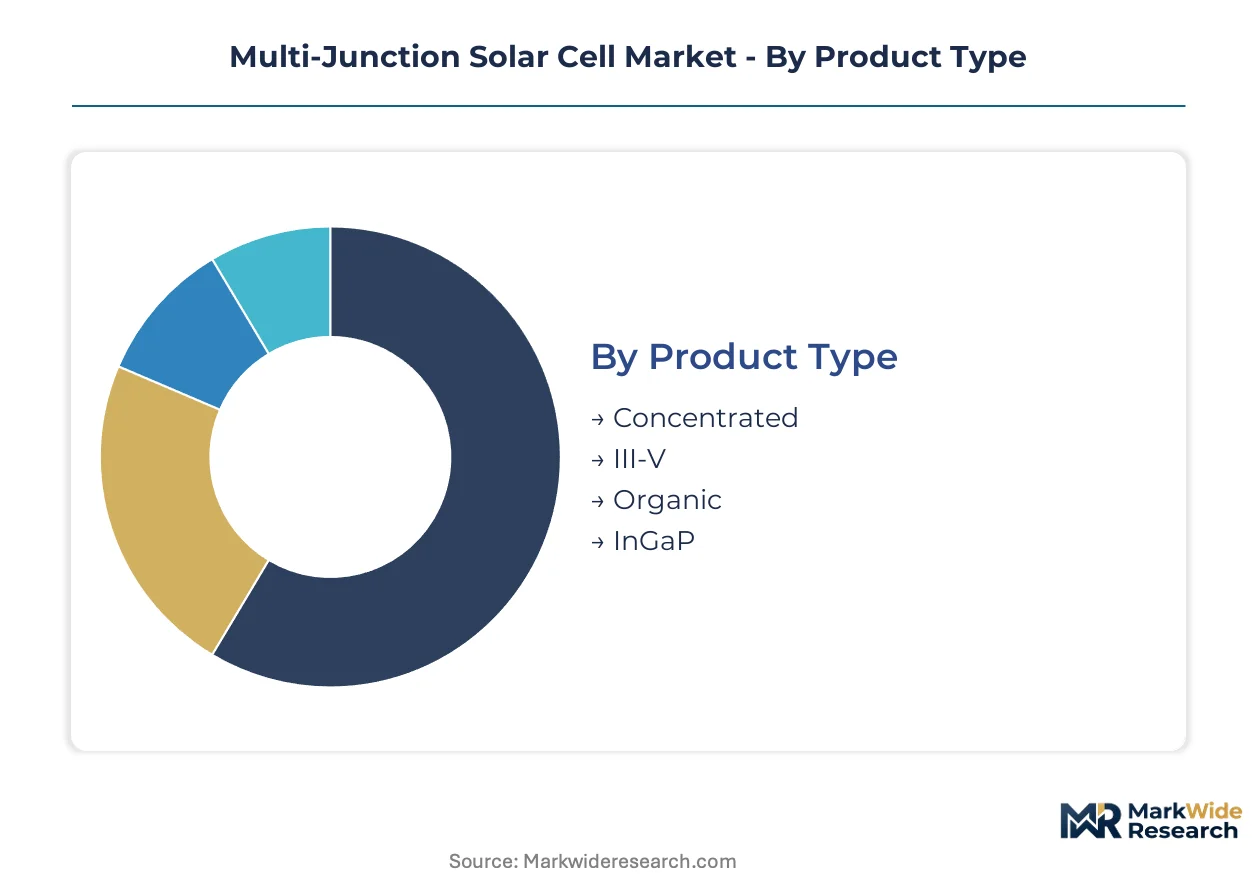
Segmentation in the multi-junction solar cell market reveals how performance specifications and qualification requirements fragment procurement across radically different use cases. Cell architectures optimized for orbital radiation environments command pricing multiples over terrestrial concentrator designs, while government qualification protocols create structural barriers between customer tiers.
Product Type:
Cost tier determines manufacturing complexity and supplier concentration across multi-junction architectures.
- Concentrated:Cells engineered for high-flux illumination under Fresnel lens arrays, achieving 47%+ efficiency through spectral splitting. Demand concentrates in southwestern United States solar farms where NREL validates field performance data and desert insolation profiles match design assumptions.
- III-V:Molecular beam epitaxy-grown stacks of InGaP, GaAs, and Ge layers delivering radiation tolerance for orbital missions. Satellite manufacturers in Japan and Germany procure these exclusively for geostationary and medium Earth orbit deployments where displacement damage dose accumulation determines mission lifetime.
- Organic:Solution-processed multi-junction stacks targeting building-integrated applications where weight and flexibility outweigh efficiency metrics.
- InGaP:Lattice-matched top cell compositions optimized for current matching in triple-junction configurations.
III-V holds installed capacity. Concentrated is rotating up the share rankings.
Application:
Application context dictates radiation-hardening depth and thermal cycling specifications.
- Aerospace:Manned spacecraft and high-altitude platforms requiring extreme reliability margins. NASA's Orion and commercial crew vehicles source triple-junction cells with 28% beginning-of-life efficiency minimums; thermal vacuum testing protocols extend qualification timelines.
- Satellite:Unmanned orbital platforms spanning LEO constellations to deep-space probes. Starlink and OneWeb procurement volumes from Cape Canaveral launch schedules are compressing delivery windows while ESA's Clean Space initiative tightens end-of-life power margin requirements.
- Power Generation:Terrestrial concentrated photovoltaic installations where dual-axis tracking and cooling systems preserve cell performance.
- Research:Laboratory demonstrations and technology validation programs funded through national science agencies.
Satellite commands procurement volume. Power Generation is expanding most quickly as Fraunhofer ISE validates field economics.
End User:
Customer type governs contract structure and technology readiness level requirements.
- Government:Defense and civil space agencies mandating TRL 9 flight heritage. NASA and ESA procurement specifications exclude unproven suppliers; the FAA's payload reliability expectations indirectly govern power system design for licensed commercial launches.
- Commercial:Satellite operators and terrestrial developers accepting performance risk for cost reduction. Long-term power purchase agreements for orbital energy services are displacing equipment sales, transferring degradation liability to manufacturers.
- Residential:Building-integrated and consumer-scale applications where multi-junction cost structures remain prohibitive.
- Industrial:Process heat and off-grid power systems where concentrator economics may achieve parity.
Government holds qualification authority. Commercial is rotating up the share rankings as procurement models shift.
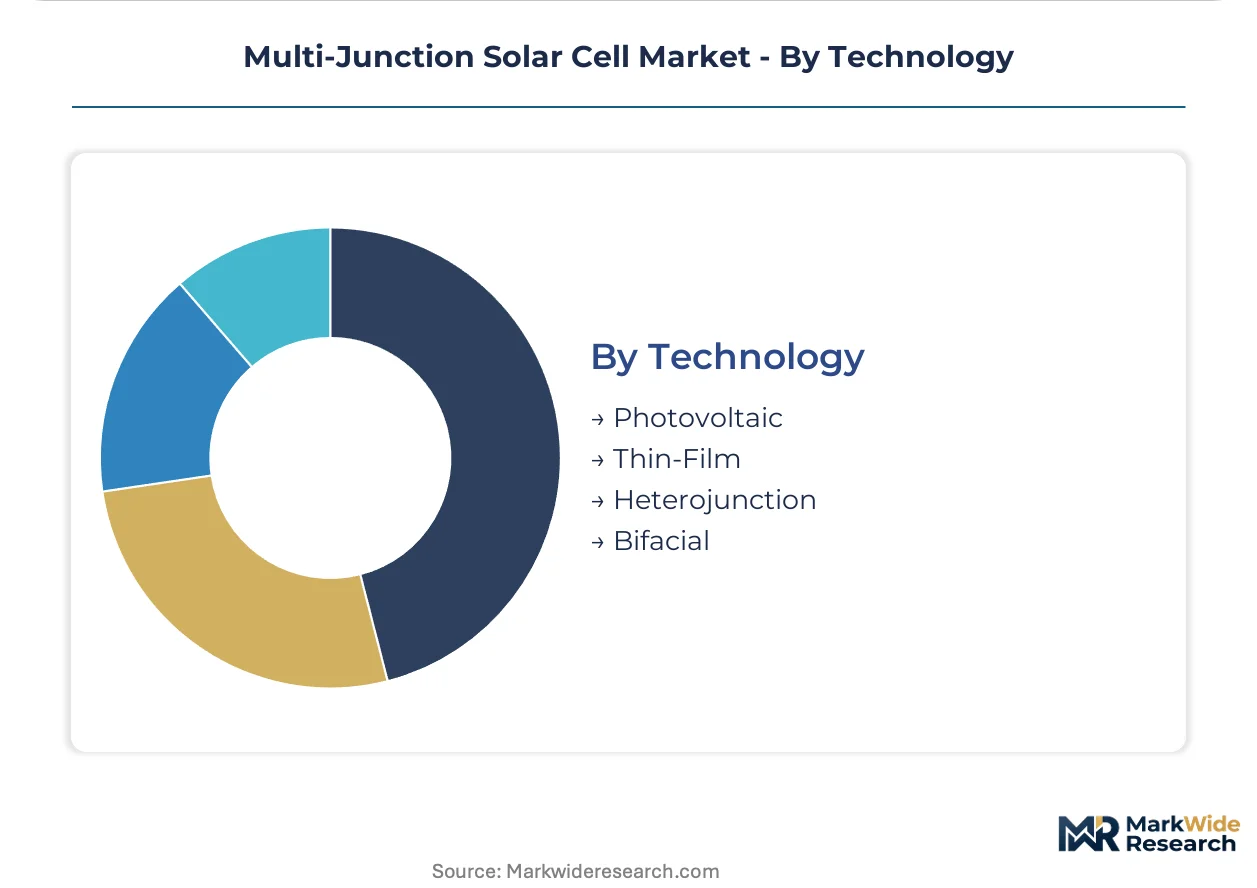
Technology:
Process architecture determines efficiency ceiling and manufacturing scalability.
- Photovoltaic:Standard p-n junction architectures forming the baseline for space and terrestrial applications. III-V epitaxial growth in Heilbronn and Albuquerque supplies this foundation; MOCVD reactor lead times of 18-24 months constrain capacity expansion.
- Thin-Film:Reduced material utilization through absorber layer minimization. Research consortia in Switzerland are stacking perovskite top cells on silicon to preserve efficiency while cutting germanium substrate dependence.
- Heterojunction:Crystalline-amorphous silicon interfaces with passivated contacts. Japan's NEDO funds development for potential space qualification.
- Bifacial:Dual-sided light capture architectures with limited applicability to concentrated illumination environments.
Photovoltaic holds installed capacity. Thin-Film is gaining share fastest through perovskite tandem convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terrestrial concentrator buyers in the southwestern United States exhibit acute price sensitivity to germanium substrate volatility, while satellite operators in Japan and Germany accept premium pricing for radiation-hardened qualification heritage.
United States
Starlink and OneWeb constellation procurement from Cape Canaveral and Vandenberg launch schedules compresses delivery windows for III-V cells. NASA's technology readiness level requirements and FAA commercial space launch licensing govern power system reliability expectations. Albuquerque, New Mexico hosts concentrated MOCVD reactor capacity serving both defense intelligence payloads and terrestrial CPV demonstrations.
Germany
Fraunhofer ISE validates terrestrial concentrator field economics while AZUR SPACE anchors European supply security through Heilbronn-based III-V manufacturing. ESA's ECSS-E-ST-20-08C qualification standards reduce supplier requalification costs for European primes. REACH substance restriction reviews scrutinize indium and gallium supply chain due diligence, prompting restructuring of supplier qualification protocols.
Japan
NEDO funds heterojunction development for potential space qualification as satellite manufacturers adopt metamorphic buffer layer architectures for next-generation bus designs. METI supports technology transfer from space to ground applications through public-private partnerships. Research consortia concentrate in Osaka and Nagoya metropolitan areas.
India
ISRO's SSLV deployment schedule creates demand for domestically qualified cells as the PLI scheme eligibility attracts foreign joint ventures into space-grade semiconductor manufacturing. The country's national space regulator shapes indigenous qualification protocols. Bengaluru and Ahmedabad clusters concentrate satellite subsystem integration activity.
Switzerland
Research consortia stack perovskite top cells on silicon bottom cells, promising cost reduction while preserving efficiency gains through two-terminal architectures. Swissmedic-equivalent standards for space hardware due diligence influence supplier selection criteria. Zurich and Geneva host precision epitaxy equipment development.
Multi-Junction Solar Cell Market Competitive Landscape
Capability concentration sits with heritage-rich specialists commanding prime contractor approved vendor lists; scale advantage sits with diversified solar manufacturers cross-leveraging terrestrial production infrastructure. The structure consolidates around three tiers: flight-proven incumbents with captive epitaxial growth, diversified photovoltaic majors with space division carve-outs, and emerging national champions serving indigenous space programs. Dominant competitive moves include strategic partnerships for MOCVD reactor access and backward integration into germanium substrate supply.
Within the heritage specialist tier, Spectrolab and AZUR SPACE Solar Power GmbH exemplify archetypes of captive supply chain control and regional supply security anchoring respectively. Emcore Corporation occupies a position representing radiation-tolerant design specialization for defense and intelligence payload applications. These three entities collectively illustrate how flight heritage accumulation and qualification protocol mastery create structural barriers against unproven market entrants.
| Leading Market Players |
|---|
| Spectrolab |
| AZUR SPACE Solar Power GmbH |
| Canadian Solar |
| Trina Solar |
| JinkoSolar Holding |
| SHARP CORPORATION |
| Umicore |
| Emcore Corporation |
| SolAero Technologies |
| Others |
Pricing and Supply Chain Analysis
MOCVD reactor undercapacity in Albuquerque and Heilbronn concentrates pricing power with heritage cell manufacturers while compressing delivery timelines for satellite constellation procurement. This utilization squeeze forces buyers into multi-year offtake commitments and transfers input cost volatility directly through to mission budgets.
Pricing Analysis
Long-term power purchase agreements for orbital energy services now dominate geostationary satellite programs, displacing transactional equipment sales and transferring fifteen-year degradation risk to manufacturers. Pricing stratifies across radiation-hardened qualification tiers, with TRL 9 flight heritage commanding substantial premiums over unproven alternatives. Cost compression in terrestrial concentrator segments intensifies as Fraunhofer ISE field data validates performance assumptions, while aerospace buyers exhibit lowest price sensitivity due to mission-critical reliability requirements and limited qualified supplier alternatives.
Supply Chain Analysis
Export control regimes governing III-V epitaxial growth technology restrict equipment and know-how flows to unapproved destinations, concentrating qualified manufacturing in the United States, Germany, and Japan. Germanium substrate supply draws from limited qualified ingot sources in China and Russia, creating single-source vulnerability for space-grade wafer specifications. Distribution runs through prime contractor approved vendor lists governed by NASA technology readiness level requirements and ESA ECSS-E-ST-20-08C qualification protocols, with direct procurement by national space agencies constituting an alternative channel for indigenous programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from cell refurbishment and aftermarket qualification testing is expanding faster than virgin wafer supply, creating recurring revenue pools that hardware margins cannot match. This shift favors vendors with predictive degradation modeling and lifecycle asset management capabilities.
For Market Incumbents: Pre-empt perovskite tandem convergence by securing exclusive research partnerships with Swiss and South Korean consortia before two-terminal architectures achieve space qualification. Lock in MOCVD reactor capacity through equipment reservations with eighteen-to-twenty-four-month lead times, and deepen backward integration into germanium substrate supply to isolate margin pools from Chinese and Russian ingot volatility.
For New Entrants and Emerging Players: India's SSLV deployment schedule and PLI scheme eligibility create the most penetrable entry point for foreign joint ventures seeking domestic qualification status. Target ISRO procurement channels through Bengaluru subsystem integrators, and leverage technology transfer agreements to bypass the five-to-seven-year flight heritage accumulation barrier that excludes direct competition with Spectrolab and AZUR SPACE heritage positions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MOCVD reactor expansion and captive epitaxial growth capacity, favoring asset-light qualification service providers over manufacturing-heavy cell producers. Five-to-ten-year viability hinges on positioning within ESA and NASA approved vendor lists; the signal to watch is ISO 24115 space sustainability standard adoption embedding end-of-life power degradation metrics into mission design criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Germanium Substrate Supply | Captive ingot sourcing insulates margin pools from Chinese and Russian supply volatility. |
| MOCVD Reactor Capacity Reservation | Equipment lead time lock-in secures delivery windows for Starlink and OneWeb constellation schedules. |
| Perovskite Tandem Research Partnership | Swiss and South Korean consortia access preserves efficiency positioning against silicon-bottom-cell cost reduction. |
| Digital Twin Integration for Qualification | Predictive degradation modeling compresses TRL progression timelines and enables service-attach revenue capture. |
| PLI Scheme Joint Venture Formation | ISRO domestic qualification pathway opens procurement access for SSLV deployment demand. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NASA technology readiness level documentation, ESA ECSS-E-ST-20-08C qualification standards, and FAA commercial space launch licensing frameworks. Primary interviews engaged satellite procurement officers at constellation operators, III-V epitaxial growth facility managers in Heilbronn and Albuquerque, and radiation-hardening engineering specialists at defense primes. Secondary validation drew from national space agency procurement disclosures, MOCVD equipment manufacturer order backlogs, and REACH substance restriction review filings. Bottom-up cell shipment estimates triangulate against top-down mission power budget allocations across geostationary, medium Earth orbit, and low Earth orbit deployment profiles.
Forecast inputs span product type segmentation across concentrated, III-V, and emerging thin-film architectures; application segmentation across aerospace, satellite, and power generation end uses; and technology segmentation across photovoltaic, heterojunction, and perovskite tandem processes. CAGRs derive from fitted growth curves calibrated to launch manifest schedules, national space program budget trajectories, and terrestrial concentrator field deployment pipelines. Industry-specific inputs include germanium substrate price volatility indices and MOCVD reactor capacity utilization rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed compound semiconductor champions or accelerated perovskite tandem qualification by Swiss research consortia would shift outcomes. Material shifts in NASA efficiency benchmarks, ESA Clean Space initiative requirements, or FAA payload reliability expectations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
China MLCC Market
Semiconductor Devices
High Electron Mobility Transistor Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Field-Effect Rectifier Diodes Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
AMD Motherboards Market
Semiconductor Devices
North America Silicon Carbide Wafers Market