
 Global Mask Alignment Systems Market | 2026-2036
Global Mask Alignment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mask Alignment Systems Market Outlook
Mask alignment equipment is rebalancing between sub-5nm EUV-critical tiers and mature-node commodity systems serving power and analog chips. ASML Holding N.V. dominates the most advanced ultraviolet alignment segment with proprietary optical architectures. Canon Inc. competes in mid-range projection aligners for MEMS and power semiconductor applications. Nikon Corporation sustains relevance through deep-ultraviolet scanner refinement for memory chip production.
Mask alignment systems position photomasks over wafers with nanometer-scale precision, typically achieving overlay accuracy below 3nm through interferometric stage feedback and active vibration isolation. Stepper technology leads in leading-edge logic fabrication where die-by-die alignment justifies throughput trade-offs, while scanner architectures capture share in high-volume memory production through field-stitching speed advantages. Hybrid systems combining optical and digital feedback are gaining traction in research institutions prototyping novel device geometries.
Japan's METI coordinates domestic equipment supply chain resilience policies affecting alignment system component sourcing. China's MIIT enforces GB standards on imported lithography-related equipment, shaping market access conditions for foreign vendors. The EU AI Act and CE marking requirements under the MDR are extending traceability mandates to semiconductor capital equipment deployed in European automotive chip fabs. Stakeholders must weigh regional certification divergence against platform standardization economics when configuring product portfolios.
Market Dynamics
The transition from DUV to EUV lithography at sub-7nm nodes is compressing alignment tolerance windows below 2nm while fragmenting equipment procurement strategies between leading-edge foundries and trailing-edge analog fabs.
Growth Catalysts
- Sub-10nm node expansion:Taiwan and South Korea foundries are commissioning new EUV lines requiring interferometric alignment stages with sub-nanometer stability.
- China's dual carbon goals:MIIT efficiency mandates are accelerating replacement cycles for legacy mercury-arc alignment systems in domestic fabs.
- Automotive chip qualification:ISO 26262 functional safety requirements are proliferating mask alignment redundancy protocols for powertrain semiconductors.
Market Restraints
- Zerodur glass supply concentration:German and Japanese specialty ceramic suppliers control low-thermal-expansion stage substrate production.
- EUV source power limitations:Plasma source instability constrains scanner throughput below economic thresholds for mid-volume logic applications.
- Export control alignment:Multilateral coordination on lithography equipment licensing is fragmenting equipment availability across Chinese state-backed fabs.
Strategic Opportunities
- India semiconductor mission:PLI scheme incentives for display and chip fabrication are creating first-mover equipment installation windows in Gujarat and Tamil Nadu.
- Hybrid optical-digital feedback:Research institutions prototyping 3D-IC architectures are piloting machine-learning-enhanced overlay correction systems.
- Refurbished system channels:Secondary markets for 200mm-compatible steppers are emerging as analog and power semiconductor fabs extend tool lifecycles.
Industry Challenges
- Interferometry specialist scarcity:Precision metrology engineering talent pools concentrate in Dutch and Japanese equipment supply chains.
- Cleanroom integration complexity:Active vibration isolation systems require facility-level coordination between tool vendors and fab constructors.
- CE-MDR certification timelines:European automotive chip fabs face extended conformity assessment periods for alignment systems deployed in safety-critical production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mask Alignment Systems Market |
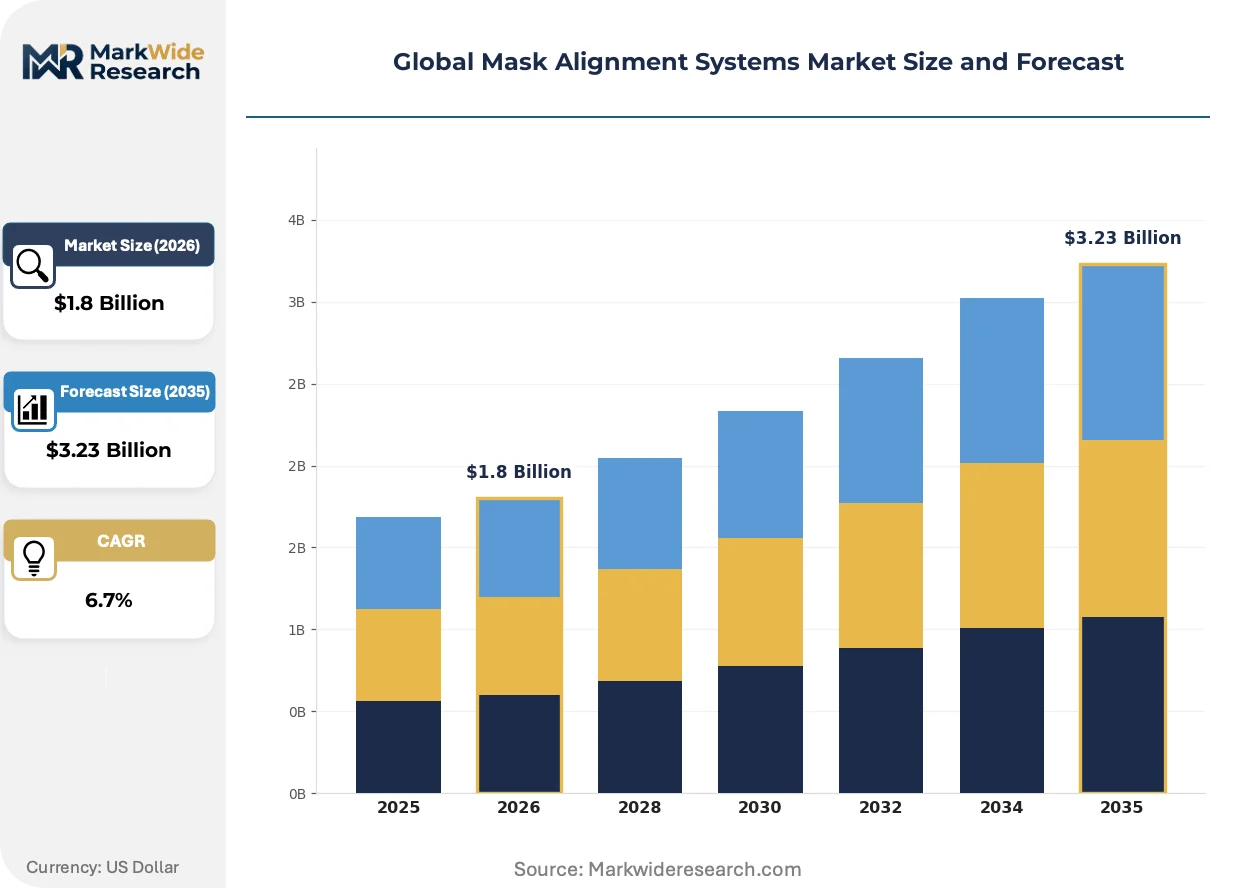
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stepper, Scanner, Projection Aligners, Laser Aligners End User: Semi-Conductor Manufacturers, Electronics Firms, Research Institutions, Foundries Technology: Optical Alignment, Mechanical Alignment, Digital Alignment, Hybrid Systems Application: Integrated Circuits, MEMS, Photovoltaics, Microelectronics |
| Companies Covered | ASML Holding N.V., Canon Inc., Nikon Corporation, EV Group, SÜSS MicroTec SE, Ultratech Inc., KLA Corporation, Veeco Instruments Inc., Attocube Systems AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mask Alignment Systems Market Strategic Shifts
Computational overlay correction and real-time stage feedback architectures are displacing static calibration protocols. Equipment vendors are reconfiguring service models around predictive maintenance telemetry.
Deep-learning-enhanced overlay prediction is absorbing residual systematic errors from thermal drift and stage hysteresis. Leading-edge logic foundries in Taiwan are deploying these algorithms across EUV scanner fleets. The technology is compressing the economic viability window for manual alignment tuning services.
REACH restrictions on perfluorinated compounds are forcing redesign of vacuum chamber sealing materials in EUV alignment stages. Equipment manufacturers are qualifying fluorine-free elastomer alternatives for plasma-facing components. Memory chip production lines in South Korea face accelerated material qualification timelines.
Consolidated procurement consortia among analog semiconductor fabs are unbundling alignment system purchases from lithography tool packages. Equipment lessors and independent service providers are capturing aftermarket overlay calibration contracts. This pattern concentrates in European automotive chip supply chains seeking cost flexibility.
Global Mask Alignment Systems Market Segmentation
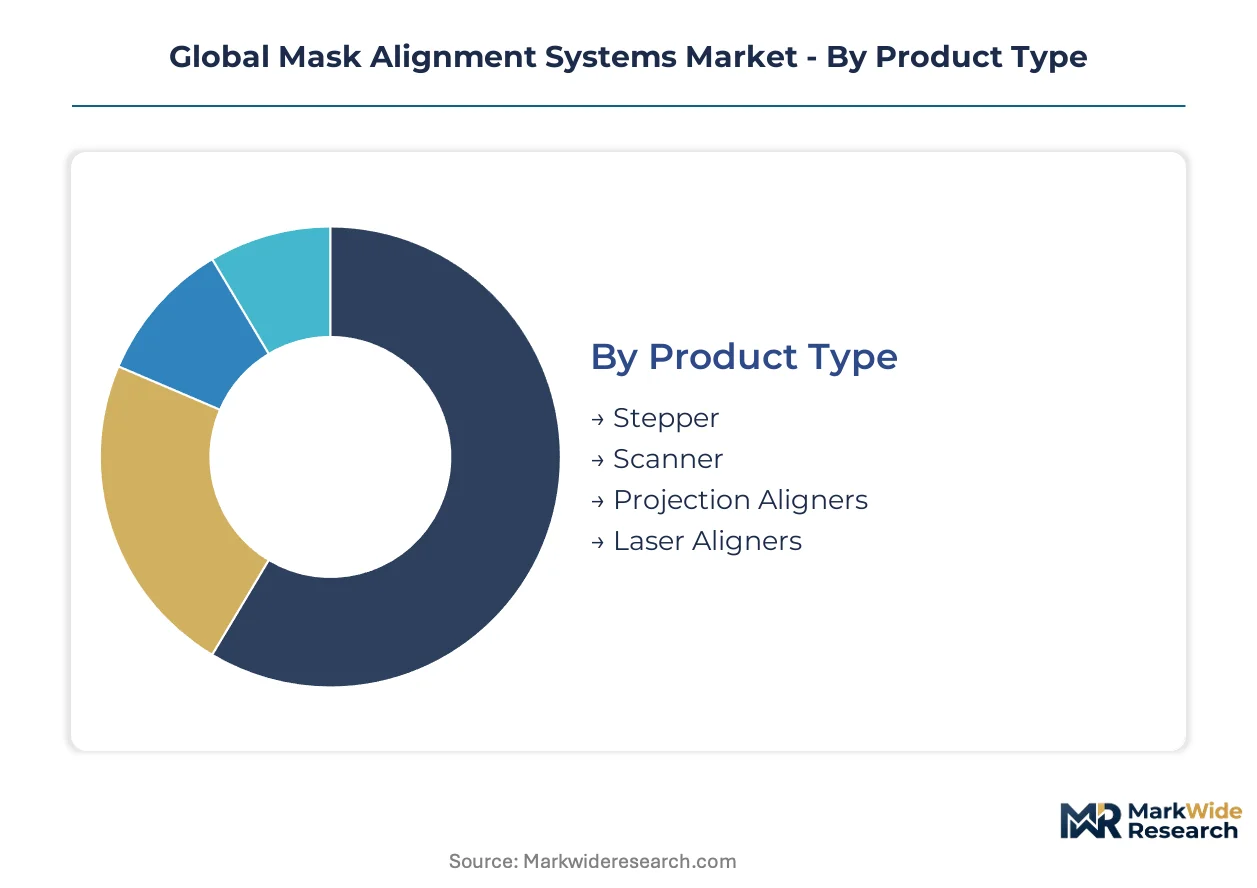
Mask alignment systems fragment across four distinct dimensions, each revealing divergent procurement priorities between leading-edge logic foundries and mature-node analog producers. Equipment specifications, integration architectures, and service intensity vary substantially across these boundaries, forcing vendors to configure modular platform strategies rather than universal solutions.
Product Type:
Stepper and scanner architectures anchor high-volume production lines as standalone capital equipment, while projection and laser aligners increasingly embed into broader lithography toolsets or specialty fabrication modules.
- Stepper:Die-by-die exposure systems achieve sub-3nm overlay precision through interferometric wafer-stage feedback and active vibration damping. Taiwan foundries deploying EUV-critical production lines specify these for logic chips at nodes below 7nm, where alignment tolerance windows compress below 2nm and justify throughput trade-offs.
- Scanner:Field-stitching architectures dominate high-volume memory fabrication in South Korea, leveraging synchronized wafer-and-reticle motion to maximize die output per hour. Samsung and SK Hynix procurement cycles favor these for NAND and DRAM layers where speed economics override die-level customization needs.
- Projection Aligners:Mid-range systems serve MEMS and power semiconductor fabs in Japan and Germany, offering 1:1 or reduction optics without the complexity of step-and-repeat mechanics.
- Laser Aligners:Compact units integrate into photovoltaic cell production lines and research prototyping benches, prioritizing cost accessibility over nanometer-scale precision.
Scanner systems lead volumes today; stepper configurations are gaining share fastest among sub-10nm logic foundries.
End User:
Procurement scale and technical sophistication diverge sharply between captive integrated device manufacturers and merchant foundry operators, with research institutions occupying a distinct experimental tier.
- Semi-Conductor Manufacturers:Integrated device manufacturers such as Intel and Texas Instruments operate captive fabs with long depreciation horizons, favoring alignment systems with 15-year service lifecycles and backward-compatible upgrade paths. Their procurement teams negotiate enterprise-level spare parts agreements and predictive maintenance telemetry subscriptions.
- Foundries:Merchant operators including TSMC and GlobalFoundries prioritize throughput maximization and rapid node transition capability, driving demand for modular alignment stages that reconfigure between DUV and EUV optical trains within single tool footprints.
- Electronics Firms:Display panel and sensor producers in China purchase alignment systems as packaged subsystems within broader lithography tool procurements, exercising limited direct vendor relationships.
- Research Institutions:University cleanrooms and national laboratories pilot hybrid optical-digital feedback architectures for 3D-IC prototyping, accepting lower reliability in exchange for experimental flexibility.
Foundries absorb the highest absolute equipment spend; research institutions are expanding fastest as government semiconductor initiatives proliferate.
Technology:
Cost tier and integration complexity stratify sharply between legacy mechanical approaches and emerging computational feedback systems, with hybrid architectures commanding premium positioning.
- Optical Alignment:Interferometric and moiré-pattern recognition systems remain the production standard for EUV and DUV lithography, leveraging 193nm and 13.5nm wavelength illumination to resolve alignment marks with sub-nanometer precision. These systems dominate Taiwan and South Korea foundry installations where overlay budgets sit below 1.5nm.
- Hybrid Systems:Machine-learning-enhanced architectures combining optical sensing with real-time digital feedback are displacing static calibration protocols at research institutions and pilot lines. These systems absorb residual systematic errors from thermal drift and stage hysteresis, compressing economic viability for manual alignment tuning services.
- Mechanical Alignment:Precision stage and kinematic coupling approaches persist in mature-node analog fabs and MEMS producers where nanometer-scale tolerances exceed device requirements.
- Digital Alignment:Purely computational overlay prediction without optical feedback remains experimental, deployed primarily in electron-beam lithography adjunct systems.
Optical alignment commands installed base dominance; hybrid systems are climbing the fastest as computational overlay correction matures.
Application:
Margin structure and equipment utilization rates vary substantially between commodity memory production and automotive-qualified power semiconductor lines.
- Integrated Circuits:Logic and memory chip fabrication consumes the most sophisticated alignment systems, with EUV-critical layers demanding interferometric stages with sub-nanometer stability and active vibration isolation. South Korean memory producers and Taiwan logic foundries drive specification intensity here.
- MEMS:Microelectromechanical systems production tolerates coarser alignment precision but requires specialized handling for non-planar substrates and released structures, favoring projection aligners with large exposure fields.
- Photovoltaics:Solar cell manufacturing prioritizes throughput over precision, with laser aligners and simplified optical systems sufficient for screen-printed metallization alignment.
- Microelectronics:Discrete components and analog chips operate at mature nodes where refurbished 200mm-compatible steppers extend economic tool lifecycles.
Integrated circuit applications anchor revenue concentration today; MEMS alignment requirements are expanding most quickly as sensor proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision metrology engineering talent pools concentrate in Dutch and Japanese equipment supply chains, with Taiwanese and South Korean foundries anchoring demand concentration for sub-10nm alignment systems.
Taiwan
TSMC and other merchant foundries commission EUV-critical production lines requiring interferometric alignment stages with sub-nanometer stability. The National Development Council coordinates domestic semiconductor advancement initiatives affecting capital equipment procurement timelines. Hsinchu Science Park hosts the densest concentration of leading-edge mask alignment installations worldwide.
South Korea
Samsung and SK Hynix drive scanner system demand for high-volume NAND and DRAM fabrication where speed economics override die-level customization. The Ministry of Trade, Industry and Energy (METI) implements strategic technology protection frameworks shaping equipment sourcing decisions. Pyeongtaek and Yongin clusters anchor memory chip production alignment system deployment.
Japan
Canon and Nikon sustain domestic precision optics manufacturing ecosystems serving both captive IDM fabs and export markets. METI coordinates supply chain resilience policies affecting Zerodur glass substrate and interferometry component sourcing. Kumamoto and Hiroshima prefectures concentrate MEMS and power semiconductor alignment system installations.
United States
Intel operates captive fabs with 15-year service lifecycle requirements and backward-compatible upgrade paths for alignment platforms. The Department of Commerce administers export control licensing fragmenting equipment availability for certain overseas destinations. Arizona and Oregon fabrication campuses anchor domestic EUV alignment stage procurement.
China
State-backed fabs accelerate replacement cycles for legacy mercury-arc alignment systems under MIIT efficiency mandates tied to dual carbon goals. GB standards enforcement on imported lithography-related equipment shapes market access conditions for foreign vendors. Shanghai and Beijing municipal clusters concentrate domestic alignment system demand.
Global Mask Alignment Systems Market Competitive Environment
Capital-heavy lithography equipment producers compete with asset-light alignment subsystem specialists in a consolidated top tier above fragmented specialty suppliers. The vendor base stratifies between EUV-critical platform providers, mid-range projection aligner fabricators, and refurbished equipment channels. Three archetypes dominate: integrated lithography tool conglomerates, precision optics specialists, and aftermarket service providers. Competitive moves concentrate on strategic partnerships for vacuum chamber sealing material qualification and predictive maintenance telemetry service models.
Within the integrated lithography tier, ASML Holding N.V. and Canon Inc. represent contrasting geographic anchors for optical architecture development. Nikon Corporation occupies a position among deep-ultraviolet refinement specialists sustaining relevance in memory chip production. These three exemplify how vendor concentration follows the wavelength roadmap from DUV to EUV criticality.
| Leading Market Players |
|---|
| ASML Holding N.V. |
| Canon Inc. |
| Nikon Corporation |
| EV Group |
| SÜSS MicroTec SE |
| Ultratech Inc. |
| KLA Corporation |
| Veeco Instruments Inc. |
| Attocube Systems AG |
| Others |
Value Chain & Pricing Dynamics
EUV-critical alignment stages and mature-node projection systems occupy divergent commercial strata, with the former commanding bundled service premiums and the latter facing unbundled aftermarket competition. This bifurcation concentrates pricing power with interferometric stage specialists serving Taiwan and South Korea foundries, while commoditized segments see margin compression from refurbished equipment channels and independent calibration providers.
Pricing Analysis
Bundled lithography tool packages dominate EUV-critical procurement, whereas unbundled aftermarket services capture mature-node analog fabs seeking cost flexibility. Price differentiation hinges on overlay precision certification and geographic proximity to service engineering talent pools. Cost compression in mid-range projection aligners intensifies as European automotive chip consortia consolidate procurement and extend tool lifecycles through refurbishment. Foundries absorbing EUV scanner fleets exhibit the lowest price sensitivity; analog semiconductor captive fabs in Germany and Japan demonstrate the highest.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese suppliers of Zerodur glass substrates for interferometric stages. Manufacturing concentration in the Netherlands, Japan, and the United States anchors precision optics fabrication, while South Korea and Taiwan dominate downstream system integration. Raw material dependencies span specialty ceramics, fluorine-free elastomers, and high-purity aluminum alloys. Tariff exposure on lithography-related equipment imports into China fragments equipment availability. Distribution runs through direct OEM sales for leading-edge systems and independent lessors for refurbished 200mm-compatible channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Mask Alignment Systems Market functions as a stable compounder anchored by irreversible node transitions below 10nm that mandate recurring precision equipment refresh cycles.
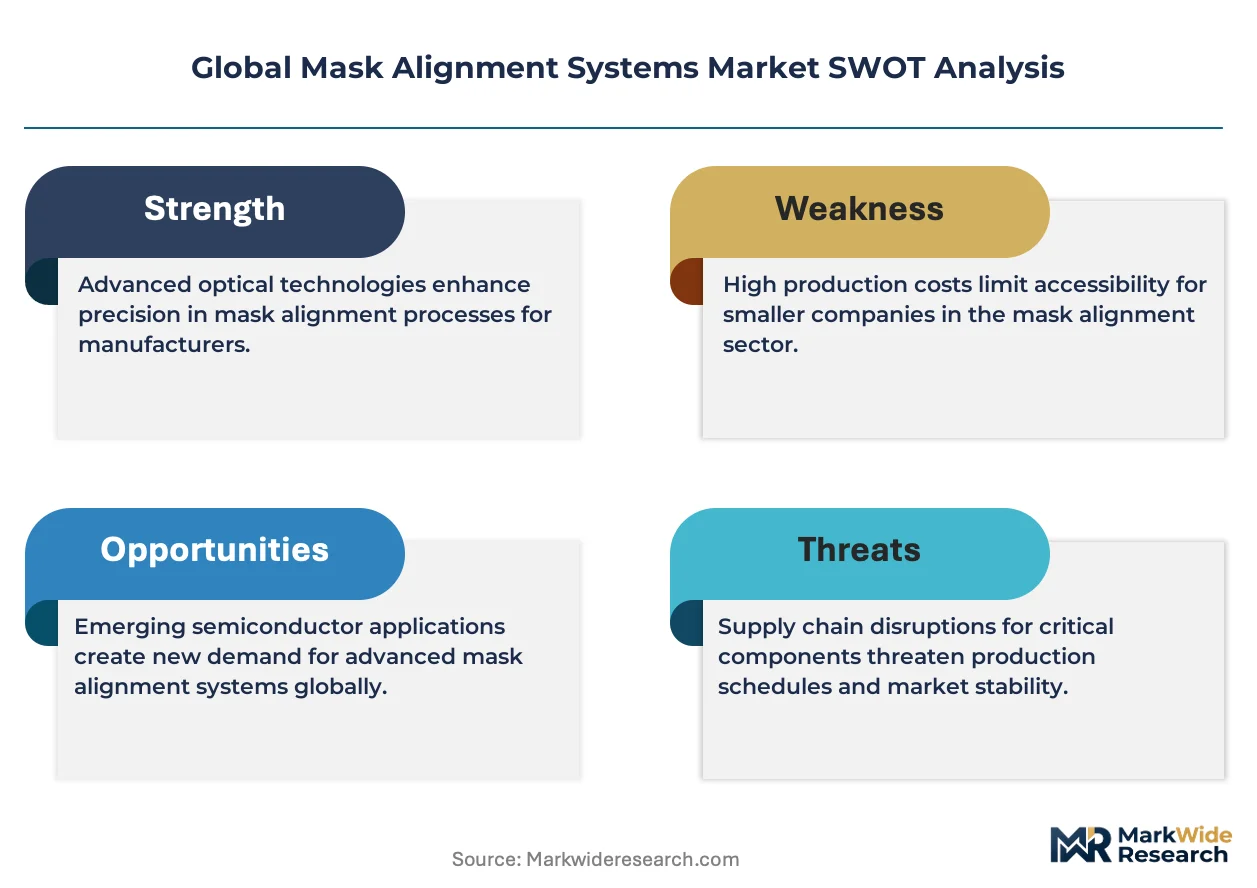
For Market Incumbents: To counter unbundling pressure from consolidated analog procurement consortia, deepen captive supply of interferometry components through backward integration into Japanese and German specialty ceramic networks. Expand predictive maintenance telemetry subscriptions to extend service revenue visibility across 15-year IDM depreciation horizons. For New Entrants and Emerging Players: Digital-channel routes through equipment leasing platforms offer lower-friction entry into refurbished 200mm stepper distribution serving India's Gujarat and Tamil Nadu fabrication clusters. Target MEMS alignment subsystems for automotive sensor fabs where ISO 26262 qualification requirements create incumbent switching costs. Pursue hybrid optical-digital feedback architectures for research institutions prototyping 3D-IC geometries. For Investors and Strategic Acquirers: Asymmetric upside sits with precision metrology engineering firms possessing interferometry specialist talent pools concentrated in Dutch and Japanese supply chains. The five-to-ten year viability window favors acquisition of stage subsystem specialists over integrated lithography conglomerates. Watch for EUV source power stability breakthroughs as the inflection signal compressing mid-volume logic application economics.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Telemetry Expansion | ASML and Canon are reconfiguring service models around real-time overlay drift monitoring for Taiwan foundry fleets. |
| Fluorine-Free Elastomer Qualification | REACH restrictions are forcing redesign of vacuum chamber sealing materials for EUV alignment stages in South Korea. |
| Hybrid Feedback Architecture Development | Machine-learning-enhanced overlay correction absorbs thermal drift errors for 3D-IC prototyping at research institutions. |
| Refurbished Equipment Channel Buildout | Secondary markets for 200mm steppers extend economic lifecycles for European automotive chip supply chains. |
| Interferometry Talent Pool Consolidation | Precision metrology engineering scarcity in Dutch and Japanese supply chains drives specialist firm acquisition premiums. |
Study Parameters
Bottom-up foundry capacity modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with lithography tool procurement directors, fab construction project managers, interferometry R&D leads, and aftermarket service heads were cross-validated against secondary sources including SEC equipment manufacturer filings, customs import records for lithography-related capital goods, and national semiconductor initiative policy documents. Triangulation between demand-side foundry expansion announcements and supply-side order book disclosures ensures coherence across estimation layers.
Historical trendline analysis of node transition cadences and alignment precision requirements informs the projection framework. Segmentation dimensions span product architecture, end-user procurement archetype, feedback technology tier, and application-specific overlay budgets. CAGRs were derived from equipment intensity ratios per wafer start capacity, adjusted for technology mix shifts across the modeling period. Forecast inputs incorporate EUV adoption curves, MIIT efficiency mandate compliance timelines, and automotive chip qualification protocol proliferation.
The model assumes a particular technology adoption path; alternative pathways for high-NA EUV lithography would alter the outlook for sub-2nm alignment tolerance windows. Forecasts reflect assumptions regarding multilateral export control coordination stability and REACH regulatory enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Acousto Optic Devices Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Photointerrupter Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
CMP Polishing Machine Market
Optical Components
Europe Scintillator Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Ring Panel Filters Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Global Non Dispersive Infrared (NDIR) Market
Optical Components
Europe Optical Imaging Market
Optical Components
Europe Tunable Laser Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Electronic Digital Magnifiers Market