
 Night Vision Tubes Market | 2026-2036
Night Vision Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Night Vision Tubes Market Insights
Gen III thin-film image intensification is redrawing quality benchmarks across the Night Vision Tubes Market. L3Harris Technologies leverages captive gallium arsenide photocathode production to sustain premium tube output for U.S. defense programs. Photonis France SAS anchors European supply through its proprietary auto-gated tube architecture. Elbit Systems Ltd. competes on integrated helmet-display systems that bundle tubes with optics and software.
Night vision tubes are vacuum-sealed electro-optical devices that amplify ambient photons through photocathode electron emission, microchannel plate multiplication, and phosphor screen conversion, typically operating at wavelengths between 400 and 900 nanometers. Their core function is to render low-light environments visible for operators in defense, security, and observation roles. Microchannel plate technology leads in military procurement due to established supply chains and proven performance in adverse conditions, while solid-state alternatives gain traction in commercial security monitoring where size and power constraints matter more than extreme low-light sensitivity. Goggles dominate defense agency spending as helmet-mounted systems become standard issue, whereas camera modules represent the fastest-expanding product type among research institutions deploying multispectral imaging platforms.
FDA regulates medical device applications of night vision technology, while the U.S. Department of State administers ITAR restrictions that govern cross-border tube transfers; the EU Green Deal and REACH frameworks increasingly influence phosphor chemistry choices for manufacturers serving European defense and commercial buyers. These overlapping compliance requirements create divergent certification pathways that favor regionally entrenched suppliers with established regulatory navigation capabilities. Stakeholders must monitor how semiconductor export controls expand to cover compound photocathode substrates, as this would constrain raw material sourcing for non-domestic tube fabricators.
Market Dynamics
ITAR export controls are concentrating procurement authority within domestic manufacturing ecosystems, forcing allied nations to develop indigenous tube fabrication or accept restricted technology tiers from U.S. suppliers.
Growth Catalysts
- Helmet-mounted system standardization:Defense agencies across NATO member states are mandating unified night vision architectures for infantry modernization programs, creating sustained demand for Gen III thin-film tubes.
- REACH phosphor chemistry compliance:The EU Green Deal is accelerating substitution of cadmium-based phosphors with europium-doped alternatives, opening procurement pathways for European-certified suppliers.
- Gallium arsenide photocathode maturation:Compound semiconductor foundries in Israel and the United States have achieved yield rates sufficient for volume military contracts, reducing unit costs for auto-gated tube variants.
Market Restraints
- Raw material supply concentration:High-purity gallium and arsenic refining capacity clusters in China and Kazakhstan, exposing non-domestic tube fabricators to export restriction risk.
- ITAR licensing friction:The U.S. Department of State's case-by-case review process for image intensifier exports creates 18-24 month procurement delays for allied defense programs.
- Digital sensor substitution threat:Uncooled infrared focal plane arrays from FLIR and BAE Systems are capturing border surveillance and vehicle platform applications where extreme low-light performance is secondary.
Strategic Opportunities
- Underpenetrated commercial security:Critical infrastructure operators in Germany and Australia are deploying night vision for perimeter monitoring, creating demand for solid-state alternatives to vacuum tube architectures.
- Multispectral imaging convergence:Research institutions are fusing image intensification with short-wave infrared sensors, requiring tube modules with modified spectral response curves.
- India's defense indigenization mandate:The PLI scheme and negative import lists are compelling foreign suppliers to establish joint ventures with Bharat Electronics and Tata Advanced Systems for domestic tube assembly.
Industry Challenges
- Microchannel plate fabrication expertise:The precision glass drawing and hydrogen reduction processes required for 6-micron pore structures rely on a workforce concentrated at three facilities worldwide.
- Dual-use classification ambiguity:Tubes rated below military Gen III specifications face inconsistent export control interpretations across customs jurisdictions, delaying commercial shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Night Vision Tubes Market |
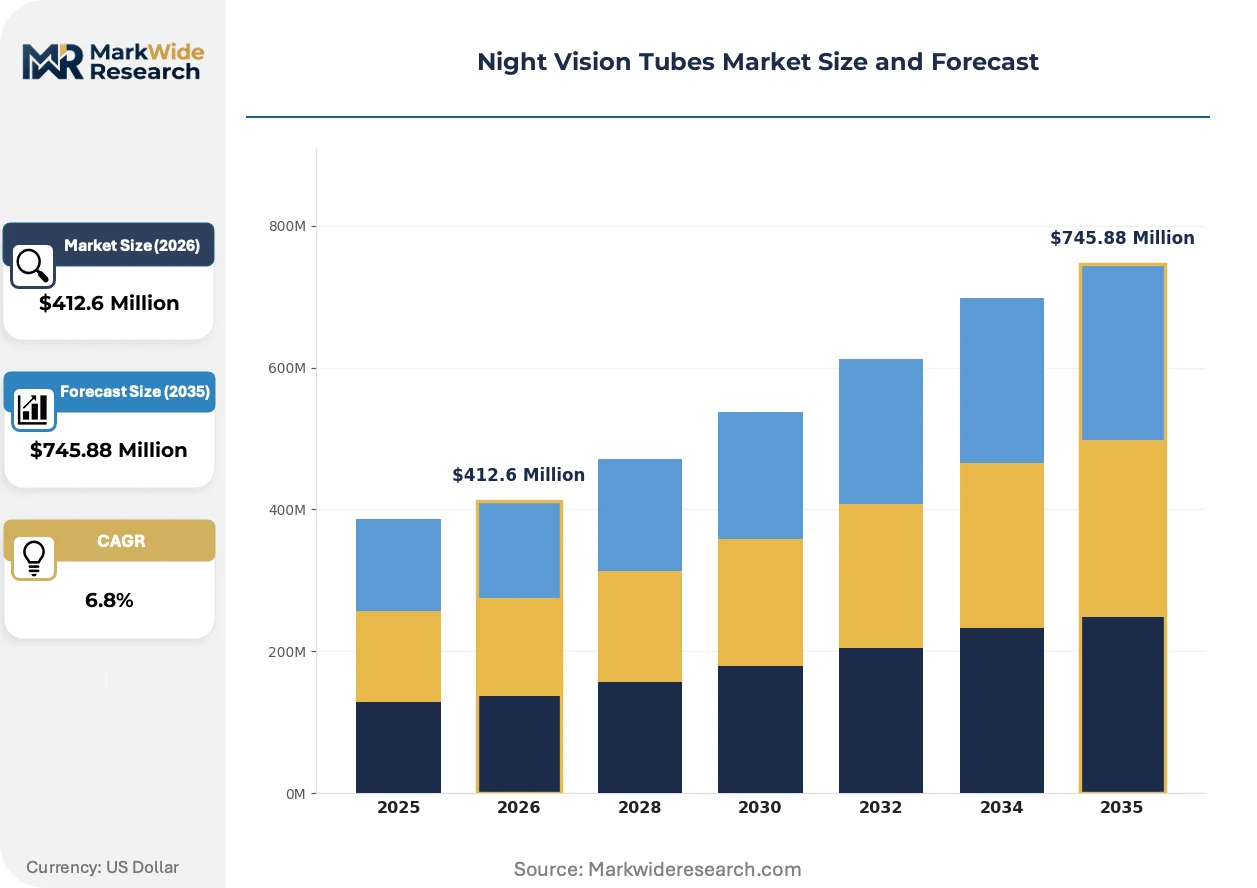
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Photomultiplier, Electron Bombarded, Solid State, Thermoelectric, Microchannel Plate Application: Military Surveillance, Wildlife Observation, Security Monitoring, Search and Rescue, Maritime Navigation Product Type: Monocular, Binocular, Goggles, Camera Modules, Rifle Scopes Customer Type: Defense Agencies, Commercial Security Firms, Research Institutions, Emergency Responders |
| Companies Covered | L3Harris Technologies Inc., Teledyne FLIR LLC, Elbit Systems Ltd., BAE Systems plc, Thales Group, Photonis France SAS, Exosens, Hamamatsu Photonics K.K., BEL Optronic Devices Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Night Vision Tubes Market Trends and Innovations
Photocathode material science and regulatory chemistry standards are the primary vectors of competitive differentiation, with manufacturing process control now determining access to defense procurement channels.
Thin-film gallium arsenide photocathodes are displacing multi-alkali designs in premium tube segments. Special operations forces across Five Eyes nations are specifying GaAs variants for helmet-mounted displays, accepting 40% cost premiums for enhanced near-infrared sensitivity. This material shift is compressing demand for legacy S-25 photocathode production lines.
REACH Annex XVII restrictions on cadmium compounds are forcing phosphor reformulation across European supply chains. ECHA's 2023 sunset date for certain luminescent materials compelled Photonis to accelerate europium-activated yttrium oxide alternatives, with certification timelines now extending 14-18 months for modified tube variants.
Defense procurement offices are consolidating vendor qualification lists to reduce technical risk exposure. The U.S. Army's PEO Soldier has compressed its approved supplier base from twelve to four tube sources since 2020, concentrating volume with vertically integrated manufacturers possessing in-house photocathode deposition. Allied programs in Germany and Israel are mirroring this consolidation pattern.
Night Vision Tubes Market Segmentation
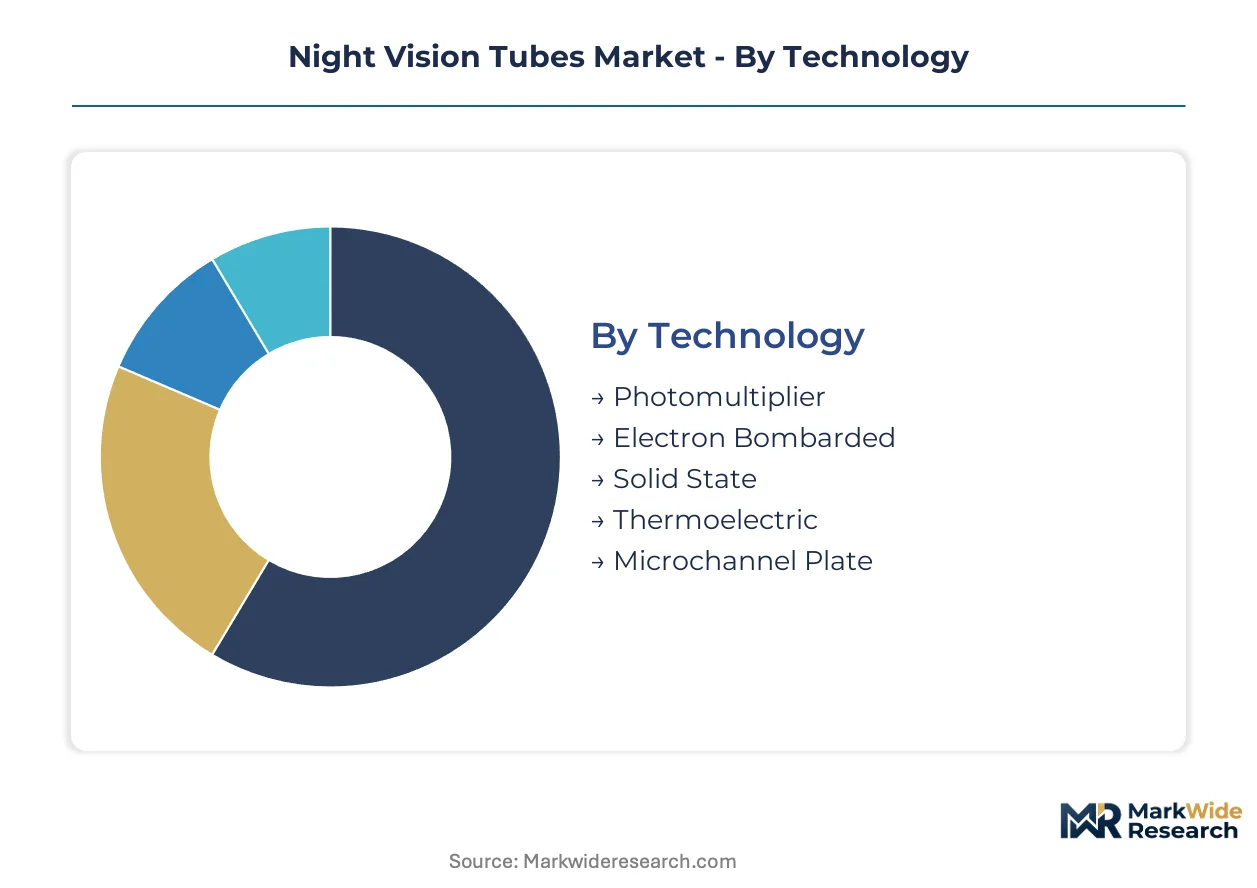
Technology selection in night vision tubes determines regulatory compliance pathways and procurement eligibility. Defense customers prioritize ITAR-controlled vacuum architectures while commercial buyers accept solid-state alternatives with relaxed export restrictions.
Technology:
FDA and ITAR frameworks create divergent certification requirements across vacuum and solid-state architectures.
- Microchannel Plate:Vacuum-sealed glass substrates with 6-micron pore structures amplify electrons through secondary emission. U.S. defense procurement concentrates here for helmet-mounted systems, constrained by ITAR licensing delays of 18-24 months for allied exports.
- Solid State:CMOS and electron-multiplying CCD sensors convert photons without vacuum components. Commercial security deployments in Germany and Australia favor this technology where REACH phosphor restrictions complicate vacuum tube compliance.
- Photomultiplier:Discrete dynode structures for laboratory-grade photon counting.
- Electron Bombarded:Direct electron acceleration for high-speed imaging applications.
- Thermoelectric:Cooled sensor arrays reducing dark current for astronomy.
Established volume favors Microchannel Plate; emerging adoption favors Solid State.
Application:
End-use concentration follows defense procurement cycles and civilian regulatory thresholds.
- Military Surveillance:Helmet-mounted and weapon-integrated systems demand Gen III thin-film performance. Five Eyes nations specify auto-gated tubes for infantry modernization, absorbing premium pricing for gallium arsenide photocathodes.
- Security Monitoring:Perimeter defense and critical infrastructure protection drive commercial procurement. German operators deploy solid-state alternatives to navigate REACH cadmium restrictions on phosphor chemistry.
- Wildlife Observation:Ecotourism and research applications requiring portable observation.
- Search and Rescue:Emergency responder deployments in low-visibility conditions.
- Maritime Navigation:Coastal patrol and vessel collision avoidance systems.
Defense procurement dominates absolute spend; commercial security climbs fastest.
Product Type:
Form factor selection reflects integration complexity and operator mobility requirements.
- Goggles:Binocular helmet-mounted systems standardize across NATO infantry programs. The U.S. Army's PEO Soldier mandates unified architectures, compressing supplier qualification lists from twelve to four approved sources.
- Camera Modules:Multispectral imaging platforms fuse image intensification with short-wave infrared sensors. Research institutions represent the steepest expansion trajectory for modified spectral response configurations.
- Monocular:Single-tube handheld units for auxiliary observation.
- Binocular:Dual-tube stationary or tripod-mounted systems.
- Rifle Scopes:Weapon-integrated targeting with ballistic compensation.
Goggles anchor defense procurement volume; Camera Modules gain share fastest in research segments.
Customer Type:
Buyer sophistication determines specification stringency and contract structure.
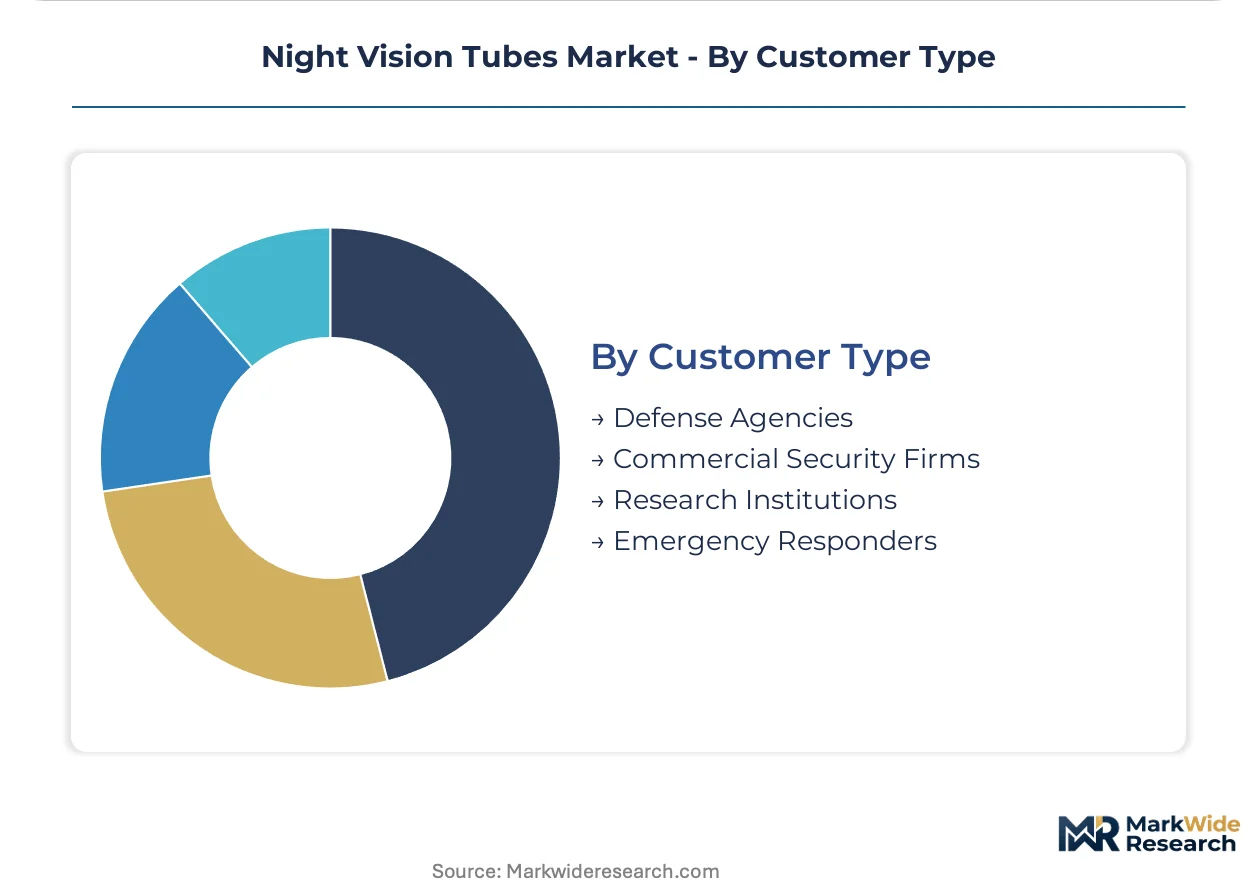
- Defense Agencies:Multi-year programs with technical data package requirements and domestic content mandates. India's PLI scheme and negative import lists compel joint ventures with Bharat Electronics for local assembly.
- Research Institutions:Small-batch procurement with custom spectral calibration. Multispectral fusion projects require tube modules with modified response curves beyond standard military specifications.
- Commercial Security Firms:Price-sensitive procurement with simplified maintenance protocols.
- Emergency Responders:Municipal and federal grant-funded acquisitions with interoperability standards.
Defense Agencies concentrate procurement authority; Research Institutions drive specification innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tube fabrication capacity clusters in three allied nations with established compound semiconductor foundries. ITAR licensing friction and REACH phosphor chemistry mandates are fragmenting procurement pathways across defense and commercial segments.
United States
Helmet-mounted system standardization across NATO infantry programs sustains Gen III thin-film tube procurement. The Department of State administers 18-24 month ITAR licensing delays that compress allied access to premium variants. Rochester, New York anchors domestic manufacturing with vertically integrated photocathode deposition capabilities serving PEO Soldier programs.
Germany
Perimeter monitoring deployments at critical infrastructure sites drive commercial security demand for solid-state alternatives. ECHA's REACH Annex XVII restrictions on cadmium compounds force phosphor reformulation with europium-doped substitutes. Oberkochen and Wetzlar host precision optics clusters integrating modified tube modules into multispectral imaging platforms.
Israel
Gallium arsenide photocathode maturation achieved yield rates sufficient for volume military contracts. The Ministry of Defense sustains domestic fabrication through captive compound semiconductor foundries. Haifa and Rehovot concentrate auto-gated tube production for integrated helmet-display systems bundling optics with software.
India
Defense indigenization mandates under the PLI scheme compel foreign suppliers into joint ventures with Bharat Electronics. DGFT negative import lists restrict finished tube imports while permitting component assembly partnerships. Hyderabad and Bengaluru emerging as assembly hubs for domestic tube fabrication with transferred technology protocols.
France
European supply chain anchoring through proprietary auto-gated tube architecture serves allied defense programs exempt from ITAR friction. The EU Green Deal accelerates substitution timelines for legacy phosphor chemistries. Brive-la-Gaillarde and Paris-Saclay cluster vacuum-sealed electro-optical device fabrication with REACH-certified europium-activated alternatives.
Night Vision Tubes Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Night Vision Tubes Market. Vertically integrated manufacturers with captive photocathode deposition concentrate defense procurement authority through compressed supplier qualification lists. Three archetypes dominate: compound semiconductor foundries controlling gallium arsenide substrate supply, precision optics integrators bundling tubes with helmet-mounted displays, and solid-state sensor specialists capturing commercial security segments. Competitive moves center on backward integration into high-purity gallium refining and strategic partnerships with allied defense agencies to navigate ITAR licensing constraints.
Among U.S.-based defense contractors, L3Harris Technologies Inc. exemplifies the vertically integrated archetype with captive production lines. Israeli compound semiconductor specialists Elbit Systems Ltd. and French vacuum electro-optical fabricator Photonis France SAS occupy positions as regional supply anchors serving ITAR-exempt procurement channels. These three represent distinct national manufacturing ecosystems responding to divergent regulatory frameworks.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| Teledyne FLIR LLC |
| Elbit Systems Ltd. |
| BAE Systems plc |
| Thales Group |
| Photonis France SAS |
| Exosens |
| Hamamatsu Photonics K.K. |
| BEL Optronic Devices Limited |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month ITAR licensing cycles compress allied access to Gen III thin-film tubes while concentrating pricing power with vertically integrated U.S. manufacturers possessing captive gallium arsenide photocathode production. This lead-time asymmetry rewards domestic fabricators with premium contract structures and forces foreign buyers toward ITAR-exempt European or Israeli supply channels at elevated cost positions.
Pricing Analysis
ITAR export controls dictate the pricing tier structure across the Night Vision Tubes Market, separating ITAR-controlled Gen III thin-film variants from ITAR-exempt lower-tier specifications. Price differentiation hinges on gallium arsenide photocathode certification grade and volume procurement scale under defense agency multi-year programs. Pricing pressure stems from solid-state infrared sensor substitution in border surveillance applications where extreme low-light sensitivity carries less weight. Commercial security firms exhibit highest price sensitivity, while Five Eyes defense procurement offices absorb 40% cost premiums for auto-gated tube performance.
Supply Chain Analysis
Inventory cycles exceeding two years for ITAR-licensed tube exports expose non-domestic fabricators to procurement disruption and cost escalation. High-purity gallium refining capacity clusters in China and Kazakhstan, while precision microchannel plate fabrication concentrates at three facilities across the United States, France, and Israel. Raw material supply draws from compound semiconductor foundries in Israel and the United States, with phosphor chemistry sourcing constrained by REACH cadmium restrictions. Single-source vulnerability pervades the 6-micron pore structure glass drawing workforce. Distribution runs through defense procurement offices and authorized technology transfer channels rather than open commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as regulatory divergence between ITAR, REACH, and India's PLI scheme creates distinct procurement channels demanding specialized compliance capabilities. Multispectral imaging convergence and commercial security digitization open niches beyond legacy defense concentration.
For Market Incumbents: Compound defensive positions through backward integration into high-purity gallium refining and accelerated europium-doped phosphor certification to preempt REACH compliance gaps. Solid-state infrared substitution from FLIR and BAE Systems threatens perimeter surveillance applications. Captive photocathode deposition capacity remains the critical lever for sustaining PEO Soldier program qualification. For New Entrants and Emerging Players: After-sales service and maintenance protocol simplification represent underexploited service-layer gaps where incumbents prioritize prime contract volume over operator support. India's defense indigenization mandate offers the most penetrable geography through joint venture structures with Bharat Electronics. Target research institution procurement with custom spectral calibration capabilities as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because compliance navigation capabilities compound faster than pure manufacturing scale in an environment of tightening export controls and divergent chemical certification regimes. Acquisition targets should display vertically integrated photocathode production plus established ITAR licensing infrastructure. Watch for semiconductor export control expansion to cover compound photocathode substrates as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Photocathode Deposition Capacity Expansion | Captive gallium arsenide production secures PEO Soldier qualification and compresses supplier lists. |
| Europium-Doped Phosphor Certification | REACH Annex XVII compliance opens European defense procurement channels previously restricted by cadmium chemistry. |
| Joint Venture Formation in India | PLI scheme alignment and DGFT negative import list navigation enable access to indigenizing defense programs. |
| Multispectral Module Development | Fused short-wave infrared and image intensification configurations capture research institution specification innovation. |
| Solid-State Alternative Commercialization | CMOS and EM-CCD architectures penetrate perimeter monitoring segments where vacuum tube REACH compliance proves prohibitive. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, compound semiconductor foundry engineers, export control compliance specialists, and critical infrastructure security directors; and secondary validation through ITAR licensing databases, ECHA REACH substance restriction filings, SEC 10-K disclosures from listed defense contractors, and customs trade flow records. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Across the projection horizon, the analytical framework modeled volume and value trajectories by technology architecture, application end-use, product form factor, and customer sophistication tier. CAGRs derived from defense procurement cycle timing, gallium arsenide photocathode yield maturation curves, and regulatory compliance timeline compression. Industry-specific inputs included ITAR licensing queue length observations and REACH sunset date implementation pacing.
Underlying assumptions cover sustained Five Eyes defense modernization spending, stable compound semiconductor foundry yield rates, and incremental REACH phosphor chemistry substitution timelines, with deviation risk concentrated in semiconductor export control expansion to photocathode substrates and allied nation indigenization policy acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
CVD Sic Ring Market
Optical Components
Liquid Light Guides Market
Optical Components
Fluorophore Market
Optical Components
Optical Encoder Market
Optical Components
Liquid Lenses Market
Optical Components
Optical Interconnect Market
Optical Components
Silicon Photonics Wafer Market
Optical Components
Global Adaptive Optics Market
Optical Components
Acousto Optic Devices Market
Optical Components
CMP Polishing Machine Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
North America Photonic Sensors Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Spatial Light Modulator Market