
 North America IP Camera Market | 2026-2036
North America IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
North America IP Camera Market Insights
Subscription-based video-surveillance-as-a-service financing is reconfiguring capital deployment across the North America IP Camera Market, enabling mid-sized security integrators to compete without heavy upfront hardware investments. Hikvision USA Inc. leverages extensive manufacturing scale to dominate price-sensitive municipal contracts. Axis Communications Inc. differentiates through open-architecture platform specialization that appeals to enterprise clients with complex multi-vendor environments. Avigilon Corporation sustains premium positioning through advanced video analytics integration.
A network-connected IP camera captures, compresses, and transmits digital video over Ethernet or Wi-Fi using H.265 or H.264 codecs, typically operating at resolutions from 1080p to 4K with power delivered via PoE or local adapters. Its primary purpose is to enable centralized remote monitoring, AI-powered analytics, and forensic retrieval for commercial and institutional security operations. Dome and bullet form factors anchor the product mix, with dome units preferred for indoor retail and banking deployments where vandal resistance and discreet positioning matter. Wireless and PoE technology segments are expanding fastest as infrastructure-light deployment becomes essential for retrofit installations across aging commercial buildings.
The FCC governs radio-frequency emissions for wireless camera systems, while NIST cybersecurity frameworks shape encryption and firmware-update requirements for federal-adjacent installations. State-level biometric privacy laws in Illinois, Texas, and Washington constrain facial analytics deployment, creating compliance complexity that favors vendors with embedded privacy-masking capabilities. Stakeholders must weigh trade-offs between feature-rich analytics and jurisdictional data-governance constraints when specifying next-generation systems.
Market Dynamics
Subscription-based financing models are restructuring capital deployment across the North America IP Camera Market, compressing hardware margins while expanding recurring revenue pools for security integrators and managed service providers.
Growth Catalysts
- Smart city infrastructure mandates:Federal infrastructure packages and state-level transportation modernization programs in Texas and California are accelerating bulk procurement of PoE-enabled surveillance networks for municipal transit hubs and highway monitoring corridors.
- NIST cybersecurity frameworks:Evolving encryption standards and firmware-update requirements for federal-adjacent installations are compelling manufacturers to embed hardware-level security protocols, creating compliance-driven replacement cycles across government and critical infrastructure verticals.
- Edge AI processing:On-camera analytics engines for license plate recognition and crowd-flow monitoring are displacing centralized server architectures, reducing bandwidth costs for casino operators and retail loss-prevention departments.
Market Restraints
- Semiconductor supply concentration:Image sensor fabrication relies on concentrated Asian foundry capacity, exposing North American integrators to lead-time volatility for 4K and thermal imaging components.
- Biometric privacy friction:Illinois Biometric Information Privacy Act and Texas Capture or Use of Biometric Identifier Act impose statutory damages for unauthorized facial analytics deployment, constraining feature utilization in multi-state retail chains.
- Wireless spectrum congestion:FCC 6 GHz unlicensed rules create interference risks for high-density wireless camera deployments in urban commercial corridors, limiting scalability of infrastructure-light retrofit solutions.
Strategic Opportunities
- Canada municipal modernization:Underpenetrated smart city infrastructure in Toronto, Vancouver, and Montreal transit authorities presents white-space demand for vandal-resistant dome units with integrated audio analytics.
- Video-surveillance-as-a-service channel expansion:Regional security dealers are adopting recurring-revenue financing platforms to compete against national integrators, opening distribution pathways for mid-tier manufacturers.
- PoE++ power convergence:Integration of 90W power-over-ethernet with LED lighting and access control systems enables single-cable infrastructure for aging commercial building retrofits across the US Sun Belt.
Industry Challenges
- Cybersecurity certification timelines:NIST SP 800-53 and FedRAMP authorization processes for cloud-connected camera platforms extend sales cycles by 8-14 months for federal contractors.
- Legacy analog integration complexity:Hybrid deployments requiring coax-to-IP encoder bridges strain technical support resources for regional integrators serving small-box retail and quick-service restaurant chains.
- Edge AI talent scarcity:Computer vision engineering and embedded firmware development skills concentrate in Seattle, San Francisco, and Austin labor markets, inflating compensation costs for camera manufacturers expanding R&D operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America IP Camera Market |
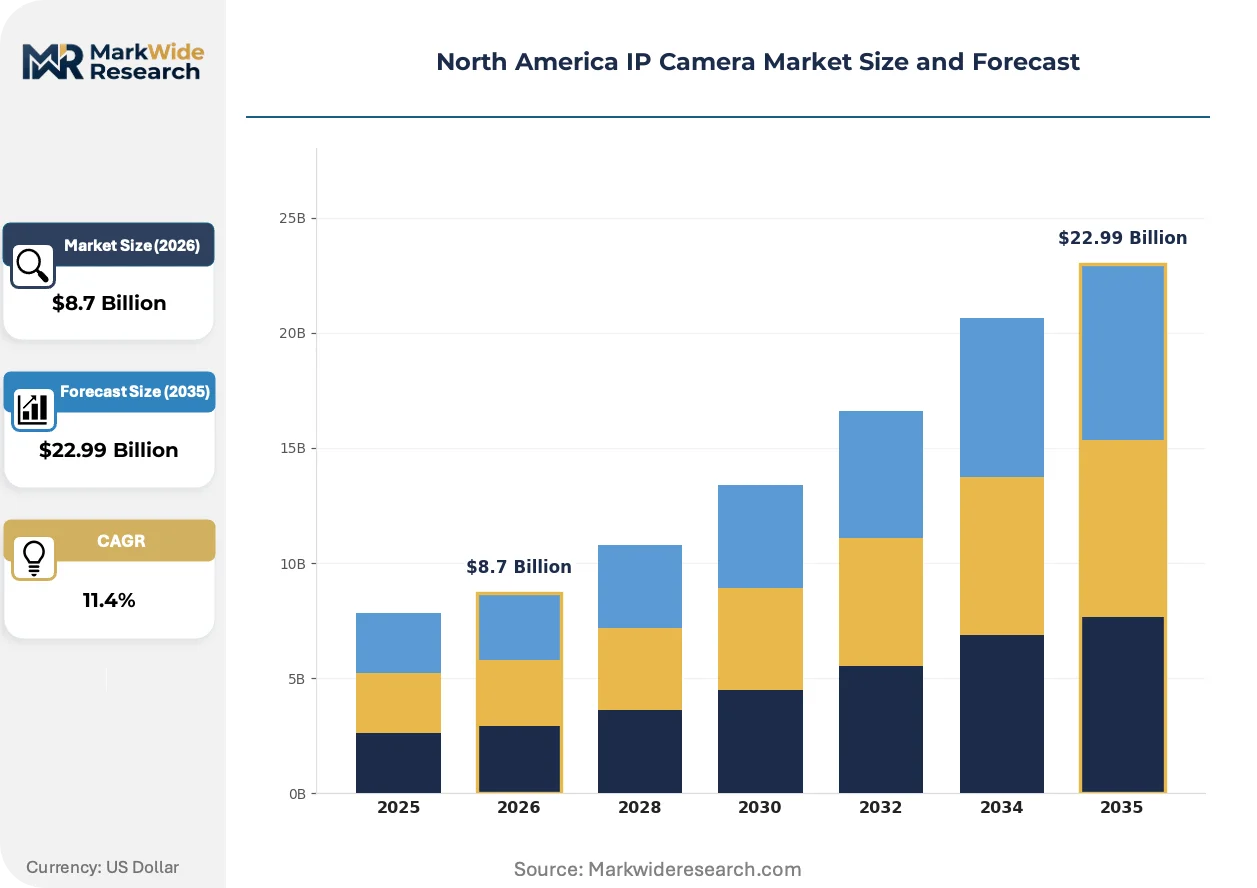
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTZ, Bullet, Dome, Box Technology: Analog, Digital, Wireless, PoE Installation: Indoor, Outdoor, Wall-mounted, Ceiling-mounted End User: Retail, Banking, Transportation, Healthcare |
| Companies Covered | Hikvision USA Inc., Axis Communications Inc., Dahua Technology USA Inc., Bosch Security Systems Inc., Honeywell International Inc., Johnson Controls International plc, Panasonic System Solutions Company of North America, Sony Electronics Inc., Avigilon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America IP Camera Market Trends and Innovations
Edge computing architectures and privacy-preserving analytics are compressing the traditional server-centric surveillance model, while regulatory fragmentation across US states and Canadian provinces forces modular compliance engineering into product roadmaps.
Multi-sensor panoramic cameras with stitched 180-degree fields of view are hybridizing physical security and operational intelligence functions. Warehouse operators and manufacturing facilities in Ohio and Michigan are adopting these units for both perimeter monitoring and production-line quality verification. This convergence is collapsing the historical separation between security and operations technology budgets, forcing vendors to reposition against industrial automation suppliers.
The FCC's 2023 expansion of unlicensed 6 GHz spectrum for Wi-Fi 6E devices is reshaping deployment economics for wireless camera networks. Commercial real estate managers in Dallas and Phoenix are leveraging the additional 1200 MHz of contiguous spectrum to support higher-density camera counts without structured cabling investments. Multi-tenant office buildings with 1970s-era infrastructure represent the most affected segment, with property technology consultants specifying Wi-Fi 6E-native units for competitive leasing differentiation.
Security procurement departments are consolidating vendor relationships to reduce integration complexity and streamline firmware-update management. Enterprise buyers in banking and healthcare verticals are replacing multi-brand environments with single-platform architectures, favoring manufacturers with open API ecosystems and third-party video management system certification. This concentration is most visible in the US Southeast, where regional hospital systems and credit union networks are executing five-year exclusive supply agreements.
North America IP Camera Market Segmentation
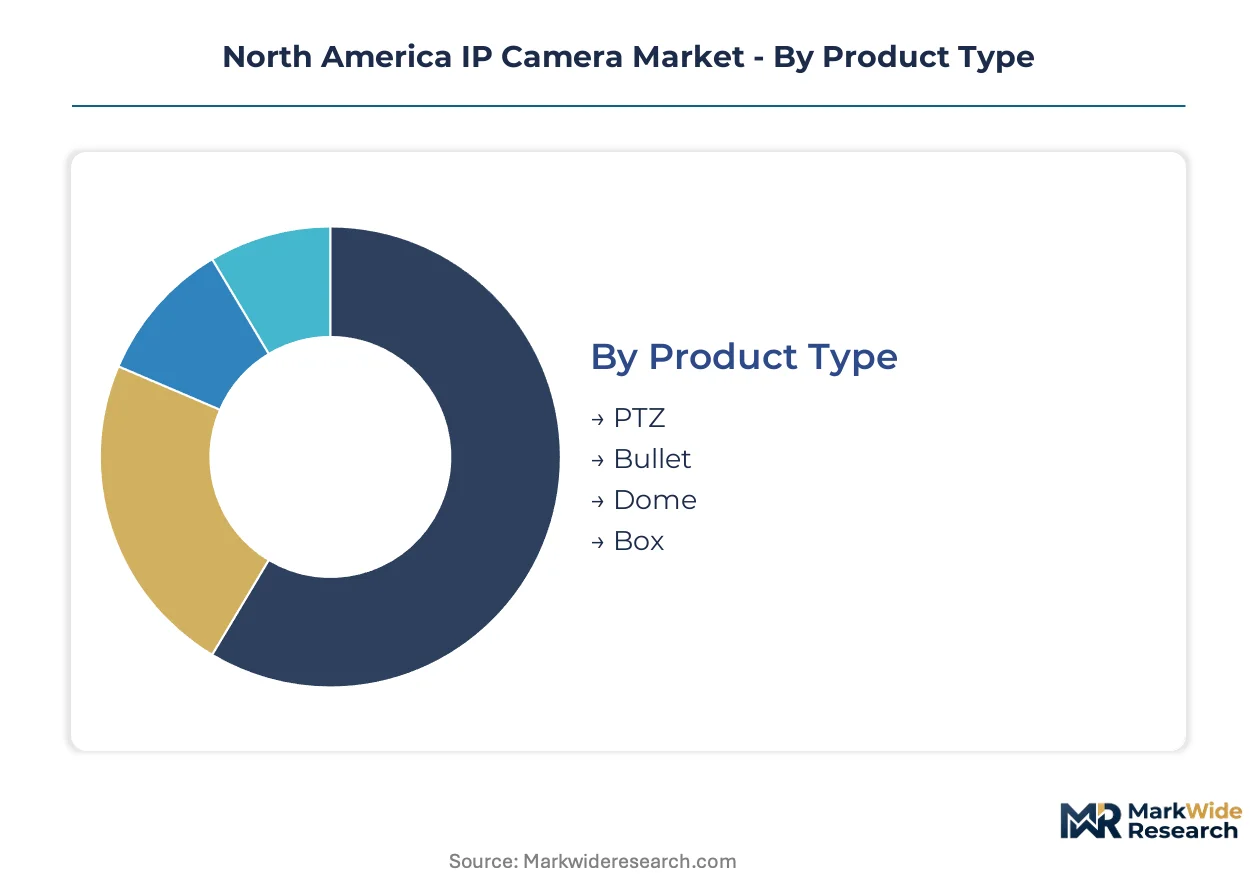
IP camera segmentation in North America reflects divergent buyer priorities across security verticals, with form factor selection driven by vandal exposure, bandwidth constraints, and legacy infrastructure compatibility. Procurement patterns fragment between cost-optimized municipal tenders and premium enterprise deployments requiring edge analytics integration.
Product Type:
Form factor selection maps directly to environmental exposure and operator control requirements across security installations.
- Dome:Hemispherical enclosures with tamper-resistant polycarbonate housings enable discreet positioning in banking lobbies and retail floor plans where aesthetic integration matters. Demand concentrates in Illinois and Texas financial institutions responding to state biometric privacy mandates with privacy-masking dome configurations.
- Bullet:Cylindrical weather-sealed housings with integrated IR illuminators anchor perimeter defense for transportation corridors and border security installations. Texas-California corridor data centers and logistics hubs drive bulk procurement of 4K bullet units with motorized varifocal lenses.
- PTZ:Pan-tilt-zoom mechanisms with optical zoom ranges to 40x serve active monitoring roles in casino operations and critical infrastructure command centers.
- Box:Modular lens-interchangeable platforms support specialized applications requiring C/CS-mount optics for low-light or thermal imaging extensions.
Dome units hold installed capacity in indoor commercial verticals. Bullet cameras are rotating up the share rankings through transportation and critical infrastructure expansion.
Technology:
Connectivity architecture determines deployment economics, with power delivery and signal transmission protocols shaping total installation cost structures.
- PoE:IEEE 802.3bt-compliant power-over-ethernet delivers 90W over single Cat6 cable, collapsing infrastructure requirements for aging commercial building retrofits across the US Sun Belt. Arizona and Nevada property technology consultants specify PoE++ native units to eliminate electrical contractor dependencies.
- Wireless:Wi-Fi 6E-native cameras leveraging FCC 6 GHz unlicensed spectrum enable infrastructure-light deployment in multi-tenant office buildings with 1970s-era structured cabling limitations. Dallas and Phoenix commercial real estate managers adopt wireless density for competitive leasing differentiation.
- Digital:Hardwired Ethernet implementations with dedicated VLAN segmentation serve enterprise buyers prioritizing cybersecurity compliance over installation flexibility.
- Analog:Coax-based legacy systems persist in hybrid upgrade pathways where complete infrastructure replacement is capital-constrained.
PoE technology holds installed capacity across commercial new-build specifications. Wireless connectivity is climbing the fastest as retrofit demand accelerates.
Installation:
Mounting configuration selection reflects environmental sealing requirements and field-of-view optimization for specific surveillance geometries.
- Outdoor:IP67-rated enclosures with integrated heater-blower modules sustain operation across Canadian prairie winters and Arizona desert thermal cycling. Toronto and Vancouver municipal transit authorities specify vandal-resistant outdoor domes with integrated audio analytics.
- Indoor:Recessed ceiling and surface-mount configurations prioritize discreet positioning in healthcare patient areas and retail customer zones.
- Wall-mounted:Vertical surface attachment optimizes downward-angled coverage for parking structure perimeters and loading dock monitoring.
- Ceiling-mounted:Suspended drop-ceiling integration enables 360-degree coverage in open-plan office and warehouse environments.
Outdoor installations hold installed capacity through smart city infrastructure mandates. Indoor mounting configurations are rotating up the share rankings with healthcare and corporate vertical expansion.
End User:
Vertical-specific compliance requirements and operational risk profiles drive divergent feature prioritization across buyer segments.
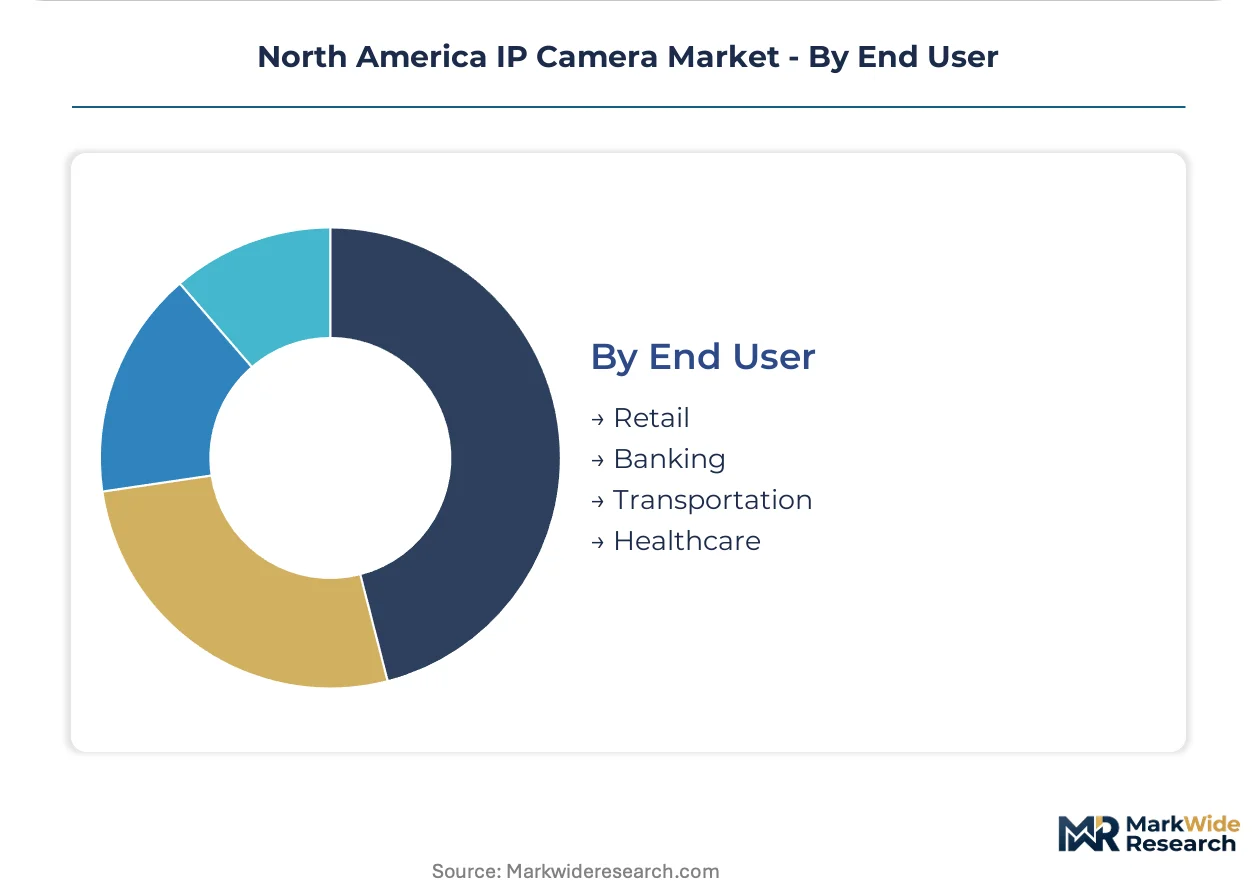
- Transportation:Federal infrastructure packages and state-level modernization programs in California and Texas accelerate bulk procurement for municipal transit hubs and highway monitoring corridors. Edge AI engines for license plate recognition and crowd-flow monitoring displace centralized server architectures in airport and rail deployments.
- Retail:Loss-prevention departments prioritize edge analytics for occupancy counting and queue management while navigating Illinois BIPA and Texas biometric identifier restrictions on facial recognition deployment.
- Banking:NIST cybersecurity frameworks and FedRAMP authorization requirements extend sales cycles for cloud-connected platforms serving federal credit unions and regional bank networks.
- Healthcare:HIPAA-aligned video management and patient privacy masking capabilities constrain feature utilization in multi-state hospital systems consolidating vendor relationships.
Transportation verticals hold installed capacity through federal funding pipelines. Retail applications are rotating up the share rankings with video-surveillance-as-a-service financing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains net import dependence for advanced image sensors and edge AI chipsets, while Canada and Mexico function as assembly and distribution nodes for continental supply chains. Cross-border component flows concentrate through the Texas-California corridor and the Great Lakes manufacturing belt.
United States
Federal infrastructure packages and state transportation modernization programs in Texas and California accelerate bulk procurement of PoE-enabled surveillance networks for municipal transit hubs. The FCC governs radio-frequency emissions for wireless camera systems, while NIST cybersecurity frameworks shape encryption requirements for federal-adjacent installations. The Dallas-Phoenix commercial corridor drives wireless density adoption as property managers leverage Wi-Fi 6E spectrum for competitive leasing differentiation.
Canada
Toronto, Vancouver, and Montreal transit authorities present white-space demand for vandal-resistant dome units with integrated audio analytics. Health Canada aligns medical device cybersecurity guidance with NIST frameworks, creating compliance continuity for healthcare vertical deployments. The Ontario-Quebec corridor concentrates smart city pilot programs, with Toronto's municipal procurement favoring open-architecture platforms for multi-vendor integration.
Mexico
Manufacturing facility security upgrades across Nuevo León and Baja California drive demand for thermal imaging and perimeter monitoring solutions. Mexico's federal telecommunications regulator, IFT, manages spectrum allocation for industrial wireless deployments. The Tijuana-Mexicali border zone anchors cross-border logistics security installations serving US customs and trade compliance requirements.
North America IP Camera Market Competitive Landscape
On the supply side, the industry is bifurcated between scale-driven hardware fabricators and software-specialized platform vendors. The vendor base stratifies across three tiers: multinational conglomerates with integrated building automation portfolios, pure-play video surveillance specialists, and emerging cloud-native service providers. Dominant competitive moves include strategic partnerships between hardware OEMs and managed service platforms, plus portfolio diversification into adjacent access control and building management systems.
Within the scale-driven tier, Hikvision USA Inc. and Dahua Technology USA Inc. exemplify manufacturing-intensive positioning, while Axis Communications Inc. and Avigilon Corporation occupy the premium specialization vector. Bosch Security Systems Inc. and Honeywell International Inc. represent diversified industrial conglomerates leveraging existing building automation channels. Johnson Controls International plc anchors the integrated security-building management convergence archetype.
| Leading Market Players |
|---|
| Hikvision USA Inc. |
| Axis Communications Inc. |
| Dahua Technology USA Inc. |
| Bosch Security Systems Inc. |
| Honeywell International Inc. |
| Johnson Controls International plc |
| Panasonic System Solutions Company of North America |
| Sony Electronics Inc. |
| Avigilon Corporation |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on Chinese-manufactured image sensors and edge AI chipsets compresses hardware margins while forcing North American integrators into dual-sourcing strategies that reshape tier spreads across the procurement landscape. Component concentration in Asian foundries determines both the premium commanded by domestic-certified units and the supply chain redundancy investments required for federal-adjacent installations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with NIST cybersecurity certification and FedRAMP authorization driving spreads between federal-grade and commercial-tier units. Price differentiation stems from encryption hardware integration and volume procurement scale, with municipal tenders squeezing margins through competitive bidding while enterprise healthcare verticals absorb premium positioning for HIPAA-aligned platforms. Pricing pressure stems from subscription-based video-surveillance-as-a-service financing that shifts revenue recognition toward recurring streams. Municipal procurement departments exhibit highest price sensitivity; critical infrastructure operators demonstrate lowest sensitivity due to compliance-driven replacement cycles.
Supply Chain Analysis
Extended payment terms from Taiwan and South Korea foundries strain working capital for North American distributors managing 4K sensor and thermal imaging component flows. Image sensor fabrication draws from concentrated Taiwanese and South Korean capacity, with Chinese assembly operations feeding finished camera modules. Single-source vulnerability in edge AI chipsets sourced from TSMC anchors supply risk for analytics-enabled units. Distribution runs through regional security integrators and managed service providers, with direct OEM relationships penetrating only the largest enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America IP Camera Market sits in a cyclical recovery phase, with federal infrastructure package disbursements and smart city mandate timelines providing predictable demand visibility through municipal procurement pipelines.
For Market Incumbents: Build switching-cost moats through deep integration with third-party video management systems and open API ecosystems that lock enterprise clients into platform architectures. Consolidate vendor relationships in banking and healthcare verticals to reduce firmware-update management complexity for buyers. Threaten emerging cloud-native entrants by embedding edge AI processing that displaces their centralized server value propositions. Leverage backward integration into PoE++ power convergence technologies to capture single-cable infrastructure spend in Sun Belt commercial retrofits.
For New Entrants and Emerging Players: Establish a beachhead in Canadian municipal modernization white space, where Toronto and Vancouver transit authorities seek vandal-resistant dome units with integrated audio analytics underserved by incumbent channel coverage. Target mid-sized security integrators adopting video-surveillance-as-a-service financing platforms that bypass capital-intensive hardware procurement barriers. Penetrate through privacy-masking feature specialization that addresses Illinois BIPA and Texas biometric identifier compliance friction constraining multi-state retail chains.
For Investors and Strategic Acquirers: NIST SP 800-53 and FedRAMP authorization timeline extensions reshape the acquisition landscape by elevating the scarcity value of pre-certified platforms with existing federal contractor relationships. Long-term viability centers on recurring revenue models with sticky integration dependencies rather than transactional hardware margins. Target acquisition archetypes include cloud-native service providers with established managed security service channels. Signal to watch: FCC 6 GHz spectrum utilization rates in Dallas-Phoenix commercial corridors as proxy for wireless density adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Open API certification with Milestone and Genetec VMS platforms locks enterprise switching costs. |
| Strategic Partnership | Managed service provider alliances compress customer acquisition costs for VSaaS financing penetration. |
| Product Launch | Wi-Fi 6E-native units capture retrofit demand in 1970s-era multi-tenant office infrastructure. |
| Acquisition of Specialist Firm | Edge AI computer vision targets address talent scarcity in Seattle and San Francisco labor markets. |
| Geographic Expansion | Toronto and Vancouver transit authority penetration exploits underpenetrated Canadian smart city infrastructure. |
Research Methodology
Cross-validation between primary interviews with security integrators, municipal procurement officers, and enterprise IT directors anchors the qualitative findings, while secondary validation draws from FCC spectrum allocation records, NIST cybersecurity framework documentation, and customs import data for image sensor trade flows. Bottom-up triangulation against top-down federal infrastructure spending disclosures ensures procurement pipeline estimates align with appropriated budget authority. Primary fieldwork encompassed channel partner interviews across the Texas-California corridor and Great Lakes distribution belt, supplemented by video management system vendor certification database analysis.
Calibration against historical municipal tender award patterns and enterprise replacement cycle data informs the projection framework across the analysis window. Segmentation dimensions modeled include form factor selection, connectivity technology, installation environment, and end-use vertical with compliance-tier stratification. CAGRs derive from installed base growth rates adjusted for cybersecurity-driven replacement acceleration and edge AI processing adoption curves. Industry-specific inputs encompass PoE++ power standard penetration rates and Wi-Fi 6E spectrum utilization density metrics in target commercial corridors.
Sensitivities concentrate around semiconductor supply lead-time volatility, FCC spectrum rule modifications, and state-level biometric privacy law expansion. Forecasts reflect documented assumptions regarding federal infrastructure disbursement timelines and NIST framework evolution. Macroeconomic contraction affecting municipal capital budgets, regulatory deviation in biometric capture restrictions, or technological disruption from alternative sensing modalities would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Holotomographic Imaging Market
Imaging
3D Time-Of-Flight Image Sensor Market
Imaging
APAC Thermal Imaging Systems Market
Imaging
Photoacoustic Tomography Market
Imaging
Photography Equipment Market
Imaging
Cinematographic Camera Market
Imaging
Medical X-Ray Detectors Market
Imaging
Digital Microscope Market
Imaging
Instant Digital Cameras Market
Imaging
Global Digital Binoculars Market
Imaging
Mobile Camera Module Market
Imaging
Automotive Compact Camera Module Market
Imaging
Vintage Cameras Market
Imaging
In Vivo Imaging Systems Market
Imaging
Ingaas Image Sensor Market
Imaging
Computer Aided Detection Market