
 North America LED Lighting Market | 2026-2036
North America LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
North America LED Lighting Market Intelligence
The US Department of Energy's appliance efficiency standards is expanding the addressable market for high-efficacy luminaires across commercial and industrial installations. Signify Holding leverages its Interact IoT platform to sustain recurring revenue streams in connected building deployments. Cree Lighting anchors its position in premium commercial downlighting through advanced chip-on-board thermal management. Eaton competes aggressively in specification-grade infrastructure for data centers and healthcare facilities.
LED lighting denotes solid-state illumination systems employing semiconductor diodes that emit light when electrical current excites electron transitions across a p-n junction, typically achieving luminous efficacies exceeding 150 lumens per watt while operating at junction temperatures below 85°C for rated lifespans. These systems serve primarily to displace legacy fluorescent and high-intensity discharge technologies across commercial, industrial, and outdoor infrastructure where energy cost reduction and maintenance interval extension drive procurement economics. Smart lighting technology captures expanding margin pools as building automation integration and sensor fusion command premium pricing over traditional retrofit alternatives. Solar LED applications represent the fastest-growing technology segment across remote and grid-stressed installations in the southwestern United States and northern Mexico where standalone photovoltaic pairing eliminates trenching and utility interconnection costs. Bulbs remain the most mature product category with compressed margins, while fixtures concentrate value capture through specification-driven architectural and outdoor projects.
The US Department of Energy, Natural Resources Canada, and Mexico's Comisión Nacional para el Uso Eficiente de la Energía collectively shape product eligibility through harmonized efficacy thresholds and testing protocols that determine market access across the integrated North American supply base. ENERGY STAR certification and DesignLights Consortium qualified product lists function as de facto procurement filters for utility rebate administrators and municipal specification writers, effectively segmenting competitive position between certified and non-certified suppliers. Stakeholders must monitor the trajectory of federal efficiency rulemakings and provincial building code adoption cycles to anticipate demand inflections and inventory positioning requirements.
Market Dynamics
Commercial building owners across the United States, Canada, and Mexico are compressing lighting replacement cycles as utility rebate programs and state-level building codes render fluorescent systems economically obsolete before physical failure.
Growth Catalysts
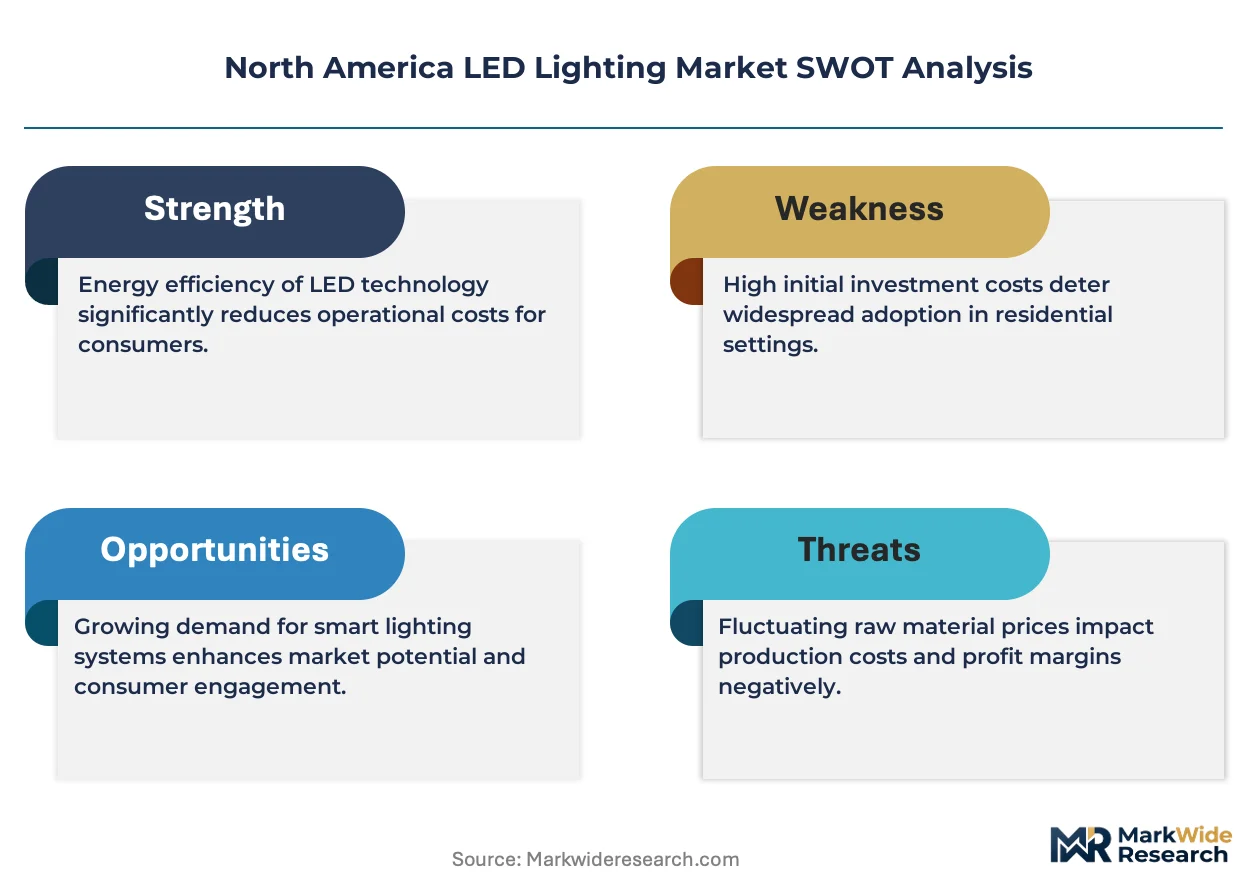
- Utility Rebate Programs:California's investor-owned utilities and Texas municipal power authorities offer tiered incentives that accelerate payback periods for high-efficacy LED retrofits in office and retail assets.
- ENERGY STAR Specification Updates:The US Department of Energy's tightening efficacy thresholds are disqualifying marginal LED products and concentrating procurement toward qualified product lists.
- Data Center Construction:Hyperscale facility operators in Virginia, Texas, and Ontario are specifying tunable white and circadian lighting systems for 24/7 operational environments.
Market Restraints
- Semiconductor Supply Concentration:LED chip fabrication concentrates in East Asian foundries, exposing North American fixture assemblers to lead time volatility and tariff exposure.
- Legacy Ballast Infrastructure:Millions of commercial buildings retain functional fluorescent troffers with years of remaining rated life, creating sunk-cost friction against early replacement.
- Copper and Aluminum Input Costs:Heat sink and driver housing materials face commodity price swings that compress margin stability for specification-grade manufacturers.
Strategic Opportunities
- Human-Centric Lighting:Circadian rhythm and tunable white systems command premium positioning in healthcare and education verticals where wellness metrics drive specification.
- Solar-LED Pairing:Standalone photovoltaic-powered street and area lighting eliminates trenching costs across remote southwestern US and northern Mexican installations.
- Interact IoT Platforms:Connected building systems integrating occupancy sensing, daylight harvesting, and HVAC coordination create recurring software revenue streams beyond hardware sales.
Industry Challenges
- DLC Certification Timelines:DesignLights Consortium qualification testing creates 4-6 month delays between product launch and rebate eligibility, compressing effective sales windows.
- Legacy Control Protocol Fragmentation:DALI, 0-10V, and emerging wireless standards require manufacturers to maintain multiple driver SKUs and complicate specification support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America LED Lighting Market |
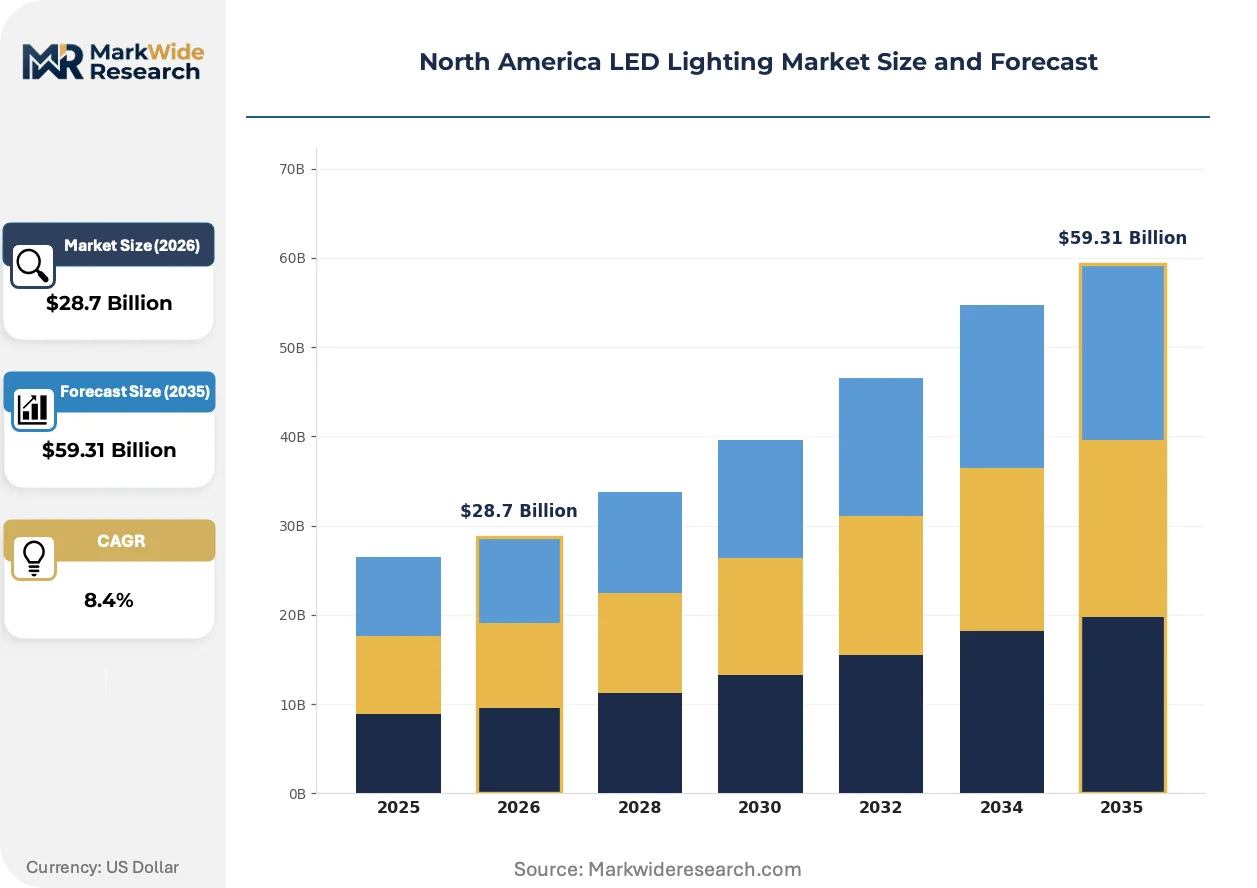
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Fixtures, Strips, Modules Application: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, Human-Centric Lighting, Solar LED, Traditional End User: Contractors, Retailers, Manufacturers, Government |
| Companies Covered | Acuity Brands Lighting, Inc., Signify Holding, Cree Lighting, ams OSRAM AG, Eaton, Hubbell, General Electric, Nichia Corporation, LSI Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America LED Lighting Market Strategic Shifts & Innovations
Chip-on-board thermal management and human-centric spectral tuning are redefining competitive differentiation beyond raw efficacy metrics, while procurement patterns shift toward integrated building automation specification.
Chip-on-board LED arrays are electrifying premium commercial downlighting by eliminating traditional package-and-substrate thermal resistance. High-end hospitality and corporate headquarters specifiers in Manhattan, Toronto, and Los Angeles are adopting these packages for 50,000-hour maintenance-free operation. The technology is electrifying margin capture in architectural specification segments where thermal performance validates premium positioning against commodity SMD alternatives.
Natural Resources Canada's amendment to the Energy Efficiency Regulations is tightening standby power limits for connected luminaires and eliminating least-efficient product tiers from federal procurement eligibility. Fixture manufacturers serving Canadian commercial and institutional channels are redesigning driver architectures to meet sub-0.5W standby thresholds. The policy compresses demand most severely in Ontario's municipal and healthcare sectors where federal funding compliance is mandatory.
Building automation specification is consolidating lighting procurement decisions under facilities management rather than traditional electrical contractor channels. Master systems integrators in Texas and California are bundling lighting controls with HVAC and security platforms, displacing standalone fixture distributors. This concentration is most visible in Class A office developments across Dallas-Fort Worth and Silicon Valley where single-source building performance contracts dominate new construction.
North America LED Lighting Market Segmentation
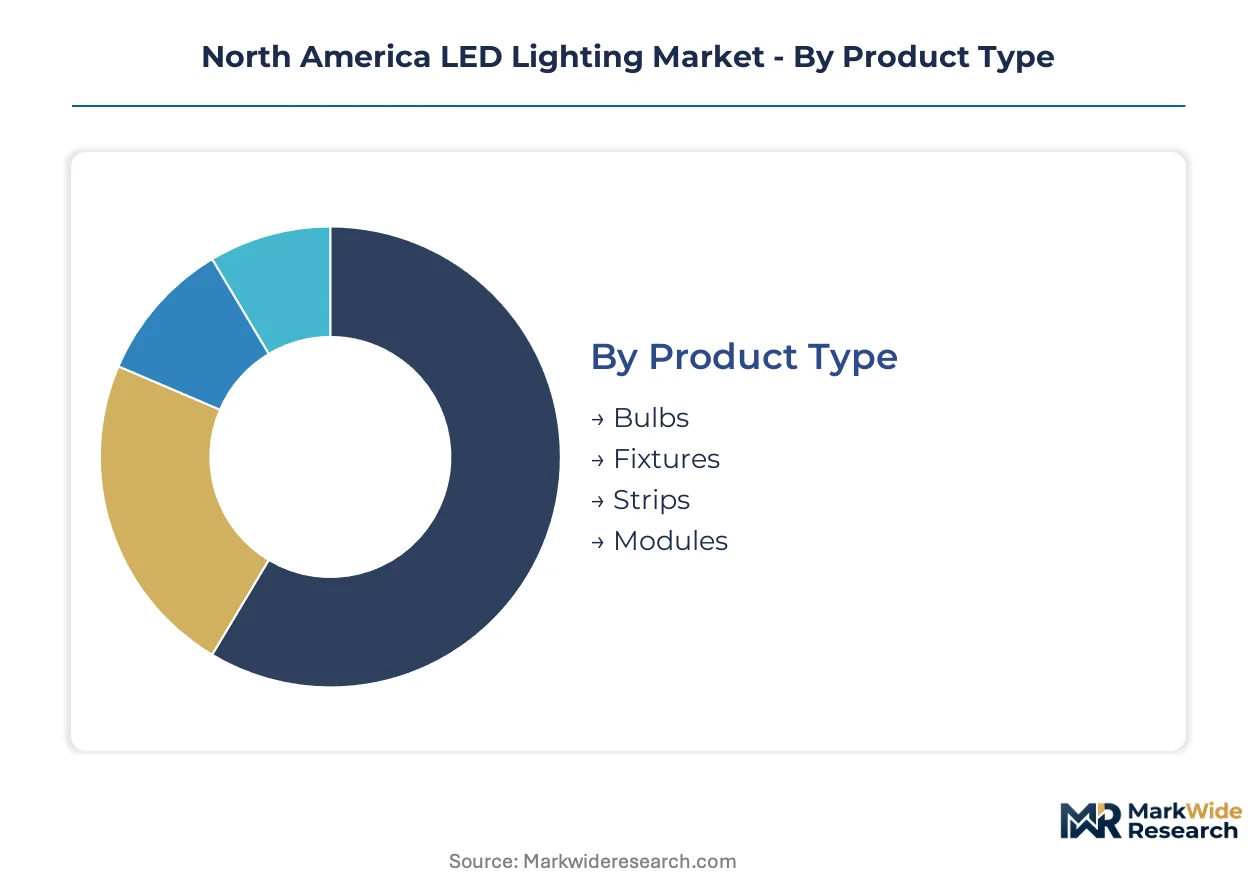
LED lighting procurement decisions fragment across multiple technical and commercial dimensions, with certification requirements and rebate eligibility creating sharp segmentation boundaries. Understanding how product specifications, application contexts, and buyer categories intersect determines effective market positioning.
Product Type:
ENERGY STAR certification applies universally across bulbs and fixtures, while DLC qualification concentrates rebate access for commercial-grade troffers and high-bay units. Strips and modules face fragmented standards depending on integration depth.
- Fixtures:Specification-grade luminaires incorporating chip-on-board thermal architecture and integrated drivers dominate commercial retrofit volumes. Demand concentrates in California office assets and Texas retail portfolios where utility administrators require DLC Premium qualification for maximum rebate tiers.
- Bulbs:Standard A19 and PAR form factors serve residential replacement cycles with compressed margins, though ENERGY STAR certification maintains procurement relevance for big-box retail channels. The category faces displacement pressure as integrated LED fixtures extend rated lifespans in new construction.
- Strips:Linear flexible arrays serve cove and accent applications in hospitality and retail environments.
- Modules:Removable light engines enable field-serviceable retrofits of existing housing infrastructure.
Leading the category by volume: Fixtures. Growing fastest: Modules.
Application:
Cost tier stratification separates specification-driven commercial installations from price-sensitive residential retrofits, with industrial and outdoor segments occupying intermediate positions based on operating hour intensity.
- Commercial:Office, retail, and hospitality assets drive premium fixture specification through 24/7 operating profiles and rebate-optimized procurement. California Title 24 compliance and Ontario building code stringency compress fluorescent replacement timelines in Class A properties.
- Industrial:High-bay and hazardous-location luminaires emphasize thermal endurance and ingress protection for manufacturing and warehousing environments. Texas petrochemical corridors and Ontario automotive plants specify explosion-rated LED arrays with 100,000-hour L70 targets.
- Outdoor:Street, area, and floodlighting applications balance efficacy with optical control for municipal and utility-scale deployment.
- Residential:Big-box and e-commerce channels dominate bulb and downlight sales with minimal specification friction.
Commercial commands the largest revenue pool. Outdoor applications are climbing the fastest as solar-LED pairing eliminates interconnection barriers.
Technology:
Margin concentration tracks connectivity depth, with sensor-integrated systems capturing software recurring revenue while basic efficacy improvements face commoditization.
- Smart Lighting:Networked luminaires with embedded occupancy sensing, daylight harvesting, and HVAC integration command premium positioning in new construction and deep retrofit scenarios. Signify's Interact platform and competing building automation protocols concentrate specification decisions in Texas and California master systems integrator channels.
- Solar LED:Standalone photovoltaic-powered street and area lighting eliminates trenching and utility interconnection costs across remote southwestern US installations and northern Mexican grid-stressed regions. The segment gains share fastest where distribution infrastructure is sparse.
- Human-Centric Lighting:Circadian-tunable and melanopic-optimized spectral systems serve healthcare and education verticals.
- Traditional:Non-connected, fixed-output LED arrays occupy replacement-driven residential and basic commercial segments.
Traditional technology retains volume leadership. Solar LED is gaining share fastest.
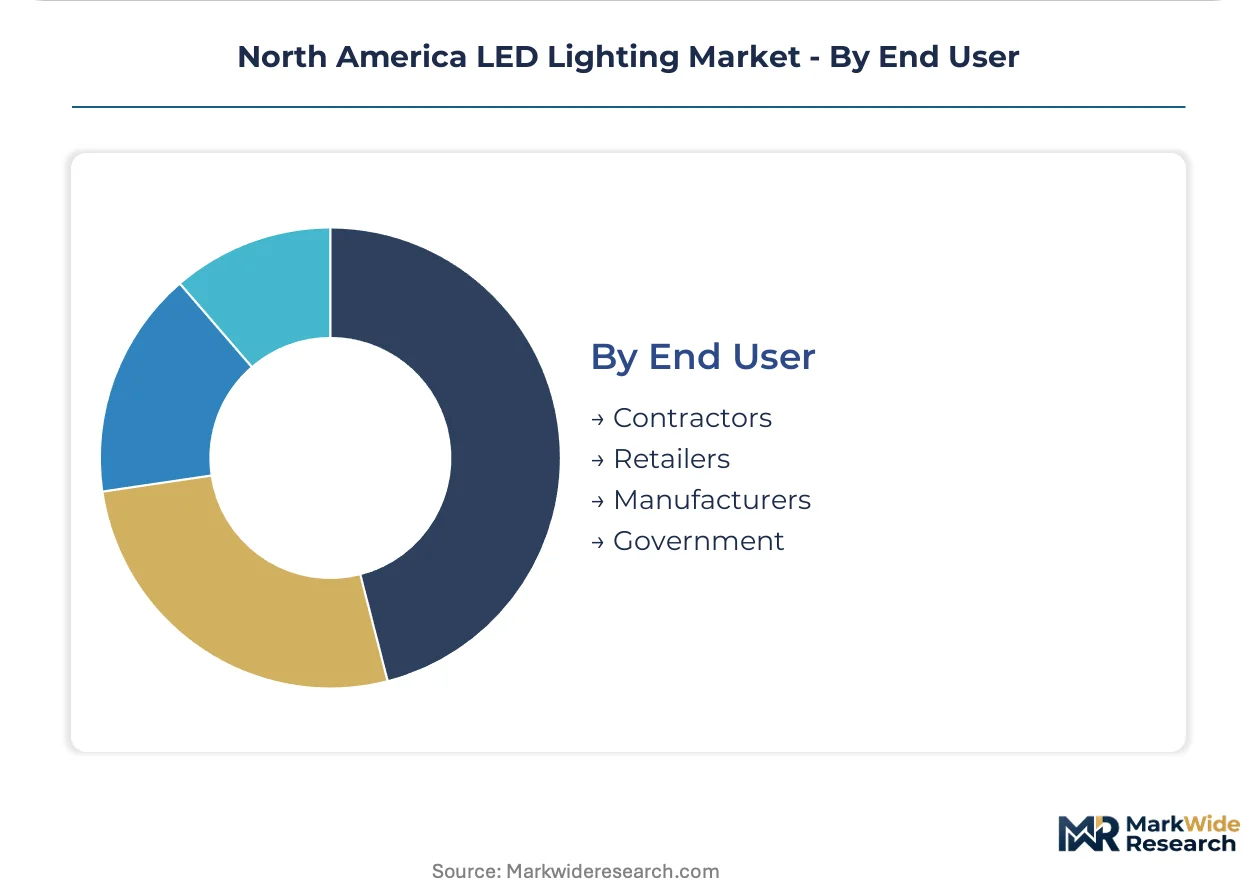
End User:
Customer type determines specification authority and procurement rhythm, with contractors and government buyers operating under distinct compliance frameworks.
- Contractors:Electrical and lighting contractors control retrofit specification in existing buildings, with purchasing influenced by distributor stocking programs and local utility rebate administration. California and Texas contractor channels concentrate volume through performance-contracting arrangements.
- Government:Federal, state, and municipal procurement operates under ENERGY STAR and FEMP efficiency mandates with domestic content preferences. Canadian federal procurement through Public Services and Procurement Canada enforces standby power limits that disqualify non-compliant luminaires.
- Retailers:Big-box and specialty lighting stores serve residential replacement and small commercial project demand.
- Manufacturers:OEM and fixture assembler procurement of LED engines and drivers supplies downstream assembly operations.
Contractors lead by transaction volume. Government procurement is expanding most quickly through infrastructure stimulus allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dallas-Fort Worth metroplex anchors North American LED specification activity through hyperscale data center construction and Class A office development. Utility rebate corridors in Texas and California concentrate procurement volume. Provincial building codes in Ontario and federal efficiency mandates across all three nations reshape fixture eligibility.
United States
California's Title 24 building standards and Texas municipal utility rebates compress fluorescent replacement timelines in commercial assets. The US Department of Energy's ENERGY STAR specification updates disqualify marginal LED products from federal procurement eligibility. Dallas-Fort Worth and Silicon Valley master systems integrators bundle lighting controls with HVAC platforms in new Class A construction.
Canada
Natural Resources Canada's Energy Efficiency Regulations amendment tightens standby power limits for connected luminaires below 0.5W. Ontario's municipal and healthcare sectors face mandatory federal funding compliance that eliminates non-compliant fixtures. Toronto and Vancouver specification channels concentrate demand for DLC Premium-qualified troffers in commercial retrofit programs.
Mexico
Grid-stressed northern states and remote southwestern regions drive standalone solar-LED street lighting deployment without trenching costs. The Comisión Nacional para el Uso Eficiente de la Energía shapes product eligibility through harmonized efficacy thresholds with US and Canadian protocols. Monterrey and Mexico City industrial corridors specify explosion-rated LED arrays for manufacturing and petrochemical facilities.
North America LED Lighting Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and thermal architecture sophistication. The vendor base stratifies between specification-grade architectural fixture specialists, connected building platform operators, and volume-driven bulb and component suppliers. Two strategic archetypes dominate: IoT-integrated system providers capturing recurring software revenue, and chip-on-board thermal specialists commanding architectural specification. Competitive moves concentrate on strategic partnerships with master systems integrators and portfolio diversification into human-centric spectral tuning.
Within the connected building platform tier, Signify Holding exemplifies the IoT-integrated archetype through its Interact platform positioning. Acuity Brands Lighting, Inc. and Cree Lighting occupy specification-grade fixture positions where thermal management and rebate eligibility determine procurement outcomes. Eaton and Hubbell represent the infrastructure-specialist archetype in data center and healthcare verticals. These five entities illustrate the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Acuity Brands Lighting, Inc. |
| Signify Holding |
| Cree Lighting |
| ams OSRAM AG |
| Eaton |
| Hubbell |
| General Electric |
| Nichia Corporation |
| LSI Industries Inc. |
| Others |
Cost & Logistics Intelligence
Utility rebate program administrators in California and Texas are tightening efficacy thresholds for maximum incentive tiers, forcing fixture assemblers to source premium LED chips and advanced thermal components that compress margin structures at the mid-market tier. This procurement pressure cascades upstream, concentrating supplier power among qualified component vendors while squeezing non-certified assemblers into price-competitive residential segments.
Pricing Analysis
Outcome-based pricing tied to energy savings verification anchors commercial retrofit contracts, with master systems integrators in Dallas-Fort Worth and Silicon Valley bundling lighting controls into building performance guarantees. Three-tier pricing structure across premium, standard, and economy levels separates DLC Premium-qualified architectural fixtures from basic troffers and commodity bulbs. Cost compression in the bulb category is intensifying because integrated LED fixtures are extending replacement cycles in new construction. Residential big-box buyers exhibit highest price sensitivity, while healthcare and data center specifiers prioritize thermal performance and certification compliance over unit cost.
Supply Chain Analysis
Workforce availability constraints in Taiwan, South Korea, and China's Guangdong province are tightening LED chip fabrication capacity, extending lead times for North American fixture assemblers. The supply chain draws from gallium nitride wafers, aluminum heat sinks, and copper driver housings sourced through East Asian foundries and Mexican maquiladora operations. Tariff exposure on Chinese semiconductor imports creates margin volatility for specification-grade manufacturers lacking alternative sourcing. Distribution runs through electrical distributor networks in California and Texas, with master systems integrators increasingly controlling direct procurement for new Class A construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America LED Lighting Market sits in a technology-transition phase where solid-state systems are displacing legacy fluorescent infrastructure ahead of physical failure, with chip-on-board thermal architecture and human-centric spectral tuning commanding premium positioning.
For Market Incumbents: Acquire connected building software capabilities and IoT platform assets to capture recurring revenue streams beyond hardware sales. Defensive consolidation should target thermal management specialists in chip-on-board architecture and DLC Premium qualification expertise, as emerging platform competitors threaten specification-grade fixture margins through bundled building automation contracts. For New Entrants and Emerging Players: Enter via solar-LED pairing for remote southwestern US and northern Mexican grid-stressed installations, where standalone photovoltaic deployment eliminates incumbent distributor channels. Target municipal street lighting and rural area illumination segments with lowest penetration of established specification-grade suppliers, leveraging direct utility relationships and bypassing traditional electrical contractor networks. For Investors and Strategic Acquirers: Re-rating potential sits with IoT-integrated platform operators given building automation consolidation in Texas and California master systems integrator channels. Long-term viability favors vendors with captive software revenue and human-centric lighting R&D pipelines. Monitor ENERGY STAR specification update trajectories as the inflection signal for qualification-driven demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Signify's Interact IoT platform captures recurring software revenue beyond hardware sales in connected building deployments. |
| Backward Integration | Cree Lighting's chip-on-board thermal management secures specification-grade positioning in premium commercial downlighting. |
| Certification Investment | DLC Premium qualification unlocks maximum utility rebate tiers in California and Texas procurement corridors. |
| Geographic Expansion | Solar-LED pairing eliminates trenching costs across remote southwestern US and northern Mexican installations. |
| Strategic Partnership | Eaton's data center and healthcare infrastructure focus leverages specification-grade relationships with master systems integrators. |
Research Approach
Multi-period observation of utility rebate program evolution, ENERGY STAR specification trajectories, and DLC qualification timelines anchored the trend analysis, supplemented by interviews with electrical contractor procurement heads, master systems integrators in Texas and California, municipal lighting program administrators, and fixture manufacturer product managers. Secondary validation drew from US Department of Energy appliance efficiency filings, Natural Resources Canada regulatory amendments, DesignLights Consortium qualified product databases, and SEC 10-K disclosures from listed lighting vendors. Bottom-up segmentation modeling and top-down macroeconomic triangulation cross-validated volume and value estimates.
Input-output matrices mapped LED chip supply from East Asian foundries through North American fixture assembly and distributor channels, with segmentation across product type, application, technology, and end-user categories modeled throughout the forecast period. CAGRs derived from regression analysis of historical replacement cycle compression, rebate program saturation curves, and building code adoption rates. Industry-specific forecast inputs included hyperscale data center construction pipelines in Virginia, Texas, and Ontario, plus solar-LED deployment trajectories in grid-stressed regions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption, tariff regime shifts, or accelerated federal efficiency rulemakings. Material deviation in ENERGY STAR specification timing, DLC certification backlog duration, or copper and aluminum commodity volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Pixel Pitch LED Market
LED
UV-C LED Market
LED
Brazil LED Market
LED
China Outdoor LED Lighting Market
LED
China LED Lighting Market
LED
High Power LED Market
LED
Bluetooth LED Bulb Market
LED
Smart LED Indoor Signage Market
LED
LED Street Light Drivers Market
LED
China Indoor LED Lighting Market
LED
Asia Pacific LED Lighting Market
LED
LED Tube Drivers Market
LED
UAE LED Lights Market
LED
Japan Indoor LED Lighting Market
LED
Surface Mount PLCC Leds Market
LED
LED Floodlight Drivers Market