
 3D Time-Of-Flight Image Sensor Market | 2026-2036
3D Time-Of-Flight Image Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
3D Time-Of-Flight Image Sensor Market Analysis
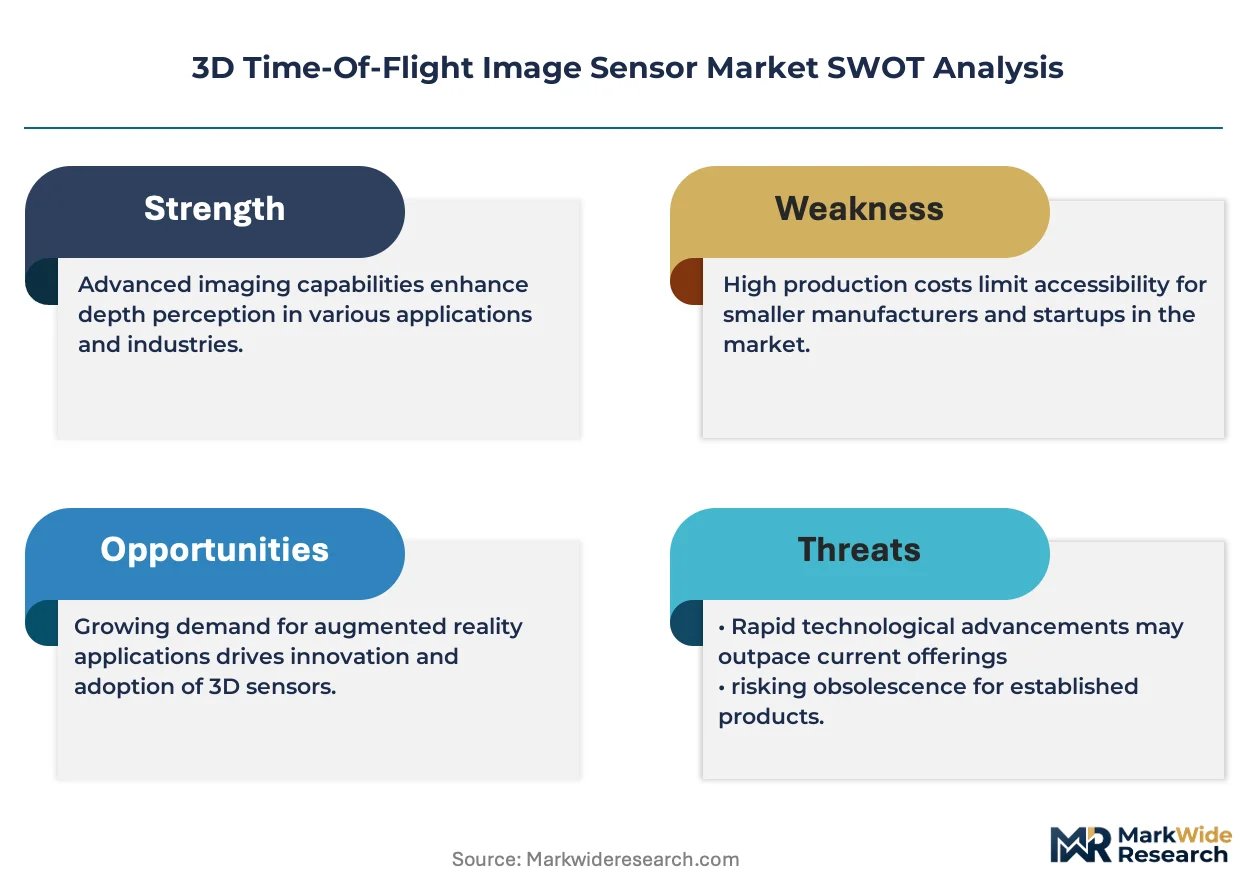
REACH compliance is pivoting the cost-of-entry calculus for European suppliers of 3D time-of-flight modules, forcing reformulation of infrared emitter materials and subassembly chemistries. Sony Semiconductor Solutions leverages captive CMOS foundry capacity to sustain margin control across high-resolution sensor tiers. STMicroelectronics anchors its position through FlightSense architecture specialization in proximity and ranging applications. Infineon Technologies competes by integrating MEMS scanning with time-of-flight signal chains for automotive lidar convergence.
3D time-of-flight image sensors measure depth by calculating photon transit time between emitter and receiver arrays, typically operating at near-infrared wavelengths with modulation frequencies above 10 MHz to achieve millimeter-scale precision in real-time spatial mapping. These devices serve industrial and commercial purposes spanning autonomous navigation, biometric authentication, gesture recognition, and volumetric measurement. Monocular sensors dominate unit economics in consumer electronics, while fused sensor architectures command premium positioning in robotics and automotive where multi-modal redundancy proves essential. CMOS technology leads wafer-level integration, though infrared-enhanced variants are gaining traction in security and healthcare end-user segments where ambient-light rejection determines system efficacy.
FDA device-classification pathways shape healthcare adoption timelines for surgical navigation and patient-monitoring implementations, while FCC Part 15 emission limits constrain laser-power budgets for indoor consumer deployments. The EU AI Act imposes conformity-assessment obligations on biometric applications, directly affecting security and smart-home product roadmaps. Stakeholders must monitor evolving interoperability standards between time-of-flight and complementary depth modalities to preserve design-win flexibility across robotics and automotive platforms.
Market Dynamics
Automotive ADAS integration is compressing sensor qualification timelines while EU AI Act conformity assessments force parallel validation tracks for biometric and safety-critical deployments.
Growth Catalysts
- EU AI Act biometric mandates:Security and smart-home OEMs must embed certified depth-sensing hardware, creating pull-through for validated ToF modules.
- Industrial automation in Germany:Factory digitization programs require real-time volumetric measurement for robotic bin-picking and quality inspection.
- Multi-modal sensor fusion:Autonomous vehicle platforms combine ToF with lidar and radar, expanding addressable silicon area per vehicle.
Market Restraints
- Indium gallium arsenide cost volatility:Near-infrared detector materials face supply concentration from limited epitaxial wafer sources.
- FCC Part 15 emission ceilings:Indoor consumer devices face hard caps on laser power, constraining range performance in ambient-light conditions.
- Stereo vision substitution:Passive depth estimation using dual-camera arrays eliminates emitter costs in price-sensitive mobile applications.
Strategic Opportunities
- India PLI scheme for electronics:Localized module assembly incentives attract ToF packagers serving domestic smartphone and automotive markets.
- Surgical navigation systems:FDA 510(k) pathways for optical tracking create premium positioning for medical-grade ToF subsystems.
- ToF-lidar convergence:Solid-state scanning architectures merge MEMS beam steering with direct time-of-flight signal chains for automotive long-range perception.
Industry Challenges
- Multi-physics simulation expertise:Concurrent optical, thermal, and electrical modeling for compact modules exceeds available talent pools.
- ISO 26262 functional safety certification:Automotive ASIL ratings require fault-mode analysis extending development cycles.
- Interoperability standard gaps:Proprietary depth data formats between ToF and structured-light systems complicate multi-sensor integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Time-Of-Flight Image Sensor Market |
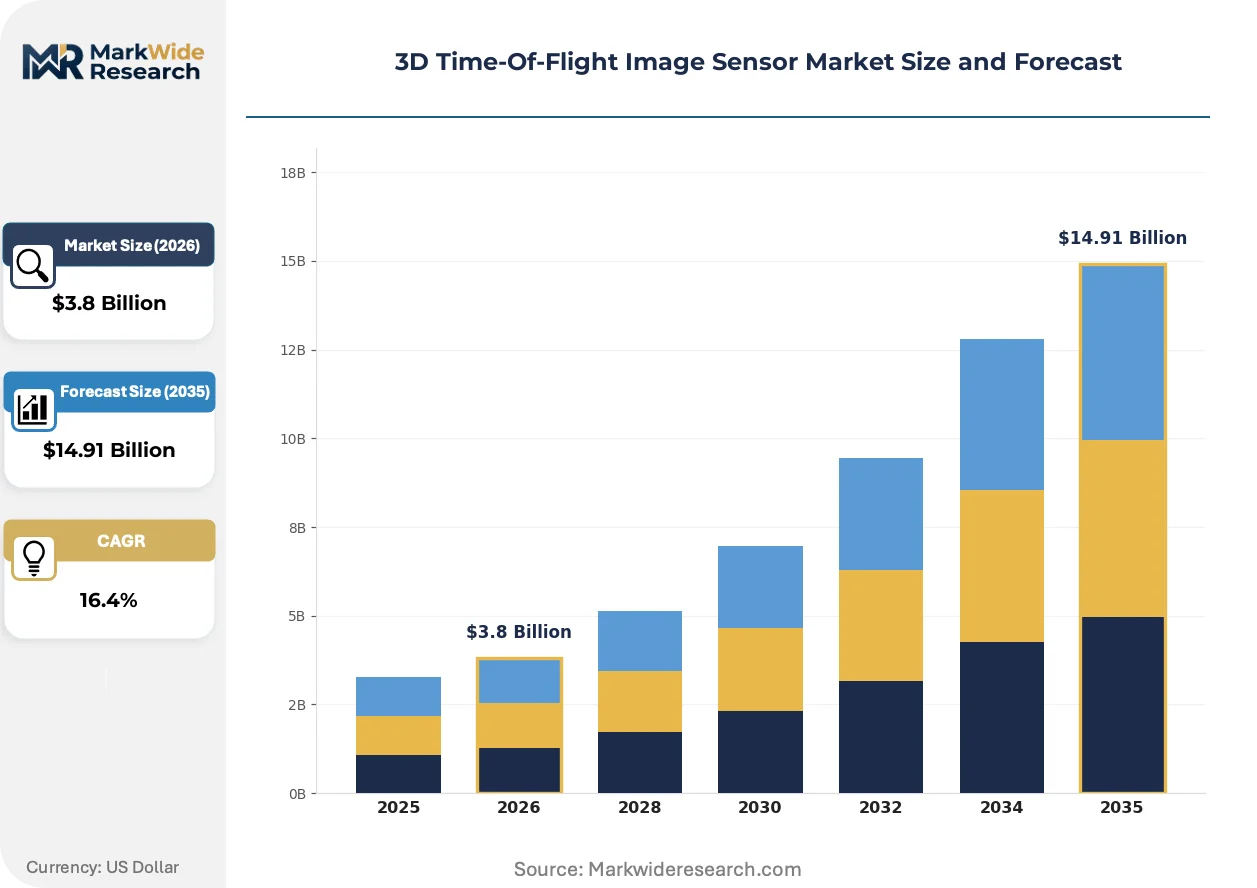
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocular Sensor, Stereo Sensor, Fused Sensor, LiDAR Sensor Application: Automotive, Robotics, Gaming, Security End User: Consumer Electronics, Industrial Automation, Healthcare, Smart Home Technology: CMOS, CCD, Infrared, Laser |
| Companies Covered | Sony Semiconductor Solutions, Panasonic Corporation, STMicroelectronics, ON Semiconductor, ams-OSRAM, Texas Instruments, Samsung Electronics, PMD Technologies, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Time-Of-Flight Image Sensor Market Emerging Trajectories
Silicon photonics integration and regulatory harmonization are compressing form factors while expanding permissible use cases across automotive and healthcare verticals.
Indirect time-of-flight architectures using photon-counting avalanche photodiodes are overtaking traditional continuous-wave phase-detection methods in long-range automotive lidar. Tier-1 suppliers in Germany and Japan are qualifying these sensors for highway-speed object detection. The shift is overtaking incumbent CMOS-based proximity solutions in premium vehicle programs.
REACH substance restrictions on cadmium and lead in infrared emitter packages are forcing material transitions to indium phosphide and aluminum gallium arsenide compounds. ECHA authorization requirements now cover critical dopants used in VCSEL fabrication. European module assemblers are redesigning subassemblies to maintain CE marking compliance.
Subscription-based sensor calibration services are replacing upfront hardware purchases in industrial automation deployments. System integrators in South Korea and Taiwan now bundle depth-sensing hardware with cloud-based drift correction and firmware updates. This model concentrates in semiconductor fabrication facilities requiring continuous metrology validation.
3D Time-Of-Flight Image Sensor Market Segmentation
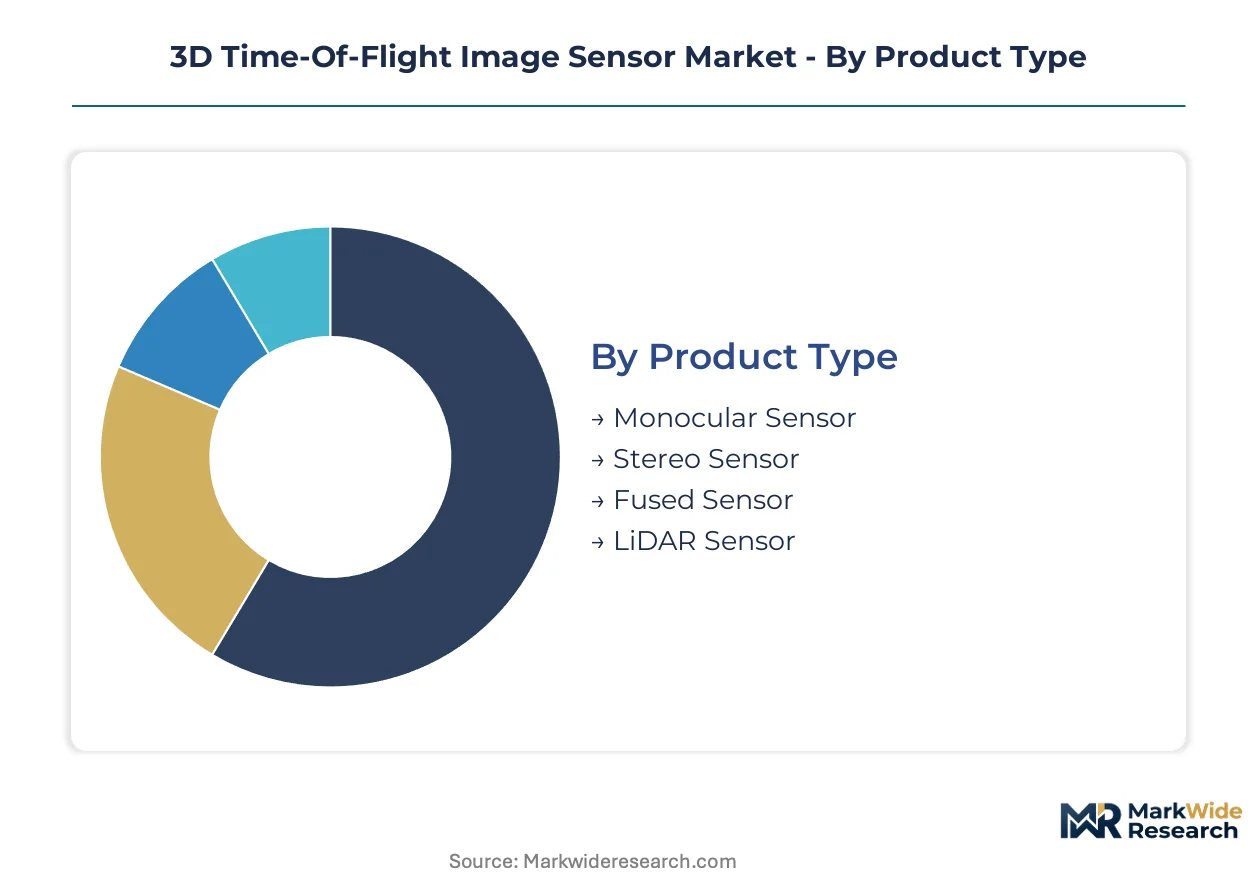
Segmentation in 3D time-of-flight sensors reveals how architectural choices cascade through cost structures, certification burdens, and integration complexity. Buyers select configurations based on range requirements, ambient-light immunity, and safety-critical validation needs.
Product Type:
Buyers differentiate by optical complexity and redundancy requirements, with cost sensitivity widening gaps between consumer and automotive-grade specifications.
- Monocular Sensor:Single-lens architectures using amplitude-modulated continuous-wave phase detection dominate smartphone face authentication and gesture interfaces. Unit economics favor high-volume consumer electronics manufacturers in South Korea and Taiwan, though FCC Part 15 power constraints limit effective range in daylight conditions.
- Fused Sensor:Multi-modal architectures combining time-of-flight with structured light or stereo vision deliver redundancy for robotics and ADAS applications. German automotive OEMs mandate fused configurations for highway-speed autonomous functions where single-sensor failure modes prove unacceptable.
- Stereo Sensor:Dual-aperture designs eliminate active illumination costs in price-sensitive mobile deployments.
- LiDAR Sensor:Scanning architectures with MEMS beam steering address long-range automotive perception.
Volume sits with monocular configurations; growth tilts toward fused architectures.
Application:
Regulatory intensity varies sharply across use cases, with automotive and security deployments facing conformity assessments that consumer gaming avoids.
- Automotive:ADAS integration demands ISO 26262 ASIL-rated sensors with fault-tolerant signal chains. KBA-type approval processes in Germany and type certification in Japan compress development timelines for tier-1 suppliers.
- Security:Biometric access control and surveillance systems trigger EU AI Act conformity obligations for high-risk applications. CE marking now requires documented performance validation against spoofing attacks.
- Robotics:Warehouse automation and service robots drive demand for compact, low-latency depth sensing.
- Gaming:Console and VR headset integration prioritizes low-cost, short-range spatial mapping.
Security applications carry the heaviest compliance burden; robotics is expanding most quickly.
End User:
Procurement sophistication separates industrial buyers with metrology validation requirements from consumer OEMs optimizing bill-of-materials costs.
- Industrial Automation:Factory digitization programs in Germany require continuous calibration and drift correction for robotic bin-picking and dimensional inspection. Subscription-based sensor-as-a-service models are displacing capital purchases in semiconductor fabrication facilities.
- Healthcare:Surgical navigation and patient monitoring systems follow FDA 510(k) pathways with optical tracking subsystems commanding premium pricing. Medical-grade validation extends development cycles but creates defensive positioning against consumer-tier competition.
- Consumer Electronics:Smartphone and tablet integration drives monocular sensor volumes with compressed margins.
- Smart Home:Gesture-controlled appliances and security cameras balance cost against ambient-light performance.
Industrial automation captures the steepest expansion trajectory; consumer electronics holds volume concentration.
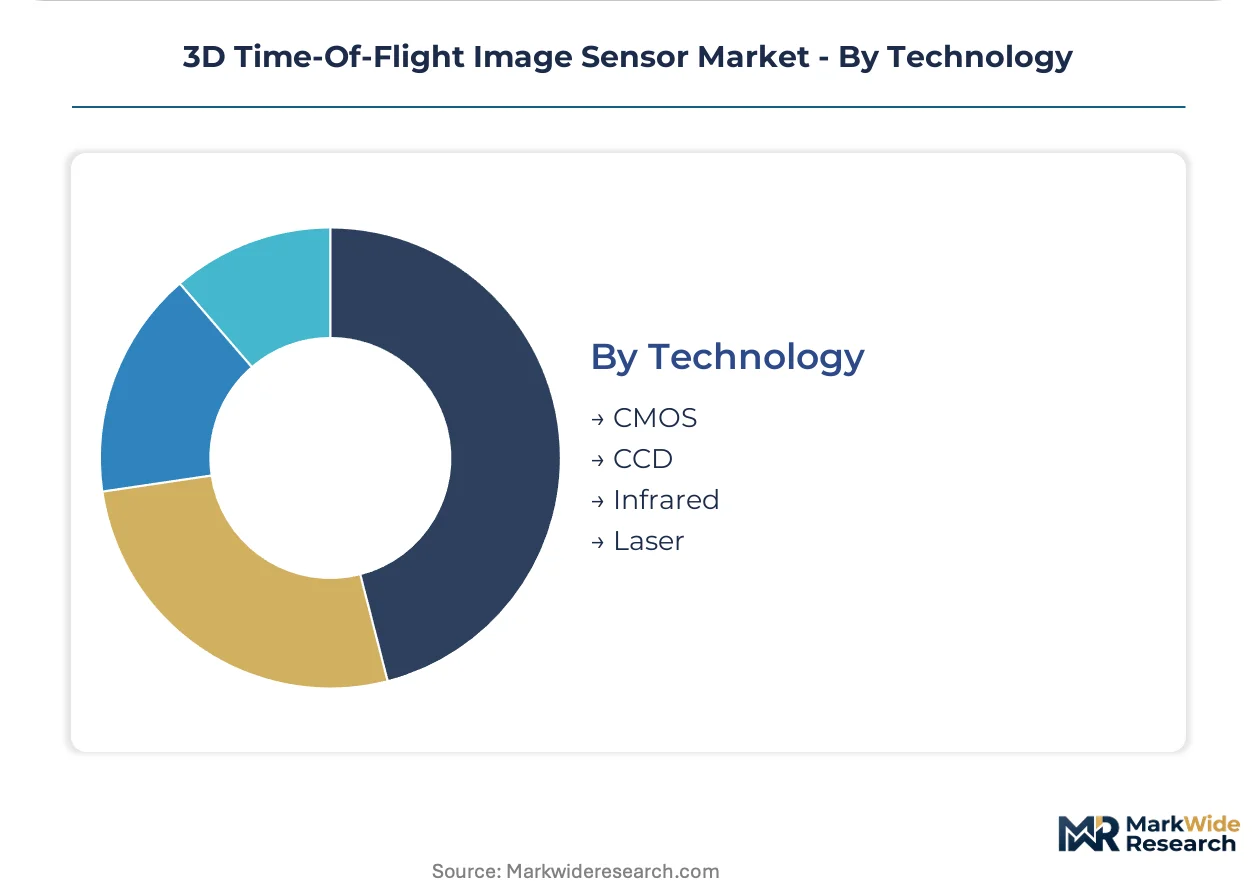
Technology:
Wafer-level integration capabilities and material compatibility with infrared emitters determine foundry partnerships and cost structures.
- CMOS:Standard and infrared-enhanced variants enable wafer-scale integration with backside-illumination architectures. Sony Semiconductor Solutions and STMicroelectronics leverage captive or preferred foundry relationships to control sensor die costs across resolution tiers.
- Infrared:Near-infrared-enhanced detector arrays with spectral selectivity above 850 nanometers dominate security and healthcare where ambient-light rejection determines system efficacy. REACH compliance is forcing material transitions away from cadmium-containing compounds.
- CCD:Legacy charge-coupled device architectures persist in specialized metrology instruments.
- Laser:Direct time-of-flight using pulsed laser diodes addresses long-range automotive lidar convergence.
CMOS dominates wafer output; infrared variants are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Hsinchu anchor wafer-level integration capacity. Korea's Pyeongtaek cluster concentrates VCSEL epitaxy supply. Germany's Saxony-Thuringia corridor houses automotive qualification facilities.
United States
FDA 510(k) pathways for surgical navigation systems pull medical-grade ToF subsystems into Minneapolis and Boston healthcare device clusters. FCC Part 15 emission ceilings constrain indoor consumer laser-power budgets. Austin and Phoenix fabrication facilities serve defense and aerospace qualification programs requiring ITAR-compliant supply chains.
Germany
KBA-type approval processes compress automotive sensor development timelines for ADAS integration. EU AI Act conformity assessments impose parallel validation tracks on biometric security deployments. Stuttgart and Ingolstadt anchor tier-1 sourcing networks for OEM vehicle programs demanding ISO 26262 ASIL-rated components.
China
MIIT GB standards for laser safety shape emitter power specifications across consumer electronics manufacturing. Yangtze River Delta module assemblers in Suzhou and Wuxi supply domestic smartphone OEMs with monocular sensors. NMPA medical device regulations extend approval timelines for surgical navigation implementations.
South Korea
MFDS medical device classification creates premium positioning pathways for optical tracking subsystems in Seoul healthcare technology corridors. Subscription-based sensor calibration services displace capital purchases in Pyeongtaek semiconductor fabrication facilities. Samsung and SK Hynix captive demand anchors VCSEL epitaxy supply concentration.
Japan
METI industrial digitization programs drive factory automation demand for real-time volumetric measurement in Aichi and Osaka manufacturing belts. PMDA regulatory pathways govern patient-monitoring device approvals. Toyota City and Nagoya clusters concentrate automotive sensor fusion development for highway-speed autonomous functions.
3D Time-Of-Flight Image Sensor Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across sensor architecture tiers. The market structure consolidates around captive CMOS foundry capacity and specialized infrared emitter material supply. Three archetypes dominate: integrated semiconductor conglomerates with captive fabrication, fabless sensor designers relying on external foundry partnerships, and module assemblers with optical packaging expertise. M&A activity concentrates on VCSEL epitaxy assets and automotive qualification capabilities.
Among integrated device manufacturers, Sony Semiconductor Solutions, STMicroelectronics, and Infineon Technologies exemplify divergent strategic positions. Sony represents the captive foundry archetype with backside-illumination CMOS control across resolution tiers. STMicroelectronics occupies the proximity-ranging specialization vector through its FlightSense architecture focus. Infineon anchors the automotive convergence tier with MEMS scanning integration for lidar signal chains.
| Leading Market Players |
|---|
| Sony Semiconductor Solutions |
| Panasonic Corporation |
| STMicroelectronics |
| ON Semiconductor |
| ams-OSRAM |
| Texas Instruments |
| Samsung Electronics |
| PMD Technologies |
| Infineon Technologies |
| Others |
Supply Flow & Price Mechanics
German automotive OEM consolidation around ISO 26262 ASIL-rated sensor procurement is compressing supplier margins while forcing foundry partners to prioritize certified wafer capacity over spot orders. This demand-side discipline cascades into tiered pricing stratification across certification tiers and volume commitments.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to automotive qualification-grade sensors where KBA-type approval deadlines compress procurement windows. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels separates buyers by fault-tolerance requirements and documentation depth. Pricing pressure stems from stereo vision substitution in price-sensitive smartphone deployments. Consumer electronics OEMs exhibit highest price sensitivity; medical device manufacturers accept premium positioning for FDA-validated subsystems.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shenzhen, and Austin coordinate hub-and-spoke fulfillment patterns for differentiated sensor tiers. Wafer fabrication concentrates in Taiwan, South Korea, and Japan; VCSEL epitaxy supply anchors in Pyeongtaek and Hsinchu. Indium gallium arsenide and indium phosphide compounds constitute critical near-infrared detector material dependencies. Single-source vulnerability in epitaxial wafer supply creates concentration risk. Distribution runs through tier-1 module assemblers with optical packaging expertise serving OEM direct programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around captive foundry capacity and automotive qualification capabilities, with REACH compliance and EU AI Act certification costs forcing sub-scale module assemblers toward exit.
For Market Incumbents: Extend FlightSense architecture roadmaps into surgical navigation subsystems to capture FDA 510(k) premium tiers. Deepen backward integration into VCSEL epitaxy through preferred wafer supply agreements, defending against indium gallium arsenide cost volatility. Prioritize ISO 26262 ASIL-D certification investment for highway-speed autonomous programs where German OEMs are consolidating supplier panels. For New Entrants and Emerging Players: EU AI Act biometric mandates in Germany open a window for validated ToF module suppliers serving security and smart-home OEMs requiring conformity-assessed depth sensing. Target industrial automation in India under PLI scheme incentives for localized module assembly serving domestic smartphone and automotive markets. Pursue sensor-as-a-service calibration subscriptions in South Korean semiconductor fabrication facilities as a recurring-revenue entry path. For Investors and Strategic Acquirers: Re-rating potential sits with fabless sensor designers possessing automotive qualification track records given tier-1 supplier consolidation around proven validation histories. Five-to-ten year viability favors specialists with MEMS scanning integration capabilities for ToF-lidar convergence architectures. Watch for inflection in India PLI scheme utilization rates as a signal of manufacturing migration momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Investment | ISO 26262 ASIL-D certification unlocks German OEM tier-1 supplier panel access. |
| VCSEL Epitaxy Backward Integration | Captive supply of indium phosphide wafers insulates against REACH material transition costs. |
| Sensor-as-a-Service Launch | Subscription calibration models penetrate South Korean semiconductor fabrication metrology demand. |
| Surgical Navigation Partnership | FDA 510(k) pathway positioning captures premium medical-grade ToF subsystem pricing. |
| India PLI Localization | Domestic module assembly qualifies for electronics manufacturing incentives serving regional OEMs. |
Methodological Framework
Independent corroboration across tier-1 supplier procurement directors, CMOS foundry planning executives, and automotive platform engineering leads underwrites the qualitative findings. Primary interviews with biomedical engineers at Minneapolis and Boston healthcare device clusters, plus industrial automation specialists in Stuttgart and Nagoya, captured application-specific demand parameters. Secondary validation drew from FDA 510(k) filings, KBA-type approval registries, ECHA REACH authorization updates, and SEC semiconductor segment disclosures. Bottom-up sensor unit demand modeling triangulated against top-down automotive content-per-vehicle estimates.
Rate-of-change decomposition across the analysis window isolates volume drivers from pricing dynamics. Segmentation dimensions span product architecture, application regulatory intensity, end-user procurement sophistication, and wafer-level technology. CAGRs derive from fitted adoption curves calibrated to disclosed OEM program timelines and foundry capacity expansion announcements. Indirect time-of-flight penetration rates in automotive lidar and REACH material transition timelines constitute key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state MEMS scanning architectures would alter the outlook for CMOS proximity sensor displacement. Forecasts reflect documented assumptions around EU AI Act implementation timelines and India PLI scheme utilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Whole Slide Imaging Systems Market
Imaging
Global Computed Radiography Market
Imaging
Industrial Camera Market
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market
Imaging
Hybrid Imaging Market
Imaging
Computer Aided Detection Market
Imaging
Hyperspectral Cameras Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Middle East and Africa Image Sensors Market
Imaging
Handheld Imaging Systems Market
Imaging
Widefield Imaging Systems Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Global Panoramic Camera Market
Imaging
AI-Based Fever Detection Camera Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Biophotonics Market