
 Ingaas Image Sensor Market | 2026-2036
Ingaas Image Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Ingaas Image Sensor Market Intelligence
Software-defined spectral calibration is expanding the addressable market for Ingaas image sensors beyond traditional hardware-only sales. Hamamatsu Photonics K.K. leverages its vertical integration in compound semiconductor growth to control substrate quality from crystal pulling through epitaxy. Teledyne Technologies Incorporated sustains a broad defense and aerospace customer base through captive foundry capacity for custom focal plane arrays. Xenics anchors the European machine vision segment with compact Ingaas cameras designed for industrial automation lines.
Indium gallium arsenide image sensors are photodetectors fabricated from III-V semiconductor alloys lattice-matched to indium phosphide substrates, typically operating in the 900–1700 nanometer near-infrared and short-wave infrared bands with room-temperature detectivity exceeding 10^12 cm·Hz^1/2/W. These devices enable thermal imaging without cryogenic cooling, semiconductor wafer defect inspection, and biomedical tissue oxygenation mapping. Area scan configurations dominate current revenue owing to their deployment in medical endoscopy and security camera systems, while line scan formats are capturing faster growth as lithium-ion battery manufacturers adopt inline infrared inspection for electrode coating uniformity. Short-wave infrared technology leads in absolute dollar contribution due to defense spending, though multispectral architectures are gaining traction in precision agriculture and food sorting applications where simultaneous visible and infrared capture reduces hardware complexity.
The U.S. Department of Defense's MIL-STD-810G environmental testing requirements and the FDA's 21 CFR Part 820 quality system regulation for medical devices both shape product development roadmaps and certification timelines for Ingaas sensor vendors. ECHA's REACH restrictions on indium compound handling and the EU's RoHS substance limitations influence material sourcing strategies and recycling obligations for manufacturers selling into European healthcare and automotive channels. Stakeholders must monitor how export control classifications under the U.S. International Traffic in Arms Regulations evolve for focal plane array technologies, as reclassification could redirect supply flows toward domestic foundries or trigger joint venture structures in allied countries.
Market Dynamics
The transition from mercury cadmium telluride to indium gallium arsenide focal plane arrays is compressing cooling requirements and extending operational lifespans, fundamentally restructuring procurement criteria across defense and industrial imaging sectors.
Growth Catalysts
- Defense procurement acceleration:NATO member states are expanding short-wave infrared camera acquisitions for night vision and surveillance applications, with Germany's automotive OEMs embedding sensors into inline quality control systems.
- REACH compliance adaptation:ECHA's restrictions on indium compound handling are driving investment in closed-loop recycling and purified material recovery, creating competitive differentiation for compliant suppliers.
- Room-temperature detectivity advancement:III-V semiconductor alloys lattice-matched to indium phosphide substrates now achieve detectivity exceeding 10^12 cm·Hz^1/2/W without cryogenic cooling, opening medical endoscopy and portable security deployments.
Market Restraints
- Substrate supply concentration:High-purity indium phosphide wafer production concentrates among Japanese and Chinese suppliers, exposing buyers to geopolitical disruption and allocation rationing during demand surges.
- RoHS material friction:EU substance limitations on heavy metals and hazardous compounds complicate electrode metallization choices, forcing reformulation of contact layers and qualification delays.
- Mercury cadmium telluride substitution threat:Established defense contractors with sunk investments in MCT cryogenic systems resist platform redesigns despite InGaAs operational advantages, slowing technology transition.
Strategic Opportunities
- Precision agriculture penetration:Multispectral architectures enabling simultaneous visible and infrared capture are reducing hardware complexity for crop health monitoring and food sorting applications.
- Battery inspection expansion:Lithium-ion electrode coating uniformity verification is accelerating line scan format adoption, with Korean and Chinese cell manufacturers qualifying inline infrared systems.
- IRITA reclassification response:Evolving U.S. International Traffic in Arms Regulations export controls for focal plane array technologies are incentivizing joint venture structures in allied countries with domestic foundry capacity.
Industry Challenges
- Compound semiconductor talent scarcity:Molecular beam epitaxy and metalorganic chemical vapor deposition process engineering expertise concentrates among legacy telecom and defense contractors, constraining foundry expansion.
- MIL-STD-810G certification timeline:Environmental testing requirements for shock, vibration, and thermal cycling extend product development cycles by 18-24 months for defense-qualified suppliers.
- Legacy system integration friction:Machine vision integrators face software compatibility barriers when retrofitting InGaAS sensors into existing GigE Vision and Camera Link architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ingaas Image Sensor Market |
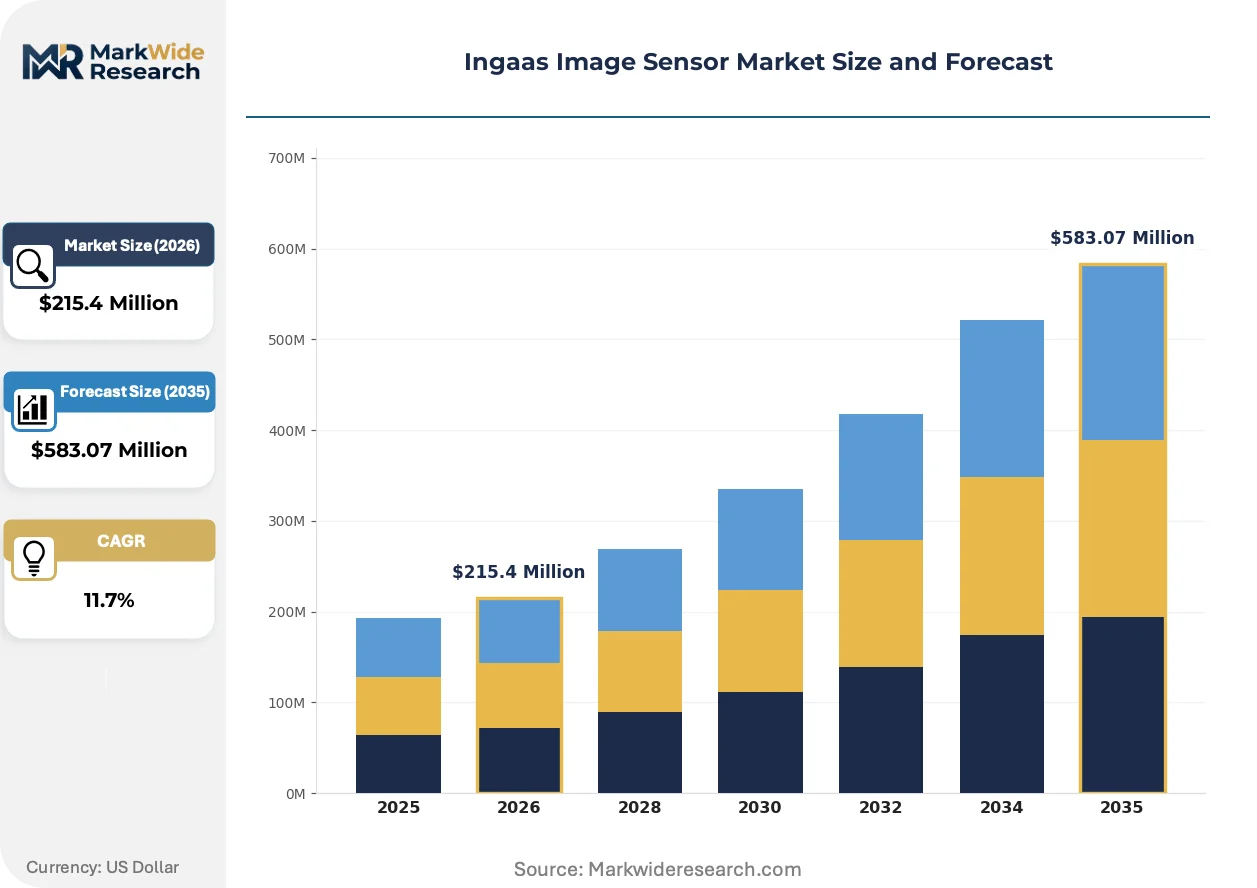
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $583.07 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Area Scan, Line Scan, 2D Sensors, 3D Sensors Application: Medical Imaging, Industrial Inspection, Security Monitoring, Consumer Electronics Technology: Near-Infrared, Short-Wave Infrared, Multispectral, Hyperspectral End User: Aerospace, Automotive, Healthcare, Research Institutions |
| Companies Covered | Hamamatsu Photonics K.K., Teledyne Technologies Incorporated, Xenics, First Sensor AG, Jenoptik AG, Lynred, New Imaging Technologies, Sofradir Group, Sensors Unlimited Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ingaas Image Sensor Market Strategic Shifts & Innovations
Software-defined spectral calibration is dissolving the boundary between hardware-only sensor sales and value-added analytics, compelling vendors to restructure R&D roadmaps and partnership strategies around embedded intelligence.
Wafer-level packaging of InGaAs photodiode arrays is consolidating cost structures for high-volume machine vision applications. Automotive battery manufacturers in Germany and South Korea are adopting these compact formats for electrode inspection lines. The technology is consolidating supplier tiers by enabling fabless design houses to compete without captive compound semiconductor foundries.
ECHA's REACH restrictions on indium compound handling are tightening material traceability requirements across European healthcare and automotive supply chains. Manufacturers must document recycling obligations and purified recovery rates from crystal pulling through epitaxy. Medical device vendors seeking CE marking under the EU MDR face extended qualification timelines as notified bodies scrutinize substance safety dossiers.
Defense agencies are compressing procurement cycles for short-wave infrared cameras through indefinite-delivery indefinite-quantity contracting vehicles. Traditional hardware specification bidding is yielding to performance-based source selection with embedded logistics support. This behavioral shift is most visible in U.S. Department of Defense programs, where systems integrators now compete on total lifecycle cost rather than unit price.
Ingaas Image Sensor Market Segmentation
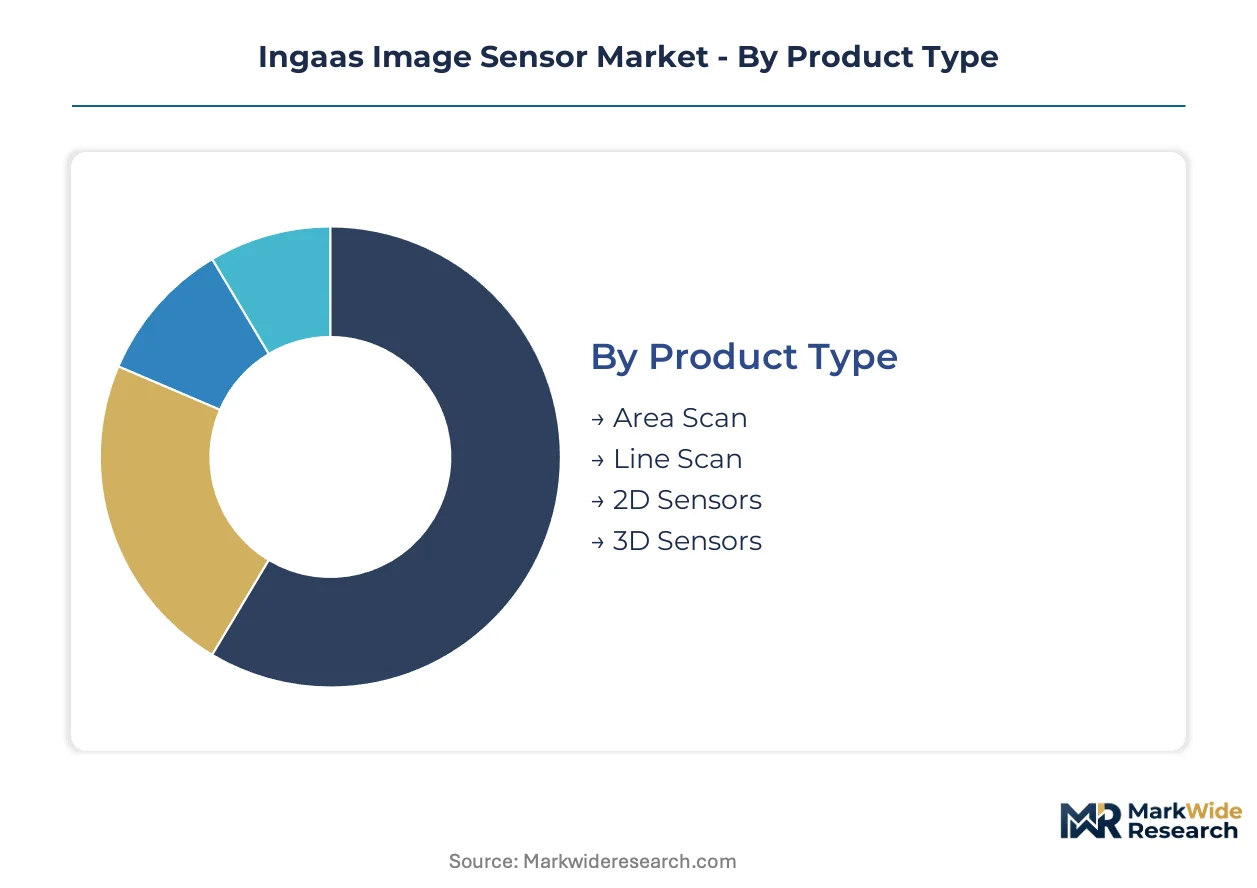
InGaAs sensor architectures diverge sharply across imaging geometries, wavelength regimes, and end-use environments. Procurement cycles and qualification timelines vary by segment, with defense aerospace demanding multi-year certification against industrial machine vision's rapid deployment cadence.
Product Type:
Upgrade cycles from legacy CCD and CMOS platforms toward compound semiconductor focal plane arrays are accelerating format transitions across inspection and surveillance systems.
- Area Scan:Two-dimensional focal plane arrays capture full-field images in single exposures, enabling real-time medical endoscopy and portable security deployments. German automotive OEMs and U.S. defense integrators dominate procurement, driven by room-temperature detectivity requirements that eliminate cryogenic cooling subsystems.
- Line Scan:Linear photodiode arrays build images through mechanical scanning motion, achieving higher spatial resolution for continuous web inspection. Korean and Chinese lithium-ion battery manufacturers are qualifying these formats for electrode coating uniformity verification, compressing inline quality control cycle times.
- 2D Sensors:Compact chip-scale packages integrate readout integrated circuits for space-constrained biomedical and consumer applications.
- 3D Sensors:Time-of-flight and structured light architectures embed InGaAs photodiodes for depth mapping in industrial robotics and autonomous navigation.
Volume placements concentrate in area scan configurations; the faster expansion belongs to line scan formats as battery inspection adoption accelerates.
Application:
Cost-tier stratification separates premium-certified medical and defense deployments from high-volume industrial and consumer segments with relaxed environmental specifications.
- Medical Imaging:FDA 21 CFR Part 820 quality system compliance governs endoscopy and tissue oxygenation mapping devices. Japanese and European healthcare systems prioritize CE-marked sensors with documented REACH substance traceability.
- Industrial Inspection:Semiconductor wafer defect detection and automotive battery electrode verification drive machine vision integration. German integrators embed compact cameras into inline production lines with GigE Vision protocol compatibility.
- Security Monitoring:Night vision and perimeter surveillance applications favor short-wave infrared sensitivity without thermal signature.
- Consumer Electronics:Emerging biometric and augmented reality applications demand wafer-level packaging cost structures.
Medical imaging commands premium pricing tiers; industrial inspection represents the steepest expansion trajectory as manufacturing automation deepens.
Technology:
Application maturity and spectral performance requirements segment the technology landscape, with established near-infrared platforms facing displacement from advanced multispectral architectures.
- Near-Infrared:900–1400 nanometer operation supports telecom test equipment and basic machine vision, though growth is decelerating as short-wave infrared costs decline.
- Short-Wave Infrared:Extended 900–1700 nanometer sensitivity enables thermal imaging through smoke and fog, moisture detection, and semiconductor subsurface defect inspection. NATO defense procurement and German automotive quality systems anchor demand.
- Multispectral:Simultaneous visible and infrared capture reduces hardware complexity for precision agriculture and food sorting. European agrotech integrators are consolidating sensor channels to lower system cost.
- Hyperspectral:Continuous narrow-band spectral resolution supports research-grade material identification and pharmaceutical quality verification.
Short-wave infrared maintains absolute revenue contribution; multispectral architectures are gaining share fastest as agricultural automation scales.
End User:
Customer-type concentration shapes supply chain configurations, with defense-qualified foundries operating under ITAR restrictions distinct from commercial healthcare and automotive channels.
- Aerospace:MIL-STD-810G environmental testing and ITAR export controls structure procurement through indefinite-delivery indefinite-quantity vehicles. U.S. Department of Defense programs prioritize total lifecycle cost over unit pricing.
- Automotive:Inline battery inspection and autonomous vehicle sensing drive German and South Korean OEM adoption. ECHA REACH compliance and EU RoHS substance limitations constrain material sourcing strategies.
- Healthcare:FDA and EU MDR regulatory pathways extend qualification timelines for endoscopy and oxygenation monitoring devices.
- Research Institutions:Academic and government laboratory procurement favors hyperspectral and custom focal plane array development.
Aerospace procurement anchors premium pricing stability; automotive applications are climbing the fastest as electric vehicle manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of indium phosphide substrates and epitaxial wafers concentrates in Japanese and Chinese foundries, while consumption clusters in German automotive lines and U.S. defense procurement channels.
United States
Defense agencies drive short-wave infrared camera acquisitions through indefinite-delivery indefinite-quantity vehicles. ITAR export controls structure procurement toward domestic foundry capacity. Boston-area systems integrators embed sensors into night vision platforms for NATO-aligned programs.
Germany
Automotive OEMs embed InGaAs sensors into inline quality control systems for electric vehicle battery inspection. ECHA REACH restrictions on indium compound handling tighten material traceability obligations. Stuttgart and Munich machine vision clusters qualify compact cameras for electrode coating uniformity verification.
Japan
Hamamatsu Photonics K.K. leverages vertical integration in compound semiconductor growth from crystal pulling through epitaxy. METI industrial policy supports domestic substrate production. Hamamatsu and Tokyo foundries supply high-purity indium phosphide wafers to global focal plane array manufacturers.
China
Lithium-ion cell manufacturers accelerate line scan format adoption for electrode inspection. MIIT standards for semiconductor equipment shape qualification protocols. Shenzhen and Shanghai battery production lines integrate infrared inspection systems for coating uniformity verification.
South Korea
Korean battery manufacturers qualify inline infrared systems for electrode production. MFDS medical device regulations extend timelines for endoscopy sensor certification. Seoul and Gyeonggi-do industrial zones concentrate machine vision integrators serving automotive and electronics sectors.
Ingaas Image Sensor Market Key Industry Players
Top-tier vendors anchor defense and aerospace qualification tiers, while mid-scale specialists serve industrial machine vision and medical segments with faster deployment cadences. Japanese compound semiconductor houses control substrate quality through captive crystal growth. European integrators concentrate on compact camera formats for automation lines. Competitive moves center on wafer-level packaging consolidation and joint venture structures in ITAR-compliant jurisdictions.
Within the vertically integrated tier, Hamamatsu Photonics K.K. exemplifies substrate-to-sensor control, while Teledyne Technologies Incorporated occupies a position spanning defense-qualified foundry capacity. Xenics represents the European machine vision specialist archetype, anchoring compact camera design for industrial automation.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| Teledyne Technologies Incorporated |
| Xenics |
| First Sensor AG |
| Jenoptik AG |
| Lynred |
| New Imaging Technologies |
| Sofradir Group |
| Sensors Unlimited Inc. |
| Others |
Cost & Logistics Intelligence
ECHA REACH restrictions on indium compound handling gate qualified supply for European healthcare and automotive channels, reserving premium-tier pricing access for vendors with documented closed-loop recycling and purified material recovery systems. German automotive OEMs and U.S. defense integrators pay certification premiums for sensors with traceable substrate provenance from crystal pulling through epitaxy.
Pricing Analysis
Margin tightening in defense-qualified tiers reflects MIL-STD-810G environmental testing timelines extending product development cycles by 18-24 months. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-compliant foundry output from commercial machine vision and consumer biometric applications. Price differentiation hinges on certification grade and volume scale, with Korean and Chinese battery manufacturers extracting volume discounts for line scan formats while medical device vendors absorb FDA 21 CFR Part 820 compliance premiums. Cost-down pressure on industrial segments accelerates as wafer-level packaging enables fabless design houses to compete without captive compound semiconductor foundries. Automotive OEMs demonstrate highest price sensitivity; aerospace procurement shows least sensitivity due to total lifecycle cost evaluation.
Supply Chain Analysis
Freight cost volatility from Japanese and Chinese substrate foundries to German automotive lines and U.S. defense integrators amplifies landed cost uncertainty for high-purity indium phosphide wafers. Production concentrates in Japan, China, and South Korea, drawing from specialized indium refining, indium phosphide crystal pulling, and molecular beam epitaxy equipment inputs. Supply chain risk centers on single-source vulnerability for substrates lattice-matched to focal plane array specifications, with geopolitical disruption threatening allocation rationing during demand surges. Distribution runs through defense-qualified systems integrators for aerospace applications, direct OEM relationships for automotive, and machine vision channel partners for industrial inspection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compound semiconductor foundry capacity for molecular beam epitaxy and metalorganic chemical vapor deposition constrains supply expansion, propping pricing for qualified vendors across defense and medical certification tiers.
For Market Incumbents: Anchor defense market position through indefinite-delivery indefinite-quantity contracting vehicles that emphasize total lifecycle cost over unit pricing. Deepen backward integration into indium phosphide substrate production to mitigate Japanese and Chinese supply concentration risk. Invest in closed-loop recycling systems to satisfy ECHA REACH documentation requirements and secure European automotive and healthcare procurement access. For New Entrants and Emerging Players: Direct-to-designer digital channels targeting fabless sensor developers offer the most penetrable entry vector, bypassing captive foundry requirements through wafer-level packaging partnerships. Precision agriculture multispectral applications present white-space opportunity with faster qualification timelines than defense or medical tiers. Pursue joint venture structures in ITAR-compliant allied countries to circumvent U.S. International Traffic in Arms Regulations restrictions on focal plane array export. For Investors and Strategic Acquirers: ITAR reclassification proceedings for focal plane array technologies are the leading indicator that domestic foundry capacity will command strategic premium. Long-term viability favors vertically integrated compound semiconductor houses with substrate-to-sensor control spanning crystal growth through camera integration. Monitor U.S. Department of Defense procurement behavioral shifts from hardware specification bidding to performance-based source selection as signal of vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Level Packaging Scale-Up | Enables fabless competitors to enter high-volume machine vision without captive foundry investment. |
| Closed-Loop Recycling Certification | Satisfies ECHA REACH substance traceability for European healthcare and automotive procurement access. |
| ITAR-Compliant Joint Venture | Positions suppliers for U.S. defense procurement should export controls reclassify focal plane arrays. |
| Multispectral Architecture Development | Captures precision agriculture and food sorting demand with reduced hardware complexity. |
| Inline Battery Inspection System Partnership | Secures placement with Korean and Chinese lithium-ion cell manufacturers scaling electrode verification. |
Research Approach
Multi-period observation of defense procurement cycles, automotive battery inspection adoption rates, and compound semiconductor foundry utilization anchored the trend analysis, supplemented by interviews with molecular beam epitaxy process engineers, machine vision integrators, biomedical device regulatory affairs leads, and defense systems procurement officers. Secondary validation drew from FDA 510(k) filings, ECHA REACH substance dossiers, U.S. Department of Defense contract award databases, and SEC filings of vertically integrated sensor manufacturers. Bottom-up segment sizing triangulated against top-down industry revenue estimates.
Input-output matrices modeled volume and value trajectories across product type, application, technology, and end user dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation with macroeconomic indicators and technology substitution curves. Industry-specific forecast inputs included lithium-ion battery production capacity expansion schedules and NATO member state short-wave infrared camera procurement commitments.
Inputs from defense procurement databases and compound semiconductor equipment utilization reports were available through the study window; gaps in real-time foundry capacity utilization introduce uncertainty bands around near-term supply constraints. Forecasts reflect documented assumptions regarding technology transition timelines from mercury cadmium telluride to indium gallium arsenide platforms. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
AI Camera Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
Wearable IP Camera Market
Imaging
APAC Image Sensors Market
Imaging
Global Acoustic Cameras Market
Imaging
Industrial Machine Vision Market
Imaging
Embedded Smart Cameras Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Document Imaging Market
Imaging
Global in Ceiling Camera Market
Imaging
Global Broadcast Cameras Market
Imaging
Global Cell Imagers Market
Imaging
Hyperspectral Cameras Market
Imaging
Vision Processing Unit Market