
 In Vivo Imaging Systems Market | 2026-2036
In Vivo Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
In Vivo Imaging Systems Market Outlook
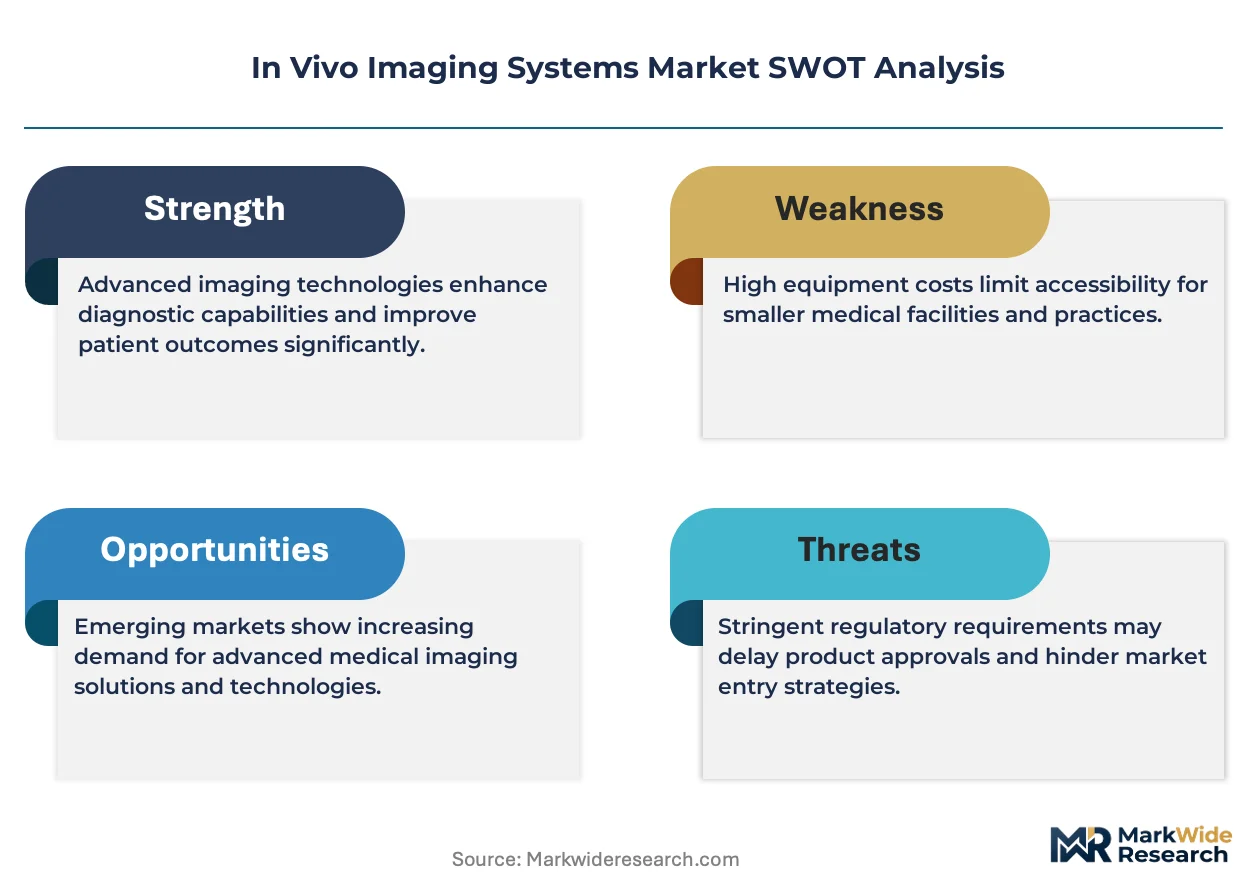
Capital-intensity divergence between installed-base incumbents and emerging modality specialists is rotating competitive dynamics toward platform consolidation. Bruker Corporation leverages its cryogen-free magnet portfolio to anchor preclinical MRI demand in European research consortia. PerkinElmer Inc. sustains optical imaging dominance through channel control over fluorescent probe supply chains. Siemens Healthineers AG competes across the full nuclear-magnetic-optical stack, extending service contracts that lock in hospital capital budgets.
In vivo imaging systems integrate electromagnetic, acoustic, or radioactive energy sources with detector arrays to visualize biological processes within living organisms, typically achieving spatial resolutions from micrometers (optical) to sub-millimeters (PET) depending on modality depth penetration. These systems serve pharmaceutical development, disease mechanism validation, and surgical navigation by enabling longitudinal observation without tissue extraction. Optical imaging and nuclear imaging segments capture divergent margin pools, with optical platforms maturing in preclinical fluorescence applications while PET-CT fusion systems command premium pricing in clinical oncology workflows. MRI systems retain structural leadership in neurology and cardiology due to superior soft-tissue contrast, though magnetic resonance technology faces growth headwinds from helium supply constraints and siting infrastructure costs.
FDA 21st Century Cures Act provisions reshape imaging biomarker qualification timelines, compressing validation pathways for quantitative radiology endpoints in drug trials. EMA's Medical Device Regulation and EU AI Act impose concurrent conformity and algorithmic transparency requirements on software-embedded imaging platforms entering European clinical settings. Stakeholders must monitor evolving reimbursement coding for AI-augmented image analysis, as payer decisions will determine whether algorithm investments convert to sustainable revenue streams or remain cost centers.
Market Dynamics
Platform consolidation pressure is intensifying as multimodal imaging architectures displace standalone modality purchases in pharmaceutical development workflows, forcing vendors to defend installed bases through service contract lock-in rather than hardware differentiation alone.
Growth Catalysts
- NIH Translational Research Funding:Federal grant clusters in the United States accelerate preclinical imaging infrastructure deployment across academic medical centers and contract research organizations.
- FDA 21st Century Cures Act:Compressed biomarker qualification timelines enable faster imaging endpoint validation for oncology and neurology drug trials, expanding addressable clinical trial demand.
- Cryogen-free MRI magnet technology:Elimination of liquid helium dependency reduces siting infrastructure barriers and extends preclinical MRI access to smaller research facilities.
Market Restraints
- Helium supply concentration:Qatar and the United States control over 75% of global helium extraction, exposing conventional MRI operators to price volatility and allocation disruptions.
- EMA MDR conformity costs:Extended technical documentation and notified body review timelines delay European commercialization of software-embedded imaging platforms by 12-18 months.
- Optical depth penetration limits:Tissue autofluorescence and photon scattering constrain functional imaging to superficial applications, ceding deep-tumor assessment to nuclear modalities.
Strategic Opportunities
- AI-augmented image reconstruction:Deep learning algorithms embedded in PET and MRI acquisition pipelines enable scan-time reduction without resolution sacrifice, creating premium pricing tiers.
- Brazilian preclinical CRO expansion:ANVISA regulatory harmonization with FDA standards positions São Paulo research clusters as nearshore alternatives for Latin American pharmaceutical development.
- Fluorescent probe supply chain integration:Captive production of targeted molecular imaging agents locks in optical platform margins and creates switching costs for end-users.
Industry Challenges
- Cross-disciplinary imaging scientist shortage:The convergence of physics, biology, and computational expertise required for multimodal platform operation outpaces specialized training program output.
- Legacy PACS integration complexity:Hospital IT infrastructure built on DICOM archives resists API-native AI imaging workflows, forcing vendors to maintain dual architecture support.
- Algorithmic transparency compliance:EU AI Act documentation requirements for clinical decision-support software impose engineering overhead that compresses R&D velocity for European market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Vivo Imaging Systems Market |
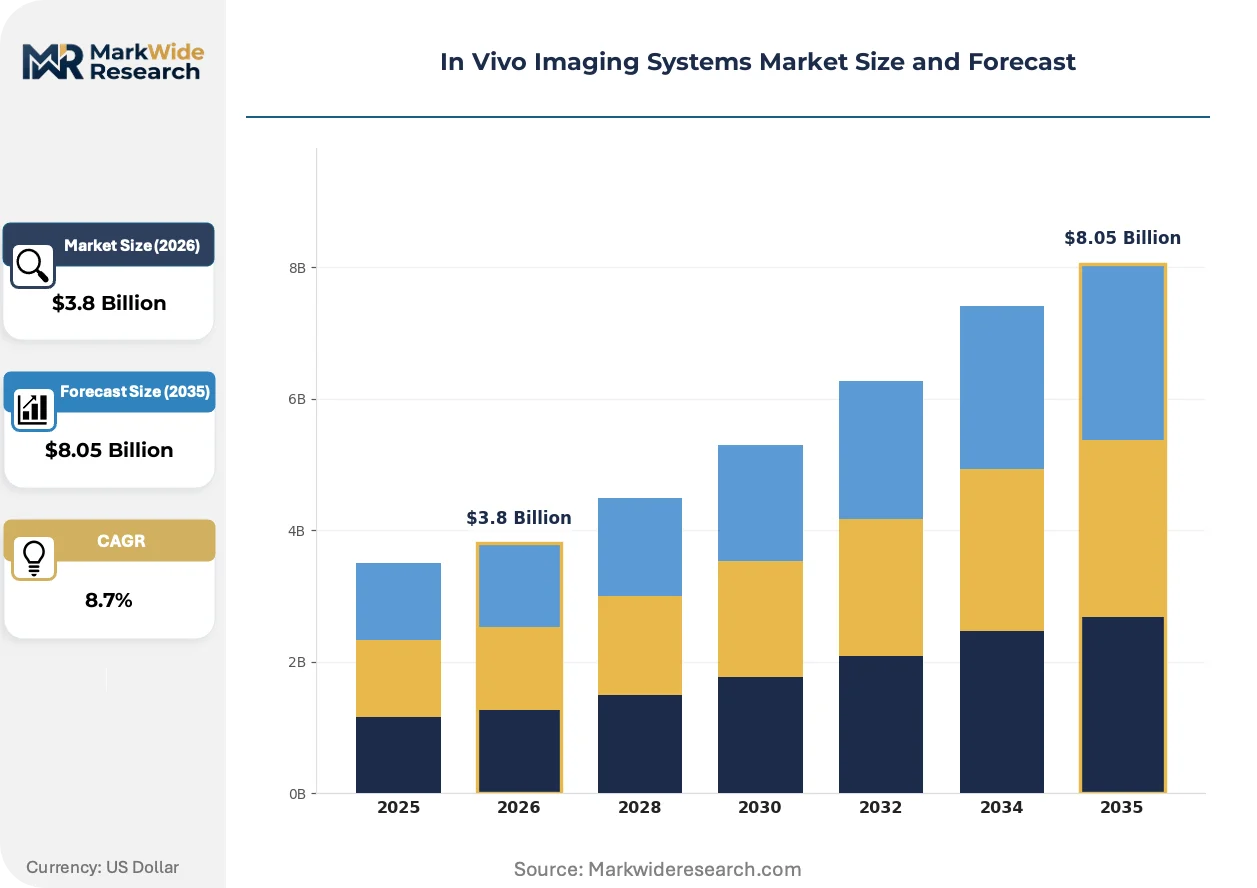
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Systems, PET Scanners, Ultrasound Systems End User: Hospitals, Research Laboratories, Diagnostic Centers, Academic Institutions Technology: Optical Imaging, Nuclear Imaging, Magnetic Resonance, X-ray Imaging Application: Cancer Detection, Cardiology, Neurology, Preclinical Studies |
| Companies Covered | Bruker Corporation, PerkinElmer Inc., Siemens Healthineers AG, FUJIFILM VisualSonics Inc., MILabs B.V., Mediso Medical Imaging Systems Ltd., LI-COR Biosciences, MR Solutions Ltd., Aspect Imaging Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Vivo Imaging Systems Market Strategic Shifts
Computational imaging architectures are displacing hardware-centric performance gains across preclinical and clinical segments, redistributing value capture toward software and probe suppliers while compressing capital equipment replacement cycles.
Photon-counting CT detector technology is bifurcating the preclinical imaging landscape. Direct conversion semiconductors eliminate electronic noise floors that constrain conventional energy-integrating detectors. Large pharmaceutical sponsors at Merck and Novartis research campuses are retrofitting existing gantry infrastructure with cadmium-zinc-telluride arrays. This upgrade path is bifurcating vendor revenue models toward detector subsystem sales and away from full-system replacement.
EMA's Medical Device Regulation recast imposes clinical evidence requirements on imaging software with diagnostic claims. Algorithm developers must now generate prospective validation data equivalent to Class IIb device submissions. European university hospital procurement committees are delaying AI-augmented platform commitments until notified body certificates issue, compressing near-term sales velocity in Germany and France while channeling R&D investment toward regulatory science capabilities.
Research consortia in the United States are unbundling after-sales service contracts from hardware procurement. NIH-funded core facilities at Stanford and Johns Hopkins now negotiate preventive maintenance, software licensing, and probe supply as separate spend categories. This disaggregation transfers pricing power to specialized service providers and fluorescent probe suppliers, fragmenting vendor account control and compressing multi-year contract values for imaging system OEMs.
In Vivo Imaging Systems Market Segmentation
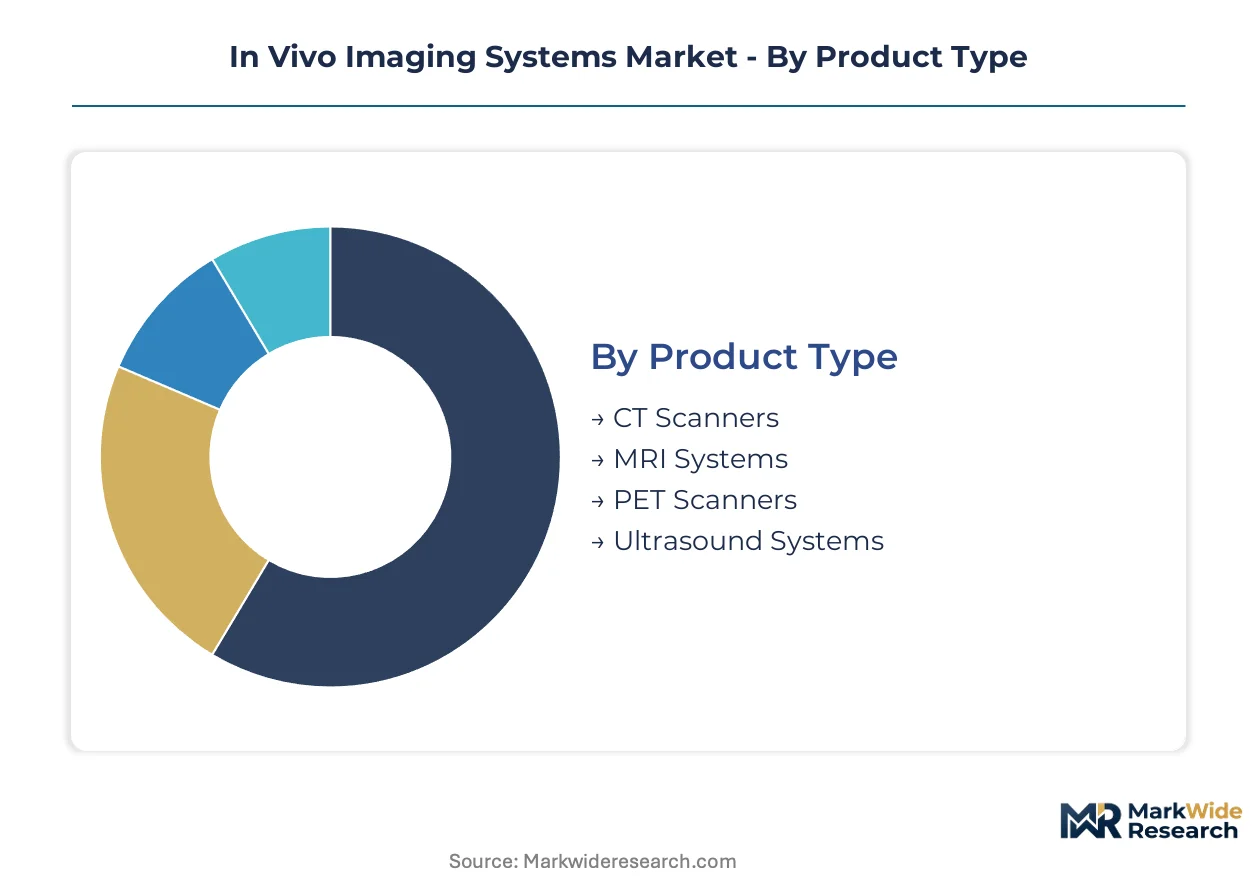
Segmentation reveals how capital allocation and reimbursement pathways diverge across imaging modalities. Preclinical versus clinical end-uses create distinct procurement cycles and margin structures that vendors must navigate simultaneously.
Product Type:
MRI systems and PET scanners command the deepest margin pools due to siting complexity and radioactive isotope supply dependencies.
- CT Scanners:Photon-counting detector arrays are retrofitting existing gantry infrastructure at pharmaceutical research campuses. Merck and Novartis facilities in the United States prioritize cadmium-zinc-telluride upgrades over full-system replacement, compressing OEM revenue recognition timelines.
- MRI Systems:Cryogen-free magnet technology eliminates liquid helium dependency, reducing infrastructure barriers for academic medical centers. NIH-funded core facilities at Stanford and Johns Hopkins now unbundle service contracts from hardware procurement.
- PET Scanners:Radiotracer supply chain integration determines operational uptime for oncology workflows. Cyclotron proximity constraints limit deployment to major metropolitan hospital clusters.
- Ultrasound Systems:Portable form factors expand point-of-care deployment in emergency departments, though reimbursement coding lags behind hardware capability.
The dominant share belongs to MRI systems, while PET scanners are closing the gap fastest through radiotracer supply chain consolidation.
End User:
Procurement authority concentrates differently across institutional types, with research laboratories exercising fragmented purchasing power against hospital centralized capital committees.
- Hospitals:Siemens Healthineers AG extends multi-year service contracts that lock in capital budgets across nuclear-magnetic-optical stacks. IT infrastructure built on DICOM archives resists API-native AI workflows, forcing dual architecture support.
- Research Laboratories:Multimodal platform demand accelerates as pharmaceutical sponsors consolidate preclinical imaging infrastructure. Bruker Corporation anchors European consortia through cryogen-free magnet portfolios.
- Diagnostic Centers:Reimbursement volatility constrains capital deployment for advanced modalities, favoring leased equipment arrangements over ownership.
- Academic Institutions:Federal grant clusters accelerate infrastructure deployment, though indirect cost recovery policies compress net equipment purchasing power.
Hospitals retain the largest installed base, yet research laboratories are expanding most quickly through NIH translational funding mechanisms.
Technology:
Software-embedded platforms face divergent regulatory burdens, with EU AI Act documentation requirements compressing R&D velocity for algorithm developers.
- Optical Imaging:Fluorescent probe supply chains determine switching costs for end-users. PerkinElmer Inc. sustains dominance through channel control over molecular imaging agents.
- Nuclear Imaging:PET-CT fusion systems command premium pricing in clinical oncology workflows. EMA MDR conformity costs delay European commercialization by 12-18 months.
- Magnetic Resonance:Superior soft-tissue contrast retains structural leadership in neurology and cardiology despite helium supply concentration risks from Qatar and United States extraction dominance.
- X-ray Imaging:Energy-integrating detectors face displacement by photon-counting architectures, bifurcating vendor revenue models toward subsystem sales.
Magnetic resonance holds the deepest clinical penetration, though optical imaging is gaining share fastest through probe supply chain integration.
Application:
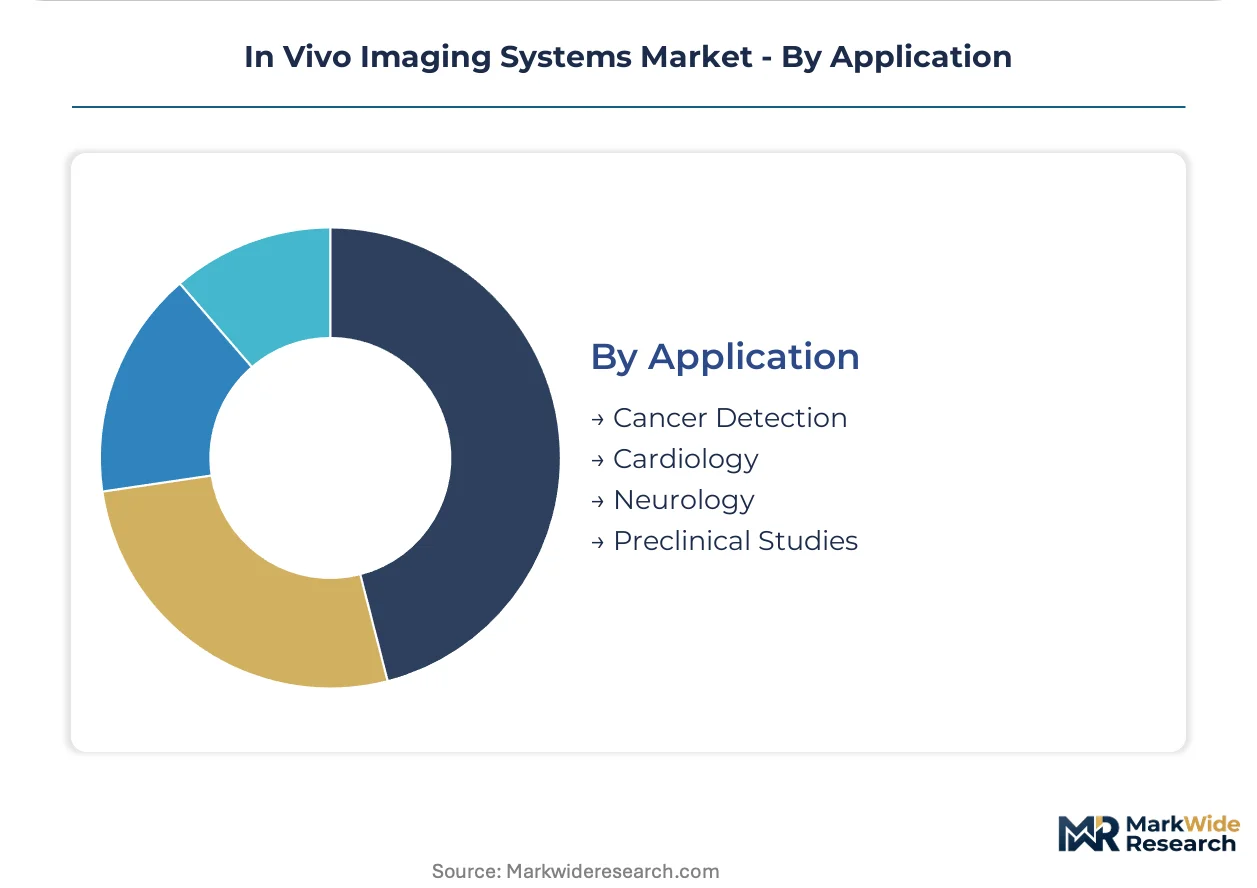
FDA 21st Century Cures Act provisions reshape biomarker qualification timelines, compressing validation pathways most acutely in oncology and neurology drug trials.
- Cancer Detection:Deep-tumor assessment requirements cede functional imaging to nuclear modalities as optical depth penetration hits tissue autofluorescence constraints.
- Cardiology:MRI soft-tissue contrast enables longitudinal observation without tissue extraction, though scan-time reduction demands drive AI-augmented reconstruction investment.
- Neurology:Quantitative radiology endpoints require prospective validation data equivalent to Class IIb device submissions under EMA recast requirements.
- Preclinical Studies:ANVISA regulatory harmonization with FDA standards positions São Paulo research clusters as nearshore alternatives for Latin American pharmaceutical development.
Cancer detection commands the largest addressable demand, while preclinical studies are climbing the fastest through federal grant acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement environments. Academic laboratories exhibit high sensitivity to capital costs and helium supply volatility. Hospital systems demonstrate lower elasticity due to locked-in service contracts and clinical workflow dependencies.
United States
NIH translational research clusters concentrate demand in Boston, San Francisco, and Research Triangle Park. FDA 21st Century Cures Act provisions accelerate imaging biomarker qualification for oncology drug trials. Stanford and Johns Hopkins core facilities now unbundle service contracts from hardware procurement, fragmenting vendor account control.
Germany
EMA Medical Device Regulation conformity costs delay software-embedded platform commercialization by 12-18 months. Federal research funding through the Helmholtz Association sustains preclinical imaging infrastructure at Munich and Heidelberg centers. Siemens Healthineers anchors domestic supply chains through multi-year hospital service agreements.
China
NMPA regulatory harmonization efforts compress approval timelines for imported imaging platforms. Government-backed biotech parks in Shanghai Zhangjiang and Suzhou BioBAY expand preclinical CRO capacity. Domestic manufacturers gain share in mid-tier MRI segments through localized cryogen-free magnet production.
Japan
PMDA qualification pathways for quantitative imaging endpoints align with FDA standards under harmonization frameworks. METI funding for precision medicine initiatives drives PET scanner deployment at Tokyo and Osaka university hospitals. Domestic vendors concentrate on compact preclinical optical systems for pharmaceutical contract research.
Brazil
ANVISA regulatory alignment with FDA standards positions São Paulo research clusters as nearshore alternatives for Latin American pharmaceutical development. Price sensitivity in public hospital procurement favors leased equipment arrangements over capital purchases. Academic partnerships with US institutions accelerate multimodal platform adoption at University of São Paulo facilities.
In Vivo Imaging Systems Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the In Vivo Imaging Systems Market. Full-stack vendors compete across nuclear, magnetic, and optical modalities through service contract lock-in strategies. Mid-scale specialists concentrate on single-modality excellence or regional channel control. Competitive moves center on probe supply chain integration and cryogen-free magnet technology licensing.
Among integrated modality vendors, Siemens Healthineers AG and Bruker Corporation occupy positions spanning clinical and preclinical segments. PerkinElmer Inc. exemplifies the probe-anchored specialist archetype through fluorescent agent supply chain control. These three entities represent distinct competitive vectors: full-stack service bundling, cryogen-free hardware differentiation, and molecular imaging agent captive production.
| Leading Market Players |
|---|
| Bruker Corporation |
| PerkinElmer Inc. |
| Siemens Healthineers AG |
| FUJIFILM VisualSonics Inc. |
| MILabs B.V. |
| Mediso Medical Imaging Systems Ltd. |
| LI-COR Biosciences |
| MR Solutions Ltd. |
| Aspect Imaging Ltd. |
| Others |
Value Chain & Pricing Dynamics
Cryogen-free magnet technology replacing liquid helium-cooled systems simultaneously redistributes manufacturing geography toward China and Germany while compressing pricing premiums previously anchored to Qatar-sourced helium supply chains. Academic medical centers in the United States now negotiate hardware procurement separately from service contracts, fragmenting vendor pricing power across multimodal imaging platforms.
Pricing Analysis
Multi-year service contract extensions drive lifetime value capture for full-stack vendors like Siemens Healthineers AG. Three-tier pricing structure across premium, standard, and economy levels stratifies by cryogen dependency and AI-augmented reconstruction capabilities. Cost compression in mid-tier MRI segments intensifies as domestic Chinese manufacturers localize cryogen-free magnet production. Research laboratories exhibit highest price sensitivity due to federal grant funding constraints, while hospital systems demonstrate lowest elasticity through locked-in clinical workflow dependencies.
Supply Chain Analysis
Helium extraction concentration in Qatar and the United States exposes conventional MRI operators to allocation disruptions and price volatility. Cadmium-zinc-telluride semiconductor arrays for photon-counting detectors draw from specialized foundries in Japan and Germany. Single-source vulnerability in radiotracer cyclotron networks constrains PET scanner deployment to major metropolitan clusters. Distribution runs through hospital capital committees and NIH-funded core facilities with divergent procurement authority structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as research consortia unbundle service contracts from hardware procurement, fragmenting vendor account control across multimodal imaging platforms.
For Market Incumbents: Consolidate probe supply chain integration to lock in optical platform margins and create switching costs for end-users. Acquire cryogen-free magnet technology licensing to defend against emerging modality specialists. Capture fluorescent agent production capacity before PerkinElmer Inc. extends channel control into adjacent molecular imaging categories. For New Entrants and Emerging Players: Differentiate on AI-augmented image reconstruction algorithms that enable scan-time reduction without resolution sacrifice. Target Brazilian preclinical CRO expansion as ANVISA regulatory harmonization creates nearshore alternatives for Latin American pharmaceutical development. Pursue software-only deployment models that bypass legacy PACS integration complexity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed preclinical imaging specialists holding European research consortia relationships. Long-term viability hinges on regulatory science capabilities for EMA MDR and EU AI Act compliance rather than hardware differentiation alone. Watch NIH funding allocation shifts as inflection indicators for translational research infrastructure deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogen-free Magnet Technology Licensing | Eliminates helium dependency and extends MRI access to smaller research facilities in Germany and China. |
| Fluorescent Probe Supply Chain Integration | Captive production of targeted molecular imaging agents locks in optical platform margins for end-users. |
| AI-augmented Image Reconstruction Development | Deep learning algorithms embedded in PET and MRI pipelines create premium pricing tiers for scan-time reduction. |
| Brazilian Preclinical CRO Expansion | ANVISA regulatory alignment with FDA standards positions São Paulo clusters for Latin American pharmaceutical demand. |
| Service Contract Unbundling Response | Specialized maintenance and software licensing offerings counter NIH-funded core facility procurement fragmentation. |
Study Parameters
Operator-level perspectives from biomedical engineers, hospital purchasing committee chairs, pharmaceutical development executives, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, NIH RePORTER grant records, and hospital procurement contract repositories. Bottom-up equipment shipment tracking and top-down research funding allocation analysis triangulated market sizing across the analysis window.
Sensitivity analysis tested helium price volatility scenarios and regulatory timeline compression effects across the projection horizon. Segmentation dimensions modeled include product type, end user category, technology platform, and application area with geographic regulatory cluster overlays. CAGRs derived from installed base evolution, replacement cycle compression, and grant funding trajectory inputs. Cryogen-free magnet adoption curves and AI-augmented reconstruction penetration rates served as industry-specific forecast modifiers.
Material uncertainties — helium supply allocation disruptions, EMA notified body capacity constraints, and NIH appropriation volatility — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization pace and translational research funding continuity. Practitioners should keep alternative scenarios live as EU AI Act documentation requirements and cyclotron network expansion patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Microwave Imaging Market
Imaging
Global Whole Slide Imaging Market
Imaging
Infrared Imaging Software Market
Imaging
Hyperspectral Cameras Market
Imaging
Holotomographic Imaging Market
Imaging
Global Digital Photography Market
Imaging
Automotive Compact Camera Module Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Global Cell Imagers Market
Imaging
Document Imaging Market
Imaging
On-Chip Color Filters Market
Imaging
Photography Equipment Market
Imaging
CCD Image Sensors Market
Imaging
Webcam Market
Imaging
Smart Camera Market
Imaging
Machine Vision Market