
 Photography Equipment Market | 2026-2036
Photography Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Photography Equipment Market Outlook
Market Context
Full-frame sensor specifications is redrawing competitive boundaries across the photography equipment industry. Canon Inc. leverages its in-house CMOS fabrication to sustain pricing power in professional tiers. Sony Corporation dominates image sensor supply to third-party manufacturers while competing directly in camera bodies. Nikon Corporation anchors its position through backward integration into precision optical glass.
Technical Definition and Segment Structure
Photography equipment encompasses image-capture apparatus including camera bodies, interchangeable optics, stabilization supports, and artificial lighting systems, typically specified by sensor format, resolution measured in megapixels, and optical transmission rates. This equipment serves commercial content production, journalistic documentation, scientific imaging, and personal creative expression. Mirrorless technology is displacing DSLRs as the primary growth vector, while lenses command the dominant margin pool due to replacement cycles that outpace camera body turnover. Professional photographers represent the most concentrated end-user segment by average transaction value, though amateur photographers generate higher absolute unit volumes.
Regulatory Environment
The EU F-Gas Regulation and REACH directives constrain solvent use in lens coating processes, while Japan's METI enforces energy-efficiency standards on battery-powered camera systems. Compliance with these frameworks shapes material selection and factory location decisions for manufacturers serving multiple jurisdictions. Stakeholders must monitor evolving chemical restrictions and battery transport regulations to anticipate cost impacts and supply chain reconfigurations.
Market Dynamics
Mirrorless sensor technology is compressing replacement cycles while the EU F-Gas Regulation forces coating chemistry reformulation across precision optics manufacturing. This dual pressure is redrawing cost structures and supplier hierarchies simultaneously.
Growth Catalysts
- Content Creator Demand:Social media production workflows are pulling mirrorless systems into amateur and semi-professional tiers. Video-centric specifications now drive sensor and processor roadmaps.
- EU F-Gas Regulation:Compliance investments in solvent-free coating processes are creating technical barriers that favor scaled manufacturers with captive R&D facilities.
- Japan Production Clusters:Tokyo-Osaka corridor concentration in CMOS fabrication and precision glass grinding sustains component availability for tier-one assembly.
Market Restraints
- Rare Earth Magnet Volatility:Voice coil motor actuators in autofocus systems depend on neodymium supply concentrated in Chinese processing facilities.
- Sensor Wafer Bottleneck:300mm CMOS fabrication capacity is concentrated among three foundry operators, constraining volume scaling for mid-tier camera brands.
- Smartphone Substitution:Computational photography on flagship mobile devices is eroding point-and-shoot and entry-DSLR addressable markets.
Strategic Opportunities
- India Content Economy:YouTube and short-form video creator expansion in Mumbai and Bangalore is generating first-time interchangeable lens demand outside traditional camera markets.
- Computational-Optical Convergence:Integration of AI-powered subject tracking with mechanical stabilization is opening hybrid product categories between smartphones and dedicated cameras.
- Japan METI Efficiency Standards:Battery performance mandates are accelerating solid-state cell adoption, enabling longer shooting durations as a differentiated specification.
Industry Challenges
- Coating Chemist Scarcity:REACH-compliant fluoropolymer formulation expertise is concentrated among retiring specialists in German and Japanese optical houses.
- Legacy Mount Compatibility:Adapter engineering for vintage glass on mirrorless bodies consumes R&D resources without generating lens revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photography Equipment Market |
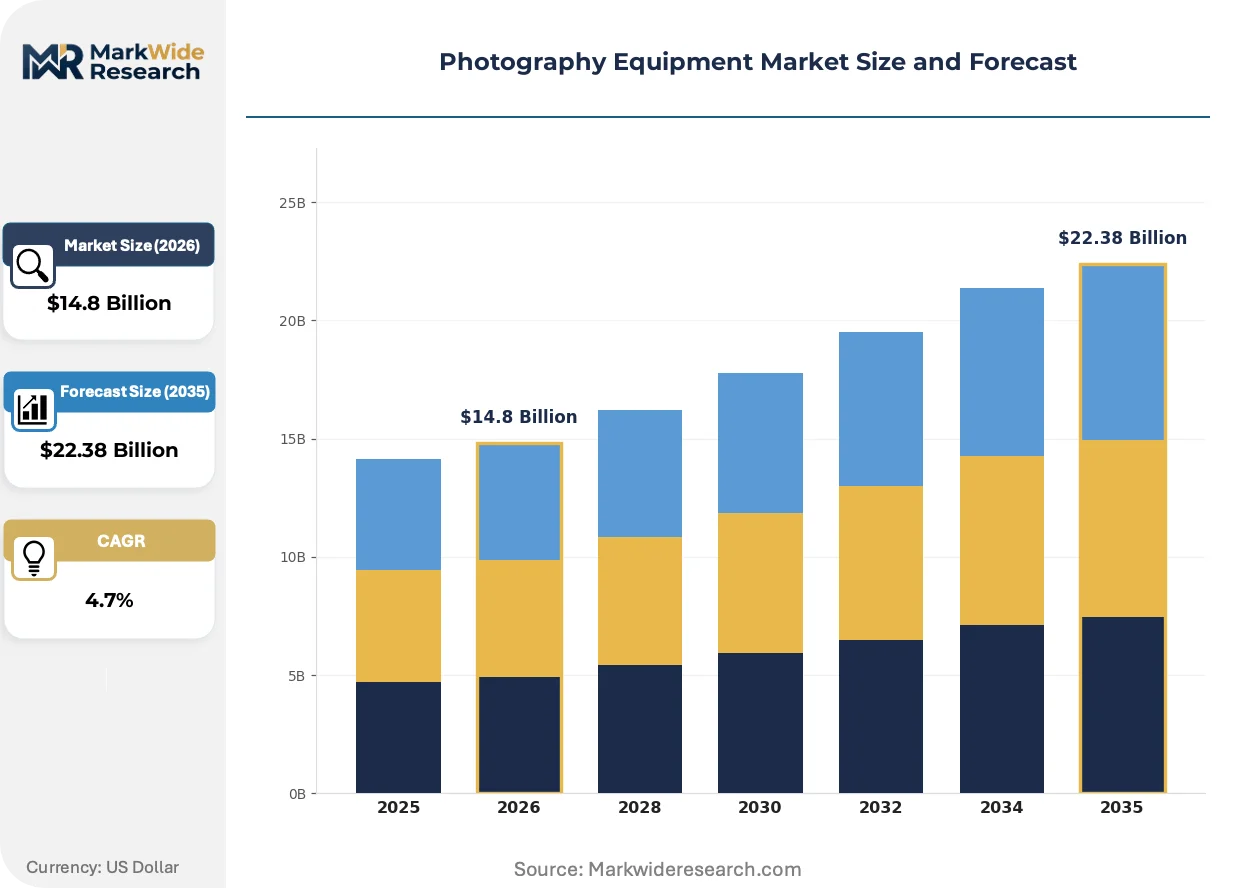
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.38 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Lenses, Tripods, Flash Units Technology: Digital, Film, Mirrorless, DSLRs Application: Portrait Photography, Landscape Photography, Event Photography, Wildlife Photography End User: Professional Photographers, Amateur Photographers, Students, Businesses |
| Companies Covered | Fujifilm Holdings Corporation, Leica Camera AG, Canon Inc., Hasselblad, Olympus Corporation, Sony Corporation, Panasonic Corporation, DJI, Nikon Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photography Equipment Market Strategic Shifts
Computational capabilities are migrating from post-processing software into camera firmware, altering the boundary between capture and editing. This shift is compressing professional workflow steps while expanding automation in consumer tiers.
Stacked CMOS architectures with integrated memory layers are bifurcating readout performance between professional and enthusiast camera tiers. Wedding and sports photographers are adopting these sensors for blackout-free continuous shooting. The technology is compressing the specification gap between flagship bodies and mid-range alternatives.
The EU F-Gas Regulation is banning hydrofluorocarbon solvents in anti-reflective coating deposition by 2027. German and Japanese lens manufacturers are retrofitting vacuum deposition lines with supercritical CO2 alternatives. Professional cinema lens production faces the steepest compliance cost given multi-layer coating complexity.
Direct-to-creator sales channels are displacing traditional camera retail in North American and European markets. Specialty retailers are unbundling after-sales support into subscription services to retain margin. This pattern is most visible among YouTube tutorial influencers who now receive pre-release hardware through manufacturer ambassador programs rather than retail purchase.
Photography Equipment Market Segmentation
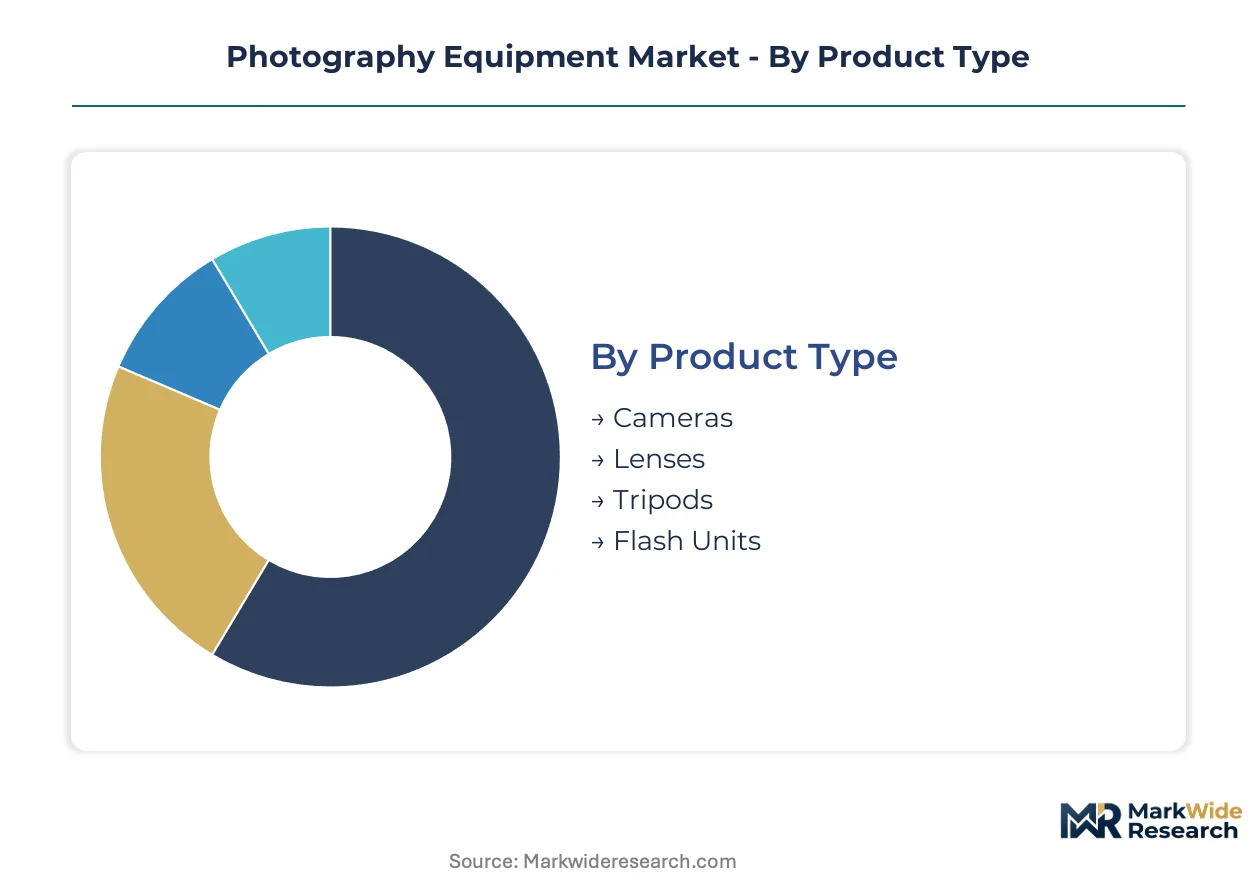
Segmentation in photography equipment reveals how margin pools concentrate in optics and mirrorless bodies while application-specific demand fragments across creator tiers. Understanding these splits exposes where manufacturers defend pricing power versus where volume commoditization accelerates.
Product Type:
Margin pools concentrate in interchangeable optics due to replacement cycles that substantially outpace camera body turnover, while tripod and lighting accessories operate on thinner hardware spreads.
- Cameras:Mirrorless bodies with full-frame sensors command the dominant equipment revenue share. Professional wedding and sports photographers in Japan and Germany are compressing replacement cycles as stacked CMOS architectures with integrated memory layers reach sub-$3,000 price tiers.
- Lenses:Interchangeable optics generate the highest gross margins across the equipment spectrum due to coating complexity and mount-specific compatibility lock-in. Cinema production houses in Mumbai and Los Angeles are pulling large-aperture prime lenses into rental fleet rotations faster than zoom alternatives.
- Tripods:Carbon fiber leg sets with modular heads serve travel content creators prioritizing weight reduction. Peak Design and Really Right Stuff anchor the premium tier through direct-to-consumer channels.
- Flash Units:Wireless TTL systems with high-speed sync capability address event photographers requiring rapid recycle times. Godox and Profoto split the market between value and professional tiers.
Lenses hold installed capacity. Mirrorless cameras are rotating up the share rankings.
Technology:
Volume concentration now sits with mirrorless architectures as DSLRs enter end-of-life manufacturing, while film experiences niche revival among enthusiast collectors.
- Digital:CMOS-based capture dominates absolute unit shipments across all price tiers. Computational photography integration in mid-range bodies is eroding differentiation between enthusiast and professional specifications.
- Film:35mm and medium format chemical capture persists in artisanal and educational segments. Kodak and Ilford sustain emulsion production for a shrinking but price-inelastic collector base.
- Mirrorless:Short flange distance designs enable lens adapter compatibility that expands addressable glass libraries. Sony, Canon, and Nikon have completed full-frame mirrorless transitions, leaving only Pentax in DSLR development.
- DSLRs:Optical viewfinder systems with phase-detect autofocus modules retain utility in extreme temperature environments where electronic viewfinders suffer latency. Remaining production concentrates on entry-level Rebel and D3xxx series for developing market education sectors.
Mirrorless systems hold installed capacity. Full-frame digital bodies are rotating up the share rankings.
Application:
Customer willingness-to-pay varies dramatically by application, with wildlife and event photography supporting equipment investments that landscape and portrait segments cannot justify.
- Portrait Photography:Studio and on-location headshot work demands fast prime lenses with focal lengths between 85mm and 135mm. Social media influencer expansion in São Paulo and Jakarta is pulling entry-level full-frame bodies into first-time interchangeable lens purchases.
- Landscape Photography:Ultra-wide zooms and graduated neutral density filter systems anchor equipment selections. Weather-sealed bodies with high dynamic range sensors serve photographers operating in Patagonia and Iceland conditions.
- Event Photography:Wedding and corporate documentation requires dual card slot redundancy and silent shutter mechanisms. Dual-pixel autofocus systems from Canon dominate this segment due to face-tracking reliability in mixed lighting.
- Wildlife Photography:Super-telephoto prime lenses with integrated teleconverters represent the highest per-customer equipment investment tier. Safari tourism recovery in Kenya and Tanzania is rebuilding demand for 600mm and 800mm optics.
Event photography holds installed capacity. Wildlife applications are rotating up the share rankings.
End User:
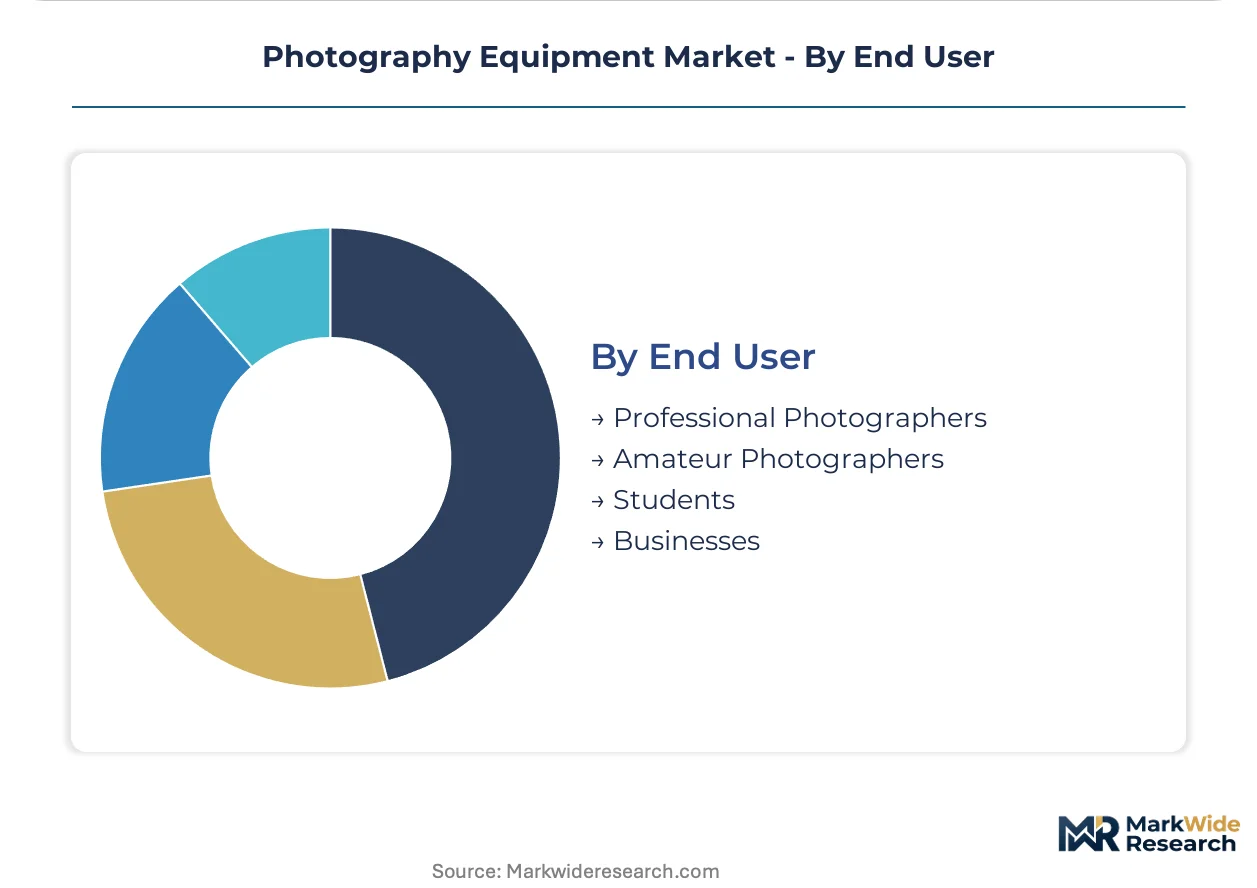
Professional photographers generate concentrated transaction values but amateur volumes drive component scale economies that lower marginal costs across all tiers.
- Professional Photographers:Full-time image creators with established client relationships purchase on three-year depreciation cycles. Photojournalists in conflict zones and commercial studios in Tokyo represent divergent durability versus resolution priorities.
- Amateur Photographers:Enthusiast hobbyists with discretionary income sustain the mid-tier body and lens replacement market. YouTube tutorial consumption in Bangalore and Mexico City is accelerating technical sophistication in this segment.
- Students:Educational program enrollees at Rochester Institute of Technology and similar institutions enter through entry-level DSLR or used mirrorless bodies. University procurement contracts favor Canon and Nikon due to service network density.
- Businesses:Corporate marketing departments and real estate agencies purchase equipment for in-house content production. E-commerce product photography requirements in Shenzhen and Amsterdam are standardizing on 45+ megapixel bodies for cropping flexibility.
Professional photographers hold installed capacity. Amateur creators are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for photography equipment varies sharply by geography. Japanese professionals absorb premium pricing for stacked CMOS bodies without volume attrition. Indian content creators drive entry-level mirrorless demand through extreme price sensitivity.
Japan
Wedding photographers in Tokyo and Osaka upgrade full-frame bodies on compressed two-year cycles. METI energy-efficiency standards on battery-powered systems accelerate solid-state cell adoption in domestic assembly. The Tokyo-Yokohama corridor concentrates CMOS fabrication and precision glass grinding for global component supply.
United States
YouTube tutorial influencers receive pre-release hardware through manufacturer ambassador programs, bypassing traditional retail. FCC equipment authorization requirements shape wireless flash and remote trigger compliance costs. Los Angeles anchors cinema lens rental fleet rotations for streaming production houses.
Germany
EU F-Gas Regulation mandates solvent-free coating deposition by 2027, forcing vacuum line retrofits at optical houses. REACH-compliant fluoropolymer formulation expertise concentrates among retiring specialists in Wetzlar and Solms. Bavarian precision mechanics clusters supply carbon fiber tripod components to premium brands.
India
Short-form video creators in Mumbai and Bangalore generate first-time interchangeable lens demand outside traditional camera markets. BIS certification requirements for electronic imports extend product launch timelines for international brands. Delhi-NCR e-commerce fulfillment centers handle direct-to-creator distribution for mid-tier mirrorless systems.
China
Shenzhen e-commerce product photography studios standardize on high-resolution bodies for cropping flexibility in catalog workflows. MIIT radio transmission regulations constrain wireless trigger frequency bands for domestic market models. Pearl River Delta assembly plants produce voice coil motor actuators dependent on neodymium supply from Chinese processing facilities.
Photography Equipment Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the photography equipment industry. The market structure consolidates around sensor fabrication scale and optical coating heritage, with three to four firms controlling professional-tier volume. Dominant archetypes include vertically integrated CMOS fabricators, precision optical houses with century-old glass expertise, and electronics conglomerates leveraging consumer scale for component sourcing. Competitive moves concentrate on backward integration into sensor foundries and direct-to-creator channel bypass of retail intermediaries.
Among heritage optical houses, Leica Camera AG and Hasselblad occupy positions defined by mechanical precision and medium-format heritage. Canon Inc. and Sony Corporation exemplify divergent approaches to vertical scope, with one emphasizing captive CMOS supply and the other dominating third-party sensor sales. Nikon Corporation sits within the precision glass tier, leveraging backward integration into optical component manufacturing.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Leica Camera AG |
| Canon Inc. |
| Hasselblad |
| Olympus Corporation |
| Sony Corporation |
| Panasonic Corporation |
| DJI |
| Nikon Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between CMOS foundries and camera manufacturers lock in wafer allocation and stabilize sensor costs across volatile rare earth markets. These contracts bind Tokyo-based fabricators to tier-one assembly partners, insulating flagship body pricing from spot-market neodymium swings while exposing mid-tier brands to component scarcity.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure across professional optics, forcing coating chemistry investments that concentrate margin in scaled manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates cinema rental houses from enthusiast creators from educational procurement. Cost compression in mid-tier mirrorless bodies intensifies because smartphone computational photography erodes entry-level addressable demand. Amateur content creators in India and Southeast Asia exhibit extreme price sensitivity, while Japanese wedding professionals absorb premium stacked-CMOS pricing without volume attrition.
Supply Chain Analysis
Japan and Taiwan anchor CMOS wafer fabrication and precision glass grinding for global component supply. Voice coil motor actuators draw from neodymium processing concentrated in Chinese facilities, while anti-reflective coating deposition rests on fluoropolymer feedstocks governed by REACH compliance. Single-source vulnerability in 300mm sensor foundry capacity threatens volume scaling for second-tier camera brands. Distribution runs through direct-to-creator channels displacing traditional retail in North American and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photography equipment is approaching a platform-economics inflection where lens mount interoperability and computational-optical convergence determine ecosystem lock-in. The shift from proprietary glass libraries to adapter-enabled vintage compatibility is reshaping competitive moats.
For Market Incumbents: Compound sensor fabrication scale with captive coating chemistry expertise to outpace EU F-Gas compliance costs that burden smaller optical houses. Deepen backward integration into solid-state battery cell production ahead of Japan METI efficiency mandates. Defend against smartphone substitution by accelerating AI-powered subject tracking differentiation in firmware updates.
For New Entrants and Emerging Players: CE marking fast-track for solvent-free coating processes opens white-space entry into European professional cinema lens supply. Target India's first-time interchangeable lens demand among Mumbai and Bangalore short-form video creators. Pursue computational-optical hybrid positioning between flagship smartphones and dedicated cameras, leveraging cloud-based editing integration as the go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward precision optical houses with century-old glass expertise and stranded coating chemist knowledge. Long-term viability hinges on 5-10 year durability of mechanical-optical differentiation against computational photography erosion. Watch for inflection in adapter-to-native lens attachment rates as the signal of ecosystem commitment depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Foundries | Canon and Sony secure wafer allocation priority against mid-tier competitors during capacity constraints. |
| Solvent-Free Coating Line Retrofit | German and Japanese manufacturers absorb EU F-Gas compliance costs that exclude smaller optical houses. |
| Direct-to-Creator Channel Expansion | YouTube ambassador programs bypass retail intermediaries, capturing margin from influencer-driven demand. |
| Computational-Optical Product Convergence | AI-powered subject tracking integration opens hybrid categories between smartphones and dedicated cameras. |
| Vintage Mount Adapter Engineering | Compatibility lock-in expands addressable glass libraries without immediate lens revenue generation. |
Study Parameters
The analysis maps mirrorless body specifications, interchangeable lens categories, and stabilization accessory tiers, each validated through product managers at tier-one manufacturers, coating chemists at German optical houses, and procurement leads at Mumbai cinema rental fleets. Primary interviews with METI regulatory affairs specialists and EU ECHA compliance officers combined with secondary validation from Japan Camera and Imaging Products Association shipment data, U.S. Census Bureau import records, and Indian BIS certification filings. Bottom-up unit shipment modeling and top-down value aggregation triangulate market size estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include sensor format tier, lens mount ecosystem, application workflow type, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical shipment patterns adjusted for technology substitution effects. Forecast inputs incorporate CMOS foundry capacity expansion timelines and EU F-Gas implementation enforcement intensity.
The analysis sits within stated boundaries; outcomes outside sustained smartphone computational photography advancement or abrupt rare earth supply disruption would require recalibration. Forecasts reflect assumptions about content creator demand persistence and coating chemistry substitution feasibility. Recalibration cycles align with material shifts in Japan METI battery efficiency mandates and EU REACH chemical restriction expansions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Europe Industrial Computed Tomography Market
Imaging
Global Automotive Imaging Market
Imaging
Machine Vision System Market
Imaging
Widefield Imaging Systems Market
Imaging
Handheld Imaging Systems Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Thermal Camera Market
Imaging
Machine Vision Camera Market
Imaging
Ent Cameras Market
Imaging
Pico Projector Market
Imaging
Semiconductor CD-SEM Systems Market
Imaging
APAC Image Sensors Market
Imaging
Compact Camera Module Market
Imaging
Global Camera Module Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Handheld Thermal Imaging Equipment Market