
 Latin America IP Camera Market | 2026-2036
Latin America IP Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America IP Camera Market Insights
Brazil's ANATEL homologation mandate for telecommunications equipment is repositioning procurement patterns toward locally certified distributors. Hangzhou Hikvision Digital Technology Co Ltd leverages its São Paulo logistics hub to sustain rapid fulfillment across Mercosur markets. Bosch Security and Systems anchors its regional presence through dedicated training centers in Mexico City and São Paulo. Motorola Solutions Inc competes on public safety integration, bundling IP cameras with command-center software for municipal clients.
An IP camera captures and transmits digital video data over Internet Protocol networks using embedded processors, compression codecs such as H.265, and Power-over-Ethernet connectivity for simplified cabling. These devices serve commercial security, traffic enforcement, and remote industrial monitoring by converting optical signals into network-addressable streams accessible via VMS platforms. Dome configurations lead residential and retail deployments due to discreet housing and vandal-resistant designs, while PTZ units command premium positioning in perimeter defense and large-area surveillance where active operator control replaces fixed-view limitations. Wireless technology segments gain traction in heritage sites and temporary installations where cable trenching proves impractical or cost-prohibitive.
ANATEL in Brazil, IFT in Mexico, and Subtel in Chile enforce electromagnetic compatibility and cybersecurity baselines that determine market access for imported IP cameras. These frameworks elevate compliance costs for uncertified vendors while creating protected channels for authorized distributors with in-country testing partnerships. Stakeholders must monitor evolving data localization requirements and encryption standards that could fragment procurement specifications across national borders.
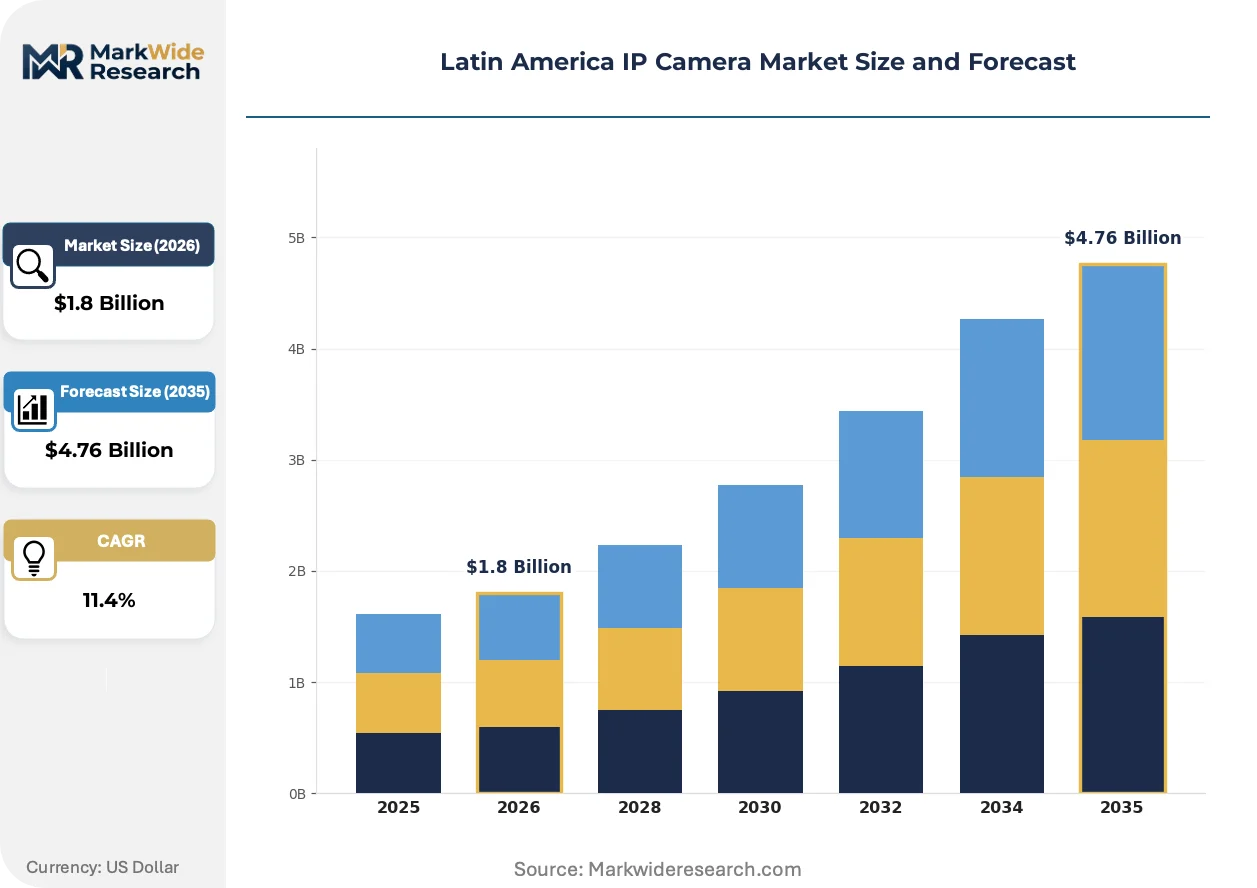
Market Dynamics
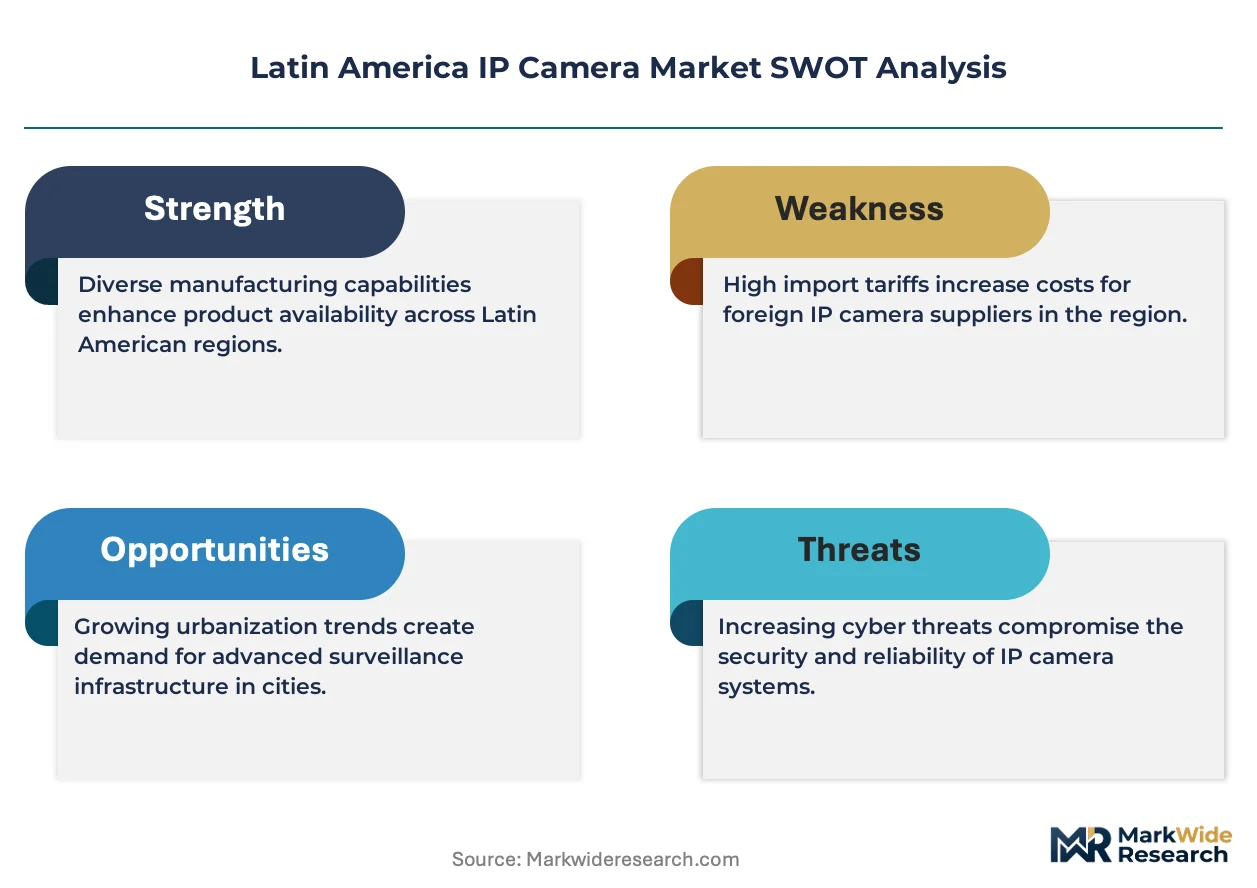
ANATEL homologation mandates in Brazil are restructuring import channels toward certified local distributors, forcing network video equipment vendors to relocate assembly and testing capabilities within Mercosur borders or surrender market access to authorized partners.
Growth Catalysts
- Smart city infrastructure:Municipal surveillance networks across São Paulo, Rio de Janeiro, and Minas Gerais states are scaling IP camera deployment for traffic enforcement and public safety command centers.
- IFT electromagnetic compliance:Mexico's telecommunications regulator is accelerating formal certification pathways that reward pre-tested equipment with faster customs clearance and federal procurement eligibility.
- Power-over-Ethernet advancement:IEEE 802.3bt high-power delivery is eliminating separate electrical runs in heritage buildings and temporary installations across Colombian heritage sites.
Market Restraints
- Semiconductor input volatility:Image sensor and SoC supply concentrates in East Asian foundries, exposing Latin American integrators to allocation rationing and extended lead times without regional buffer inventory.
- ANATEL testing bottlenecks:Brazil's single-digit accredited laboratory capacity for RF and cybersecurity validation creates 90-120 day certification queues that freeze product launches.
- Legacy analog substitution ceiling:Price-sensitive small retailers in peripheral urban zones continue deploying CVBS/TVI systems despite IP migration trends, capping premium product penetration.
Strategic Opportunities
- Chilean mining corridor:Remote industrial monitoring in Atacama and Antofagasta regions lacks ruggedized wireless IP coverage, creating white space for explosion-proof PTZ deployments with satellite backhaul.
- Subtel cybersecurity tiering:Chile's national telecom regulator is drafting mandatory encryption baselines for critical infrastructure that will advantage vendors with pre-certified H.265+ and AES-256 implementations.
- Edge-AI convergence:On-camera analytics fusion with 5G private networks is opening real-time facial recognition and perimeter breach detection contracts at Colombian port authorities and Brazilian logistics hubs.
Industry Challenges
- Multi-regulator certification fatigue:Vendors must simultaneously navigate ANATEL, IFT, and Subtel electromagnetic and data protection regimes with non-harmonized test protocols, multiplying compliance engineering headcount.
- VMS integration complexity:Municipal clients demand seamless API bridges between new IP streams and legacy analog matrix switches, forcing custom middleware development that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America IP Camera Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dome, Bullet, PTZ, C-mount Technology: Analog, Digital, Wireless, Hybrid End User: Residential, Commercial, Government, Industrial Application: Surveillance, Monitoring, Traffic Management, Retail Security |
| Companies Covered | Sony Corporation, Bosch Security and Systems, Hangzhou Hikvision Digital Technology Co Ltd, Motorola Solutions Inc, Honeywell HBT, Hanwha Vision America, Johnson Controls, GeoVision Inc, Samsung Electronics Co Ltd, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America IP Camera Market Trends and Innovations
Edge computing architectures and AI-native silicon are compressing the latency window for real-time video analytics, while regulatory fragmentation across Brazil, Mexico, and Chile is spawning specialized compliance service layers.
H.265+ and Smart Codec compression is electrifying bandwidth efficiency in metropolitan surveillance networks. Brazilian state police departments and Mexican city governments are mandating these formats for new tenders to preserve fiber capacity. This compression advance is electrifying the displacement of H.264-only equipment from federal procurement lists, compressing residual value in installed base upgrades.
ANATEL Resolution 242 is tightening cybersecurity baselines for network video equipment entering Brazil, requiring firmware signing and vulnerability disclosure protocols. Industrial consequence includes mandatory in-country firmware customization that blocks direct gray-market imports. Municipal and banking verticals are responding by restricting vendor shortlists to holders of permanent ANATEL homologation certificates with local legal representation.
Subscription-based video-analytics licensing is unbundling hardware from software revenue in enterprise security procurement. Large retail chains across São Paulo and Mexico City are shifting from perpetual VMS licenses to per-camera monthly fees that include cloud storage and AI feature updates. This model is most visible in Brazil's southeastern retail corridor where IT security budgets favor operational expenditure classification over capital depreciation cycles.
Latin America IP Camera Market Segmentation
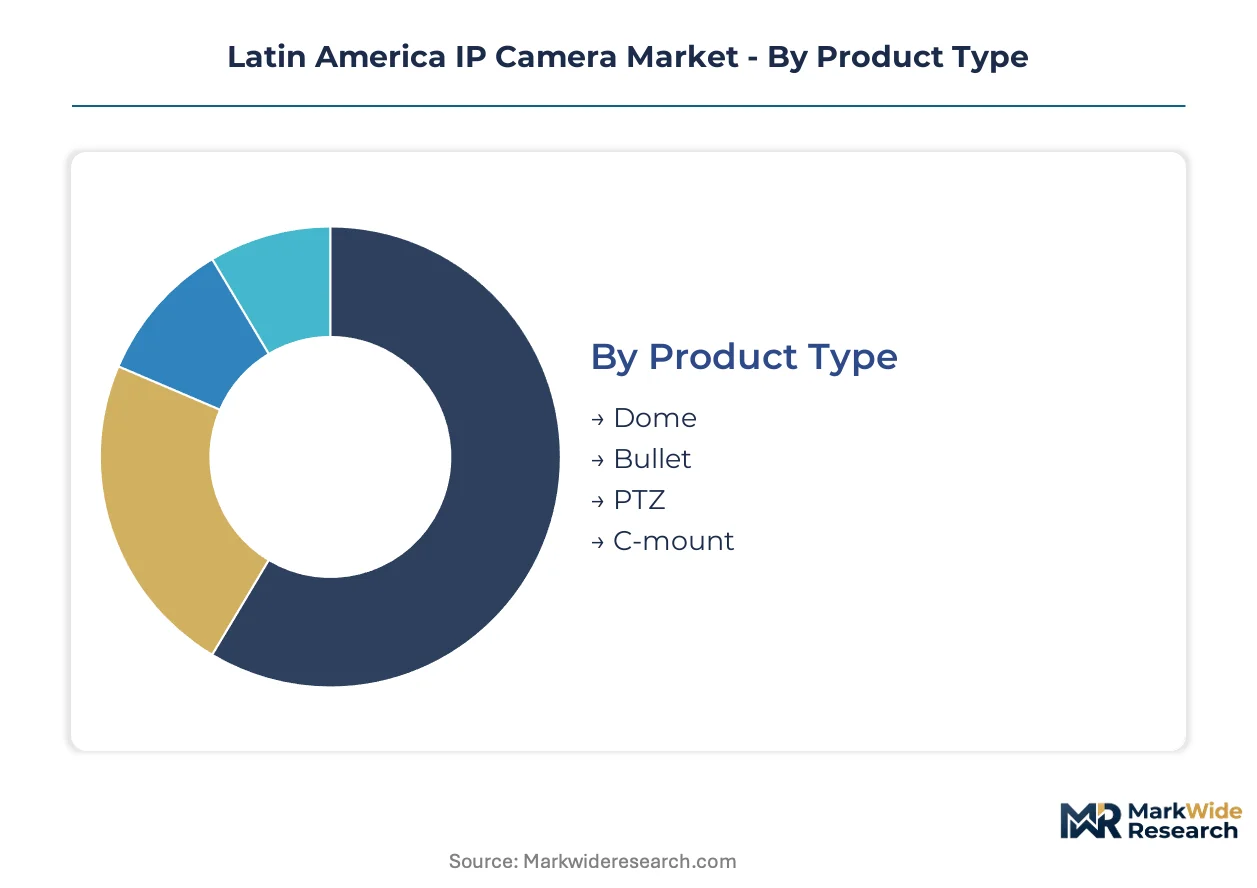
Latin American procurement patterns diverge sharply between volume-driven residential deployments and premium-tier municipal contracts. ANATEL certification requirements and PoE infrastructure gaps create distinct cost-performance trade-offs across each segment boundary.
Product Type:
Dome units dominate unit volume across Brazil's southeastern retail corridor, while PTZ configurations capture disproportionate margin in federal security tenders.
- Dome:Vandal-resistant housings with 360-degree coverage suit São Paulo shopping centers and Rio de Janeiro transit hubs. Brazilian state police departments specify IK10-rated domes for public space deployments where physical tampering risks concentrate.
- PTZ:Motorized pan-tilt-zoom mechanisms with optical zoom exceeding 30x enable perimeter defense at Colombian ports and Chilean mining installations. Command-center operators demand these units for active threat tracking across large-area surveillance zones.
- Bullet:Weather-sealed cylindrical housings with integrated IR illumination serve outdoor perimeter applications across Mexico's northern industrial parks.
- C-mount:Interchangeable lens systems accommodate specialized optics for machine vision and scientific monitoring in Brazilian agricultural research stations.
Today's leader: Dome. Tomorrow's challenger: PTZ.
Technology:
Digital IP streams displace analog infrastructure fastest where fiber backhaul exists, while wireless segments expand in heritage zones with cable trenching restrictions.
- Digital:H.265+ compression with Power-over-Ethernet connectivity eliminates separate electrical infrastructure in new Brazilian smart city builds. São Paulo municipal tenders now mandate digital-native equipment for traffic enforcement networks.
- Wireless:802.11ac/ax mesh configurations with solar power integration serve temporary installations across Colombian archaeological sites and Brazilian agricultural frontiers. ANATEL spectrum licensing creates compliance friction that advantages pre-certified vendor partnerships.
- Analog:CVBS/TVI systems persist in price-sensitive small retail deployments across peripheral urban zones where IP migration capital budgets remain constrained.
- Hybrid:Multi-protocol encoders bridge legacy coaxial infrastructure with IP backhaul, easing transition pain for Mexican municipal clients with mixed installed bases.
Digital installations command the steepest expansion trajectory. Wireless deployments are gaining share fastest in heritage-protected zones.
End User:
Government verticals concentrate premium procurement through certified channels, while residential demand fragments across uncertified import streams.
- Government:Federal and state security agencies across Brazil, Mexico, and Chile mandate ANATEL, IFT, or Subtel certification with local legal representation. Command-center integration requirements favor vendors with in-country training infrastructure.
- Commercial:Large retail chains in São Paulo and Mexico City shift toward subscription-based analytics licensing with cloud storage components. IT security budgets favor operational expenditure classification over capital depreciation cycles.
- Residential:Consumer-grade WiFi cameras with mobile app integration spread through Brazilian e-commerce channels, often bypassing formal homologation requirements.
- Industrial:Explosion-proof specifications for Chilean mining corridors and Brazilian petrochemical facilities demand ruggedized housings with satellite backhaul compatibility.
Commercial verticals drive margin expansion. Government tenders anchor volume concentration.
Application:
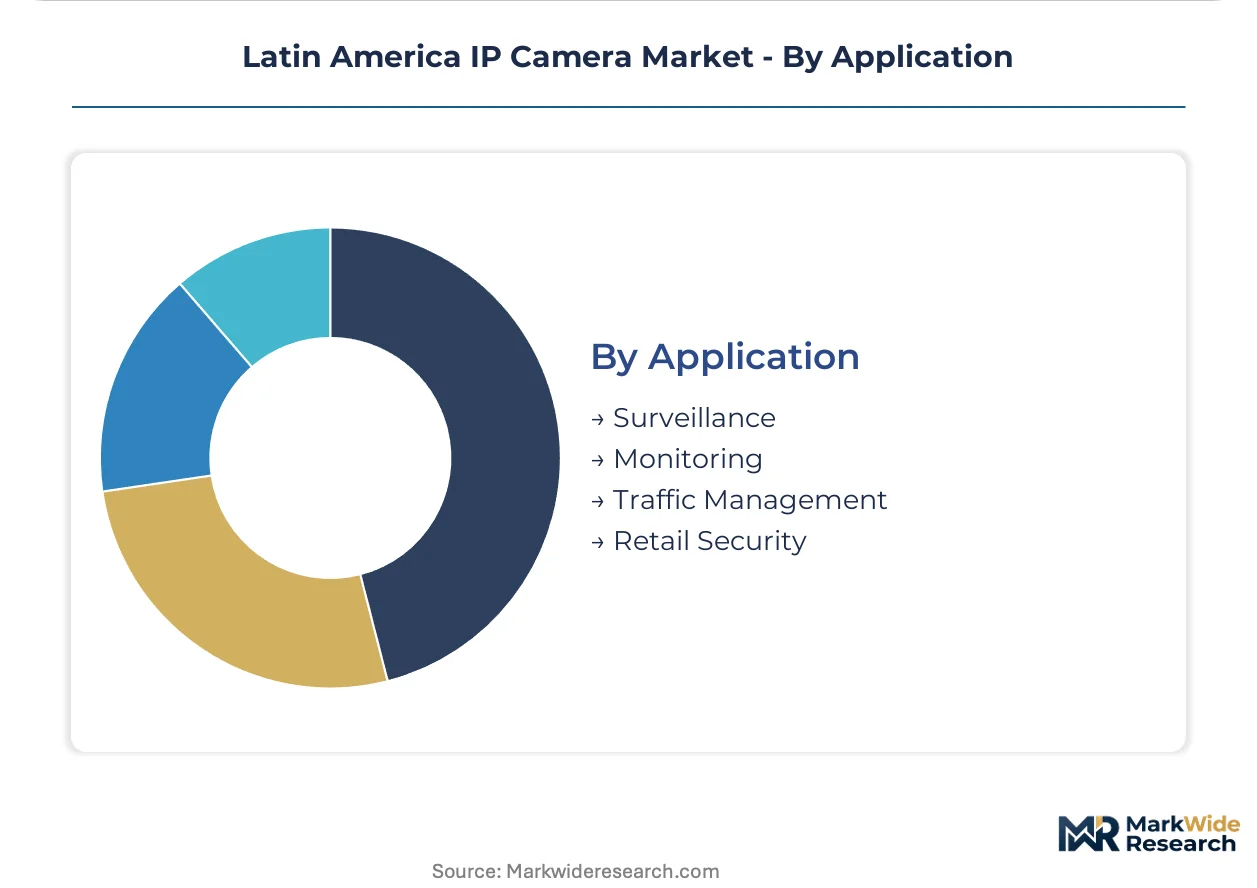
Surveillance applications absorb the bulk of metropolitan fiber capacity, while traffic management contracts impose the strictest latency and compression standards.
- Surveillance:Real-time monitoring for public safety and asset protection dominates bandwidth consumption across Brazilian state police networks and Mexican city government command centers.
- Traffic Management:Automatic number plate recognition and red-light enforcement systems in São Paulo and Rio de Janeiro require edge-AI processing with sub-100ms latency for violation capture validity.
- Monitoring:Remote industrial oversight in Chilean Atacama mining regions and Colombian logistics hubs favors satellite-backhaul wireless configurations with offline storage buffering.
- Retail Security:Loss prevention analytics with dwell-time and heat-mapping functions spread through São Paulo's southeastern retail corridor via per-camera monthly licensing models.
Surveillance maintains installed base dominance. Traffic management claims the fastest technology refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Latin America IP camera industry traces its commercial roots to São Paulo's early 2000s security integration sector, where Brazilian distributors first aggregated Asian-manufactured network video equipment for Mercosur markets. This foundation established procurement patterns that persist today, with certification requirements and logistics hubs concentrated in the region's largest metropolitan corridors.
Brazil
Smart city infrastructure in São Paulo, Rio de Janeiro, and Minas Gerais states drives municipal surveillance network expansion. ANATEL Resolution 242 mandates firmware signing and vulnerability disclosure for all network video equipment, blocking direct gray-market imports. The southeastern corridor anchors procurement volume, with state police departments specifying IK10-rated dome configurations for public space deployments.
Mexico
Federal security tenders and northern industrial park surveillance sustain demand for weather-sealed bullet cameras with integrated IR illumination. IFT electromagnetic compliance certification accelerates customs clearance and unlocks federal procurement eligibility for pre-tested equipment. Mexico City serves as the regional training hub where command-center integration capabilities concentrate.
Chile
Remote industrial monitoring in Atacama and Antofagasta mining regions creates demand for explosion-proof PTZ units with satellite backhaul compatibility. Subtel is drafting mandatory encryption baselines for critical infrastructure that will advantage vendors with pre-certified H.265+ and AES-256 implementations. The northern mining corridor lacks ruggedized wireless IP coverage, presenting white space for specialized deployments.
Colombia
Port authority contracts and logistics hub security drive edge-AI convergence with 5G private networks for real-time perimeter breach detection. IEEE 802.3bt high-power PoE eliminates separate electrical runs in heritage-protected archaeological sites where cable trenching is prohibited. Bogotá and Cartagena anchor commercial procurement, with Caribbean port installations commanding premium analytics integration.
Argentina
Economic volatility constrains capital expenditure cycles, yet Buenos Aires municipal security programs maintain selective IP migration in high-traffic transit corridors. Mercosur trade integration allows Brazilian-certified equipment to enter via simplified customs pathways, reducing effective compliance burdens for ANATEL-homologated vendors. The metropolitan area concentrates residual demand from banking and retail verticals.
Latin America IP Camera Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and command-center integration capabilities. The vendor base stratifies between full-stack security conglomerates with regional training infrastructure and specialized network video equipment manufacturers dependent on distributor partnerships. Three archetypes dominate: integrated safety-technology conglomerates, dedicated video surveillance specialists, and diversified electronics manufacturers with security divisions. Capacity expansion into local assembly facilities and strategic partnerships with in-country testing laboratories represent the dominant competitive moves.
Within the integrated conglomerate tier, Hangzhou Hikvision Digital Technology Co Ltd and Bosch Security and Systems exemplify contrasting geographic anchoring strategies. Hangzhou Hikvision leverages its São Paulo logistics hub to sustain rapid fulfillment across Mercosur markets, while Bosch anchors regional presence through dedicated training centers in Mexico City and São Paulo. Motorola Solutions Inc occupies a position emphasizing public safety system integration, bundling network video equipment with command-center software for municipal clients. These three represent the certification-heavy, relationship-driven competitive vector that ANATEL, IFT, and Subtel frameworks increasingly favor.
| Leading Market Players |
|---|
| Sony Corporation |
| Bosch Security and Systems |
| Hangzhou Hikvision Digital Technology Co Ltd |
| Motorola Solutions Inc |
| Honeywell HBT |
| Hanwha Vision America |
| Johnson Controls |
| GeoVision Inc |
| Samsung Electronics Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ANATEL-homologated premium tiers and uncertified gray-market imports manifests in pricing power concentration among authorized distributors while supply chains reorganize around São Paulo logistics hubs and Mexican customs clearance corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ANATEL-certified federal contractors from municipal integrators and residential e-commerce channels. Price differentiation rests on certification depth and command-center integration capabilities. Pricing pressure stems from semiconductor input volatility and extended certification queues. Residential WiFi camera buyers exhibit highest price sensitivity while government security agencies prioritize compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in São Paulo and Mexico City anchor hub-and-spoke fulfillment patterns across Mercosur and northern Mexico industrial corridors. Image sensor and SoC supply concentrates in Taiwan, South Korea, and China, exposing Latin American integrators to allocation rationing. Single-source vulnerability in East Asian foundries creates structural risk. Distribution runs through certified local partners with in-country testing laboratory relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America IP Camera Market functions as a stable compounder anchored by irreversible smart city infrastructure commitments across Brazilian and Mexican metropolitan corridors.
For Market Incumbents: Extend certification infrastructure depth by securing permanent ANATEL homologation certificates with local legal representation, and expand São Paulo logistics hub capacity to buffer against East Asian semiconductor allocation volatility. Threat substitution emerges from edge-AI native entrants bundling analytics with hardware. Vertical integration into firmware customization capabilities represents the critical defensive lever. For New Entrants and Emerging Players: Capture white space in Chilean mining corridor explosion-proof PTZ deployments and Colombian 5G private network port authority contracts where incumbent coverage remains thin. The most penetrable segment comprises ruggedized wireless configurations with satellite backhaul compatibility. Go-to-market execution should prioritize partnerships with in-country testing laboratories to compress certification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-regulator certification fatigue fragments vendor economics and elevates compliance engineering headcount disproportionately. Long-term viability favors acquirers of ANATEL-certified distributors with established municipal relationships and training infrastructure. Signal to monitor: IFT and Subtel encryption baseline finalization dates that will trigger vendor shortlist restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| ANATEL Certification Investment | Unlocks federal procurement eligibility and blocks gray-market competitors from banking verticals. |
| São Paulo Logistics Hub Expansion | Compresses fulfillment lead times across Mercosur markets and sustains rapid municipal tender response. |
| Edge-AI Analytics Partnership | Enables real-time facial recognition contracts at Colombian port authorities and Brazilian logistics hubs. |
| In-Country Testing Laboratory Alliance | Reduces 90-120 day certification queues that currently freeze product launches. |
| Subscription Licensing Model Migration | Captures recurring revenue from São Paulo retail chains favoring operational expenditure classification. |
Research Methodology
Multiple input streams — primary interviews with municipal security procurement officers, VMS platform engineers, and ANATEL certification consultants; secondary validation against customs import records, telecommunications regulator filings, and smart city tender databases; plus distributor shipment audits — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across product type, technology, end user, and application dimensions, with regional regulatory cluster as an additional modeling layer. CAGRs were derived from segmented growth trajectory analysis incorporating PoE infrastructure deployment rates, fiber backhaul expansion timelines, and municipal budget allocation patterns.
Underlying measurement precision varies by segment; government and commercial verticals carry tighter precision than residential channels where informal import flows obscure tracking. Forecasts reflect documented assumptions around certification timeline normalization and semiconductor supply stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Image Intensifier Market
Imaging
Gige Camera Market
Imaging
Camera Accessories Market
Imaging
TDI Camera Market
Imaging
Japan Digital X-Ray Market
Imaging
Industrial X-Ray Inspection Equipment and Imaging Software Market
Imaging
SDI Camera Market
Imaging
X-Ray Systems Market
Imaging
Weatherproof Camera Market
Imaging
Global Image Processing Systems Market
Imaging
Photoacoustic Tomography Market
Imaging
Computer Aided Detection Market
Imaging
Plenoptic Camera Market
Imaging
Instaprint Camera Market
Imaging
Mobile Camera Module Market
Imaging
SWIR Camera Market