
 Automotive Compact Camera Module Market | 2026-2036
Automotive Compact Camera Module Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Compact Camera Module Market Intelligence
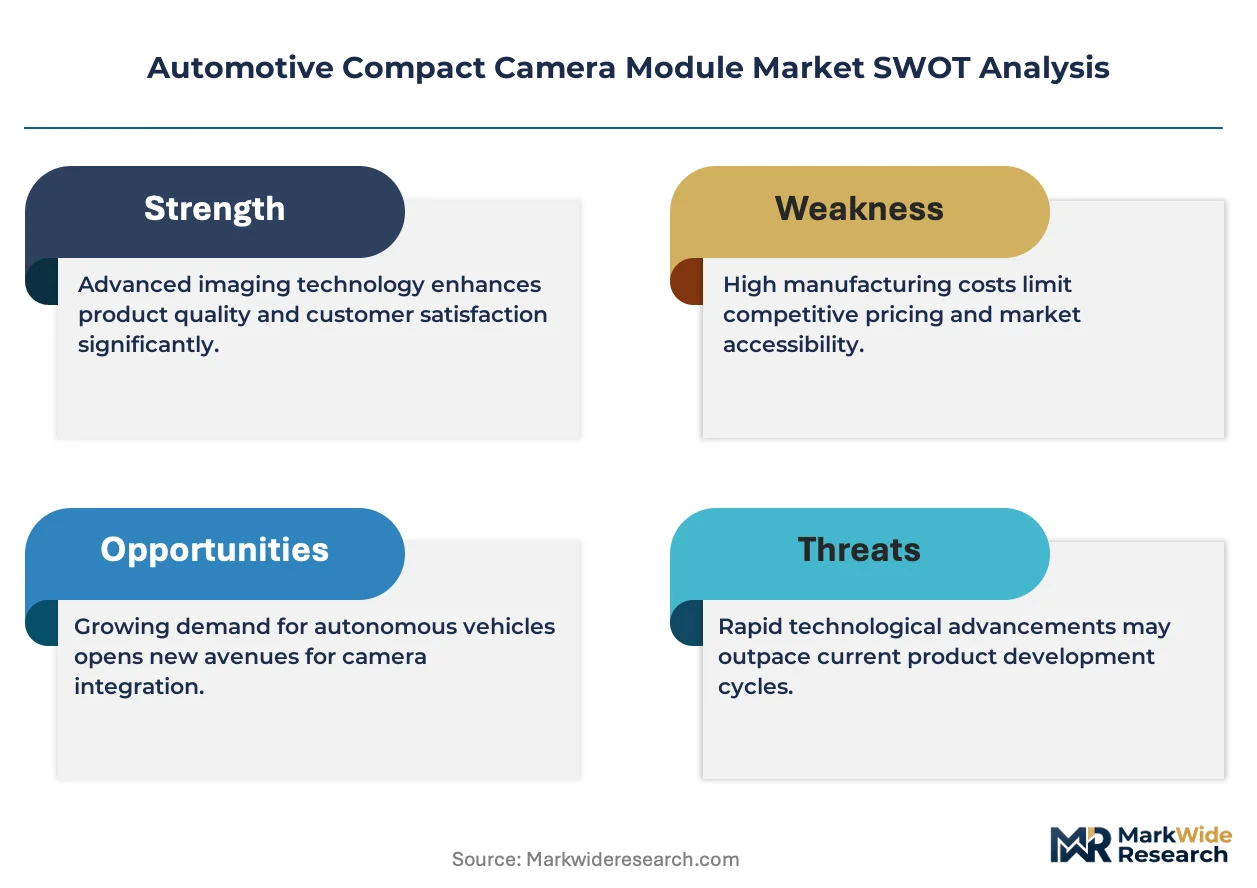
The capital investment gap between fabless image processor design and integrated module manufacturing is rotating market structure toward specialized partnerships. Robert Bosch GmbH leverages its vast manufacturing scale for system integration. Continental AG competes on its comprehensive ADAS portfolio, embedding its own camera modules. In contrast, Ambarella Inc. specializes in high-performance System-on-Chip (SoC) development, supplying critical processing power to module makers.
An automotive compact camera module is an integrated optoelectronic device combining a lens assembly, an image sensor, and signal processing circuitry within a sealed housing. Its primary function is to capture high-fidelity visual data for vehicle perception systems, often featuring a CMOS sensor for its low power consumption and fast readout speeds. Within applications, Advanced Driver Assistance Systems represent the largest volume driver. Demand for High-Dynamic Range (HDR) imaging technology is accelerating to improve performance in varied lighting conditions, a critical requirement for surround view systems.
Functional safety standards, notably ISO 26262, dictate stringent design and validation processes for all critical camera components. Concurrently, regulations from bodies like the US National Highway Traffic Safety Administration (NHTSA) and rules under the UNECE framework create direct demand for specific camera-based safety features. Module suppliers must now navigate the complex trade-off between increasing sensor resolution and processing power while managing thermal dissipation within ever-shrinking physical footprints.
Market Dynamics
The market's central dynamic is the tension between escalating safety mandates and the physical constraints of vehicle design. Regulatory pressure from bodies like the NHTSA and under the UNECE framework compels higher camera counts and performance for ADAS.
Growth Catalysts
- Regulatory Mandates:The European Union's General Safety Regulation requires advanced safety systems in new vehicles, directly stimulating demand for camera modules for features like lane departure warnings and emergency braking.
- Technology Advancement:Demand for High-Dynamic Range (HDR) imaging is rising to improve sensor performance in challenging lighting. This is critical for the accuracy of surround-view systems and automated parking functions.
- National Industrial Policy:China's focus on vehicle intelligence as a strategic priority accelerates the integration of sophisticated camera systems, pushing local OEMs to adopt multi-camera setups for higher levels of driving automation.
Market Restraints
- Thermal Management Complexity:Increasing sensor resolutions and onboard processing power generate significant heat, creating a major design challenge to dissipate it effectively within the module's compact, sealed housing.
- Capital Investment Barriers:The high capital expenditure required for vertically integrated module manufacturing and cleanroom assembly creates a barrier to entry, favoring large, established players with significant scale.
- Stringent Safety Standards:Adherence to functional safety standards like ISO 26262 imposes rigorous and costly design, validation, and documentation requirements on every component, from the image sensor to the processing SoC.
Strategic Opportunities
- In-Cabin Sensing Applications:The development of driver and occupant monitoring systems represents a significant growth vector, using cameras for attention detection, personalization, and child presence detection to meet new safety protocols.
- Edge AI Integration:Converging AI processing directly onto the camera's System-on-Chip (SoC) enables faster decision-making and reduces data bandwidth to central ECUs, creating an opportunity for specialized, intelligent camera modules.
- Emerging Market Adoption:As safety standards begin to tighten in markets like India and Brazil, there is a clear opportunity for suppliers to introduce cost-effective ADAS camera solutions tailored for entry-level and mid-range vehicles.
Industry Challenges
- Sensor Fusion Complexity:A primary operational challenge is the effective integration of camera data with inputs from other sensors, such as radar and LiDAR. Ensuring reliable sensor fusion is critical for robust perception in all conditions.
- Supply Chain Volatility:The supply of automotive-grade CMOS image sensors is concentrated among a few key suppliers. This creates potential bottlenecks and sourcing challenges for module manufacturers during periods of high demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Compact Camera Module Market |
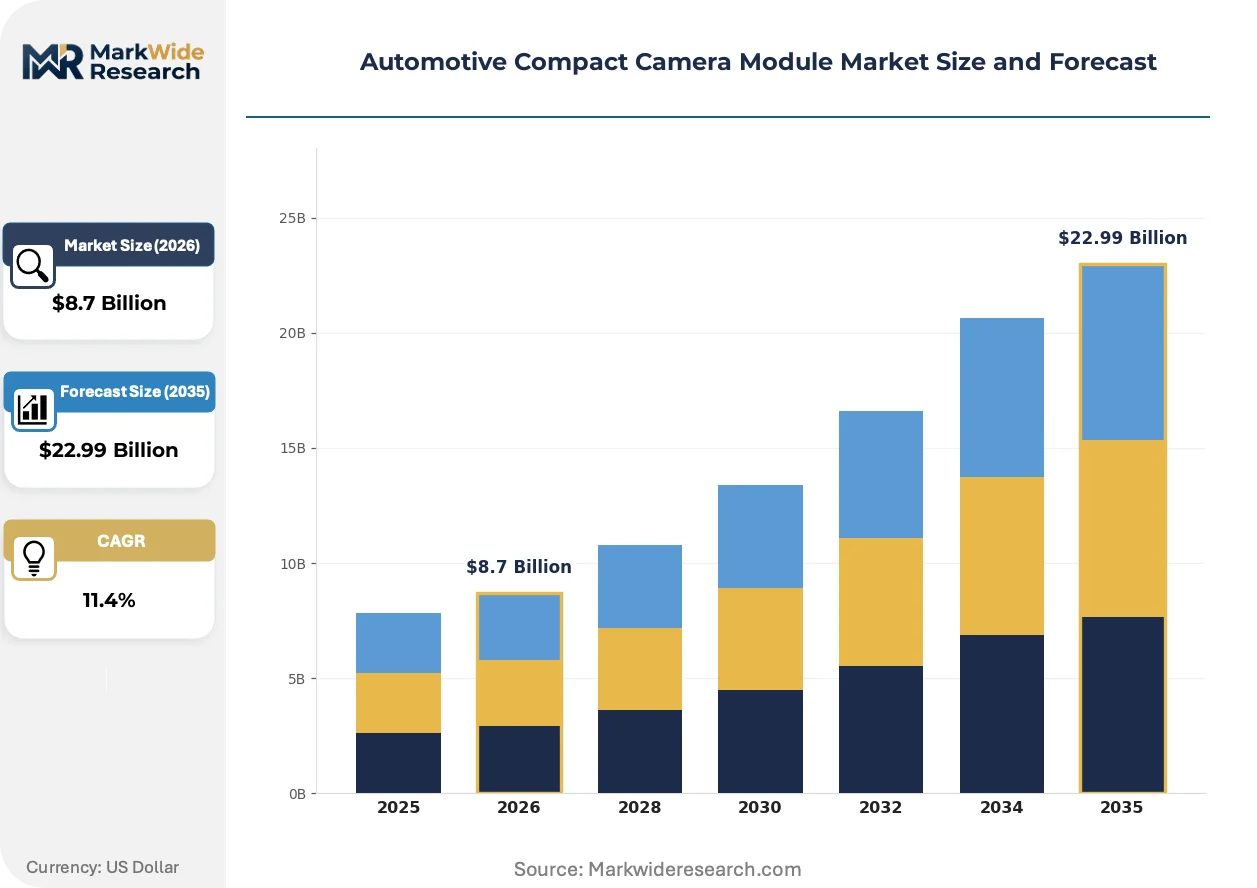
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lens Camera, Dual-Lens Camera, Multi-Lens Camera, Panoramic Camera, 3D Camera Technology: CMOS Sensor, CCD Sensor, Night Vision, HDR Imaging, High-Definition Application: Advanced Driver Assistance Systems, Surround View Systems, Parking Assistance, Blind Spot Detection, Lane Departure Warning End User: Original Equipment Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers, Fleet Operators |
| Companies Covered | Robert Bosch GmbH, Continental AG, Magna International Inc., Denso Corporation, Aptiv PLC, Valeo SA, LG Innotek Co. Ltd., Sony Group Corp., Ambarella Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Compact Camera Module Market Strategic Shifts & Innovations
The technological frontier is defined by the pursuit of machine vision that equals or exceeds human perception. This goal drives innovation in sensor technology, on-device processing, and the software architectures that interpret visual data for autonomous systems.
Event-based vision sensors, which detect changes in pixel luminance instead of capturing full frames, offer a new paradigm for vehicle perception. Automotive system designers are adopting this technology for specialized ADAS functions that demand extremely low latency and power consumption. This novel sensing approach is displacing traditional frame-based CMOS sensors in niche, high-speed applications like pre-collision systems and pedestrian avoidance.
In China, regulations from the Ministry of Industry and Information Technology (MIIT) are promoting specific ADAS capabilities as part of a national push for vehicle intelligence. This policy directly influences OEM product planning, creating demand for camera modules with integrated processing powerful enough to support Level 2+ automated driving features. The forward-facing camera segment is most affected, with suppliers embedding more advanced SoCs to meet these evolving performance standards.
A distinct behavioral shift involves automotive OEMs unbundling software from camera hardware procurement. This move away from turnkey hardware-software bundles from module makers allows OEMs to develop proprietary perception algorithms for greater brand differentiation. This trend is most prominent within the premium vehicle segments in Germany and the US, favoring module suppliers that provide open and programmable hardware platforms.
Automotive Compact Camera Module Market Segmentation
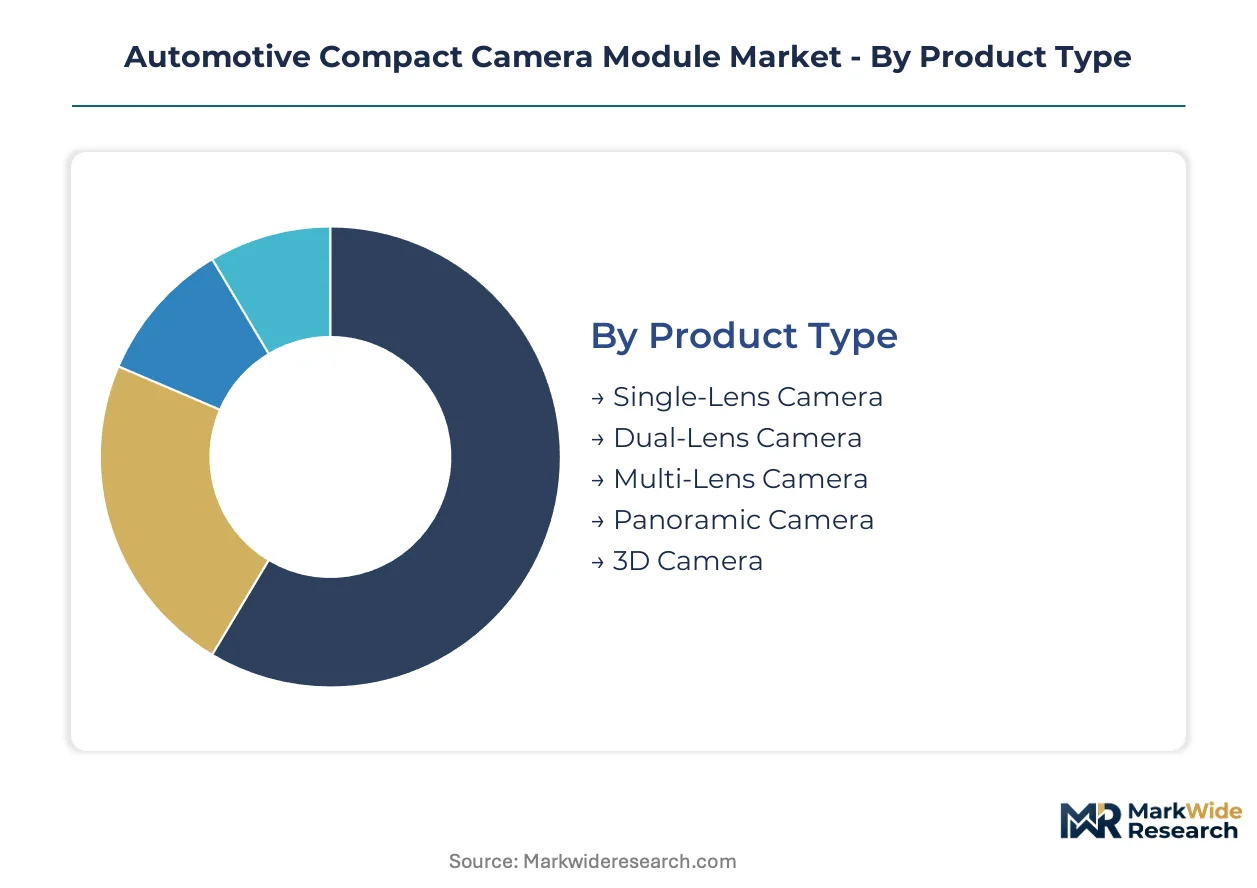
The automotive compact camera module market's segmentation reflects the intricate interplay between evolving vehicle architectures and stringent safety requirements. Understanding these distinct segments provides clarity on where engineering efforts and market investments are concentrating.
Product Type:
The product type segmentation for automotive compact camera modules reflects diverse design philosophies, catering to both established domestic vehicle models and advanced export markets.
- Single-Lens Camera:This fundamental design integrates one lens assembly with an image sensor and processing unit, primarily used for simpler ADAS functions like rear-view cameras or basic forward collision warnings in mass-market vehicles. Demand for these modules remains strong in entry-level vehicles and regions with nascent ADAS adoption.
- Multi-Lens Camera:These sophisticated modules incorporate multiple lens-sensor combinations, often with integrated processing, to provide wider fields of view or stereoscopic vision, crucial for advanced perception in premium vehicles and higher levels of automated driving. The push for Level 2+ autonomy in markets like China drives demand for these complex systems.
- Dual-Lens Camera:These systems often combine two lenses for specific applications like stereoscopic depth perception or wider-angle coverage for front-facing ADAS.
- Panoramic Camera:Designed for an ultra-wide field of view, these modules are essential for surround-view systems, enabling a 360-degree perspective around the vehicle.
- 3D Camera:Utilizing advanced sensing techniques, 3D cameras provide depth information, critical for precise object detection and environmental mapping in highly automated vehicles.
Single-Lens Camera commands the established base. The steepest expansion runs through Multi-Lens Camera.
Technology:
Technology segmentation highlights the foundational imaging components and the advanced capabilities demanded by evolving vehicle perception systems.
- CMOS Sensor:Complementary Metal-Oxide-Semiconductor sensors form the backbone of modern automotive camera modules, prized for their low power consumption, fast readout speeds, and cost-effectiveness in high-volume production. Their integration is pervasive across all camera applications.
- HDR Imaging:High-Dynamic Range imaging technology significantly improves image clarity and detail in challenging lighting conditions, such as tunnels, direct sunlight, or nighttime driving, making it indispensable for robust ADAS and autonomous driving systems. This technology is crucial for surround view systems operating in varied environments.
- CCD Sensor:Charge-Coupled Device sensors, while offering high image quality, are generally less common in new automotive designs due to higher power consumption and slower readout compared to CMOS.
- Night Vision:This technology enhances visibility in low-light conditions, typically through infrared illumination or highly sensitive sensors, improving safety for nighttime driving assistance systems.
- High-Definition:High-definition capabilities ensure superior image resolution, providing clearer visual data for perception algorithms and driver displays, particularly important for object recognition and detailed scene analysis.
CMOS Sensor technology forms the bedrock of current camera module designs. HDR Imaging is gaining momentum for its performance advantages.
Application:
Application segmentation delineates the functional roles of camera modules, from fundamental safety features to complex autonomous driving support.
- Advanced Driver Assistance Systems:ADAS applications represent the largest volume driver for automotive camera modules, encompassing functions like adaptive cruise control, lane keeping assist, and automatic emergency braking, mandated by regulations like the EU General Safety Regulation. These systems rely on precise visual data for real-time decision-making.
- Surround View Systems:These systems utilize multiple cameras positioned around the vehicle to create a stitched 360-degree view, assisting with parking, low-speed maneuvering, and obstacle detection. The demand for comprehensive spatial awareness drives this segment.
- Parking Assistance:Cameras provide visual aids for parking maneuvers, including rear-view cameras and automated parking systems, enhancing convenience and reducing collision risks.
- Blind Spot Detection:Cameras monitor adjacent lanes to alert drivers of vehicles in their blind spots, significantly improving highway safety.
- Lane Departure Warning:These systems use forward-facing cameras to detect unintentional lane changes, providing alerts to the driver to prevent accidents.
Advanced Driver Assistance Systems represent the largest segment by volume. Surround View Systems are experiencing significant uptake for comprehensive environmental awareness.
End User:
End user segmentation illustrates the varied procurement channels and integration points for automotive camera modules across the vehicle lifecycle.
- Original Equipment Manufacturers:OEMs are the primary purchasers, integrating camera modules directly into new vehicle designs during the manufacturing process to enable ADAS and infotainment features. Their procurement is driven by new model development and regulatory compliance.
- Tier-1 Suppliers:These suppliers act as intermediaries, integrating camera modules from component manufacturers into larger ADAS or infotainment systems, which they then supply to OEMs. Tier-1s often add their own software and system integration expertise.
- Aftermarket Providers:Aftermarket providers offer camera solutions for installation in vehicles post-purchase, catering to consumers seeking to upgrade older models with new safety or convenience features.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, often receiving pre-integrated camera systems from Tier-1 suppliers for installation into the vehicle chassis.
- Fleet Operators:Fleet operators integrate camera systems into their commercial vehicles for purposes such as driver monitoring, accident recording, and telematics, enhancing safety and operational oversight.
Original Equipment Manufacturers drive the bulk of initial demand. Tier-1 Suppliers play a critical role in system integration and delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive compact camera module market exhibits a nuanced export-import balance, with advanced manufacturing hubs supplying sophisticated components to diverse vehicle assembly regions. Key technology providers often concentrate production in specific countries, while demand is distributed globally. This intricate trade dynamic influences regional specialization and supply chain resilience.
China
China's demand for camera modules stems from rapid ADAS adoption for domestic and export vehicles. The Ministry of Industry and Information Technology (MIIT) regulations actively promote vehicle intelligence, mandating higher automated driving levels. Major automotive clusters in the Yangtze River Delta, like Shanghai, integrate sophisticated multi-camera systems.
Germany
Germany drives demand for premium camera modules, focusing on high-performance ADAS and autonomous driving. The KBA enforces UNECE regulations, pushing advanced safety features in new vehicles. Automotive engineering centers in Bavaria, such as Munich, lead innovation in sensor fusion and intelligent camera module development.
United States
United States vehicle manufacturers prioritize camera modules for safety-critical ADAS and in-cabin monitoring. The NHTSA proposes new regulations compelling expanded camera integration for enhanced vehicle safety. Detroit, Michigan, remains a hub for automotive R&D, integrating cutting-edge camera technologies.
Japan
Japan's automotive industry emphasizes high-reliability camera modules for advanced driver assistance and parking systems. METI promotes innovation in automotive electronics, supporting domestic component suppliers. Major automotive manufacturing regions, including Aichi Prefecture, develop miniaturized, high-resolution camera solutions.
South Korea
South Korea's automotive sector integrates camera modules for sophisticated ADAS and future mobility solutions. The country's national standards align with international safety mandates, driving demand for advanced perception systems. Ulsan, a prominent automotive manufacturing city, is a key center for compact camera module integration.
Automotive Compact Camera Module Market Key Industry Players
Concentration sits with established automotive suppliers and specialized technology providers. The market structure is tiered, featuring large system integrators alongside niche component specialists. Strategic archetypes include vertically integrated module manufacturers, fabless image processor developers, and comprehensive ADAS solution providers. Dominant competitive moves involve strategic partnerships for technology co-development, portfolio diversification into new application areas, and targeted mergers for capability acquisition.
Within the comprehensive ADAS solution provider archetype, Germany-based Robert Bosch GmbH and Continental AG occupy significant positions. Robert Bosch GmbH leverages its vast manufacturing scale for system integration, while Continental AG competes on its comprehensive ADAS portfolio. Ambarella Inc., a US-based corporation, exemplifies the specialized fabless image processor developer, supplying critical System-on-Chip (SoC) technology to module makers. These entities represent distinct approaches to capturing value across the automotive camera module supply chain, from component specialization to full system integration.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Magna International Inc. |
| Denso Corporation |
| Aptiv PLC |
| Valeo SA |
| LG Innotek Co. Ltd. |
| Sony Group Corp. |
| Ambarella Inc. |
| Others |
Cost & Logistics Intelligence
ISO 26262 functional safety standards gate both supply qualification and price differentiation for automotive camera modules. These rigorous compliance requirements drive up component costs while ensuring market entry for qualified suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for automotive camera modules. Price differentiation stems from ISO 26262 certification levels and customization for specific vehicle platforms. Pricing softness reflects increasing competition among module makers, particularly for mass-market applications. OEMs demonstrate lower price sensitivity for safety-critical ADAS features, while aftermarket providers seek cost-effective basic camera solutions.
Supply Chain Analysis
Strategic stockpiling of critical components mitigates supply chain volatility in the automotive camera module market. Geographic supply concentrates in Japan, South Korea, and China for high-performance CMOS image sensors and specialized SoCs. The industry relies on these key inputs, creating a single-source vulnerability for advanced sensor technology. Distribution runs through Tier-1 suppliers who integrate modules into larger ADAS systems for Original Equipment Manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Demand for in-cabin sensing applications and emerging market adoption presents a fragmentation opportunity within the automotive compact camera module market. These distinct demand-side shifts create specialized niches for focused innovation.
For Market Incumbents: Compound existing manufacturing scale through strategic partnerships for integrated module production. Expand comprehensive ADAS portfolios to counter disruptive event-based vision sensors. Invest in advanced SoC development and robust thermal management solutions to maintain performance leadership. Capacity additions in key manufacturing regions ensure stable supply against potential bottlenecks.
For New Entrants and Emerging Players: Anchor in specialized niches by developing cost-effective ADAS camera solutions for emerging markets like India and Brazil. Target in-cabin sensing applications for driver and occupant monitoring, a penetrable segment driven by new safety protocols. Offer open and programmable hardware platforms, enabling OEMs to develop proprietary perception algorithms for differentiation. Edge AI integration provides a distinct competitive angle.
For Investors and Strategic Acquirers: UNECE framework regulations reshaping global safety standards reshapes the acquisition landscape for automotive camera module suppliers. The market offers long-term growth potential over the next decade, driven by increasing ADAS mandates. Target specialized SoC developers or module makers with robust intellectual property in HDR imaging and Edge AI. Adoption rates of Level 2+ automated driving features in mass-market vehicles are a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in HDR Imaging R&D | Improves camera performance in varied lighting, critical for surround view systems. |
| Develop Edge AI-enabled SoCs | Enables faster decision-making directly on the camera, reducing data bandwidth needs. |
| Expand into In-Cabin Sensing | Addresses new safety protocols for driver attention and occupant detection. |
| Forge OEM software partnerships | Supports proprietary perception algorithm development for brand differentiation. |
| Enhance Thermal Management Solutions | Manages heat from high-resolution sensors within compact module footprints. |
Research Approach
A standing panel of automotive OEM platform engineers, Tier-1 supplier procurement leads, and ADAS system integrators provided ongoing calibration. Primary interviews with these stakeholders, alongside image sensor R&D directors, were combined with secondary validation. This included analysis of vehicle production databases, IHS Markit registration data, SEC filings of key players, and UNECE regulatory updates. Both bottom-up and top-down triangulation ensured data consistency.
Forecast outputs were consistently validated against external benchmarks like vehicle production volumes and ADAS penetration rates. A robust analytical framework was employed across the analysis window, modeling segmentation dimensions including product type, technology, application, end user, and vehicle class. Compound Annual Growth Rates were derived from historical trends and projected market drivers. Regulatory mandates for ADAS and advancements in image sensor technology served as key forecast inputs.
Decision-makers should treat outputs as directional under current ADAS regulatory trajectories and technology adoption rates; material deviation would warrant model refresh. Forecasts reflect these base assumptions, acknowledging risks from supply chain volatility for image sensors or shifts in national industrial policies. Revision becomes warranted when these conditions cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Europe IP Camera Market
Imaging
Mobile Imaging Market
Imaging
Weatherproof Camera Market
Imaging
Global Ingaas Camera Market
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market
Imaging
North America Multi Camera Vision Inspection Systems Market
Imaging
Camera with Flip Screen Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Global Trail Camera Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Ingaas Image Sensor Market
Imaging
Light Field Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Global Thermal Imager Market
Imaging
Microwave Imaging Market