
 Instant Digital Cameras Market | 2026-2036
Instant Digital Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Digital Cameras Market Insights
Specialized optical engineering talent is unwinding supply constraints for precision lens assemblies in instant digital camera manufacturing. Fujifilm Holdings Corporation leverages its vertically integrated film chemistry heritage to sustain proprietary instant printing formulations. Polaroid Corporation anchors its competitive position through direct-to-consumer channel control and nostalgic brand equity. Canon Inc. differentiates via dual-sensor architectures that bridge instant output with post-capture digital editing workflows.
An instant digital camera combines a digital image sensor with integrated dye-sublimation or Zink thermal printing hardware to produce physical photographs within seconds of capture, typically operating at resolutions between 10 and 20 megapixels with built-in lithium-ion power systems. The device serves commercial event documentation and consumer memory preservation where immediate tangible output carries premium value. Compact and Mini product types dominate unit volume through portability-driven gifting and travel use cases, while Professional-grade variants command margin pools among studio photographers requiring manual exposure control. Zero Ink technology leads material cost efficiency by eliminating ribbon cartridges, though Digital Sensor fidelity remains the primary quality differentiator across price tiers.
Japan's METI enforces energy efficiency standards on battery-powered imaging devices, directly influencing power management chipset selection and standby consumption thresholds. The EU RoHS directive and REACH chemical restrictions constrain substrate adhesives and solder compositions in European-bound units, adding compliance layers to supply chain qualification. China's SAMR oversees mandatory CCC certification for wireless-enabled models with Bluetooth and Wi-Fi transmission modules. Stakeholders must monitor evolving right-to-repair mandates across multiple jurisdictions that could mandate spare part availability and firmware update timelines for embedded printing mechanisms.
Market Dynamics
Heritage chemical supply chains and precision optical component sourcing are constraining manufacturing scale-up as demand concentrates among event photography specialists and gifting segments.
Growth Catalysts
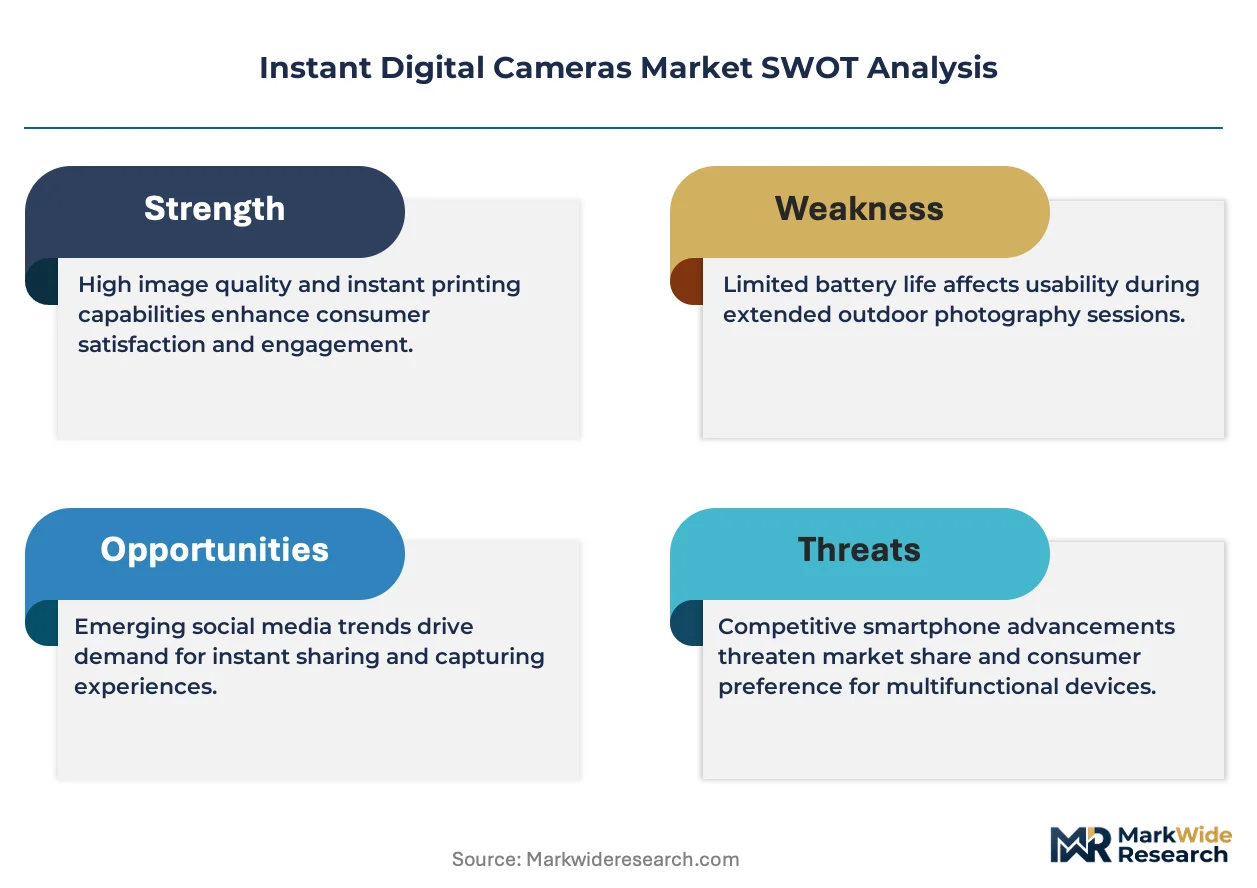
- RoHS Directive Compliance:EU REACH and RoHS restrictions on hazardous substances are accelerating substrate material innovation, forcing suppliers to qualify lead-free solder compositions and bio-based adhesives that reduce environmental liability.
- Event Photography Vertical:Wedding and corporate event planners are standardizing instant output workflows where immediate physical photo distribution replaces delayed digital-only delivery, embedding devices into service packages.
- Zink Thermal Chemistry:Zero Ink printing architectures eliminate ribbon cartridge supply chains, reducing per-print material costs and enabling compact form factors for travel and gifting applications.
Market Restraints
- Lithium-Ion Cell Volatility:Battery raw material price swings and cobalt supply concentration in the Democratic Republic of Congo create input cost unpredictability for integrated power systems.
- Optical Talent Scarcity:Specialized lens assembly engineering expertise concentrates in Japan and Germany, creating recruitment bottlenecks for precision manufacturing expansion.
- Smartphone Substitution:Mobile device camera quality improvements and portable photo printer accessories capture casual memory-preservation demand that instant cameras previously served exclusively.
Strategic Opportunities
- India Gifting Penetration:Underdeveloped retail distribution for instant cameras in tier-2 and tier-3 Indian cities creates whitespace for localized marketing and regional language interface development.
- Right-to-Repair Mandates:Emerging EU and US regulatory requirements for spare part availability and firmware update timelines favor manufacturers with modular printing mechanism designs and extended service infrastructure.
- Bluetooth-WiFi Convergence:Wireless-enabled hybrid workflows combining instant physical output with cloud backup and social sharing are attracting younger demographics previously absent from the category.
Industry Challenges
- Dye-Sublimation Calibration Expertise:Color science engineering talent shortages complicate quality control for thermal transfer consistency across temperature and humidity variations.
- CCC Certification Timelines:China's SAMR mandatory certification for wireless transmission modules extends product launch schedules by four to six months for Bluetooth-equipped models.
- Legacy Firmware Integration:Embedded printing controller architectures require extensive validation against updated smartphone operating systems, consuming software development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Digital Cameras Market |
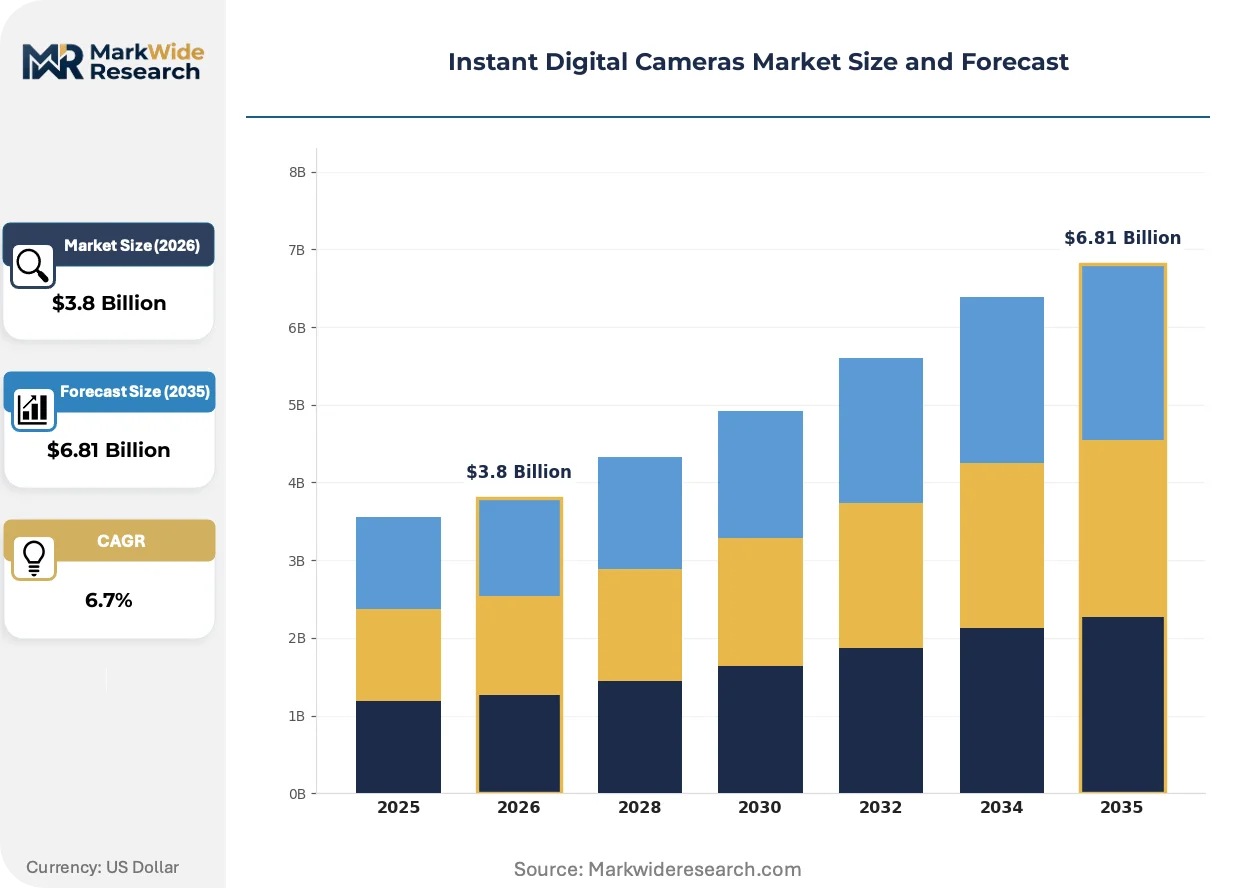
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact, Mini, Professional, Smartphone Technology: Digital Sensor, Zero Ink, Wi-Fi, Bluetooth End User: Consumers, Photographers, Retailers, Event Planners Distribution Channel: Online Retail, Electronics Stores, Photography Shops, Others |
| Companies Covered | Fujifilm Holdings Corporation, Polaroid Corporation, Canon Inc., Leica Camera AG, Lomography, MiNT Camera, Ricoh Company, Ltd., Sony Corporation, Kodak Alaris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Digital Cameras Market Trends and Innovations
Component miniaturization and regulatory chemical restrictions are compressing product development cycles while reshaping buyer expectations around connectivity and sustainability credentials.
Thermal printing hardware is miniaturizing through advances in micro-heating element arrays and flexible substrate handling, enabling sub-200-gram device weights without sacrificing print speed. Travel photography enthusiasts and festival-goers are adopting these ultra-portable units at accelerating rates, displacing bulkier instant camera formats from luggage and daypack use cases. This compression of physical footprint is enabling wearable and accessory-integrated instant photography concepts previously impractical.
EU RoHS substance restrictions and REACH chemical authorization requirements are eliminating legacy substrate adhesives containing restricted phthalates and heavy metal stabilizers from European-bound production lines. Manufacturers are reformulating circuit board laminates and housing polymers to maintain flame-retardant performance under revised compositional constraints. Professional-grade product tiers face the steepest compliance costs due to higher thermal load specifications and extended warranty obligations.
Wedding planners and corporate event coordinators are unbundling instant camera hardware from full-service photography packages, shifting toward equipment rental and per-event procurement models. This disintermediation of traditional retail purchase channels concentrates demand among specialized AV rental houses and direct B2B vendor relationships. Japan's heritage brand loyalty sustains premium pricing in this segment, while price-sensitive event markets in Southeast Asia favor short-term rental arrangements over capital expenditure.
Instant Digital Cameras Market Segmentation
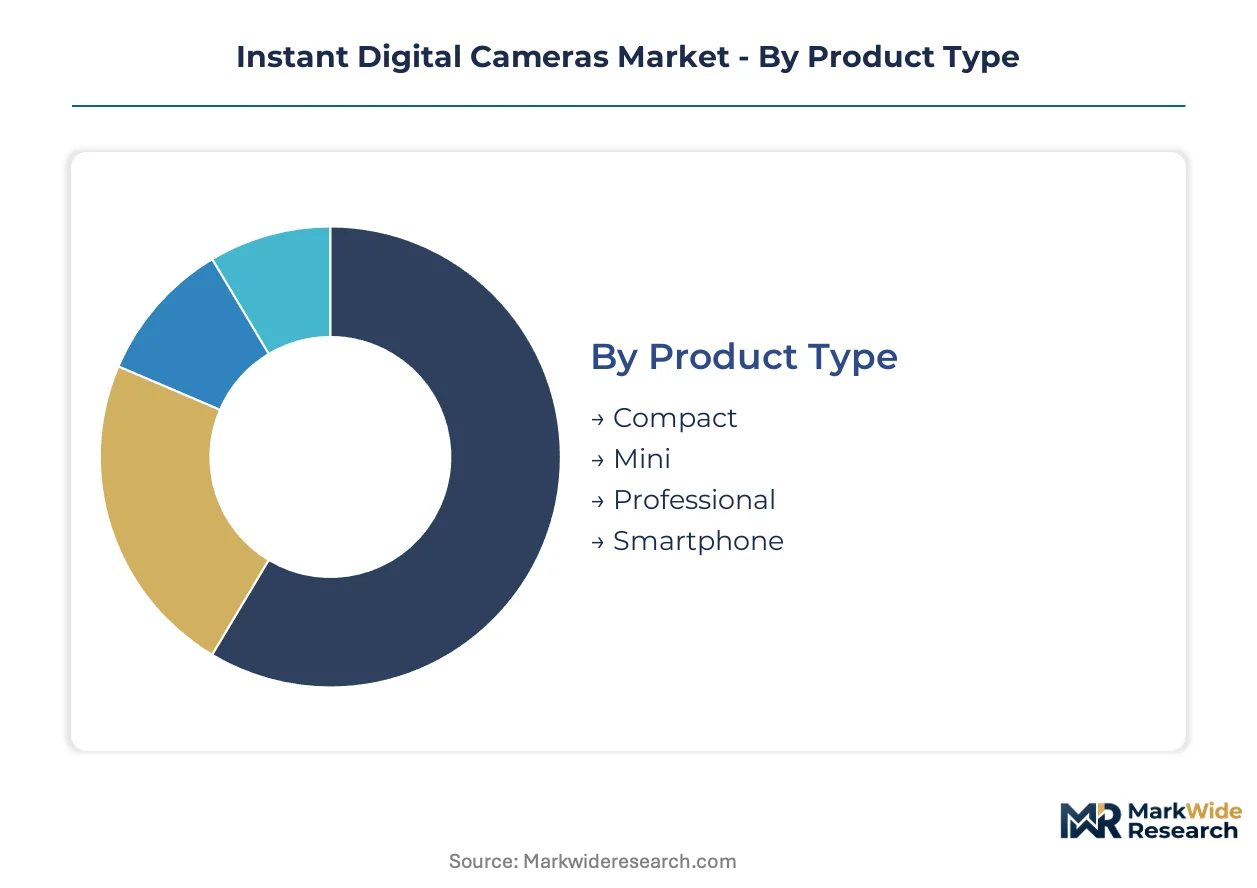
Segmentation in instant digital cameras reveals divergent vulnerability to smartphone substitution, with pocketable formats facing acute pressure while professional tiers defend margin through irreplaceable physical output workflows. Understanding these fault lines guides portfolio allocation and channel investment decisions.
Product Type:
Smartphone substitution pressure concentrates most intensely on pocketable formats where convenience overlaps directly with mobile photography, while professional segments leverage instant tangible output as a defensive moat.
- Compact:Mid-size form factors balance print quality with portability, typically housing 10-16 megapixel sensors and integrated dye-sublimation engines. Demand concentrates among travel photography enthusiasts in Japan and gifting purchasers in urban India where immediate physical memento creation carries cultural weight. These units face persistent margin compression from Zink-based Mini alternatives.
- Mini:Sub-200-gram devices leverage Zero Ink thermal arrays to eliminate ribbon cartridges, enabling festival-goers and Gen Z travelers to prioritize luggage efficiency over maximum print fidelity. Japan's heritage retail networks sustain premium positioning, while Southeast Asian markets favor aggressive promotional pricing for entry-level gifting.
- Professional:Manual exposure control, dual-sensor architectures, and calibrated color science serve studio photographers and wedding specialists requiring post-capture editing flexibility alongside instant output.
- Smartphone:Hybrid attachments and dedicated companion devices attempt to bridge mobile capture with physical printing, though native smartphone printer accessories erode this segment's addressable market.
Mini anchors the volume base through gifting penetration and travel portability, while Professional gains share at the steepest rate as event photography workflows standardize instant physical distribution.
Technology:
Cost tier stratification separates premium sensor investments from material-efficient thermal architectures, with connectivity modules commanding disproportionate certification burden.
- Zero Ink:Thermal chemistry eliminates ribbon supply chains, reducing per-print costs and enabling waterproof, tear-resistant output favored by outdoor enthusiasts and children's photography applications.
- Digital Sensor:CMOS architectures ranging 10-20 megapixels determine image quality hierarchy, with larger sensor formats concentrated in Professional tiers where low-light performance justifies price premiums.
- Wi-Fi:Wireless transmission mandates China's SAMR CCC certification, extending launch timelines four to six months for models targeting Chinese e-commerce channels.
- Bluetooth:Lower-power connectivity enables smartphone pairing for hybrid workflows, attracting younger demographics previously absent from instant camera ownership.
Digital Sensor commands margin concentration in premium tiers, while Zero Ink expands most quickly through cost-sensitive gifting and travel applications.
End User:
Customer type segmentation tracks the unbundling of hardware ownership toward rental and service-integrated procurement models.
- Event Planners:Wedding and corporate coordinators are shifting from retail purchase to per-event equipment rental, concentrating demand among specialized AV rental houses in Japan and direct B2B vendor relationships in Southeast Asia.
- Consumers:Memory preservation demand fragments across casual gifting, travel documentation, and parent-child photography where immediate tangible output carries emotional premium over delayed digital delivery.
- Photographers:Studio professionals and independent event specialists require manual control, calibrated color output, and extended warranty coverage unavailable in mass-market tiers.
- Retailers:Electronics chains and specialty camera shops face inventory risk from seasonal demand spikes, driving consignment arrangements and manufacturer-managed replenishment programs.
Consumers sustain absolute volume leadership, though Event Planners exhibit the steepest procurement growth as instant output becomes standard in service packages.
Distribution Channel:
Channel structure reflects geographic variation in retail infrastructure maturity and regulatory compliance burden for wireless-enabled models.
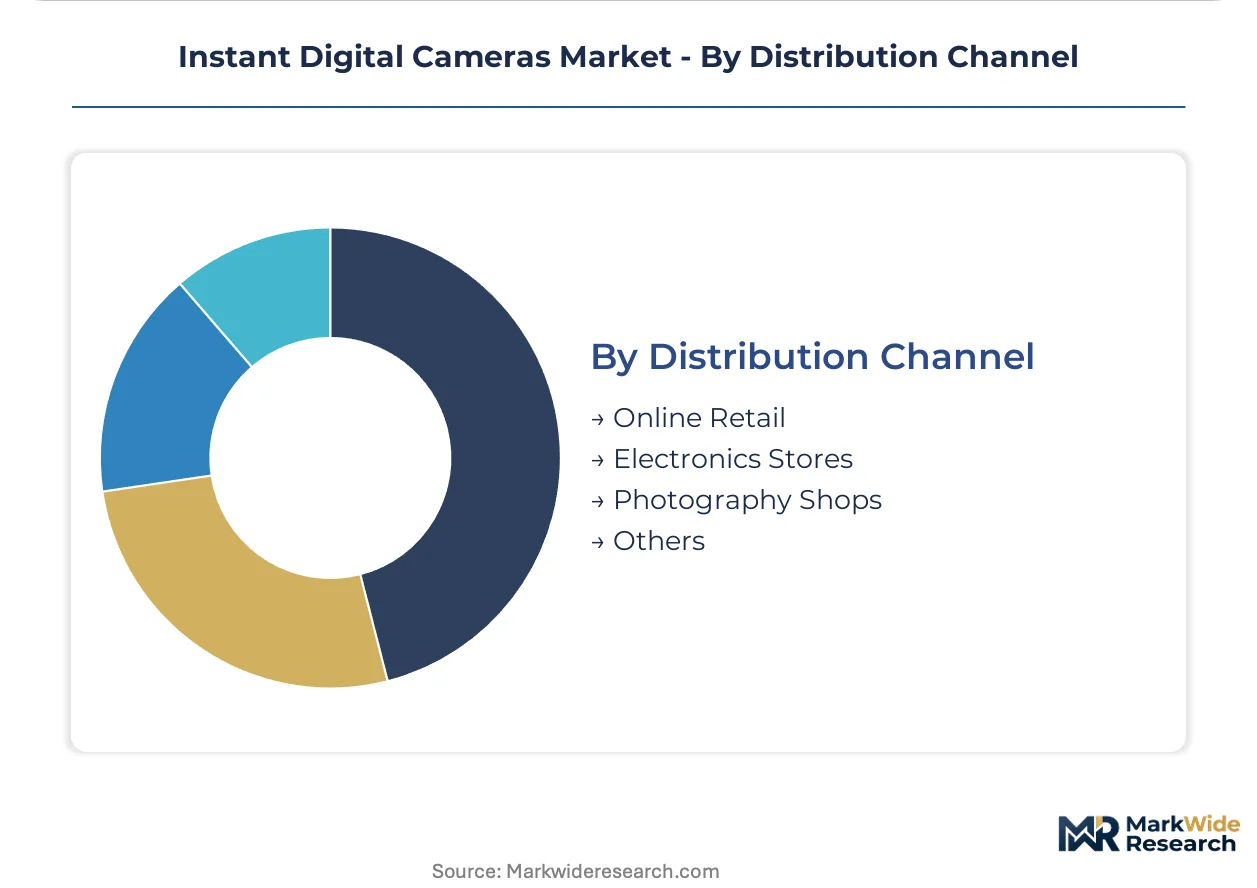
- Online Retail:E-commerce platforms capture price-sensitive demand in India and Southeast Asia, though wireless certification requirements for Bluetooth and Wi-Fi models create fulfillment complexity for cross-border shipments into China.
- Electronics Stores:Mass-market retailers in Japan sustain heritage brand loyalty through tactile product demonstration and instant film bundling promotions.
- Photography Shops:Specialty dealers concentrate Professional-tier sales through technical consultation and after-sales calibration services.
- Others:AV rental houses, direct B2B contracts, and event service integrators capture disintermediated demand from institutional Event Planner procurement.
Electronics Stores anchor established market penetration in developed Asia, while Online Retail climbs fastest through underpenetrated Indian tier-2 and tier-3 cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese consumers deploy instant digital cameras for ritualized memory preservation at family gatherings and seasonal festivals, while Indian buyers prioritize compact gifting formats for wedding return presents and corporate diwali hampers.
Japan
Heritage retail networks in Tokyo and Osaka sustain premium positioning for instant cameras through tactile demonstration counters and instant film bundling. METI enforces energy efficiency standards on battery-powered imaging devices, influencing power management chipset selection. Precision optical engineering clusters in Nagoya and Yokohama concentrate lens assembly expertise for professional-tier manufacturing.
United States
Event photography specialists in Los Angeles and New York standardize instant output workflows for wedding and corporate activations. FCC certification requirements for Bluetooth and Wi-Fi transmission modules create pre-market testing obligations. Direct-to-consumer channel control concentrates in West Coast e-commerce fulfillment centers serving nostalgic millennial demographics.
Germany
Professional studio photographers in Munich and Berlin require manual exposure control and calibrated color science for commercial portrait work. EU RoHS and REACH restrictions constrain substrate adhesives and solder compositions in European-bound production. Precision manufacturing heritage in Baden-Württemberg supports dye-sublimation calibration engineering talent pools.
India
Tier-2 and tier-3 cities including Jaipur, Lucknow, and Kochi present whitespace for localized marketing and regional language interface development. BIS certification mandates create compliance layers for electronics imports. Electronics retail chains in Delhi-NCR and Mumbai experiment with consignment arrangements to manage seasonal gifting demand spikes.
China
Shenzhen and Dongguan manufacturing clusters produce thermal printing hardware and micro-heating element arrays for global supply chains. SAMR oversees mandatory CCC certification for wireless-enabled models, extending launch timelines for Bluetooth-equipped variants. Domestic e-commerce platforms capture price-sensitive demand while cross-border fulfillment faces wireless certification complexity.
Instant Digital Cameras Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with heritage chemical and optical conglomerates commanding premium positioning against agile miniaturization specialists. The structure rewards backward integration into film chemistry and captive lens production while penalizing pure hardware assemblers dependent on commodity sensor sourcing. Two strategic archetypes dominate: vertically integrated imaging conglomerates with century-old chemical expertise, and modular hardware specialists leveraging Zink thermal licensing. Competitive moves concentrate on direct-to-consumer channel control and regulatory pre-certification for wireless transmission modules.
Within the heritage conglomerate tier, Fujifilm Holdings Corporation and Canon Inc. exemplify positions built on proprietary instant printing formulations and dual-sensor architectures respectively. Polaroid Corporation anchors the nostalgic brand equity archetype through direct channel strategies. These three entities collectively represent the spectrum from chemical-vertical integration through optical-engineering differentiation to brand-licensing monetization, illustrating how competitive advantage sources fragment across supply chain control points rather than concentrating in single capabilities.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Polaroid Corporation |
| Canon Inc. |
| Leica Camera AG |
| Lomography |
| MiNT Camera |
| Ricoh Company, Ltd. |
| Sony Corporation |
| Kodak Alaris |
| Others |
Pricing and Supply Chain Analysis
EU REACH chemical authorization gates both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb reformulation costs for bio-based adhesives and lead-free solder compositions that separate European-bound Professional tiers from standard Mini and Compact variants destined for less regulated markets. This regulatory moat allows heritage brands with captive chemical expertise to command premium positioning while commodity assemblers face margin compression from compliance burden.
Pricing Analysis
Long-term offtake contracts dominate procurement between heritage manufacturers and event photography rental houses, insulating Professional-tier pricing from spot-market volatility in lithium-ion cell inputs. Three-tier pricing structure across premium, standard, and economy levels separates manual-exposure Professional units with calibrated color science from automated Compact variants and entry-level Mini gifting formats. Cost compression in Mini tiers intensifies because Zink thermal licensing fees and Zero Ink substrate sourcing erode already thin margins. Event planners exhibit lowest price sensitivity due to service-bundled procurement, while Gen Z travel purchasers drive aggressive promotional pricing in Southeast Asian online channels.
Supply Chain Analysis
Japan and Germany anchor precision optical component fabrication, with Nagoya and Yokohama clusters concentrating lens assembly expertise and Baden-Württemberg housing dye-sublimation calibration engineering talent. Manufacturing draws from cobalt-intensive lithium-ion cells sourced through Democratic Republic of Congo supply chains, CMOS sensor wafers from Taiwan foundries, and thermal printing hardware from Shenzhen and Dongguan. Single-source vulnerability concentrates in specialized color science engineering pools, where recruitment bottlenecks constrain quality control scaling. Distribution runs through heritage retail networks in developed Asia, direct-to-consumer e-commerce fulfillment centers in North America, and emerging AV rental house channels for event photography verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The instant digital camera market rewards proprietary chemical formulation mastery and precision optical engineering capabilities that resist rapid replication, creating defensive moats for incumbents with backward-integrated supply chains while challenging pure hardware assemblers dependent on commodity sourcing.
For Market Incumbents: Compound defensive positioning through captive lens production in Nagoya and Yokohama clusters while accelerating CCC pre-certification for Bluetooth-equipped models targeting Chinese e-commerce channels. Smartphone printer accessories and native mobile photography workflows represent the most acute substitution threat; counter this by embedding instant output into irreplaceable event photography service packages through direct B2B vendor relationships. For New Entrants and Emerging Players: Lead with localized regional language interfaces and consignment-based retail arrangements in India's tier-2 and tier-3 cities, where gifting penetration remains underdeveloped and heritage brand loyalty has not yet cemented. The most penetrable whitespace sits in festival-goer and Gen Z travel segments prioritizing luggage efficiency over maximum print fidelity; attack this through ultra-portable sub-200-gram Zink-based designs distributed via aggressive online promotional pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed modular hardware specialists licensing Zink thermal technology without captive chemical or optical capabilities. Long-term viability hinges on regulatory pre-positioning for right-to-repair mandates and wireless certification timelines that favor manufacturers with extended service infrastructure. Watch for inflection signals in India's BIS certification enforcement patterns and EU spare part availability mandate implementation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Chemistry | Captive instant printing formulation supply secures margin defense against commodity assemblers dependent on licensed thermal technology. |
| CCC Pre-Certification Investment | SAMR wireless transmission approval eliminates four-to-six-month launch delays for Bluetooth-equipped models targeting Chinese e-commerce. |
| Direct B2B Channel Development | Per-event equipment rental relationships with wedding planners disintermediate retail inventory risk and embed hardware into service packages. |
| Right-to-Repair Modular Design | Spare part availability and firmware update infrastructure align with emerging EU and US regulatory mandates for embedded printing mechanisms. |
| Regional Language Interface Localization | Tier-2 and tier-3 Indian city penetration requires Hindi, Tamil, and Marathi UI adaptations beyond English-default heritage brand offerings. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with product managers at heritage imaging conglomerates, supply chain directors at thermal printing hardware manufacturers, wedding photography rental house operators, and METI regulatory compliance officers; and secondary validation against customs trade records for instant camera imports, SEC 10-K filings of listed imaging conglomerates, and CCC certification databases maintained by SAMR. Bottom-up unit shipment estimates by product tier and technology type were triangulated against top-down market value reconstructions from retail audit data and distributor channel checks.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation dimensions spanning product type, printing technology, connectivity module, and end-user archetype, with regional regulatory cluster overlays for EU RoHS, China CCC, and India BIS compliance tiers. CAGRs were derived from regression analysis of historical adoption curves in comparable imaging hardware categories, adjusted for smartphone substitution pressure indices and event photography vertical penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained lithium-ion cell price stability, cobalt supply chain continuity, and heritage brand retail network maintenance would require recalibration. Forecasts reflect documented assumptions around Zink thermal chemistry adoption velocity and right-to-repair mandate implementation scope. Recalibration cycles align with material shifts in EU chemical authorization timelines, India BIS enforcement patterns, and wireless certification requirement expansions across target markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Japan Digital X-Ray Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
IR Camera Market
Imaging
Global Microbolometer Market
Imaging
Machine Vision System Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Global Ingaas Camera Market
Imaging
Low-Light Imaging Market
Imaging
Asia Pacific IP Camera Market
Imaging
Cinematographic Camera Market
Imaging
Global in Ceiling Camera Market
Imaging
Instaprint Camera Market
Imaging
Microscopic Camera Market
Imaging
Wide Field Imaging Devices Market
Imaging
Global Document Scanner Market