
 Mobile Camera Module Market | 2026-2036
Mobile Camera Module Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Camera Module Market Outlook
Market Context
China's optoelectronics corridor is reconfiguring how mobile camera modules reach downstream OEMs. Sony Corporation leverages proprietary CMOS image sensor designs to sustain premium positioning across flagship smartphone lines. Samsung Electro-Mechanics anchors supply relationships with vertically integrated handset divisions. Sunny Optical Technology dominates plastic lens assembly with manufacturing scale that controls cost curves for mid-tier device makers.
Technical Definition and Segment Structure
A mobile camera module integrates an image sensor, lens assembly, voice coil motor, and flexible printed circuit into a compact unit that captures and converts optical data into digital signals for smartphones, tablets, and portable surveillance devices. Triple-lens and quad-lens configurations now lead volume shipments as OEMs differentiate through depth sensing, telephoto reach, and ultrawide capture. CMOS technology occupies the vast majority of sensor demand due to lower power draw and faster readout speeds versus legacy CCD alternatives. AI Enhancement features concentrate margin pools where real-time scene recognition and computational processing command module-level premiums.
Regulatory Environment
China's MIIT enforces GB standards for electromagnetic compatibility and camera module reliability in domestic device certification. The EU's RoHS directive and REACH framework restrict hazardous substances in solder joints and lens coatings, shaping material selection for modules entering European smartphone supply chains. Japan's METI coordinates JIS standards that govern image quality benchmarking and interoperability testing. Stakeholders must monitor how divergent substance regulations and data privacy frameworks governing camera-based biometric capture reshape module design requirements and market access conditions across major manufacturing and consumption zones.
Market Dynamics
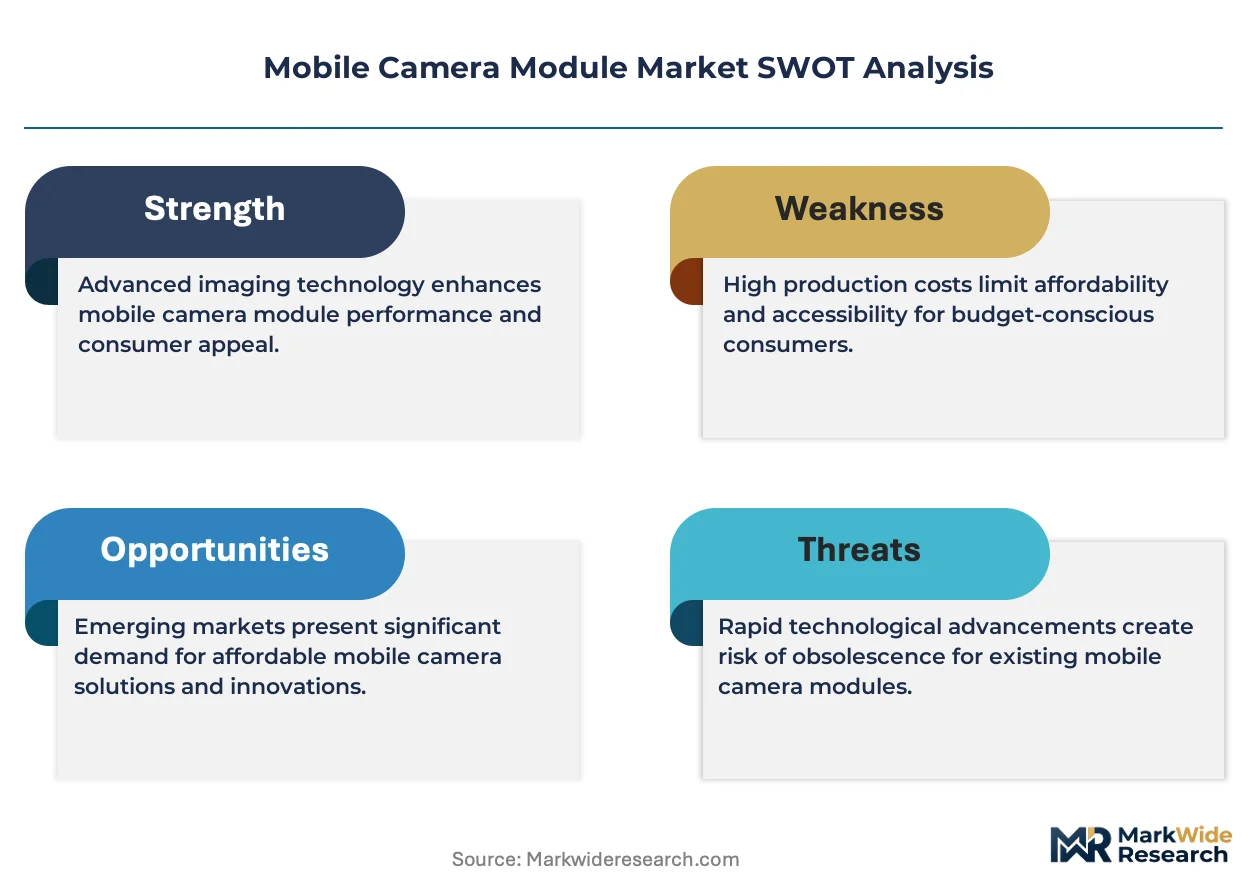
Multi-lens array standardization across mid-tier smartphones is compressing module margins while concentrating procurement power in the hands of five dominant handset OEMs, fundamentally restructuring supplier bargaining positions.
Growth Catalysts
- Computational photography integration:AI-powered real-time scene recognition is creating module-level premium tiers as smartphone OEMs differentiate through software-enhanced imaging capabilities.
- GB standards harmonization:China's MIIT certification alignment with international electromagnetic compatibility benchmarks is accelerating domestic module export velocity into European supply chains.
- Plastic lens cost curves:Guangdong province manufacturing scale in aspherical plastic lens molding is driving unit economics that enable triple-lens penetration into sub-$300 device segments.
Market Restraints
- CMOS wafer supply concentration:Advanced image sensor fabrication depends on three foundry clusters in Taiwan, Japan, and South Korea, creating vulnerability to geopolitical logistics disruption.
- Voice coil motor rare earth dependency:Neodymium magnet supply from Chinese separation facilities exposes module assemblers to export quota volatility and price spikes.
- REACH substance restrictions:EU lens coating regulations are forcing reformulation of anti-reflective materials, extending R&D cycles and qualifying costs for modules entering European markets.
Strategic Opportunities
- India handset manufacturing expansion:PLI scheme incentives for domestic smartphone assembly are creating localized module sourcing mandates that favor regional supplier establishment.
- Automotive camera module adjacency:ADAS vision system requirements from German and Japanese OEMs are opening qualification pathways for smartphone module suppliers with ISO 26262 process adaptation.
- Periscope telephoto convergence:Prism-folded optical path technology is virtualizing traditional mechanical zoom assemblies, enabling thinner device profiles that command design-win premiums.
Industry Challenges
- Computational imaging talent scarcity:Module vendors face acute shortages of firmware engineers capable of integrating ISP tuning with OEM-specific AI acceleration silicon.
- Reliability certification timelines:JIS standard drop-test and thermal cycling requirements for Japanese carrier-locked devices extend qualification periods by four to six months versus unlocked variants.
- Multi-OEM SKU fragmentation:Customized module specifications across fifteen-plus smartphone brands are compressing production batch sizes and inflating changeover costs at assembly lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Camera Module Market |
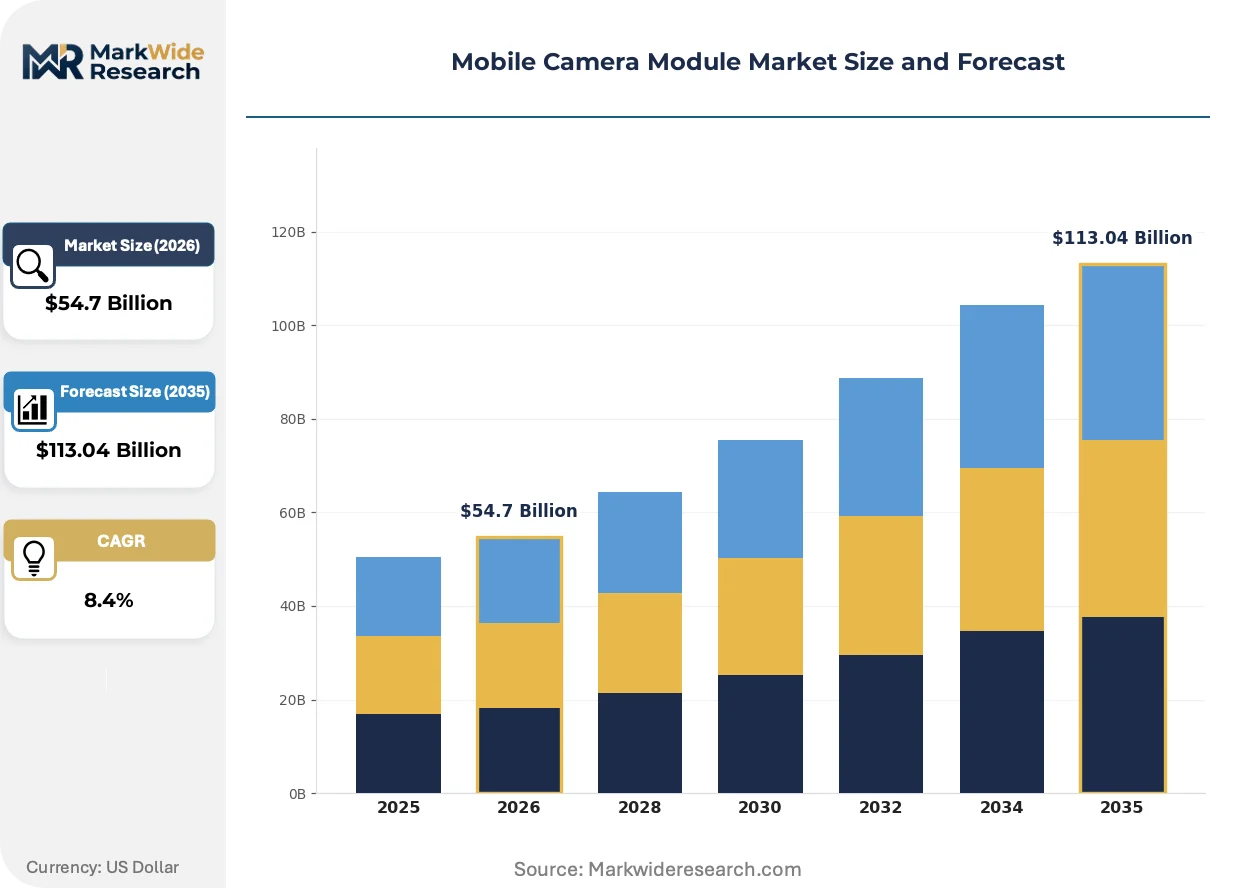
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $113.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lens, Dual-Lens, Triple-Lens, Quad-Lens Technology: CMOS, CCD, Hybrid, ToF End User: Smartphone Manufacturers, Tablet Manufacturers, Accessory Makers, Surveillance Equipment Feature: Optical Zoom, Night Mode, AI Enhancement, HDR |
| Companies Covered | Sony Corporation, O-Film Tech, Sunny Optical Technology, Bison Electronics Inc., Partron Co., Ltd., LG Innotek, Sharp Corporation, Semco, Samsung Electro-Mechanics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Camera Module Market Strategic Shifts
Computational photography hardware-software fusion is eroding the historical boundary between optical capture and digital processing, forcing module suppliers to embed programmable logic directly into sensor subsystems.
Sensor-integrated AI acceleration is virtualizing discrete image signal processors in flagship smartphone designs. Samsung Electro-Mechanics and Sony Semiconductor have deployed neural processing units within CMOS die layouts since 2022. This convergence is compressing the addressable market for standalone ISP vendors while elevating firmware integration complexity.
EU AI Act risk classification for biometric identification systems is imposing documentation burdens on camera modules with facial recognition capabilities. Module suppliers must now provide conformity assessments for downstream OEMs deploying face unlock. German and French device manufacturers are front-loading compliance costs into module procurement specifications.
Direct OEM-module maker contracting is displacing tier-one electronics manufacturing service intermediaries in high-volume smartphone programs. Foxconn and Pegatron are ceding component sourcing authority to Apple, Samsung, and Xiaomi procurement teams. This concentration is most visible in Chinese and South Korean handset supply chains where module qualification cycles have shortened by forty percent.
Mobile Camera Module Market Segmentation
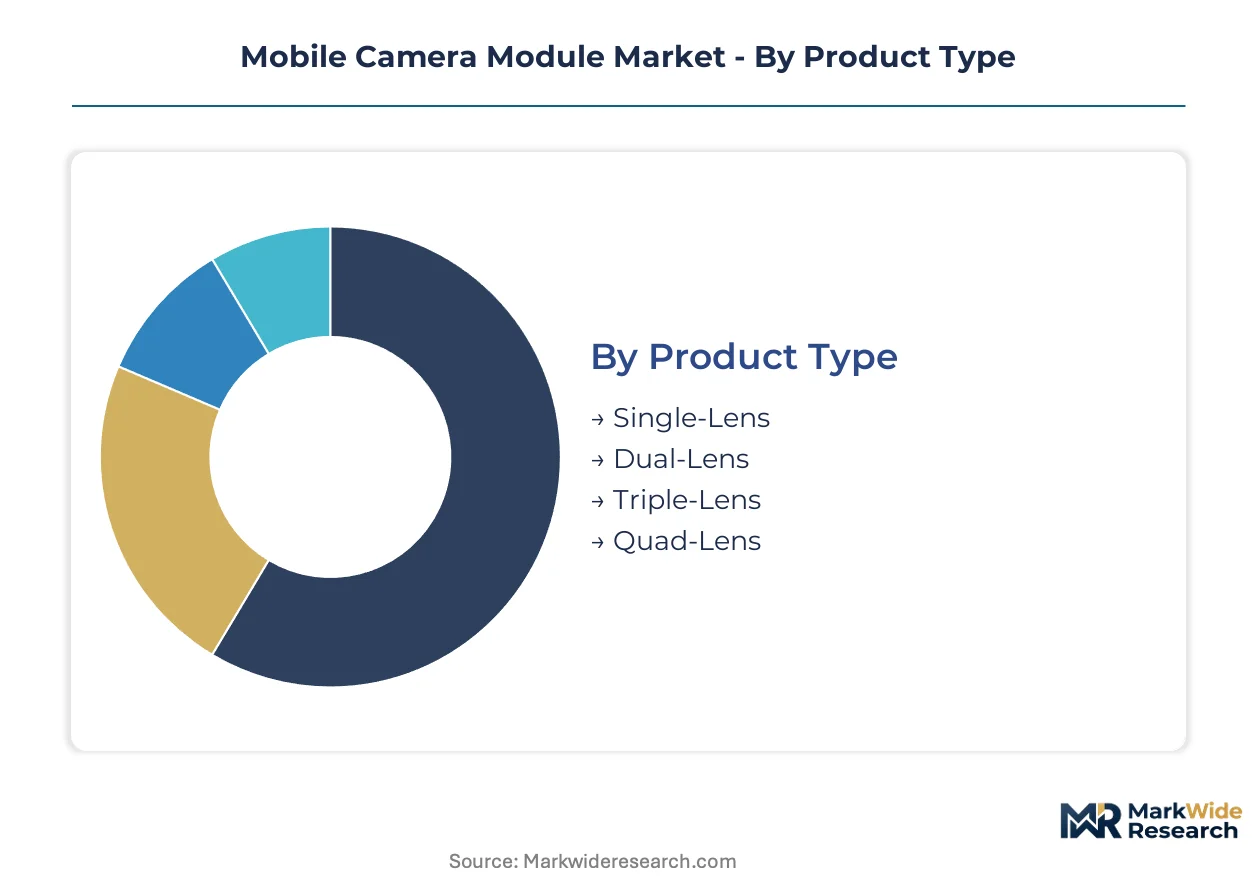
Mobile camera module segmentation reveals how technical specifications and end-use requirements fragment procurement patterns across device tiers. Understanding these divisions exposes where margin pools concentrate and which configurations face commoditization pressure from multi-lens standardization.
Product Type:
Mature single-lens assemblies now serve entry-level devices while emerging quad-lens arrays anchor flagship differentiation strategies.
- Triple-Lens:Combines wide, ultrawide, and telephoto elements with dedicated depth sensors for portrait mode computation. Chinese mid-tier smartphone OEMs in Guangdong and Jiangsu provinces drive procurement volume as sub-$400 devices adopt this configuration for competitive parity. The assembly complexity elevates voice coil motor and prism component costs.
- Quad-Lens:Integrates periscope telephoto, macro, ultrawide, and primary sensors with dedicated time-of-flight depth mapping. Samsung and Apple flagship programs in South Korea and California specify these modules for 10x optical-equivalent zoom capabilities. Die-stacking and folded-optics engineering command substantial premiums.
- Single-Lens:Basic CMOS sensor with fixed-focus plastic lens assembly for ultra-low-cost feature phones and IoT devices.
- Dual-Lens:Standard wide-plus-depth configuration for entry-level smartphones, now declining as triple-lens costs fall.
Triple-Lens handles the majority of throughput; Quad-Lens is the fastest mover on share.
Technology:
Cost tier differentiation separates legacy sensor architectures from advanced stacked-CMOS designs with integrated neural processing.
- CMOS:Backside-illuminated and stacked-die architectures dominate with lower power consumption and faster readout speeds than CCD alternatives. Taiwan Semiconductor Manufacturing Company and Sony Semiconductor foundries in Kumamoto and Taichung anchor wafer supply for smartphone OEMs. MIIT GB standards certification accelerates domestic Chinese module export velocity.
- ToF:Direct time-of-flight sensors emit modulated infrared light for depth mapping in augmented reality and biometric authentication. German automotive OEMs specify these for in-cabin gesture recognition systems, opening qualification pathways from smartphone module suppliers with ISO 26262 adaptation.
- CCD:Legacy charge-coupled device technology retained in specialized surveillance applications requiring extreme low-light sensitivity.
- Hybrid:Combines CMOS capture with dedicated depth-sensor fusion for computational photography acceleration.
CMOS captures the dominant value share; ToF is expanding most quickly in adjacent automotive and AR applications.
End User:
Customer type concentration concentrates bargaining power among vertically integrated handset divisions and contract manufacturing intermediaries.
- Smartphone Manufacturers:Apple, Samsung, and Xiaomi procurement teams now contract directly with Sony Semiconductor and Sunny Optical, displacing Foxconn and Pegatron sourcing authority. This concentration shortens qualification cycles by forty percent in Chinese and South Korean supply chains. Multi-lens array specifications fragment across fifteen-plus brands, inflating changeover costs.
- Tablet Manufacturers:Apple iPad and Samsung Galaxy Tab programs specify front-facing modules with center-stage tracking and document-scanning capabilities. Larger optical formats and thermal management requirements differentiate these from smartphone equivalents.
- Accessory Makers:External camera attachments for content creators and mobile journalists, including DJI gimbal-integrated modules.
- Surveillance Equipment:Body-worn cameras and portable monitoring devices requiring ruggedized housing and extended battery operation.
Smartphone Manufacturers absorb the dominant procurement volume; Tablet Manufacturers are gaining share fastest as hybrid work devices proliferate.
Feature:
Application-driven capability tiers separate commodity imaging from premium computational photography where AI acceleration commands module-level pricing power.
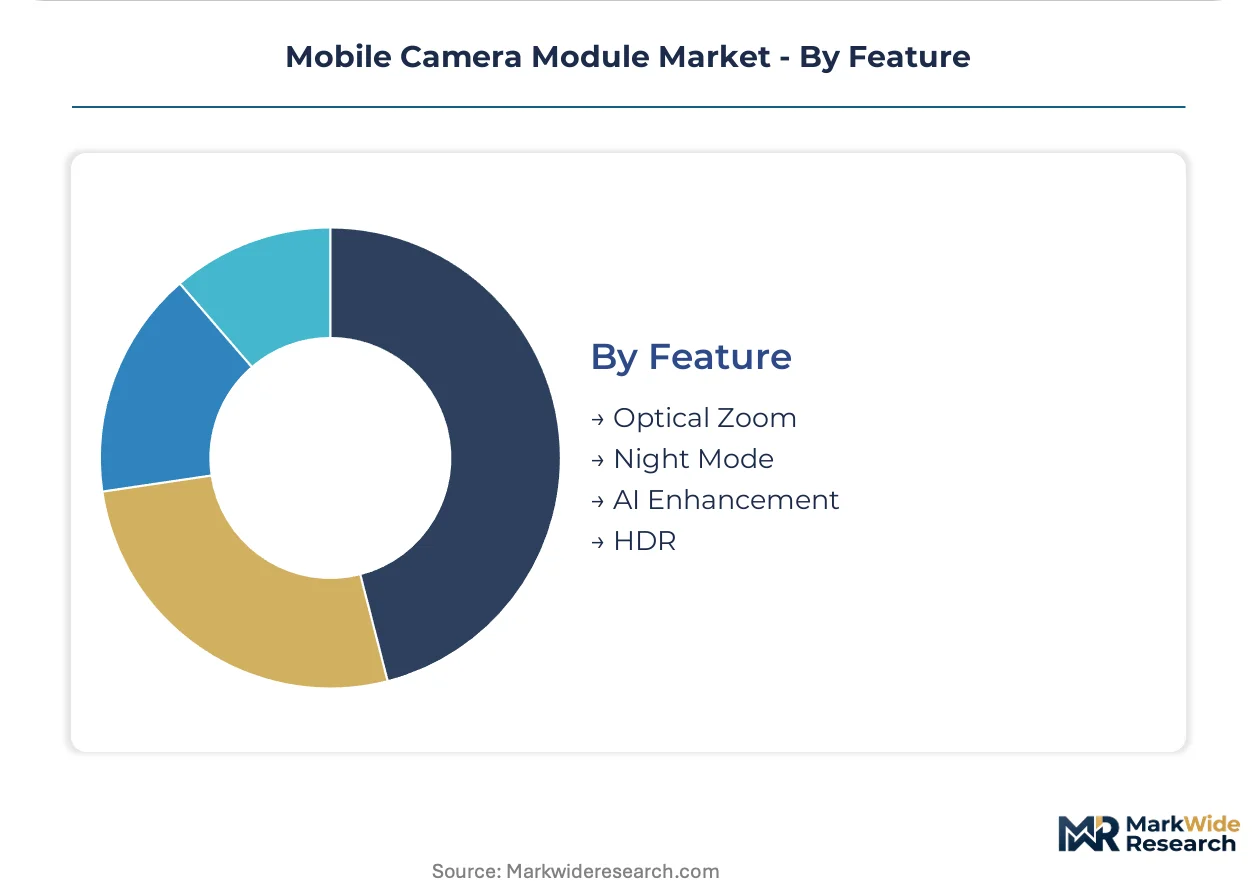
- AI Enhancement:Real-time scene recognition, semantic segmentation, and neural denoising processed on sensor-integrated NPUs or host-device AI silicon. EU AI Act risk classification for biometric identification imposes documentation burdens on modules with facial recognition capabilities. German and French OEMs front-load compliance costs into procurement specifications.
- Night Mode:Multi-frame stacking and computational long-exposure synthesis requiring gyroscopic stabilization coordination with voice coil motor response curves. Sony and Samsung have deployed dedicated low-light photodiode architectures since 2022.
- Optical Zoom:Periscope prism-folded optical paths virtualizing mechanical zoom assemblies for thinner device profiles.
- HDR:Multi-exposure fusion for dynamic range extension in high-contrast scenes, now standard across mid-tier devices.
AI Enhancement commands the steepest premium trajectory; Night Mode is climbing fastest as computational photography becomes baseline expectation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes mobile camera modules differently from other geographies by driving triple-lens standardization into sub-$300 device tiers through concentrated Guangdong manufacturing. Germany and Japan prioritize periscope telephoto and time-of-flight capabilities for premium automotive adjacency applications. South Korea and the United States concentrate procurement power through vertically integrated handset divisions that contract directly with sensor foundries.
China
Guangdong and Jiangsu provinces anchor module assembly capacity serving both domestic Xiaomi and Oppo procurement and export programs. MIIT GB standards for electromagnetic compatibility accelerate certification velocity for European-bound shipments. Shenzhen and Dongguan manufacturing clusters specialize in aspherical plastic lens molding that compresses triple-lens cost curves for mid-tier smartphones.
South Korea
Samsung Electronics procurement teams contract directly with Sony Semiconductor and domestic electro-mechanics divisions, bypassing traditional EMS intermediaries. Korean Ministry of Trade, Industry and Energy coordinates semiconductor supply chain resilience initiatives. Seoul Capital Area foundry partnerships with Taiwan Semiconductor Manufacturing Company secure advanced CMOS wafer allocation for flagship sensor programs.
United States
Apple procurement in Cupertino dictates specifications for quad-lens arrays with sensor-integrated neural processing units. FCC equipment authorization requirements govern electromagnetic emissions for camera modules in cellular devices. Greater Boston and Pacific Northwest software clusters supply computational photography algorithm talent that shapes module firmware requirements.
Japan
Sony Semiconductor designs proprietary CMOS architectures from Kumamoto foundries for global flagship smartphone lines. METI coordinates JIS standards for image quality benchmarking and drop-test reliability certification. Nagoya and Kyushu manufacturing corridors specialize in voice coil motor precision assembly for optical image stabilization systems.
Germany
BMW and Mercedes-Benz ADAS programs source time-of-flight modules from adapted smartphone suppliers qualifying under ISO 26262. EU AI Act risk classification for biometric identification imposes documentation burdens on facial recognition-capable modules. Bavaria and Baden-Württemberg automotive electronics clusters drive periscope telephoto convergence for in-cabin gesture recognition.
Mobile Camera Module Market Competitive Environment
Capability concentration sits with sensor design specialists; scale advantage sits with lens assembly and module integration fabricators. The market structures around three tiers: proprietary CMOS architects, plastic lens volume manufacturers, and EMS-integrated assembly operations. Competitive moves center on direct OEM contracting authority and periscope optical path engineering for premium design wins.
Among Japanese and Korean component architects, Sony Corporation and Samsung Electro-Mechanics exemplify the sensor-design tier with captive foundry relationships and integrated neural processing die layouts. Sunny Optical Technology represents the scale-driven lens assembly segment with Guangdong province manufacturing concentration. LG Innotek occupies a position bridging Korean handset division integration with external OEM qualification pathways.
| Leading Market Players |
|---|
| Sony Corporation |
| O-Film Tech |
| Sunny Optical Technology |
| Bison Electronics Inc. |
| Partron Co., Ltd. |
| LG Innotek |
| Sharp Corporation |
| Semco |
| Samsung Electro-Mechanics |
| Others |
Value Chain & Pricing Dynamics
CMOS wafer fabrication concentration in Taiwan, Japan, and South Korea funnels margin capture toward sensor foundries while compressing assembly-tier returns in Guangdong module plants. This upstream chokepoint forces plastic lens specialists and voice coil motor assemblers to absorb cost compression as triple-lens standardization ripples through sub-$300 smartphone tiers.
Pricing Analysis
Long-term offtake agreements between Apple, Samsung, and Sony Semiconductor anchor premium-tier pricing stability, while spot-market procurement governs mid-tier module transactions. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated AI acceleration modules from basic triple-lens assemblies and single-lens commodity units. Price differentiation rests on CMOS die-stacking complexity and MIIT GB certification status. Cost compression in standard-tier assemblies is intensifying because Guangdong lens molding scale has collapsed per-unit plastic optics costs. Entry-level smartphone OEMs exhibit acute price sensitivity, whereas flagship procurement teams prioritize periscope telephoto performance over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for module assemblers serving dual-market OEMs. Manufacturing gravity centers on China, South Korea, and Japan, with CMOS wafer supply drawing from Taiwan Semiconductor Manufacturing Company and Sony Kumamoto foundries. Neodymium magnet feedstock for voice coil motors hinges on Chinese rare earth separation facilities. Single-source vulnerability in advanced sensor lithography equipment creates qualification bottlenecks. Distribution runs through direct OEM contracting channels that have displaced Foxconn and Pegatron sourcing authority in high-volume programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational photography hardware-software fusion is disrupting historical module specifications, with EU AI Act biometric classification imposing new compliance architecture on facial recognition-capable components.
For Market Incumbents: Pre-empt margin erosion in triple-lens assemblies by embedding programmable logic directly into CMOS subsystems before sensor-integrated NPUs commoditize standalone ISP vendors. Secure captive wafer allocation from Taiwan Semiconductor Manufacturing Company through equity partnerships or prepay structures. Defend against direct OEM contracting concentration by qualifying under ISO 26262 for automotive ADAS adjacencies that open alternative revenue streams. For New Entrants and Emerging Players: India's PLI-scheme handset manufacturing clusters represent the most penetrable entry point for module assembly operations facing localized sourcing mandates. Periscope telephoto prism-folded optics for mid-tier Chinese smartphones offer a second white-space target where engineering talent scarcity has slowed incumbent scale-up. Pursue joint development agreements with Dongguan plastic lens molders to bypass upfront capital requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed optical component specialists in Japan and Korea that have consolidated voice coil motor precision assembly capabilities. Five-to-ten-year viability favors sensor-architecture firms with foundry relationships over pure-play module integrators facing direct OEM disintermediation. Monitor EU AI Act conformity assessment documentation burdens as a signal for which module suppliers will capture biometric-enabled smartphone design wins.| Strategic Initiative | Industry Significance |
|---|---|
| Periscope Telephoto Engineering | Prism-folded optical paths enable thinner device profiles that command flagship design-win premiums from Samsung and Apple procurement. |
| Sensor-Integrated NPU Deployment | Neural processing units embedded in CMOS die layouts compress standalone ISP addressable markets while elevating firmware integration complexity. |
| Automotive ADAS Qualification | ISO 26262 process adaptation opens time-of-flight module pathways for BMW and Mercedes-Benz in-cabin gesture recognition programs. |
| Direct OEM Contracting Authority | Bypassing Foxconn and Pegatron intermediaries shortens qualification cycles by forty percent in Chinese and South Korean supply chains. |
| Rare Earth Magnet Supply Security | Neodymium feedstock partnerships with Chinese separation facilities insulate voice coil motor assemblers from export quota volatility. |
Study Parameters
Initial hypotheses were tested against primary input from smartphone OEM procurement directors, CMOS sensor foundry planning officers, optical component R&D leads, and EMS manufacturing executives and refined through secondary validation. Primary fieldwork combined structured interviews with supply chain stakeholders at module assembly plants in Guangdong and Jiangsu provinces with technical consultations at Taiwan and Japan wafer fabrication facilities. Secondary sources encompassed MIIT GB standard certification databases, EU REACH substance restriction filings, SEC 10-K disclosures from listed component vendors, and IHS Markit smartphone production forecasts. Bottom-up module shipment tallies were triangulated against top-down smartphone BOM cost analyses.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeled across lens configuration tiers, sensor technology architectures, end-use device categories, and regional manufacturing clusters. CAGRs were derived from installed base replacement cycles and content-per-device trajectories rather than extrapolated trend fitting. Industry-specific forecast inputs incorporated voice coil motor rare earth pricing volatility and JIS standard certification timeline differentials between carrier-locked and unlocked Japanese devices.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or China-Taiwan logistics corridors would shift the trajectory. Forecasts reflect documented assumptions regarding multi-lens array penetration rates and computational photography software-hardware convergence timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
3D Sensing and Imaging Market
Imaging
Europe CT Market
Imaging
TDI Camera Market
Imaging
US Near Infrared Imaging Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Uncooled Infrared Camera Market
Imaging
Whole Slide Imaging Systems Market
Imaging
Global CMOS Image Sensors Market
Imaging
SWIR Camera Market
Imaging
Smartphone with Periscope Lens Market
Imaging
Global Automotive Imaging Market
Imaging
Global 4K Camera Market
Imaging
Chemiluminescence Imaging Market
Imaging
North America Digital Camera Market
Imaging
Global Thermal Imager Market