
 North America Surface Analysis Market | 2026-2036
North America Surface Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
North America Surface Analysis Market Analytics
Silicon carbide is realigning semiconductor substrate economics across North American fabrication facilities. Thermo Fisher Scientific leverages its vertical integration in mass spectrometry to control supply chains for advanced node inspection. Bruker Corporation anchors its position through R&D intensity in atomic force microscopy platforms for materials science. Oxford Instruments plc differentiates via specialized X-ray photoelectron spectroscopy systems serving academic and industrial research labs.
Surface analysis encompasses techniques that probe the outermost atomic layers of materials to determine elemental composition, chemical states, and topographical features with resolution typically spanning angstroms to micrometers. These methods serve critical quality assurance functions in semiconductor fabrication, pharmaceutical development, and advanced materials engineering. Spectroscopy commands the largest revenue pool due to its ubiquity in industrial laboratories, while microscopy segments capture premium margins from semiconductor manufacturers requiring nanometer-scale defect characterization. Chromatography maintains steady demand from pharmaceutical companies performing surface contamination analysis for drug delivery systems.
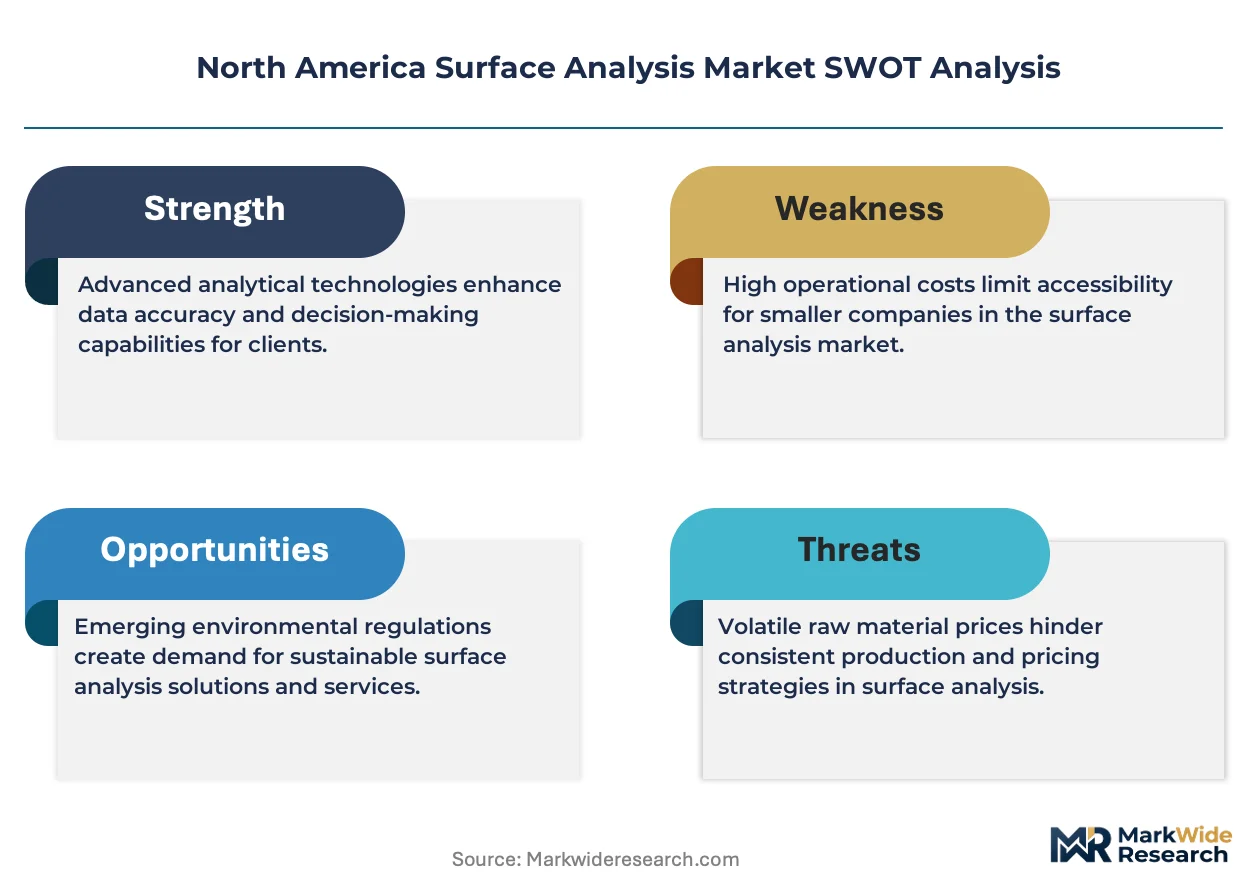
The EPA regulates chemical emissions from analytical instrument manufacturing facilities, compelling vendors to redesign solvent-based sample preparation protocols. FDA guidelines for pharmaceutical surface characterization directly shape instrument validation requirements and procurement specifications. OSHA standards governing laboratory chemical exposure influence facility investment in automated surface analysis platforms. Stakeholders must monitor evolving semiconductor node roadmaps and corresponding metrology demands to align R&D portfolios with fabrication technology transitions.
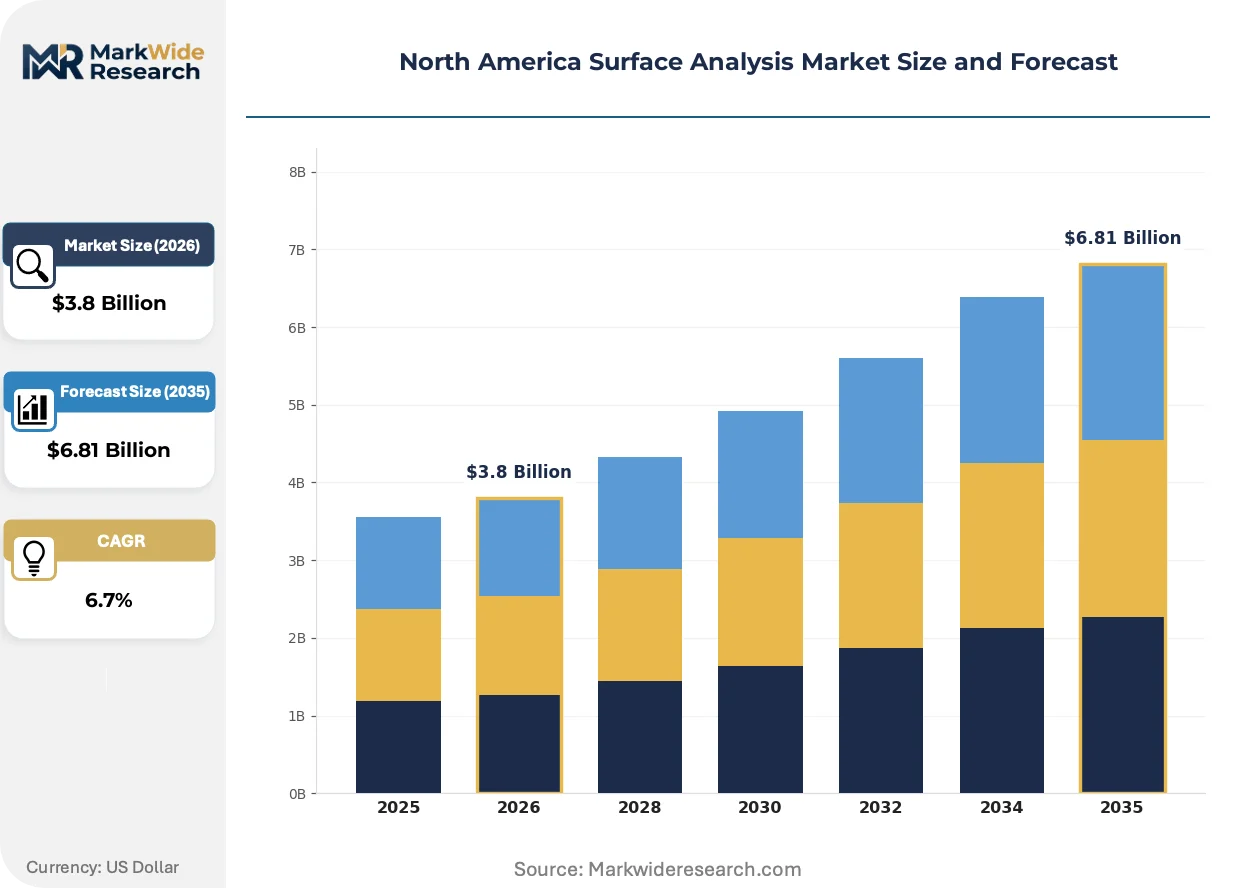
Market Dynamics
Semiconductor node shrinkage below 7nm is compressing defect tolerance thresholds and forcing foundries to upgrade surface analysis metrology at unprecedented frequency. This structural pressure cascades through equipment procurement cycles, calibration service contracts, and technician certification programs across the United States, Canada, and Mexico.
Growth Catalysts
- CHIPS Act funding:Federal subsidies for domestic semiconductor fabrication are accelerating capital expenditure timelines for metrology equipment at new Arizona and Texas foundry sites.
- Pharmaceutical surface characterization mandates:FDA guidelines for injectable drug container integrity are expanding X-ray photoelectron spectroscopy deployments in New Jersey and Massachusetts manufacturing facilities.
- Silicon carbide substrate qualification:Electric vehicle power module producers are adopting atomic force microscopy for wide-bandgap material validation at Michigan and North Carolina automotive supplier clusters.
Market Restraints
- Helium supply concentration:Mass spectrometry operations depend on helium sourced primarily from the US Federal Helium Reserve and Qatar, creating vulnerability to allocation disruptions and price volatility.
- Technical limitation at sub-angstrom resolution:Current scanning probe microscopy platforms face fundamental noise floor constraints when characterizing 2nm node defects, requiring expensive cryogenic cooling retrofits.
- EPA emissions compliance friction:Solvent-based sample preparation protocols for secondary ion mass spectrometry face tightening volatile organic compound limits, extending equipment recertification timelines.
Strategic Opportunities
- Mexico nearshoring corridor:Medical device manufacturing expansion in Baja California and Chihuahua is creating first-time demand for surface contamination analysis in orthopedic implant production.
- AI-assisted spectral interpretation:Machine learning algorithms trained on semiconductor defect libraries are converging with cloud-deployed analysis platforms to reduce skilled technician dependency.
- Canadian critical minerals strategy:Federal incentives for rare earth processing in Saskatchewan are driving procurement of X-ray fluorescence systems for ore characterization and separation verification.
Industry Challenges
- Metrology technician shortage:Vacuum technology and ultra-high purity handling expertise required for electron spectroscopy maintenance remains scarce in US Midwest manufacturing corridors.
- Multi-vendor integration complexity:Semiconductor fabs operating hybrid instrument fleets from competing suppliers face protocol translation failures during automated defect review workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Surface Analysis Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spectroscopy, Microscopy, Chromatography, Surface Plasmon Resonance End User: Research Institutes, Semiconductor Manufacturers, Pharmaceutical Companies, Academic Institutions Technology: Atomic Force Microscopy, X-Ray Photoelectron Spectroscopy, Scanning Electron Microscopy, Time-of-Flight SIMS Application: Material Characterization, Quality Control, Failure Analysis, Coating Thickness Measurement |
| Companies Covered | Thermo Fisher Scientific Inc., Bruker Corporation, Agilent Technologies, Inc., HORIBA Ltd., JEOL Ltd., Oxford Instruments plc, Malvern Panalytical, Shimadzu Corporation, Cameca, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Surface Analysis Market Evolving Landscape
Ambient pressure surface analysis techniques are displacing legacy ultra-high vacuum systems in pharmaceutical quality control workflows. This shift reflects broader instrumentation democratization as non-specialist operators assume routine testing responsibilities previously reserved for dedicated research laboratories.
Time-of-flight secondary ion mass spectrometry is converging with cluster ion beam sources to enable molecular depth profiling of organic electronic materials without beam-induced damage. Display manufacturers in California and Texas are adopting these platforms for OLED stack characterization. The technology is converging with automated sample handling to compress analysis cycles from hours to minutes for production-line deployment.
OSHA laboratory chemical exposure standards are compelling facility managers to replace manual solvent-based sample prep with enclosed automated workstations. This regulatory pressure elevates capital requirements for new installations but reduces long-term liability exposure. Pharmaceutical and contract research organizations in Massachusetts and North Carolina are front-loading these investments ahead of inspection cycle renewals.
Consolidated service contracts are displacing per-instrument maintenance agreements as procurement teams seek operational expenditure predictability. Original equipment manufacturers are responding with multi-site fleet management programs spanning California, Texas, and Arizona semiconductor clusters. This bundling trend concentrates vendor relationships and raises switching costs for facilities considering platform migrations.
North America Surface Analysis Market Segmentation
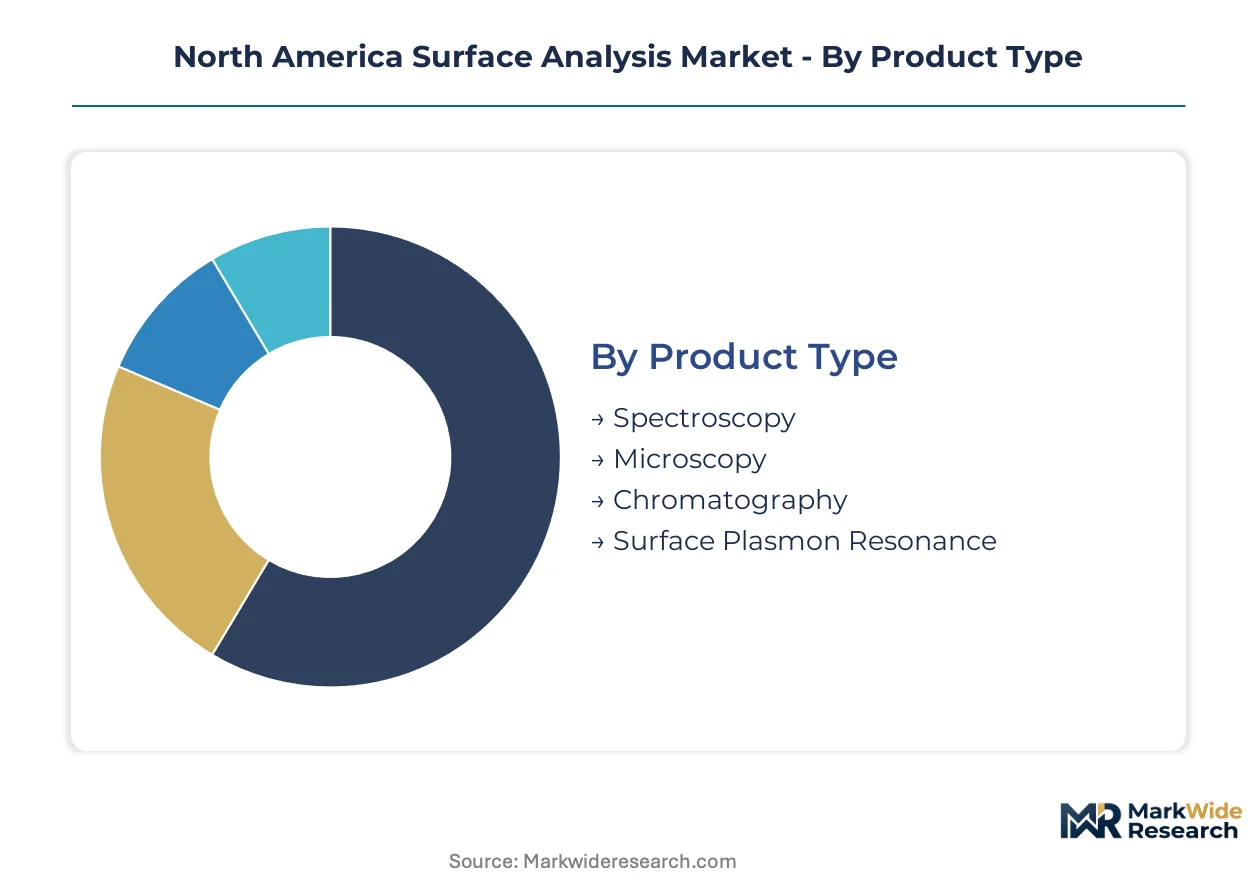
Surface analysis procurement in North America fragments across technical specifications, regulatory validation requirements, and end-use workflows. Vendors must align product portfolios with distinct certification burdens governing semiconductor fabs, pharmaceutical cleanrooms, and academic research facilities.
Product Type:
Spectroscopy platforms carry FDA 21 CFR Part 11 validation obligations for pharmaceutical GMP environments, while microscopy systems face SEMI S2 safety certifications for semiconductor cleanroom deployment. Chromatography and SPR instruments navigate dual EPA emissions compliance and OSHA chemical handling mandates.
- Spectroscopy:X-ray photoelectron and secondary ion mass spectrometry systems dominate industrial laboratories with elemental composition mapping capabilities. Demand concentrates in California's Silicon Valley cluster, where foundries require angstrom-scale chemical state detection for sub-7nm node qualification.
- Microscopy:Scanning probe and electron microscopy platforms capture premium margins through nanometer-scale topographical resolution. Semiconductor manufacturers in Arizona and Texas drive procurement for automated defect review workflows at advanced packaging facilities.
- Chromatography:Gas and liquid chromatography systems serve pharmaceutical surface contamination protocols with established USP validation pathways. Massachusetts and New Jersey manufacturing corridors sustain steady replacement cycles for injectable drug container testing.
- Surface Plasmon Resonance:Label-free biosensing platforms support biopharmaceutical binding kinetics research with specialized optical configurations. Academic medical centers in Boston and San Diego anchor installed base expansion.
Spectroscopy sits at the top of the volume ranking, with microscopy climbing the fastest on semiconductor capital expenditure acceleration.
End User:
Procurement authority varies sharply across customer types, with semiconductor fabs consolidating enterprise-wide agreements while academic institutions rely on individual PI grants. Pharmaceutical companies impose stringent vendor audit requirements that smaller research institutes bypass.
- Research Institutes:National laboratories and federally funded centers operate multi-technique core facilities serving diverse investigator portfolios. Oak Ridge and Argonne National Laboratory procurement programs emphasize cryogenic sample handling capabilities for quantum materials research.
- Semiconductor Manufacturers:Integrated device manufacturers and pure-play foundries drive the highest per-site instrument density with 24/7 operational requirements. Intel, TSMC Arizona, and Samsung Texas facilities are expanding metrology suites under CHIPS Act funding timelines.
- Pharmaceutical Companies:Big pharma and contract manufacturing organizations prioritize validated workflows for regulatory submission support. Pfizer and Moderna manufacturing networks in Massachusetts and Maryland are retrofitting facilities for automated surface contamination monitoring.
- Academic Institutions:University core facilities balance teaching mandates with competitive research output pressures. UC Berkeley, MIT, and University of Toronto maintain diverse instrument fleets through multi-year NSF and CIHR equipment grants.
Semiconductor manufacturers command the largest revenue share, with pharmaceutical companies expanding most quickly on FDA container integrity mandate enforcement.
Technology:
Technical differentiation centers on spatial resolution, chemical specificity, and sample damage thresholds. Atomic force microscopy achieves sub-nanometer topography without vacuum requirements, while electron spectroscopy demands ultra-high purity infrastructure.
- Atomic Force Microscopy:Cantilever-based probe systems map surface topography and mechanical properties under ambient conditions. Michigan and North Carolina automotive supplier clusters are adopting AFM for silicon carbide power module substrate qualification.
- X-Ray Photoelectron Spectroscopy:Soft X-ray excitation reveals elemental composition and chemical bonding states with surface sensitivity. Pharmaceutical manufacturers in New Jersey deploy XPS for drug-eluting stent coating verification under FDA premarket submission requirements.
- Scanning Electron Microscopy:Focused electron beam imaging achieves nanometer resolution for defect visualization and dimensional metrology. Arizona and Texas foundries integrate SEM platforms with automated wafer handling for high-volume production monitoring.
- Time-of-Flight SIMS:Pulsed ion beam sputtering enables molecular depth profiling with parts-per-billion detection limits. OLED display manufacturers in California are adopting TOF-SIMS for organic stack characterization in foldable device development.
Scanning electron microscopy holds the broadest installed base, with time-of-flight SIMS gaining share fastest on organic electronics manufacturing expansion.
Application:
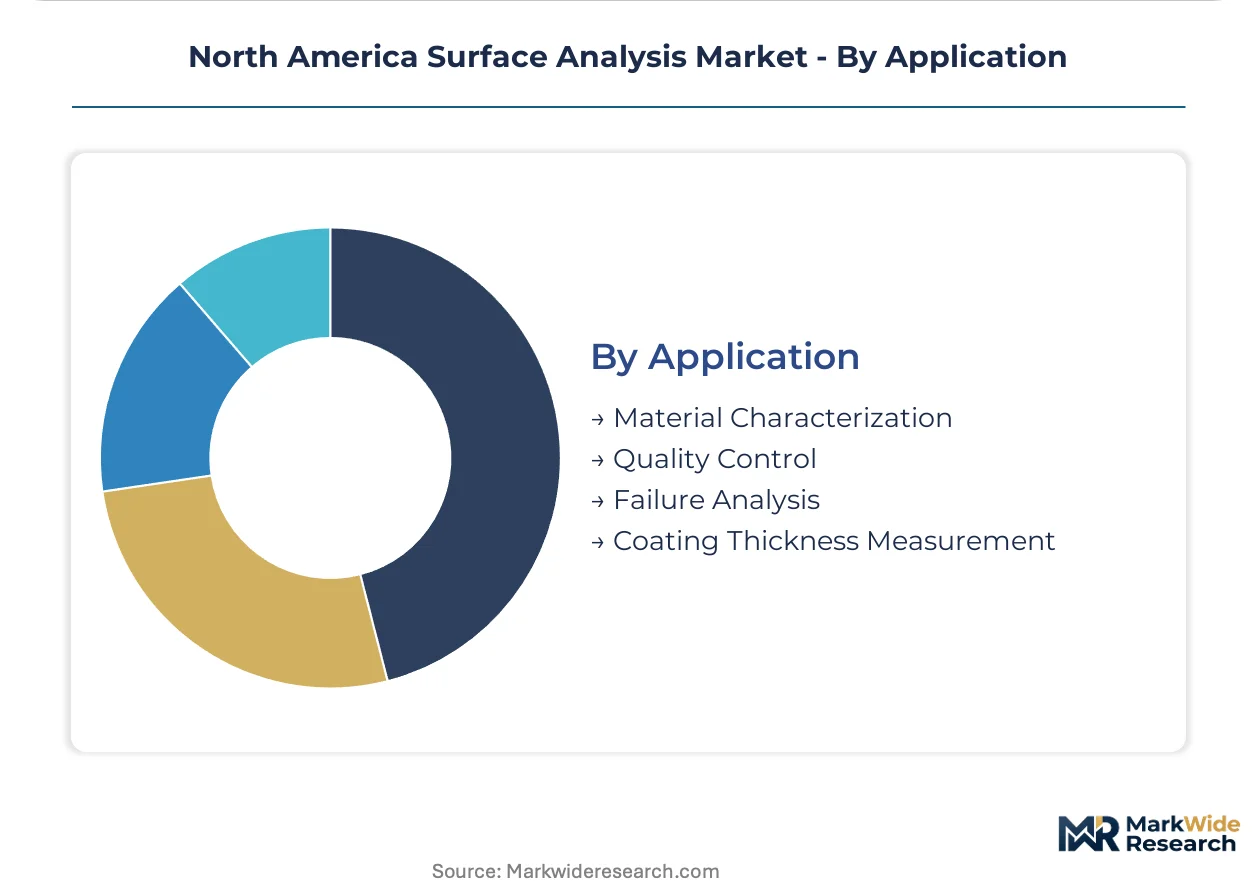
Workflow requirements dictate instrument configuration, with quality control demanding high throughput automation and failure analysis prioritizing analytical flexibility. Material characterization spans both research and production environments with divergent specification tolerances.
- Material Characterization:Comprehensive property mapping supports R&D pipelines and supplier qualification programs. Canadian critical minerals processing facilities in Saskatchewan are deploying X-ray fluorescence and electron microscopy for rare earth separation verification.
- Quality Control:Statistical process control integration requires validated measurement protocols and automated pass/fail reporting. Semiconductor fabs in Oregon and New York are upgrading QC metrology for 3nm node production ramp schedules.
- Failure Analysis:Root-cause investigation workflows demand multi-technique correlation and destructive sample preparation capabilities. Aerospace suppliers in California and Texas maintain dedicated FA laboratories for composite delamination and coating adhesion investigations.
- Coating Thickness Measurement:Non-destructive profiling supports medical device and optical component manufacturing with tight dimensional tolerances. Orthopedic implant producers in Baja California and Chihuahua are establishing first-time surface analysis capabilities for nearshored production.
Quality control represents the largest application segment by instrument count, with coating thickness measurement expanding most quickly on Mexico medical device manufacturing corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's semiconductor fabrication corridor anchors surface analysis procurement across North America, with federal CHIPS Act disbursements accelerating capital deployment timelines through 2035.
United States
Arizona and Texas foundry construction under CHIPS Act funding is compressing metrology equipment delivery schedules. EPA emissions standards for analytical instrument manufacturing are compelling solvent-based protocol redesigns at production facilities. Intel's Oregon campus and TSMC's Phoenix operations are expanding atomic force microscopy suites for sub-3nm node qualification.
Canada
Saskatchewan's rare earth processing incentives are driving X-ray fluorescence procurement for separation verification workflows. Federal critical minerals strategy allocations are elevating capital expenditure ceilings for materials characterization infrastructure. Toronto-Waterloo corridor research institutes are deploying multi-technique core facilities through NSERC equipment grants.
Mexico
Baja California and Chihuahua medical device manufacturing expansion is creating first-time demand for surface contamination analysis in orthopedic implant production. Nearshoring tax incentives are accelerating facility commissioning timelines for US-bound contract manufacturers. Tijuana and Juárez industrial parks are establishing ISO 13485-compliant metrology laboratories.
North America Surface Analysis Market Competitive Landscape
Global majors compete with regional champions across instrumentation technology and service network density. The vendor base organizes around three tiers: diversified analytical platform conglomerates, specialized microscopy and spectroscopy developers, and regional service-integrated distributors. Consolidation pressure intensifies as semiconductor fabs demand unified fleet management contracts spanning calibration, training, and predictive maintenance. Strategic partnerships between instrument manufacturers and foundry operators are displacing transactional procurement models.
Among diversified analytical platform conglomerates, Thermo Fisher Scientific Inc. and Agilent Technologies, Inc. exemplify scale-driven archetypes with mass spectrometry and chromatography portfolios. Bruker Corporation and HORIBA Ltd. occupy positions within specialized microscopy and spectroscopy tiers, serving materials science and semiconductor defect characterization workflows. Oxford Instruments plc represents the focused instrumentation developer model with X-ray photoelectron spectroscopy specialization for academic and industrial research laboratories.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bruker Corporation |
| Agilent Technologies, Inc. |
| HORIBA Ltd. |
| JEOL Ltd. |
| Oxford Instruments plc |
| Malvern Panalytical |
| Shimadzu Corporation |
| Cameca |
| Others |
Value Network & Pricing Analysis
Captive helium sourcing through the US Federal Helium Reserve anchors pricing power for mass spectrometry vendors while creating vulnerability to allocation disruptions that cascade through semiconductor metrology procurement cycles. This integration choice concentrates supply risk in a single federal asset and amplifies cost pass-through sensitivity for foundries dependent on sub-7nm defect characterization.
Pricing Analysis
Input-cost pass-through from helium spot volatility and cryogenic cooling retrofits for sub-angstrom resolution is compressing margins across spectroscopy and microscopy tiers. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical GMP systems from research-grade configurations, with certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from EPA solvent-based protocol redesign costs extending equipment recertification timelines. Semiconductor fabs demonstrate lowest price sensitivity due to node shrinkage imperatives, while academic core facilities face capital grant constraints elevating budget scrutiny.
Supply Chain Analysis
Workforce availability constraints in Michigan automotive supplier clusters and Arizona foundry corridors are extending field service engineer deployment timelines for atomic force microscopy maintenance. Manufacturing concentrates in the United States, Germany, and Japan for precision ion optics and vacuum chamber fabrication. Raw material dependencies span high-purity helium from the US Federal Reserve and Qatar, specialized ceramics for cantilever probes, and rare earth elements for X-ray source anodes. Single-source vulnerability around Federal Helium Reserve depletion risk threatens mass spectrometry operations. Distribution runs through direct OEM field service organizations and regional certified service partners for calibration-intensive metrology fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by semiconductor node shrinkage below 3nm forcing unprecedented metrology upgrade frequency and premium specification procurement.
For Market Incumbents: Anticipate helium supply disruption scenarios by securing alternative noble gas sourcing partnerships and cryogen-free platform development roadmaps. Consolidate service contract bundling across California, Texas, and Arizona semiconductor clusters to raise switching costs against emerging AI-assisted spectral interpretation competitors. Certification investment in EPA-compliant solvent-free sample preparation protocols represents the critical defensive lever. For New Entrants and Emerging Players: Capture Mexico nearshoring corridor white-space in Baja California and Chihuahua orthopedic implant surface contamination analysis, where first-time ISO 13485-compliant metrology laboratory demand outpaces established vendor service network density. Target pharmaceutical quality control workflows adopting ambient pressure techniques as the most penetrable segment. Lead with cloud-deployed AI-assisted spectral interpretation platforms to reduce skilled technician dependency as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional service-integrated distributors because semiconductor fabs are consolidating enterprise-wide fleet management contracts spanning calibration, training, and predictive maintenance. Long-term viability centers on vendor relationships with CHIPS Act-funded foundry operators. Target acquisition archetype: specialized microscopy developers with cryogenic sample handling capabilities for quantum materials research. Watch helium spot price volatility and Federal Reserve allocation policy as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Helium Supply Diversification | Secures noble gas sourcing from Qatar and Algeria to mitigate Federal Reserve depletion risk. |
| Cryogen-Free Platform Development | Eliminates liquid helium dependency for sub-angstrom scanning probe microscopy at 2nm nodes. |
| Multi-Site Fleet Management Contracts | Concentrates vendor relationships with Intel Oregon and TSMC Arizona under unified service agreements. |
| AI-Assisted Spectral Interpretation Integration | Reduces skilled technician dependency for semiconductor defect libraries through machine learning deployment. |
| Mexico Nearshoring Service Network Expansion | Establishes ISO 13485-compliant metrology presence in Tijuana and Juárez industrial parks. |
Research Methodology
Bottom-up semiconductor fab and pharmaceutical manufacturer modeling reconciled against top-down analytical instrument production tracking forms the analytical core of this study. Primary interviews with metrology equipment procurement directors, EPA compliance officers, vacuum technology maintenance technicians, and foundry process integration engineers combined with secondary validation from SEC 10-K filings, SEMI industry reports, FDA 510(k) clearance databases, and CHIPS Act funding disbursement records. Triangulation across these sources ensures demand-side and supply-side figures converge within acceptable variance bands.
Input-output matrix framing connects node shrinkage roadmaps to metrology equipment replacement cycles, with segmentation across spectroscopy, microscopy, chromatography, and surface plasmon resonance product types; semiconductor, pharmaceutical, academic, and research institute end users; and quality control, failure analysis, material characterization, and coating thickness measurement applications. CAGRs derive from equipment procurement pipeline analysis and capital expenditure commitment tracking across the projection horizon. Forecast inputs incorporate EPA emissions compliance timeline acceleration and helium spot price trajectory assumptions.
Underlying measurement precision varies by segment; semiconductor manufacturer demand carries tighter precision than academic core facility projections due to disclosed capital expenditure commitments and foundry construction timelines. Forecasts reflect documented assumptions regarding CHIPS Act disbursement schedules, node transition cadence, and regulatory enforcement intensity. Material deviation in Federal Helium Reserve depletion policy, EPA volatile organic compound limit revisions, or semiconductor node roadmap delays warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
Surface Plasmon Resonance (SPR) System Market
Analytical Instruments
Battery Testers and Analyzers Market
Analytical Instruments
Europe Mass Spectroscopy Market
Analytical Instruments
Analytical X-Ray Instrumentation Market
Analytical Instruments
Ph Meters Market
Analytical Instruments
Power Device Analyzer Market
Analytical Instruments
Cleanroom Particle Counters Market
Analytical Instruments
Gas Chromatography Systems Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Scanning Electron Microscopes (SEM) Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
Logic Analyzer Market
Analytical Instruments
Spectrum Analyzer Market