
 Cinematographic Camera Market | 2026-2036
Cinematographic Camera Market Size, Share, and Industry Trends Forecast 2026-2036
Cinematographic Camera Market Analysis
Aftermarket service revenue is rewriting profit structures across the cinematographic camera supply base. ARRI AG leverages its Munich-based service network to sustain premium positioning on large-format rentals. RED Digital Cinema anchors its profitability through direct-to-user module upgrades and proprietary media workflows. Sony Group Corporation dominates broadcast-cinema hybrid deployments with sensor fabrication scale that few competitors replicate.
A cinematographic camera is a precision imaging instrument engineered for motion-picture acquisition, typically featuring Super 35mm or larger format sensors, 10-bit or greater color depth, and logarithmic gamma encoding for post-production grading flexibility. These systems serve commercial film production, episodic television, and high-end advertising where theatrical exhibition standards govern deliverable specifications. Digital cameras now lead product-type revenue as film negative processing infrastructure contracts regionally. Mirrorless technology is displacing traditional DSLR chassis across independent filmmaker and content creator end-user segments due to reduced weight profiles and continuous autofocus integration. Compact cinematic configurations represent the fastest-growing technology tier for documentary and live-event applications where operator mobility determines shot feasibility.
The FCC governs wireless transmission modules embedded in camera systems for live monitoring and director's viewfinder applications in the United States. EMA and REACH compliance in Europe restrict hazardous substance use in sensor manufacturing and battery assemblies, raising entry costs for non-compliant suppliers. ISO 26262 functional safety standards increasingly influence robotic camera platform development for automated studio environments. Stakeholders must monitor regulatory divergence between electromagnetic emission standards and chemical substance restrictions as procurement decisions increasingly weight compliance documentation alongside imaging specifications.
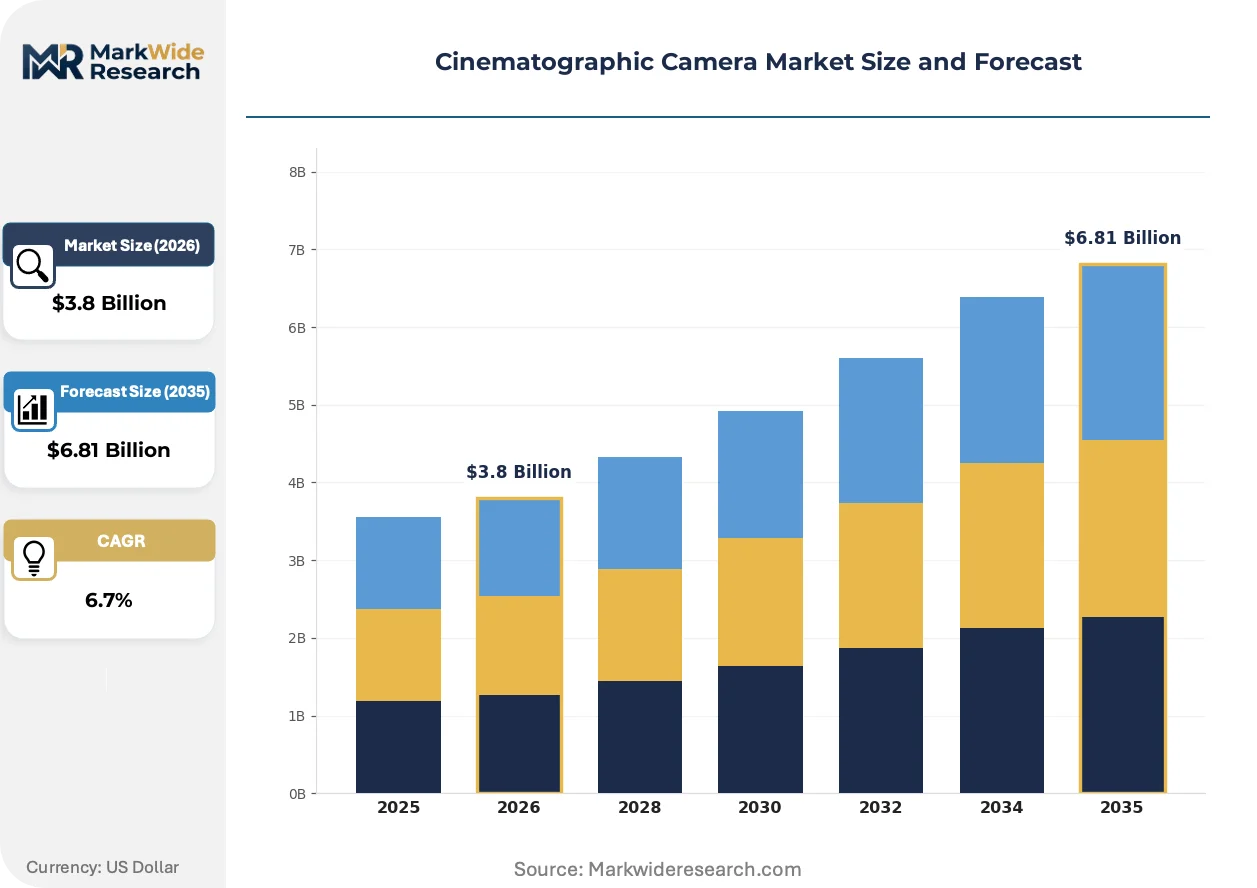
Market Dynamics
Streaming platform procurement cycles now compress hardware refresh timelines across major production hubs, forcing manufacturers to align sensor development roadmaps with content commissioning calendars rather than traditional theatrical release windows.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases accelerate R&D investment in sustainable cooling systems for high-resolution image sensors among European equipment manufacturers.
- Live-event cinematography:Concert films and sports documentaries drive demand for compact camera configurations with wireless transmission modules capable of real-time director monitoring.
- Atlanta studio cluster expansion:Georgia's production infrastructure growth creates concentrated procurement pull for rental-ready large-format camera packages with standardized accessory ecosystems.
Market Restraints
- Sensor fabrication concentration:Advanced CMOS image sensor production concentrates among a handful of East Asian foundries, exposing supply chains to geopolitical disruption and capacity allocation constraints.
- REACH compliance costs:European chemical substance restrictions elevate material certification expenses for battery assemblies and printed circuit boards, disadvantaging smaller equipment assemblers without dedicated compliance teams.
- Film processing infrastructure contraction:Regional laboratory closures for photochemical negative processing strand legacy camera owners without reliable dailies and archival workflow support.
Strategic Opportunities
- India content production surge:Domestic streaming platform commissioning expansion creates underpenetrated demand for mid-tier digital cinema cameras suited to multilingual episodic production.
- ISO 26262 robotic platforms:Automated studio camera systems for broadcast sports and virtual production stages open hardware-software integration revenue streams beyond traditional camera body sales.
- Direct-to-creator module upgrades:Bypassing rental house intermediaries, manufacturers can capture margin from independent filmmakers through firmware-unlocked feature sets and sensor block replacements.
Industry Challenges
- Gimbal stabilization engineering talent:Shortage of motion-control specialists capable of integrating compact camera payloads with drone and vehicle-mounted stabilization systems delays product development cycles.
- Multi-jurisdiction wireless certification:FCC, CE marking, and MIC approval timelines for radio-frequency transmission modules extend go-to-market schedules by six to twelve months for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cinematographic Camera Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Cameras, Film Cameras, Action Cameras, 360-Degree Cameras Technology: DSLR, Mirrorless, Cinematic, Compact End User: Film Studios, Independent Filmmakers, Content Creators, Educational Institutions Application: Feature Films, Documentaries, Commercials, Live Events |
| Companies Covered | ARRI AG, RED Digital Cinema, Blackmagic Design, Canon Inc., Sony Group Corporation, Panasonic Holdings Corporation, Nikon Corporation, Panavision, Kinefinity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cinematographic Camera Market Emerging Trajectories
Image acquisition technology is fragmenting across specialized form factors as distinct use cases demand divergent engineering trade-offs between sensor size, thermal management, and operator mobility.
Computational photography pipelines are migrating from post-production facilities into camera bodies themselves. Machine learning algorithms now execute real-time noise reduction and dynamic range expansion at the point of capture. Documentary crews shooting run-and-gun scenarios adopt these embedded processing capabilities fastest. The technology is migrating from luxury cinema packages into sub-$10,000 mirrorless chassis, compressing the price-performance gap between professional and prosumer tiers.
REACH substance restrictions and EU F-Gas Regulation phase-down schedules force material substitutions across European-manufactured equipment. Sensor packaging now excludes specified phthalates and heavy metals, while thermal management systems transition toward hydrocarbon refrigerants. German and Italian camera assemblers absorb the steepest compliance costs, passing through price adjustments to rental houses with long-term fleet refresh obligations.
Production companies now unbundle after-sales service contracts from equipment purchase agreements, treating maintenance as a separately negotiable spend category. Streaming platform technical operations teams drive this behavior, centralizing fleet management across multiple production subsidiaries. Los Angeles and London post-production facilities exhibit the most aggressive service unbundling, pressuring manufacturers to publish transparent parts pricing and remote diagnostic protocols.
Cinematographic Camera Market Segmentation
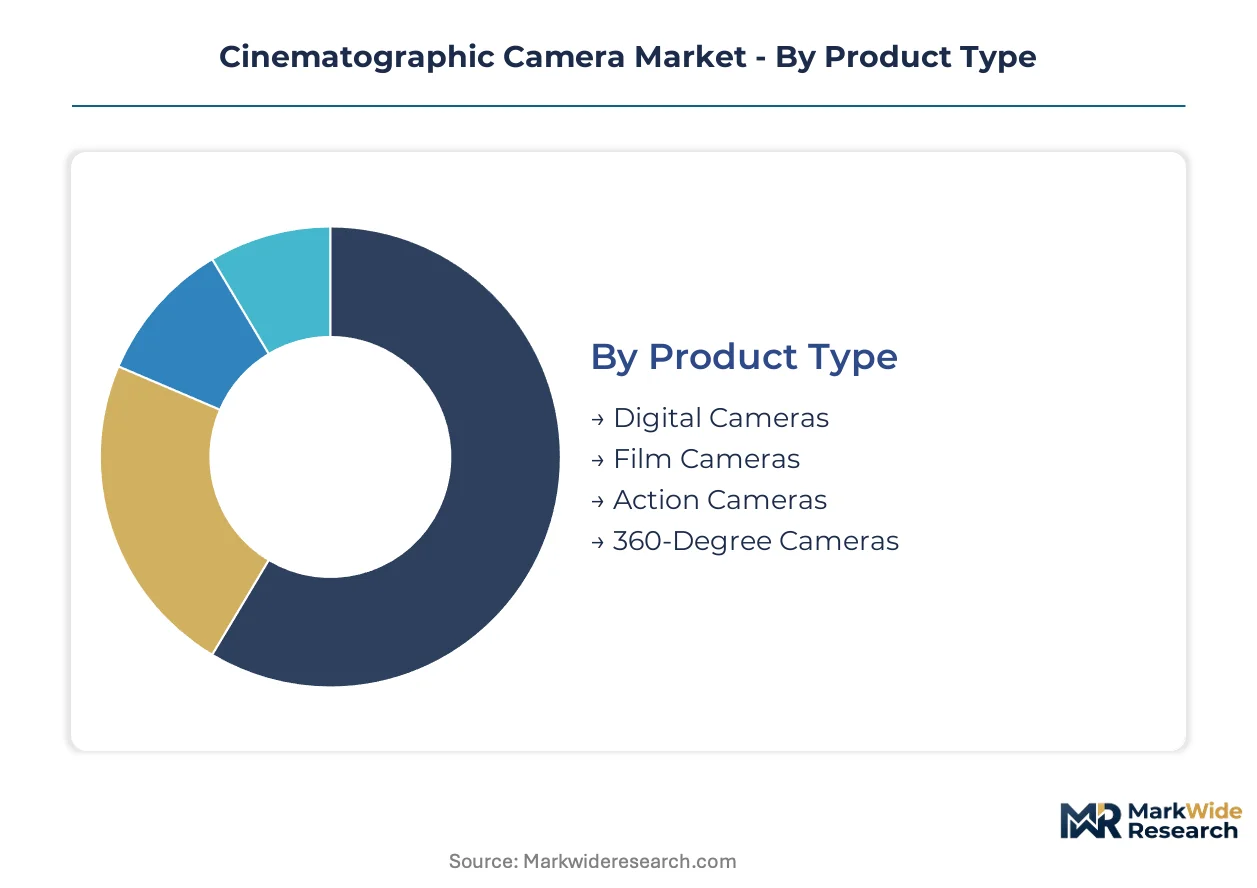
Segmentation in cinematographic cameras reveals divergent hardware refresh rhythms across user types and production formats. Equipment procurement cycles range from quarterly module upgrades for streaming content creators to decade-long investments for theatrical film studios.
Product Type:
Digital cameras turn over fastest as streaming platforms compress commissioning calendars, while film cameras face extended replacement cycles amid laboratory infrastructure contraction.
- Digital Cameras:Super 35mm and larger format sensors with 10-bit color depth and logarithmic gamma encoding dominate commercial production. Los Angeles and Atlanta studio clusters drive concentrated procurement for rental-ready packages as streaming commissioning accelerates hardware refresh timelines.
- Film Cameras:Photochemical negative acquisition systems retain niche demand for archival preservation and select theatrical productions. Regional laboratory closures strand legacy owners without reliable dailies processing, constraining fleet expansion outside established preservation hubs.
- Action Cameras:Ruggedized compact systems for extreme environment cinematography serve sports documentaries and stunt sequences.
- 360-Degree Cameras:Spherical capture systems enable virtual production backgrounds and immersive content formats.
Digital cameras anchor the volume base while action cameras gain share at the steepest rate.
Technology:
Cost tiers separate professional rental house fleets from independent creator equipment, with sensor fabrication scale determining price-performance positioning.
- Mirrorless:Reduced weight profiles and continuous autofocus integration displace traditional chassis across independent filmmaker segments. Documentary crews adopt embedded computational photography capabilities fastest as real-time noise reduction migrates from post-production into camera bodies.
- Cinematic:Large-format sensor blocks with proprietary media workflows command premium rental positioning. ARRI AG leverages Munich-based service networks to sustain margins on theatrical production deployments.
- DSLR:Optical viewfinder systems retain limited demand among legacy equipment owners and specific broadcast applications.
- Compact:Lightweight configurations with wireless transmission modules serve live-event cinematography where operator mobility determines shot feasibility.
Cinematic technology captures the highest margin tier while compact configurations expand most quickly into documentary and concert film applications.
End User:
Customer type determines procurement channel structure, with rental house intermediaries dominating studio transactions and direct-to-manufacturer sales rising among independent operators.
- Film Studios:Theatrical exhibition standards govern deliverable specifications for feature production. Streaming platform technical operations teams centralize fleet management across multiple production subsidiaries, unbundling after-sales service from equipment purchase agreements.
- Content Creators:Firmware-unlocked feature sets and sensor block replacements enable manufacturers to bypass rental intermediaries. Independent filmmakers drive demand for sub-$10,000 mirrorless chassis as embedded processing compresses the price-performance gap with professional tiers.
- Independent Filmmakers:Mid-tier digital cinema requirements for episodic and commercial production concentrate in multilingual commissioning markets.
- Educational Institutions:Training programs and academic research facilities sustain demand for standardized curriculum equipment.
Film studios anchor the volume base while content creators gain share at the steepest rate.
Application:
Application-specific requirements fragment engineering priorities between controlled studio environments and unpredictable location conditions.
- Feature Films:Theatrical exhibition specifications mandate maximum resolution and color grading latitude. Large-format camera packages with standardized accessory ecosystems dominate Los Angeles production infrastructure.
- Live Events:Real-time director monitoring demands wireless transmission modules and compact form factors. Concert films and sports documentaries drive fastest adoption of gimbal-stabilized and drone-mounted configurations.
- Documentaries:Run-and-gun scenarios prioritize operator mobility and extended battery endurance over maximum resolution.
- Commercials:Compressed production schedules favor rental-ready equipment with rapid technical support response.
Feature films anchor the volume base while live events gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement channels. Rental houses in established production hubs absorb premium pricing for fleet-standardized packages, while independent operators in emerging markets prioritize sub-$10,000 mirrorless configurations with firmware-upgrade paths.
United States
Los Angeles studio clusters and Atlanta's expanding production infrastructure drive concentrated demand for large-format rental packages. FCC electromagnetic emission standards govern wireless transmission modules for director monitoring applications. Georgia's tax incentive programs accelerate fleet turnover rates among regional rental houses serving streaming platform productions.
Germany
ARRI AG's Munich-based service network sustains premium positioning for theatrical production equipment across European rental markets. EU F-Gas Regulation phase-down mandates force thermal management redesigns in high-resolution sensor systems. Bavarian manufacturing facilities absorb elevated REACH compliance costs for battery assemblies and printed circuit boards.
United Kingdom
London post-production facilities exhibit aggressive service unbundling from equipment purchase agreements. EMA chemical substance restrictions elevate material certification expenses for sensor packaging. Soho-based technical operations teams centralize fleet management across multiple production subsidiaries under streaming platform ownership.
India
Domestic streaming platform commissioning expansion creates underpenetrated demand for mid-tier digital cinema cameras suited to multilingual episodic production. BIS certification requirements for electronic imaging equipment extend go-to-market timelines for imported hardware. Maharashtra's Mumbai production cluster concentrates procurement pull for documentary and commercial configurations.
Japan
Sensor fabrication scale advantages concentrate among established precision imaging manufacturers serving broadcast-cinema hybrid deployments. METI industrial standards influence robotic camera platform development for automated studio environments. Tokyo-based technical operations anchor regional procurement patterns for compact configurations with embedded computational photography capabilities.
Cinematographic Camera Market Vendor Landscape
Capability concentration sits with heritage cinema equipment specialists; scale advantage sits with consumer electronics conglomerates with sensor fabrication integration. The vendor base separates into three functional tiers: Munich-rooted service-anchored theatrical specialists, California-based modular upgrade platforms, and Tokyo-headquartered broadcast-cinema hybrid suppliers. Consolidation pressure runs through rental house fleet standardization requirements and streaming platform technical specification centralization. Dominant competitive moves include direct-to-creator module upgrade programs and proprietary media workflow lock-in.
Within the heritage specialist tier, ARRI AG exemplifies service-network-dependent premium positioning. RED Digital Cinema occupies a position as the modular upgrade archetype bypassing rental intermediaries. Sony Group Corporation anchors the scale-driven broadcast-cinema hybrid segment with sensor fabrication integration that few competitors replicate.
| Leading Market Players |
|---|
| ARRI AG |
| RED Digital Cinema |
| Blackmagic Design |
| Canon Inc. |
| Sony Group Corporation |
| Panasonic Holdings Corporation |
| Nikon Corporation |
| Panavision |
| Kinefinity |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific freight corridors connecting East Asian sensor foundries to Los Angeles and Atlanta studio clusters transmit cost volatility directly into rental house fleet economics, compressing margins for non-integrated assemblers while amplifying price differentiation between premium service-anchored packages and commodity hardware tiers.
Pricing Analysis
After-sales service revenue tiers encompassing firmware unlocks, sensor block replacements, and extended maintenance contracts now drive lifetime value capture across manufacturer portfolios. Three-tier pricing structure across premium, standard, and economy levels separates ARRI AG's Munich-serviced theatrical packages from RED's modular upgrade paths and Blackmagic's sub-$10,000 mirrorless chassis. Price differentiation hinges on certification grade for EU F-Gas and REACH compliance alongside geographic delivery cost to production hubs. Cost compression in mid-tier digital cinema is intensifying because streaming platform technical operations teams centralize fleet procurement and unbundle service contracts. Independent filmmakers exhibit highest price sensitivity, while Los Angeles studio clusters absorbing premium positioning show lowest elasticity due to standardized accessory ecosystem lock-in.
Supply Chain Analysis
Export-control regimes restricting advanced CMOS image sensor fabrication equipment to East Asian foundries concentrate production capacity among Taiwan, South Korea, and Japan, exposing downstream assemblers to geopolitical allocation constraints. Supply chains draw from specialized silicon wafer substrates, precision optical glass, and hydrocarbon refrigerant thermal management systems. Single-source vulnerability concentrates in advanced sensor lithography where fewer than three foundries maintain theatrical-grade yield rates. Distribution runs through rental house intermediaries for studio production and direct-to-manufacturer channels for independent content creators, with firmware-upgrade paths increasingly bypassing traditional fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through EU F-Gas and REACH compliance creates switching costs that strand non-compliant competitors outside European rental markets.
For Market Incumbents: Pre-empt emerging modular-upgrade competitors by deepening backward integration into sensor calibration firmware and proprietary media workflow lock-in. Incumbents should accelerate Munich-based service network expansion to defend against streaming platform technical operations teams unbundling maintenance contracts. Certification investment in ISO 26262 robotic camera platforms creates channel control over automated studio deployments.
For New Entrants and Emerging Players: India's underpenetrated mid-tier digital cinema segment for multilingual episodic production offers the most accessible white-space target for new entrants. Documentary and concert film applications with compact wireless-enabled configurations present secondary penetration opportunity. A direct-to-creator go-to-market angle bypassing rental house intermediaries captures margin from firmware-unlocked feature sets.
For Investors and Strategic Acquirers: Heritage cinema equipment specialists with captive sensor fabrication partnerships represent the priority acquisition archetype for long-term viability across the next decade. Investors should monitor streaming platform commissioning calendar compression as the inflection indicator for hardware refresh cycle acceleration. Consolidation pressure through fleet standardization requirements favors scale-driven broadcast-cinema hybrid suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Creator Module Upgrade Program | Bypasses rental intermediaries to capture margin from independent filmmakers through firmware-unlocked sensor capabilities. |
| EU F-Gas Compliance Certification | Creates regulatory moat excluding non-compliant assemblers from European theatrical production equipment markets. |
| Robotic Camera Platform Development | Opens ISO 26262-governed hardware-software integration revenue beyond traditional camera body sales. |
| India Market Localization Partnership | Addresses BIS certification delays and multilingual episodic production demand in Maharashtra's Mumbai cluster. |
| After-Sales Service Unbundling Response | Publishes transparent parts pricing to retain streaming platform technical operations team relationships. |
Methodological Framework
Operator-level perspectives from rental house fleet managers, streaming platform technical operations leads, cinematography rental coordinators, and post-production facility engineers anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from SEC equipment manufacturer filings, EMA regulatory submission databases, and customs import records for imaging equipment. Bottom-up triangulation across procurement volume estimates and top-down cross-checks against production infrastructure investment disclosures ensured analytical robustness.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, technology tier, end-user category, and application format. CAGRs derived from production volume elasticity models incorporating streaming commissioning calendar compression and theatrical release window evolution. Forecast inputs included sensor fabrication capacity allocation schedules and regional laboratory infrastructure contraction rates for photochemical processing.
Practitioners should monitor East Asian foundry capacity allocation shifts and EU F-Gas phase-down enforcement intensity for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Camcorder Market
Imaging
Borescope Market
Imaging
Phosphor Screen Scanner Market
Imaging
Uncooled Thermal Imaging Market
Imaging
Global Digital Photography Market
Imaging
Micro Computed Tomography Market
Imaging
Global Automotive Imaging Market
Imaging
Brain Imaging and Neuroimaging Market
Imaging
Automotive 3D Imaging Market
Imaging
Side View Camera System Market
Imaging
Digital Microscope Market
Imaging
Global Broadcast Cameras Market
Imaging
Europe IP Camera Market
Imaging
Embedded Smart Cameras Market
Imaging
Live Cell Imaging Market
Imaging
AI-Based Fever Detection Camera Market