
 Holotomographic Imaging Market | 2026-2036
Holotomographic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Holotomographic Imaging Market Analytics
Aftermarket service revenue for instrument calibration and software updates is reconfiguring profitability models across the competitive landscape. Carl Zeiss AG leverages its established microscopy service infrastructure to capture recurring revenue streams. Tomocube Inc. anchors its commercial strategy on specialized holotomography platforms for live-cell analysis. Nikon competes through deep integration of optical engineering expertise with quantitative phase imaging workflows.
Holotomographic imaging reconstructs three-dimensional refractive index distributions of biological specimens without fluorescent labels or phototoxic staining, typically achieving diffraction-limited resolution across axial depths exceeding one hundred micrometers. The technique serves pharmaceutical screening and clinical pathology by enabling longitudinal observation of living cells in their native states. Microscopes and systems command the dominant share of hardware expenditure, while software segments for AI-driven segmentation and quantitative analysis represent the fastest-expanding margin pool. Label-free technology leads adoption in academic settings, whereas quantitative imaging applications in drug discovery are displacing conventional fluorescence-based assays.
FDA 510(k) pathways for novel optical diagnostic devices shape product development priorities for manufacturers seeking clinical market access. ISO 13485 quality management standards and EU MDR requirements govern instrument certification for healthcare deployment in regulated jurisdictions. EMA guidance on biomarker validation and the EU AI Act's risk classification framework for diagnostic algorithms will determine which stakeholders capture value in clinical translation.
Market Dynamics
Pharmaceutical contract research organizations are consolidating purchasing power around label-free quantitative imaging platforms, compressing vendor margins while accelerating FDA 510(k) clearance timelines for AI-integrated diagnostic systems.
Growth Catalysts
- FDA 510(k) Pathway Acceleration:Streamlined premarket notification procedures for AI-enhanced optical diagnostic devices reduce commercial deployment barriers for manufacturers targeting clinical pathology workflows.
- Live-Cell Analysis Demand:Drug discovery laboratories are abandoning phototoxic fluorescence assays in favor of longitudinal observation capabilities that holotomography provides for toxicity screening.
- South Korean Government Funding:National research foundation grants for advanced bioimaging infrastructure at university medical centers are driving procurement volumes in Seoul and Daegu clusters.
Market Restraints
- High-Precision Optics Supply Concentration:German and Japanese specialty lens manufacturers control critical objective lens supply, creating vulnerability for instrument assemblers without captive optical fabrication.
- EU MDR Certification Burden:Extended clinical evaluation requirements and notified body capacity constraints are delaying CE marking timelines for quantitative phase imaging systems intended for diagnostic use.
- Fluorescence Microscopy Incumbency:Established antibody staining protocols and researcher familiarity with confocal platforms create switching friction in academic settings despite holotomography's label-free advantages.
Strategic Opportunities
- AI Algorithm Licensing Models:Revenue streams from segmentation and quantitative analysis software subscriptions are expanding faster than hardware sales as laboratories seek recurring analytical capabilities.
- EMA Biomarker Validation Guidance:Emerging regulatory frameworks for quantitative imaging biomarkers in oncology trials create first-mover advantages for vendors with validated analytical pipelines.
- India Research Infrastructure Buildout:Central government biotechnology department funding for national imaging facilities in Bangalore and Hyderabad represents underpenetrated demand for mid-range holotomography systems.
Industry Challenges
- Computational Reconstruction Expertise Gap:Laboratories lack personnel trained in inverse problem algorithms and GPU-accelerated tomographic reconstruction, forcing vendors to bundle extensive training and support services.
- Interoperability with LIMS:Integration of proprietary holotomography data formats with existing laboratory information management systems requires custom middleware development that extends deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holotomographic Imaging Market |
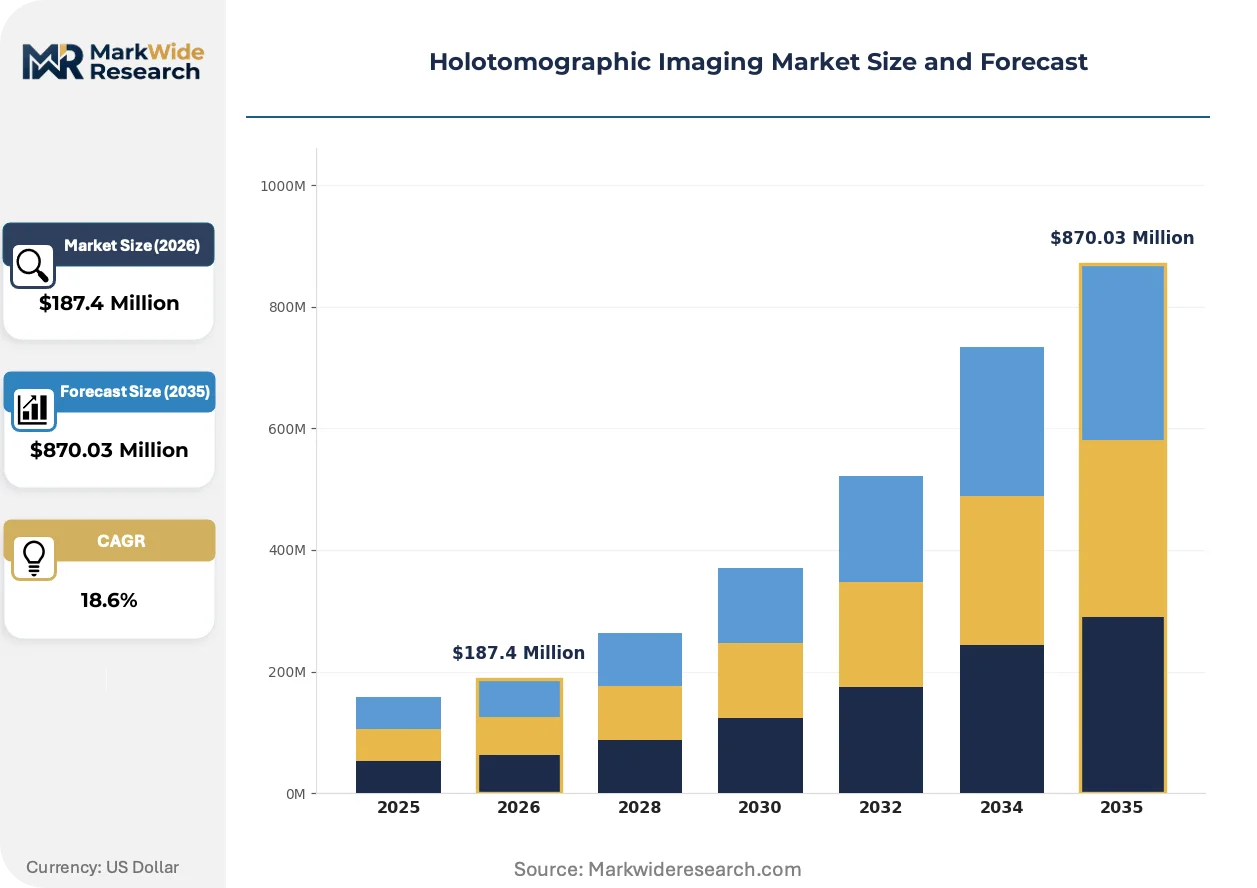
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscopes, Systems, Software, Accessories Technology: Label-Free, 3D Imaging, Phase Imaging, Quantitative Imaging Application: Cell Biology, Material Science, Clinical Diagnostics, Pharmaceutical Research End User: Academic Institutions, Research Laboratories, Healthcare Facilities, Industrial Manufacturers |
| Companies Covered | AXT PTY LTD, Carl Zeiss AG, Tomocube Inc., Nikon, Hamamatsu Photonics, Nanolive SA, Leica Microsystems, Olympus Corporation, EINST Technology Pte Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holotomographic Imaging Market Evolving Landscape
Computational imaging architectures are converging with machine learning inference at the edge, compressing reconstruction times from hours to minutes while enabling real-time decision support in pharmaceutical screening workflows.
Deep learning-based phase retrieval algorithms are hybridizing with traditional interferometric measurement techniques. Contract research organizations in Boston and Basel are deploying these hybrid systems for high-throughput phenotypic screening. The convergence is collapsing the distinction between raw acquisition and analyzed output, eliminating post-processing bottlenecks that previously constrained experimental throughput.
The EU AI Act's risk classification framework for diagnostic algorithms is compelling manufacturers to restructure product development roadmaps. High-risk system designations for pathology applications trigger conformity assessment procedures that extend certification timelines by twelve to eighteen months. German and French notified bodies are prioritizing submissions that include prospective clinical validation studies over retrospective algorithm training datasets.
Service unbundling is fragmenting traditional instrument procurement contracts. Academic medical centers in the United States are separating hardware acquisition from software licensing and calibration maintenance, enabling multi-vendor analytical stacks. This purchasing pattern is most pronounced at National Institutes of Health-funded institutions where modular budgeting aligns with grant cycle constraints and equipment sharing mandates across departmental boundaries.
Holotomographic Imaging Market Segmentation
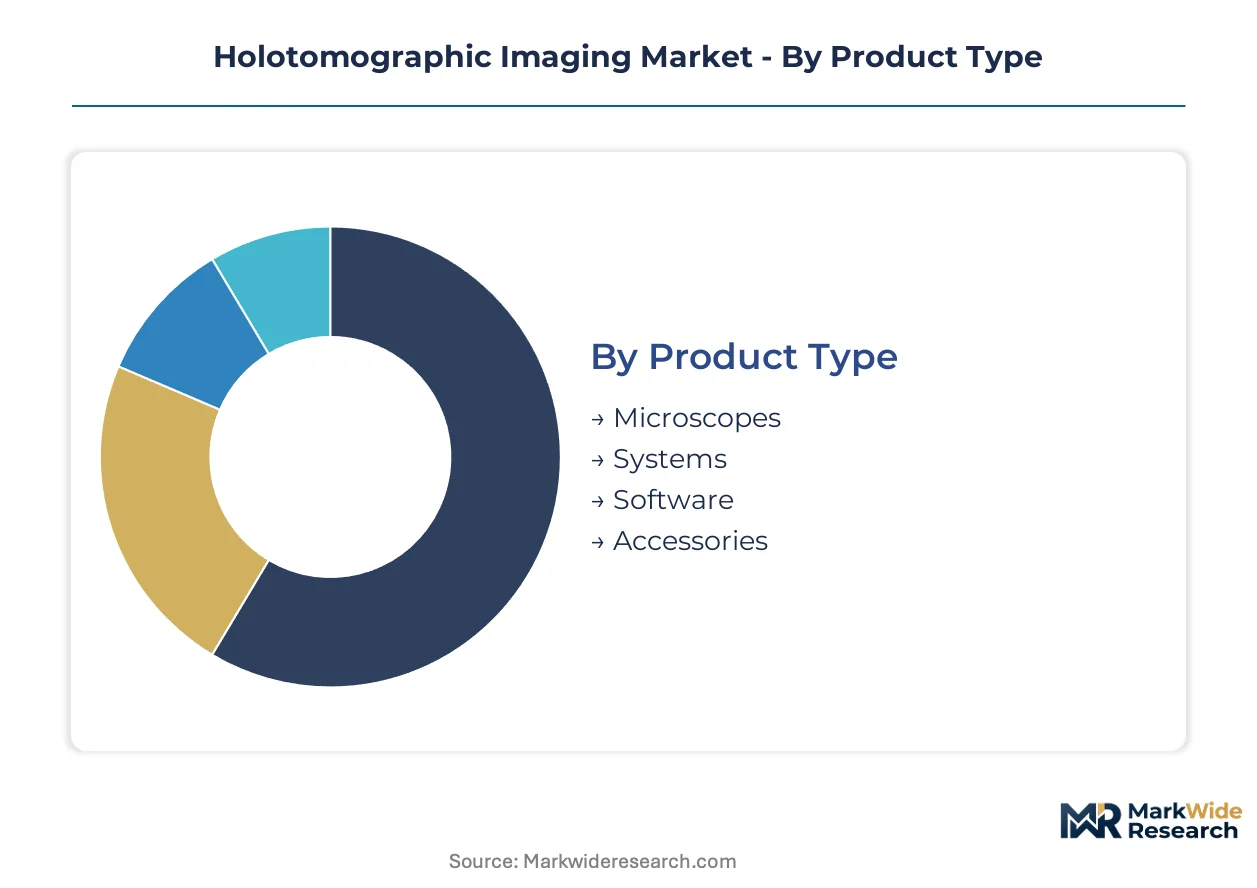
Segmentation in holotomographic imaging reveals how hardware expenditure, software margins, and end-use requirements diverge across research and clinical settings. Understanding these divisions exposes where procurement power concentrates and which technology configurations command premium positioning.
Product Type:
Hardware differentiation separates capital-intensive platforms from recurring revenue attachments that laboratories prioritize in grant-funded environments.
- Microscopes:Optical assemblies with specialized objective lenses and interferometric detection modules deliver diffraction-limited resolution across axial depths exceeding one hundred micrometers. Demand clusters at university medical centers in the United States, Germany, and South Korea where national research foundation grants underwrite instrument acquisition.
- Systems:Integrated platforms combining acquisition hardware with GPU-accelerated reconstruction engines compress tomographic processing from hours to minutes. Pharmaceutical contract research organizations in Boston and Basel are consolidating purchasing power around these configurations for high-throughput phenotypic screening.
- Software:AI-driven segmentation and quantitative analysis modules.
- Accessories:Calibration standards, sample holders, and illumination components.
Microscopes command the established base. The steepest expansion runs through Software.
Technology:
Technical approaches segment by whether specimens require fluorescent labels or native-state observation, determining adoption friction in established microscopy workflows.
- Label-Free:Elimination of phototoxic staining and fluorescent tags enables longitudinal observation of living cells without perturbation. Academic institutions lead adoption despite switching friction from established antibody protocols, particularly at NIH-funded institutions where equipment sharing mandates favor modular analytical stacks.
- 3D Imaging:Reconstruction of volumetric refractive index distributions.
- Phase Imaging:Interferometric measurement of optical path length variations.
- Quantitative Imaging:Numerical extraction of biophysical parameters from phase data. Drug discovery laboratories are displacing conventional fluorescence-based assays with these capabilities for toxicity screening, driving fastest share gain in pharmaceutical research applications.
Label-Free anchors current installed base. Quantitative Imaging climbs the fastest as validated analytical pipelines penetrate regulated workflows.
Application:
Use-case segmentation tracks where longitudinal live-cell observation displaces destructive or endpoint assays, with regulatory clearance timelines determining commercial access.
- Cell Biology:Native-state observation of cellular dynamics, division, and response to stimuli without fixation artifacts. Research laboratories in Seoul and Daegu clusters leverage South Korean government funding for advanced bioimaging infrastructure.
- Material Science:Characterization of transparent and semi-transparent specimens.
- Clinical Diagnostics:Pathology workflows requiring FDA 510(k) clearance or EU MDR certification for diagnostic claims. Extended clinical evaluation requirements and notified body capacity constraints delay CE marking timelines for quantitative phase imaging systems in regulated jurisdictions.
- Pharmaceutical Research:High-throughput toxicity screening and mechanism-of-action studies. FDA 510(k) pathway acceleration for AI-enhanced optical diagnostic devices reduces commercial deployment barriers for manufacturers targeting these workflows.
Cell Biology holds the largest installed footprint. Pharmaceutical Research gains share fastest as CRO procurement consolidates around label-free quantitative platforms.
End User:
Customer type segmentation exposes diverging procurement patterns between grant-funded academic flexibility and industrial purchasing discipline.
- Academic Institutions:University medical centers and research institutes with modular budgeting aligned to grant cycles. Service unbundling is fragmenting traditional instrument procurement contracts, enabling multi-vendor analytical stacks at National Institutes of Health-funded institutions.
- Research Laboratories:Dedicated imaging facilities and core microscopy centers.
- Healthcare Facilities:Clinical pathology departments requiring diagnostic-grade systems with ISO 13485 quality management certification and conformity assessment under EU AI Act risk classification frameworks.
- Industrial Manufacturers:Quality control and materials characterization operations.
Academic Institutions dominate current procurement volumes. Healthcare Facilities expand most quickly as FDA clearance pathways mature for AI-integrated diagnostic systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across jurisdictions. United States buyers absorb premium pricing for FDA-cleared systems, while Indian research institutes prioritize cost-calibrated mid-range platforms under central government biotechnology funding schemes.
United States
University medical centers and NIH-funded institutions drive instrument acquisition through modular grant budgeting aligned to equipment-sharing mandates. FDA 510(k) pathway acceleration for AI-enhanced optical diagnostic devices compresses commercial deployment timelines for clinical pathology applications. Boston and San Francisco Bay Area clusters anchor pharmaceutical contract research organization procurement volumes.
Germany
Specialty lens manufacturers in Baden-Württemberg and Bavaria control critical objective lens supply for instrument assemblers. EU MDR certification requirements and notified body capacity constraints extend CE marking timelines for quantitative phase imaging systems. Munich and Heidelberg university medical centers concentrate demand for label-free live-cell analysis platforms.
South Korea
National research foundation grants underwrite advanced bioimaging infrastructure procurement at university medical centers. MFDS regulatory frameworks for medical device software shape AI-integrated diagnostic system development priorities. Seoul and Daegu clusters anchor government-funded imaging facility buildouts with concentrated vendor activity.
India
Central government biotechnology department funding supports national imaging facility development in metropolitan research hubs. CDSCO regulatory pathways for optical diagnostic devices remain underdeveloped relative to mature markets, creating deployment friction. Bangalore and Hyderabad represent underpenetrated demand centers for mid-range holotomography systems in academic settings.
Switzerland
Pharmaceutical headquarters concentration in Basel drives demand for high-throughput phenotypic screening platforms. Swissmedic conformity assessment procedures for diagnostic-grade systems align with EU MDR standards despite non-member status. Zurich and Geneva academic medical centers procure label-free platforms for longitudinal toxicity studies.
Holotomographic Imaging Market Competitive Landscape
Established optical conglomerates and specialized holotomography innovators split the market along capability-depth versus breadth-of-portfolio lines. Tier-one players leverage captive precision-optics fabrication and legacy microscopy service infrastructure to capture recurring calibration revenue. Mid-scale specialists compete through AI-integrated reconstruction engines and application-specific live-cell workflows. Dominant competitive moves include strategic partnerships for computational algorithm licensing and geographic expansion into government-funded Asian research clusters.
Within the diversified-optical tier, Carl Zeiss AG and Nikon occupy positions anchored by decades of microscopy infrastructure and global service networks. Tomocube Inc. exemplifies the specialized-platform archetype, concentrating development resources on dedicated holotomography systems for native-state cellular observation. These three entities collectively illustrate how market positioning stratifies between breadth-driven incumbents and depth-focused innovators.
| Leading Market Players |
|---|
| AXT PTY LTD |
| Carl Zeiss AG |
| Tomocube Inc. |
| Nikon |
| Hamamatsu Photonics |
| Nanolive SA |
| Leica Microsystems |
| Olympus Corporation |
| EINST Technology Pte Ltd |
| Others |
Value Network & Pricing Analysis
Shanghai-Seoul air freight corridors carry precision optical components at rates that compress margins for instrument assemblers lacking captive lens fabrication. German and Japanese specialty manufacturers control critical objective lens supply, forcing downstream vendors to absorb logistics volatility or cede pricing power to integrated competitors with in-house optical production.
Pricing Analysis
Aftermarket service revenue from calibration contracts and software subscription renewals drives lifetime value in this market. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared diagnostic systems from research-grade configurations, with certification tier and after-sales bundling as primary differentiation levers. Cost compression in mid-range hardware is intensifying because pharmaceutical contract research organizations are consolidating purchasing power around integrated platforms. Academic institutions exhibit highest price sensitivity due to grant-cycle budgeting constraints, while clinical pathology departments absorb premium pricing for regulatory-cleared systems.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts semiconductor laser and detector module sourcing for interferometric detection assemblies. Critical supply draws from Germany, Japan, and South Korea for precision objective lenses, GPU-accelerated reconstruction engines, and specialized illumination components. Single-source vulnerability concentrates in high-NA objective lens fabrication, where Schott glass and proprietary coating technologies anchor production. Distribution runs through direct sales teams for clinical systems and specialized microscopy distributors for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as service unbundling fragments traditional instrument procurement contracts, creating niches for modular software vendors and independent calibration providers alongside hardware incumbents.
For Market Incumbents: Build switching-cost moats through proprietary data format ecosystems that lock laboratories into analytical workflows. Deepen backward integration into precision optics fabrication to neutralize supply-side vulnerability from German and Japanese lens manufacturers. Capture recurring revenue through AI algorithm licensing models that outpace hardware sales expansion. Prioritize ISO 13485 certification investment to defend against emerging diagnostic-grade competitors seeking clinical market access. For New Entrants and Emerging Players: Pursue underpenetrated demand in Indian national imaging facilities where central government biotechnology funding supports mid-range system procurement. Target Bangalore and Hyderabad academic clusters with cost-calibrated platforms that sacrifice FDA clearance pathways for research-grade performance. Attack the computational reconstruction expertise gap with bundled training services and GPU-accelerated cloud reconstruction offerings. Deploy direct-to-laboratory digital sales channels to bypass established microscopy distributor relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified optical conglomerates seeking to divest non-core microscopy divisions amid portfolio rationalization. Long-term viability hinges on AI-integrated diagnostic system clearance timelines and EMA biomarker validation framework maturation. Acquire specialized holotomography innovators with validated analytical pipelines for oncology trials. Monitor FDA 510(k) submission volumes for AI-enhanced optical devices as inflection indicator for clinical market access velocity.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm Licensing Platform | Recurring revenue from pharmaceutical CROs in Boston and Basel exceeds hardware margins. |
| Backward Integration into Precision Optics | Captive objective lens production neutralizes supply concentration in Baden-Württemberg. |
| FDA 510(k) Diagnostic Pathway Investment | Clinical pathology access unlocks premium pricing at NIH-funded university medical centers. |
| EMA Biomarker Validation Partnership | First-mover positioning in quantitative imaging biomarkers for oncology trials secures advantage. |
| South Korean Government Funding Alignment | Seoul and Daegu cluster procurement anchors regional demand for live-cell analysis platforms. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committees, pharmaceutical screening directors, and microscopy core facility managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA medical device guidance documents, South Korean National Research Foundation grant disclosures, and EU MDR notified body capacity reports. Bottom-up instrument shipment tracking and top-down research funding allocation analysis provided triangulation across data sources.
Scenario-bracketing around regulatory clearance timelines and research funding cycles shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology approach, application area, end-user category, and regional regulatory cluster. CAGRs derived from instrument replacement cycles, grant funding growth trajectories, and AI diagnostic algorithm adoption curves. GPU processing cost decline and interferometric detector module pricing trends informed hardware margin projections.
Sensitivities concentrate around EU MDR notified body capacity constraints, FDA AI diagnostic device review queue length, and South Korean government bioimaging infrastructure budget allocations. Forecasts reflect assumptions on regulatory pathway acceleration and pharmaceutical CRO procurement consolidation patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
North America IP Camera Market
Imaging
Thermal Camera Market
Imaging
Infrared Imaging Market
Imaging
Microscope Digital Cameras Market
Imaging
Europe CT Market
Imaging
Handheld Fluorescence Imaging Devices Market
Imaging
Handheld Imager Market
Imaging
EUV Mask Inspection System Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Thermal Imaging Camera Market
Imaging
Digital Image Processing Market
Imaging
In Vivo Imaging Systems Market
Imaging
Thermal Imaging Systems Market
Imaging
Plenoptic Camera Market
Imaging
Infrared Imaging Software Market
Imaging
IR Camera Market