
 North America Digital Camera Market | 2026-2036
North America Digital Camera Market Size, Share, and Industry Trends Forecast 2026-2036
North America Digital Camera Market Intelligence
Modular lens-and-body bundling is rebalancing buyer choice across the North America digital camera landscape. Canon Inc. leverages its EF and RF mount ecosystem to sustain loyalty among professional photographers who prioritize backward compatibility. Sony Corporation dominates full-frame mirrorless sensor development, while Nikon Corporation anchors its position through Z-mount optics that compete on low-light performance.
A digital camera captures still images or video through an electronic image sensor, typically CMOS or CCD, converting photons into digital signals processed by onboard ASICs for storage on removable media. Mirrorless product types lead volume growth as EVF latency and battery efficiency close the gap with optical viewfinder performance. Professional photographers within the end-user segment command the highest price tier concentration, while action cameras capture expanding share among videographers seeking stabilized 4K output in rugged form factors.
The FCC equipment authorization process governs wireless transmission capabilities in cameras sold across the United States, while Health Canada and the PMRA oversee electromagnetic compatibility standards for Canadian imports. California's SB 244 right-to-repair legislation pressures manufacturers to expand parts availability, altering post-sale service economics. Stakeholders must monitor how state-level repair mandates interact with federal warranty regulations to anticipate compliance cost allocation between brands and authorized service networks.
Market Dynamics
Video-first content creation workflows are restructuring demand patterns across the North America digital camera market, compressing upgrade cycles and elevating computational imaging capabilities as primary purchase criteria over optical heritage.
Growth Catalysts
- FCC Equipment Authorization:Wireless-enabled cameras with live-streaming functionality gain faster market entry through streamlined certification pathways, accelerating product refresh rates for streaming-focused creators.
- California SB 244 Right-to-Repair Mandate:Parts availability requirements extend product lifecycles and reduce total cost of ownership for professional videographers operating high-duty-cycle equipment.
- Los Angeles and San Francisco Metro Clusters:Production studio density and independent creator concentration generate concentrated demand pull for cinema-grade mirrorless systems and cinema lenses.
Market Restraints
- Image Sensor Supply Concentration:Advanced CMOS fabrication capacity concentrates among a limited set of foundry operators, creating input bottlenecks for full-frame and medium-format camera production.
- Smartphone Computational Photography Substitution:Multi-frame stacking and AI-driven night modes on flagship mobile devices erode entry-level compact camera demand among casual consumers.
- Battery Chemistry Cost Volatility:Lithium-ion cell price fluctuations impact margin structures for manufacturers prioritizing extended recording times in 4K and 8K video specifications.
Strategic Opportunities
- Texas and Atlanta Production Hubs:Emerging content creation centers outside traditional coastal clusters present underdeveloped demand pockets for professional camera dealers and rental houses.
- Direct-to-Creator E-commerce Channels:Manufacturer-owned storefronts bypass traditional retail markups, capturing margin while building first-party data on independent filmmaker purchase patterns.
- Health Canada Electromagnetic Compatibility Harmonization:Alignment with FCC testing protocols reduces dual-certification burdens for cross-border product launches, compressing time-to-revenue for Canadian market entry.
Industry Challenges
- ASIC and Firmware Talent Scarcity:Computational imaging pipelines require specialized signal processing engineers, with competition intensifying from autonomous vehicle and smartphone sectors for equivalent skill sets.
- Legacy Mount Compatibility Engineering:Adapter development for vintage lens ecosystems demands ongoing R&D investment without corresponding hardware revenue, straining product development prioritization.
- Climate-Controlled Storage Infrastructure:Professional-grade sensor and lens inventory requires humidity-managed warehousing, elevating working capital requirements for distributor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Digital Camera Market |
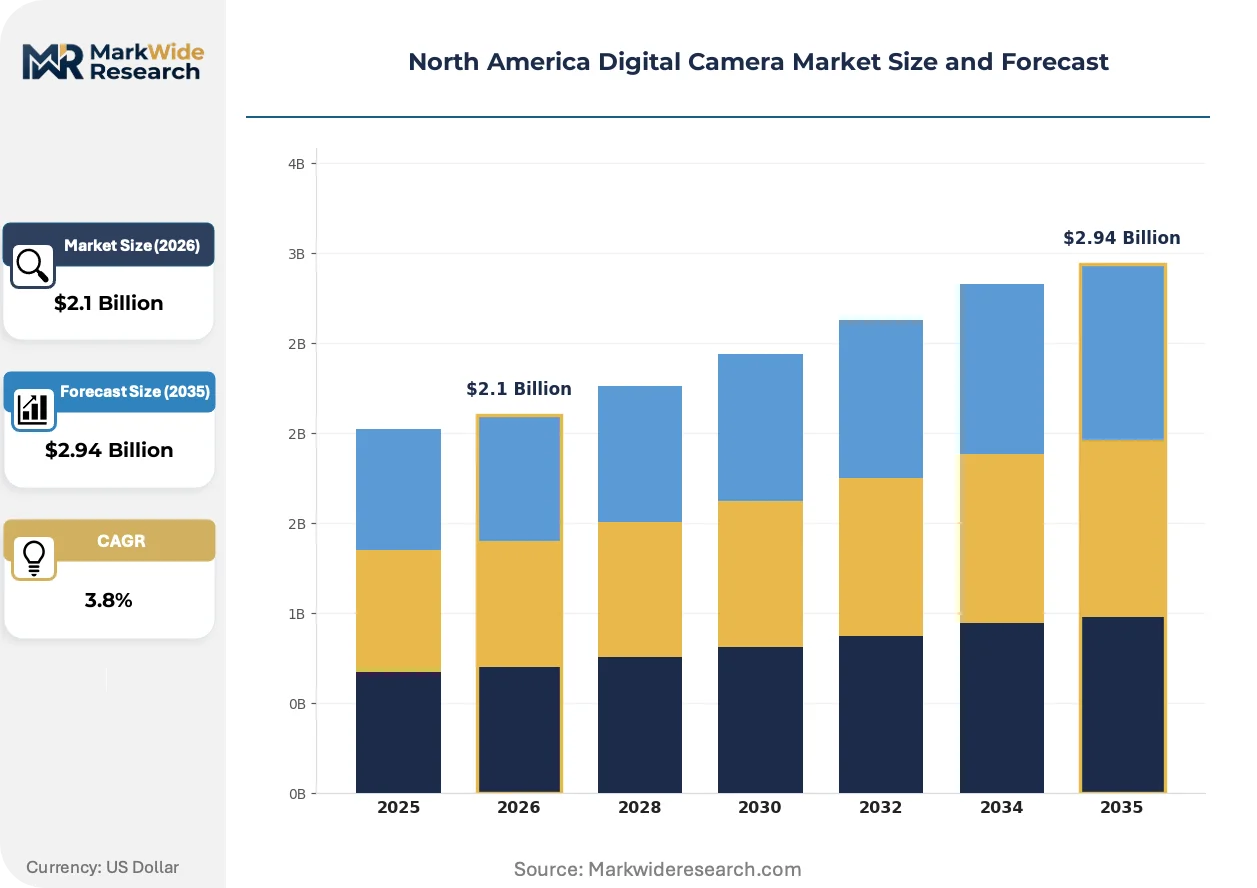
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DSLR, Mirrorless, Compact, Action End User: Professional Photographers, Amateurs, Videographers, Hobbyists Technology: Optical, Digital, Hybrid, Film Price Tier: Entry-Level, Mid-Range, High-End, Luxury |
| Companies Covered | Canon Inc., Nikon Corporation, Sony Corporation, Panasonic Corporation, FUJIFILM Holdings Corporation, Olympus Corporation, Leica Camera AG, GoPro Inc., Ricoh Imaging Company, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Digital Camera Market Strategic Shifts & Innovations
Computational photography integration and modular hardware architectures are dissolving traditional boundaries between capture devices and post-production pipelines, redefining where value accrues in the imaging ecosystem.
Computational stacking algorithms are modularizing the boundary between optical hardware and software correction layers. Wedding and event videographers adopt these systems fastest, accepting slight EVF latency tradeoffs for real-time HDR preview and in-camera subject tracking. This modularization compresses the traditional separation between production and post-production roles, forcing rental houses to retrain staff on hybrid capture-color workflows.
California's SB 244 right-to-repair legislation is mandating parts availability timelines and diagnostic tool access for authorized service networks. Manufacturers must restructure warranty economics to accommodate independent repair channel participation. Professional cinema camera operators in Los Angeles benefit most, as extended service windows reduce downtime costs on production schedules.
Creator economy procurement patterns favor subscription-based equipment access over capital ownership. YouTube and TikTok content producers in Austin and Miami increasingly source through short-term rental platforms and peer-to-peer lending marketplaces. This behavioral shift concentrates inventory risk with specialized rental aggregators rather than individual creators or traditional dealers.
North America Digital Camera Market Segmentation
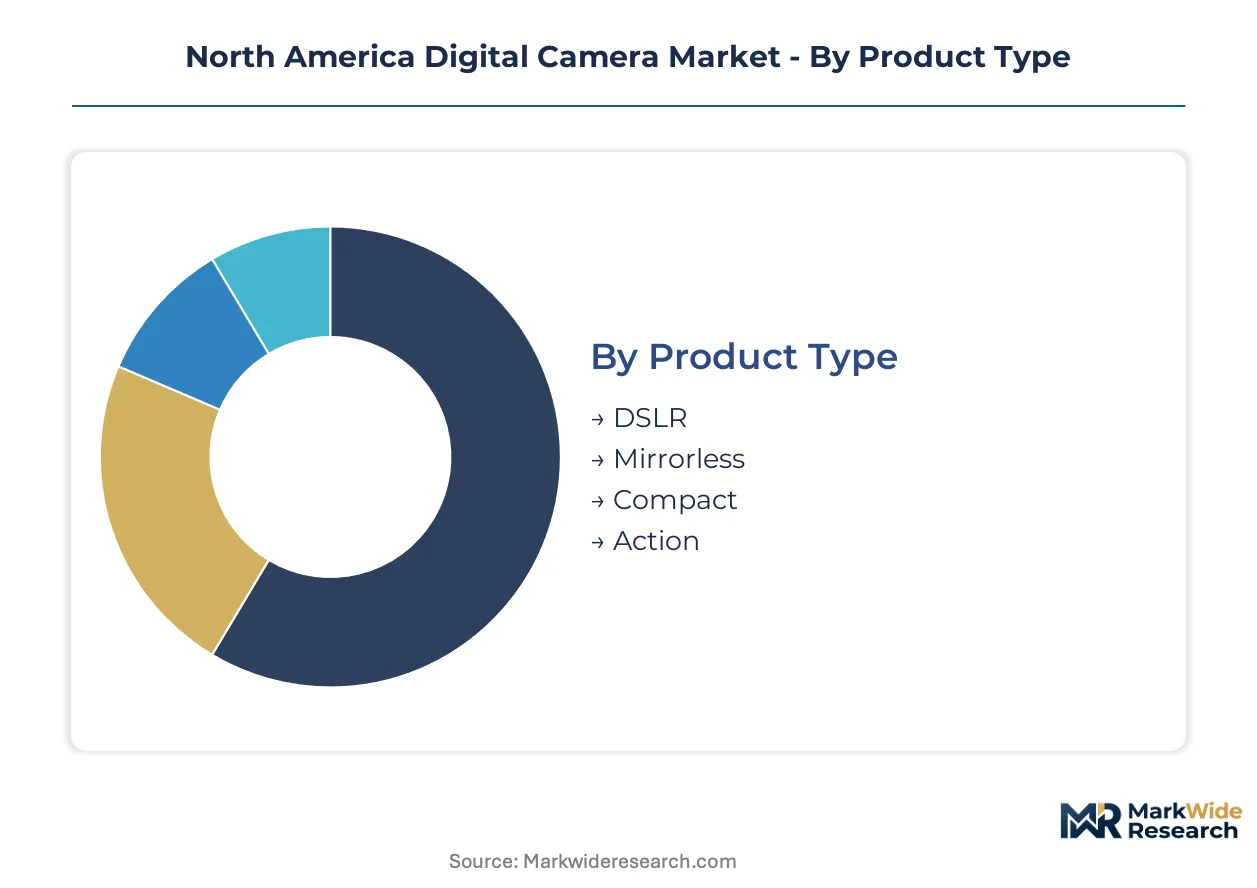
Camera manufacturers balance modular component architectures against integrated system designs across North America's imaging landscape. Segmentation reveals how computational capabilities and workflow specialization reshape purchasing patterns among content creators and production professionals.
Product Type:
The customization-vs-standardization spectrum spans interchangeable-lens systems with extensive accessory ecosystems versus fixed-lens units optimized for specific capture scenarios.
- DSLR:Optical viewfinder systems with mechanical mirror assemblies deliver zero-lag framing for sports and wildlife photographers. Demand concentrates among legacy professionals in Texas and Arizona who maintain extensive EF and F-mount lens collections. The FCC's streamlined equipment authorization benefits wireless tethering accessories extending DSLR utility in studio workflows.
- Mirrorless:Electronic viewfinder architectures with shortened flange distances enable compact body designs without sacrificing full-frame sensor formats. Los Angeles production studios and San Francisco Bay Area independent creators drive concentrated demand for cinema-grade mirrorless systems with internal 4K recording.
- Compact:Fixed-lens designs prioritize portability over optical flexibility for travel and documentary applications.
- Action:Ruggedized form factors with integrated stabilization target adventure sports and POV cinematography in Colorado and Utah outdoor recreation markets.
Leading the category by volume: Mirrorless. Growing fastest: Action.
End User:
Customer sophistication and production scale determine equipment specifications across the professional-amateur continuum.
- Professional Photographers:Commercial image-makers operating on client billing cycles require dual-card redundancy and weather sealing for high-duty-cycle deployment. California wedding studios and New York fashion photographers anchor demand for medium-format systems and cinema lenses. The SB 244 right-to-repair mandate reduces downtime costs for operators maintaining owned equipment fleets.
- Videographers:Moving-image specialists prioritize sustained recording durations, log gamma profiles, and external monitoring outputs for post-production flexibility. YouTube creators in Austin and Atlanta metro areas compress upgrade cycles as platform algorithm changes reward production value investments.
- Amateurs:Enthusiast purchasers with intermittent usage patterns favor hybrid systems bridging casual and semi-professional applications.
- Hobbyists:Recreation-focused buyers emphasize ease of operation and automated scene modes over manual control granularity.
Volume leadership sits with Professional Photographers. Steepest expansion trajectory belongs to Videographers.
Technology:
Capture methodology and signal processing architecture differentiate performance characteristics across imaging workflows.
- Digital:CMOS and CCD sensor arrays with onboard ADC conversion dominate contemporary production pipelines. FCC equipment authorization governs wireless transmission modules enabling instant image transfer for event photographers in Miami and Chicago metropolitan markets. Health Canada electromagnetic compatibility standards align with US testing protocols for cross-border product distribution.
- Hybrid:Systems combining analog capture elements with digital output stages serve niche archival and artistic applications.
- Optical:Pure analog viewfinder and exposure systems persist in specialized educational and fine-art contexts.
- Film:Chemical-based capture retains dedicated practitioner bases despite supply chain constraints for emulsion stocks and processing chemistry.
Digital commands category volume. Hybrid gains share fastest among specialty practitioners.
Price Tier:
Margin structures and feature bundling stratify across budget-conscious entry points to bespoke luxury configurations.
- High-End:Full-frame and medium-format systems with professional service warranties target revenue-generating operators. Los Angeles cinema camera rental houses and San Francisco commercial studios concentrate procurement at this tier for client-facing production value. Lithium-ion battery cost volatility impacts margin structures for manufacturers specifying extended recording durations.
- Mid-Range:APS-C and entry-level full-frame bodies balance sensor performance against portability for serious enthusiasts.
- Entry-Level:Sub-$1000 price points face sustained pressure from smartphone computational photography substitution among casual consumers.
- Luxury:Limited-edition collaborations and precious metal finishes serve collector markets with minimal correlation to imaging utility.
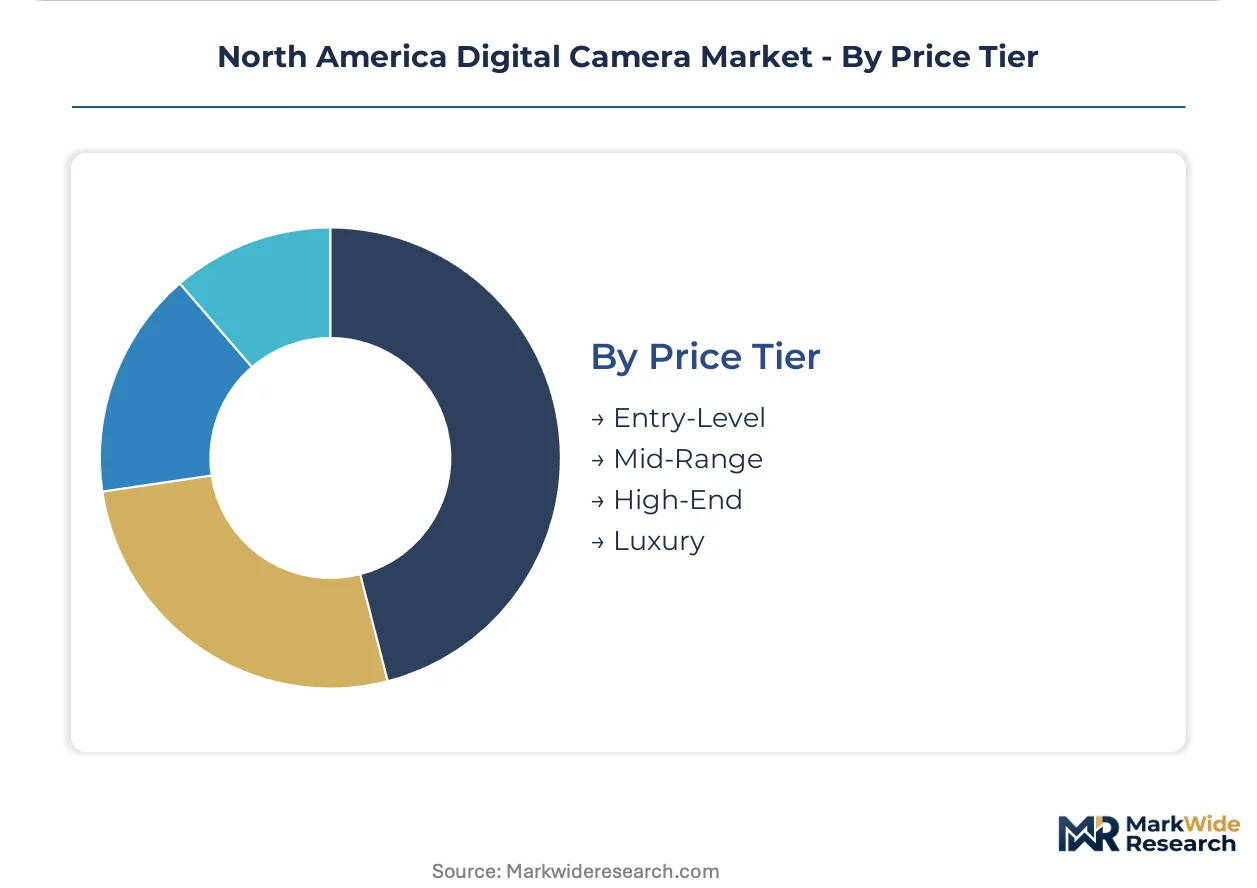
Mid-Range leads category volume. High-End climbs fastest as video-first workflows elevate professional feature requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Film and Television Tax Credit 3.0 concentrates production infrastructure and camera procurement decisions in the Los Angeles metro area, anchoring North American demand for cinema-grade imaging systems.
United States
FCC equipment authorization requirements govern wireless-enabled cameras with live-streaming capabilities, accelerating certification timelines for streaming-focused creators in Austin and Atlanta. YouTube and TikTok content producers in Miami metro areas compress upgrade cycles as platform algorithms reward production value investments. The SB 244 right-to-repair mandate in California extends parts availability timelines, reducing downtime costs for Los Angeles production studios operating high-duty-cycle equipment fleets.
Canada
Health Canada and PMRA electromagnetic compatibility standards align with FCC testing protocols, reducing dual-certification burdens for cross-border product launches into Toronto and Vancouver markets. Independent filmmakers in Montreal benefit from harmonized regulatory frameworks that compress time-to-revenue for new camera models. British Columbia's post-production sector concentrates demand for cinema-grade mirrorless systems with internal 4K recording specifications.
Mexico
Baja California's proximity to Los Angeles production infrastructure generates cross-border rental demand for professional cinema cameras used in location shooting. Mexico's national telecommunications regulator oversees wireless transmission modules, creating compliance coordination requirements for manufacturers serving Mexico City content creators. Guadalajara's emerging post-production cluster attracts investment in color-grading infrastructure that pulls camera procurement decisions.
North America Digital Camera Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the North America digital camera landscape. Market structure shows moderate consolidation around vertically integrated sensor developers and lens manufacturers, with fragmentation persisting in specialized action camera and cinema lens niches. Three archetypes dominate: full-stack imaging conglomerates controlling sensor-to-lens pipelines, modular system specialists emphasizing mount ecosystem compatibility, and ruggedized action camera pure-plays. Competitive moves concentrate on strategic partnerships for computational imaging IP and geographic expansion into emerging content creation hubs.
Within the full-stack imaging tier, Canon Inc. and Sony Corporation exemplify divergent approaches to ecosystem lock-in versus sensor supremacy. Nikon Corporation occupies a position bridging optical heritage with mirrorless transition imperatives. Panasonic Corporation and FUJIFILM Holdings Corporation sit within the hybrid video-still specialist archetype, while GoPro Inc. anchors the ruggedized action camera segment. These named entities represent strategic positioning patterns rather than specific market share claims.
| Leading Market Players |
|---|
| Canon Inc. |
| Nikon Corporation |
| Sony Corporation |
| Panasonic Corporation |
| FUJIFILM Holdings Corporation |
| Olympus Corporation |
| Leica Camera AG |
| GoPro Inc. |
| Ricoh Imaging Company, Ltd. |
| Others |
Cost & Logistics Intelligence
ASIC and firmware engineering talent concentration in California's Bay Area and Austin metro corridors creates labor-cost differentials that widen pricing-tier spreads between premium cinema-grade systems and mid-range mirrorless bodies. Manufacturers absorbing these specialized compensation premiums pass differential costs to professional videographers while entry-level compact segments face margin compression from smartphone substitution.
Pricing Analysis
Short lead-time premiums for FCC-authorized wireless modules command pricing advantages over spot-inventory procurement for non-certified components. Three-tier pricing structure across premium, standard, and economy levels segments by sensor format and recording specification, with full-frame cinema systems carrying brand premiums from Los Angeles studio procurement patterns. Price erosion runs through entry-level fixed-lens compacts as computational photography on flagship smartphones displaces casual consumer demand. Professional videographers in production studio clusters demonstrate least price sensitivity due to client-billing recovery models, while independent YouTube creators in emerging hubs exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing qualification requirements for advanced CMOS sensors concentrate procurement relationships across Japan, South Korea, and Taiwan fabrication facilities. Image sensor supply draws from limited foundry operators, lithium-ion battery cells feed from East Asian chemical processing hubs, and precision optical glass originates from German and Japanese specialty manufacturers. Single-source vulnerability in advanced sensor lithography equipment creates bottleneck exposure for full-frame and medium-format production ramps. Distribution runs through authorized dealer networks in coastal metro clusters, with direct-to-creator e-commerce channels capturing expanding share among independent filmmakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC equipment authorization requirements function as a cost-of-compliance moat, elevating barrier-to-entry economics for wireless-enabled camera entrants and consolidating advantage among incumbents with established certification infrastructure.
For Market Incumbents: To counter smartphone computational photography substitution at the entry tier, Canon and Sony should deepen backward integration into proprietary image processing ASICs while expanding captive sensor fabrication capacity. Channel control through direct-to-creator storefronts captures first-party data and margin compression from traditional retail markups. For New Entrants and Emerging Players: California SB 244 in the United States opens a window for independent repair channel specialists to capture service revenue from legacy equipment fleets as manufacturers restructure warranty economics. White-space targets include Texas and Atlanta production hubs outside saturated coastal clusters, with go-to-market execution through short-term rental platforms serving creator economy procurement shifts. For Investors and Strategic Acquirers: Re-rating potential sits with modular system specialists given Health Canada electromagnetic compatibility harmonization compressing cross-border certification timelines. Long-term viability over the coming decade favors pure-play action camera developers with ruggedized IP and stabilized 4K output specifications. Signal to watch: lithium-ion cell cost volatility as inflection indicator for margin structure sustainability in extended-recording video specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Computational Imaging ASIC Development | Proprietary signal processing pipelines differentiate HDR preview and real-time subject tracking for wedding videographers. |
| Direct-to-Creator E-commerce Launch | Manufacturer-owned storefronts bypass retail markups while building first-party data on Austin and Miami filmmaker purchase patterns. |
| Right-to-Repair Service Network Expansion | SB 244 compliance extends parts availability timelines, reducing downtime costs for Los Angeles production studios. |
| Cross-Border Certification Harmonization | Health Canada alignment with FCC protocols compresses time-to-revenue for Toronto and Vancouver market entry. |
| Emerging Hub Rental Platform Partnership | Inventory aggregation models concentrate risk with specialized rental houses serving Atlanta and Austin content creators. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North America digital camera market assessment. Primary interviews with camera product managers, rental house operations directors, post-production facility engineers, and independent filmmaker procurement leads combined with FCC equipment authorization databases, Health Canada electromagnetic compatibility standards, California SB 244 legislative tracking, and SEC manufacturer disclosures. Bottom-up shipment modeling and top-down production value estimates underwent cross-validation triangulation.
Granularity-level modeling distinguished product type, end-user sophistication tier, sensor technology architecture, and regional metro cluster demand density across the projection horizon. CAGRs derived from segment-level volume trajectories and value-per-unit trends incorporated lithium-ion battery cost volatility assumptions, computational photography substitution elasticities, and platform algorithm-driven upgrade cycle compression for YouTube and TikTok creators.
The model assumes a particular technology adoption path; alternative pathways for mirrorless EVF latency reduction would alter the outlook for DSLR residual demand among sports photographers. Forecasts reflect assumptions around FCC certification timeline stability and Health Canada protocol alignment durability. Deviation in lithium-ion cell supply chain disruption or smartphone night-mode computational advancement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Multi Camera System Market
Imaging
LCD Digital Microscope Market
Imaging
Macroscopic Imaging Systems Market
Imaging
High Dynamic Range Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Europe IP Camera Market
Imaging
CMOS Camera Market
Imaging
Europe Image Sensors Market
Imaging
Photoacoustic Microscope Market
Imaging
North America Image Sensors Market
Imaging
Infrared Imaging Market
Imaging
Visualiser Market
Imaging
Facial Recognition Machine Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
PET Scanners Market
Imaging
Short-Wave Infrared Imaging Market