
 Photoacoustic Tomography Market | 2026-2036
Photoacoustic Tomography Market Size, Share, and Industry Trends Forecast 2026-2036
Photoacoustic Tomography Market Analytics
The capital-intensity divergence between laser-source manufacturers and system integrators is bifurcating competitive dynamics in photoacoustic tomography. FUJIFILM VisualSonics Inc. leverages its vertically integrated transducer fabrication to dominate preclinical imaging segments. iThera Medical GmbH anchors its position through specialized clinical-grade photoacoustic-ultrasound platforms for dermatology and oncology. Seno Medical Instruments differentiates via dedicated breast imaging systems that navigate the regulatory pathway toward commercial reimbursement.
Photoacoustic tomography combines pulsed laser excitation with ultrasonic detection to generate high-resolution optical absorption maps of biological tissue, typically operating at near-infrared wavelengths between 680 and 1064 nanometers for deep-tissue penetration. The technology serves primarily as a non-invasive diagnostic tool for visualizing hemoglobin concentration, oxygen saturation, and exogenous contrast agents in clinical and preclinical settings. Laser-based systems command the largest installed base among technology segments, while microwave-photoacoustic configurations represent the fastest-expanding category for deep-brain research applications. Oncology applications absorb the majority of current procurement budgets, though cardiovascular imaging is emerging as a high-margin segment where functional parameters like plaque lipid content drive premium pricing. Hospitals constitute the dominant end-user channel, yet research laboratories sustain the highest replacement rates as principal investigators upgrade from single-wavelength to multi-spectral platforms.
The FDA oversees premarket notification and breakthrough device pathways for photoacoustic imaging systems in the United States, while the EMA's Medical Device Regulation governs clinical adoption across European member states. Japan's PMDA maintains distinct technical standards for laser safety classification that shape product localization requirements for Asian market entry. Stakeholders must monitor evolving reimbursement coding decisions by national health technology assessment bodies, as definitive procedure codes remain the critical unlock for volume deployment beyond research settings.
Market Dynamics
The FDA's breakthrough device designation pathway is compressing clinical validation timelines for photoacoustic imaging systems, while reimbursement coding decisions by CMS and analogous bodies in Germany and Japan determine whether procurement escapes research-only budgets. This regulatory velocity mismatch against payer adoption creates the central structural tension.
Growth Catalysts
- Oncology Department Expansion:Academic medical centers in the United States are deploying photoacoustic platforms for intraoperative tumor margin assessment, replacing frozen-section pathology workflows in select procedures.
- Reimbursement Framework Maturation:Germany's Institut für das Entgeltsystem im Krankenhaus (InEK) is evaluating procedure codes for hybrid photoacoustic-ultrasound examinations, unlocking hospital budget allocation.
- Laser Source Cost Curve:Solid-state laser manufacturers are achieving economies of scale in near-infrared diode production, reducing system bill-of-materials for original equipment manufacturers.
Market Restraints
- Input Concentration Risk:High-performance acoustic transducers rely on single-crystal piezoelectric materials sourced from limited specialty ceramic foundries in Japan and Germany.
- Technical Depth Limitation:Tissue optical scattering at wavelengths below 700 nanometers restricts functional imaging penetration to approximately three centimeters in most clinical scenarios.
- Substitute Modality Pressure:Contrast-enhanced ultrasound and functional MRI maintain entrenched reimbursement codes and radiologist familiarity for vascular mapping applications.
Strategic Opportunities
- Cardiovascular White Space:Lipid-rich plaque characterization in coronary and carotid arteries represents an underpenetrated application where photoacoustic spectroscopy differentiates from intravascular ultrasound.
- Technology Convergence:Integration of photoacoustic detection with robotic surgical platforms enables real-time tissue feedback during minimally invasive oncologic resections.
- Research-to-Clinical Channel:Direct-to-hospital sales models are displacing traditional distributor networks for multi-spectral platform upgrades in principal investigator laboratories.
Industry Challenges
- Specialized Workforce Scarcity:Biomedical engineers trained in both laser safety protocols and acoustic signal processing remain concentrated at fewer than twelve academic institutions worldwide.
- Multi-Jurisdictional Certification Burden:Laser safety classification standards diverge between FDA 21 CFR 1040, IEC 60825, and Japan's JIS C 6802, requiring redundant testing protocols for global product launches.
- Legacy PACS Integration Friction:Hospital information technology departments resist DICOM conformance modifications needed to accommodate photoacoustic-specific metadata fields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoacoustic Tomography Market |
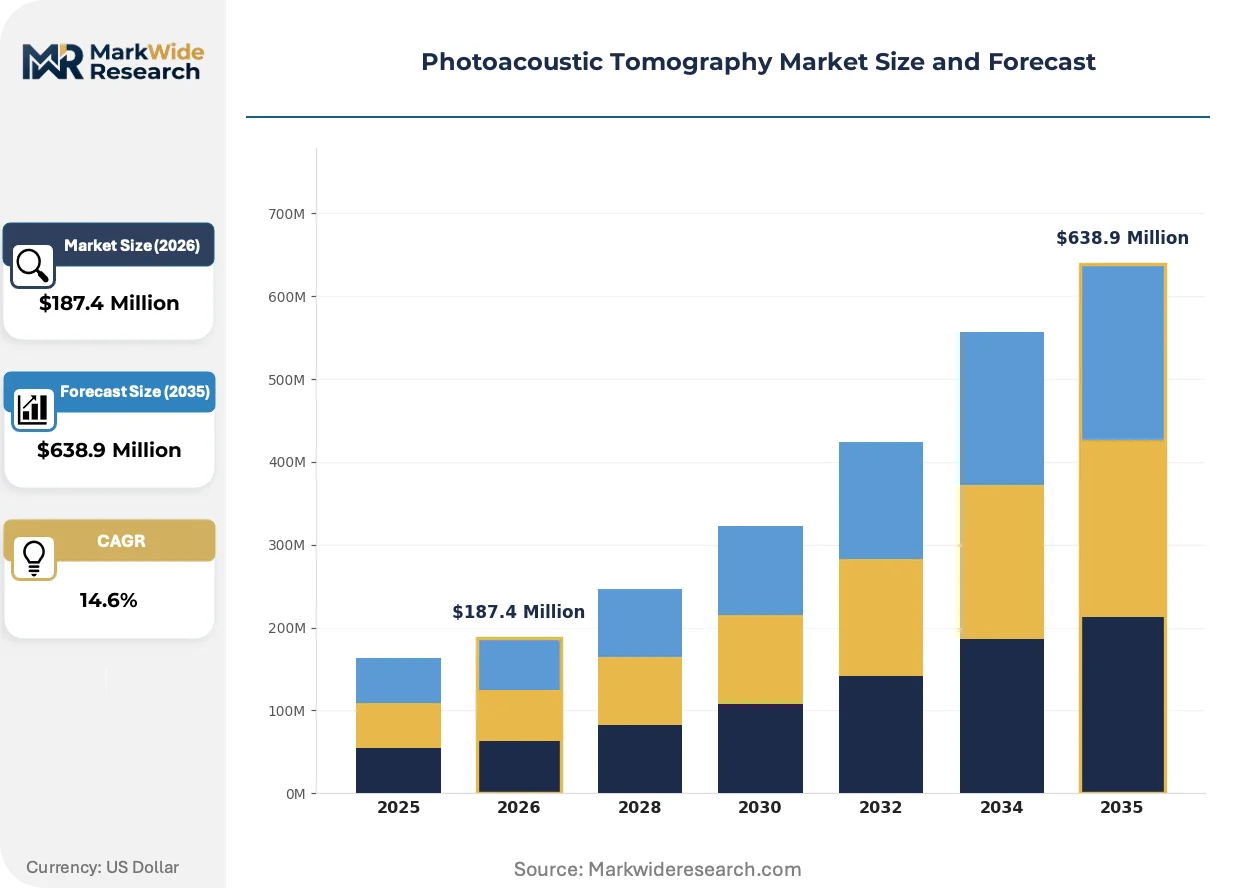
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasound, Microwave, Laser, Radiofrequency Application: Oncology, Cardiovascular, Neurology, Orthopedics End User: Hospitals, Diagnostic Centers, Research Laboratories, Clinics Product Type: Imaging Systems, Software, Accessories, Consumables |
| Companies Covered | FUJIFILM VisualSonics Inc., Seno Medical Instruments, Advantest Corporation, iThera Medical GmbH, TomoWave Laboratories, Inc., Kibero GmbH, OPOTEK LLC, illumiSonics Inc., Aspectus GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoacoustic Tomography Market Evolving Landscape
Multi-spectral acquisition protocols are displacing single-wavelength systems across both preclinical and clinical installed bases, while regulatory science investments by dominant vendors reshape competitive differentiation around real-world evidence generation rather than hardware specifications alone.
Multi-spectral photoacoustic imaging is decomposing the functional limitation of single-wavelength systems by enabling simultaneous hemoglobin, oxygen saturation, and exogenous contrast agent quantification. Oncology departments at tertiary referral centers are adopting these platforms for treatment response monitoring, compressing the competitive moat between research-grade and clinical-grade system categories.
Japan's PMDA revised its laser medical device guidance in 2023 to streamline technical documentation requirements for near-infrared photoacoustic systems, reducing premarket submission preparation timelines by approximately six months for compliant manufacturers. Domestic system integrators are responding by accelerating product localization for Asian market entry, while European manufacturers face renewed pressure to harmonize quality management systems with both MDR and PMDA standards.
Hospital procurement committees are unbundling capital equipment acquisition from multi-year service contracts, forcing original equipment manufacturers to compete on discrete maintenance event pricing rather than bundled lifecycle packages. This pattern is most visible in United States academic medical centers where shared instrumentation grant funding creates fragmented purchasing authority across departmental silos.
Photoacoustic Tomography Market Segmentation
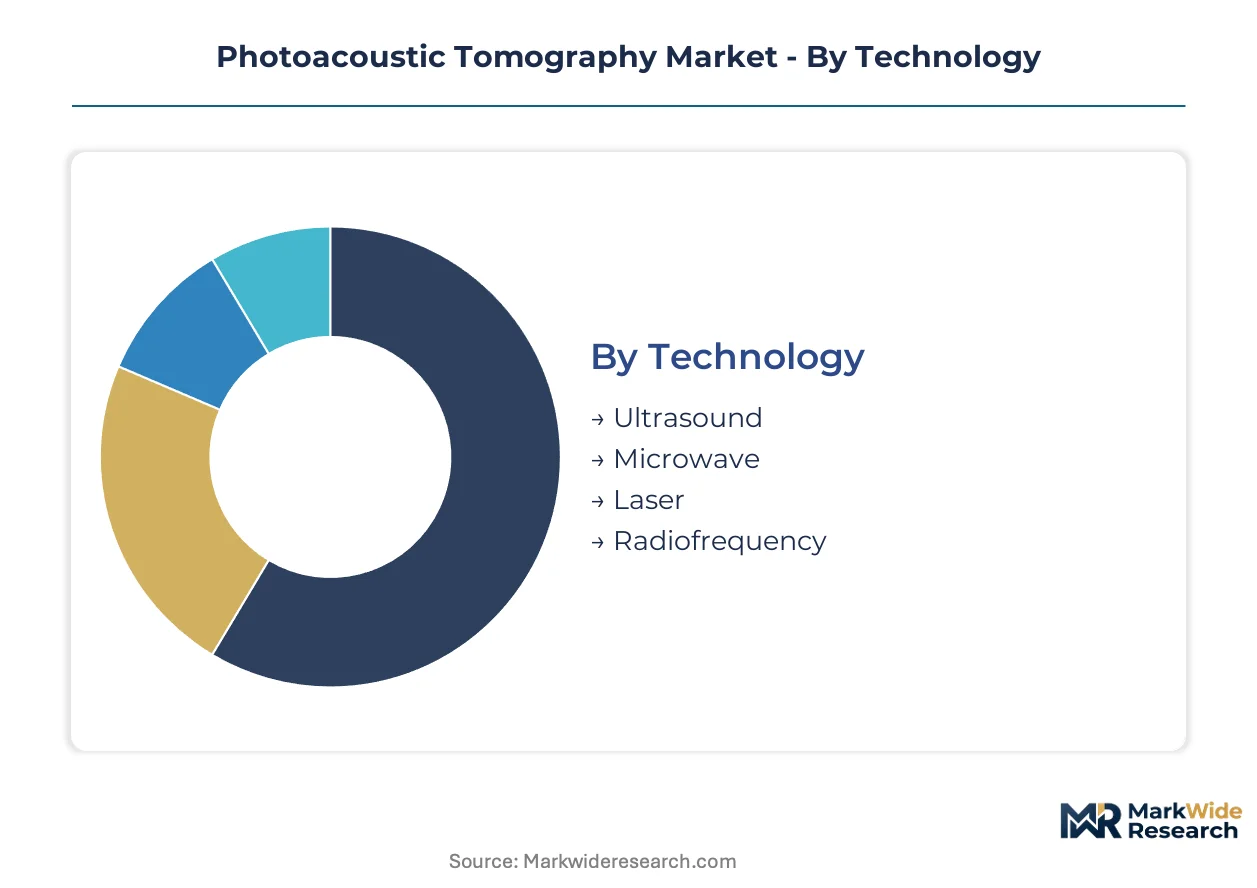
Photoacoustic tomography procurement patterns diverge sharply across technology platforms and clinical settings. Understanding these segment boundaries reveals where capital deployment concentrates and which application areas command premium pricing.
Technology:
Laser-based platforms anchor domestic demand in the United States, Germany, and Japan, while microwave configurations find stronger uptake in export markets pursuing deep-tissue research applications.
- Laser:Near-infrared diode systems operating between 680 and 1064 nanometers generate optical absorption maps through pulsed excitation. United States academic medical centers deploy these platforms for intraoperative tumor margin assessment, replacing frozen-section pathology in select oncologic procedures.
- Microwave:These configurations penetrate deeper biological tissue by employing electromagnetic excitation rather than optical wavelengths. Research institutions in Asia-Pacific markets favor microwave-photoacoustic systems for deep-brain imaging studies where optical scattering limits conventional approaches.
- Ultrasound:Hybrid platforms combine photoacoustic detection with conventional ultrasonic imaging in integrated hardware.
- Radiofrequency:Specialized systems serve preclinical research settings requiring alternative excitation modalities.
Laser platforms hold the largest share; momentum sits with microwave configurations for neuroscience applications.
Application:
Margin profiles vary substantially across clinical domains, with oncology commanding the steepest equipment premiums and cardiovascular emerging as a high-value expansion target.
- Oncology:Tertiary referral centers utilize multi-spectral photoacoustic imaging for treatment response monitoring and surgical guidance. German hospital procurement committees allocate dedicated budgets for hybrid photoacoustic-ultrasound examinations as InEK evaluates permanent procedure codes.
- Cardiovascular:Intravascular and carotid applications target lipid-rich plaque characterization through spectroscopic differentiation. Japanese medical device distributors report rising inquiries for coronary imaging systems that distinguish lipid content from fibrous cap tissue.
- Neurology:Deep-brain functional mapping drives demand in academic research consortia.
- Orthopedics:Bone and joint applications remain concentrated in specialized musculoskeletal imaging centers.
Oncology absorbs the dominant procurement volume; cardiovascular imaging is climbing the fastest as a revenue expansion vector.
End User:
Customer sophistication tiers separate research laboratories with rapid upgrade cycles from hospital capital committees with extended depreciation horizons.
- Hospitals:United States academic medical centers unbundle capital acquisition from service contracts, forcing discrete maintenance pricing across departmental silos with fragmented purchasing authority.
- Research Laboratories:Principal investigators sustain the highest replacement rates as they migrate from single-wavelength to multi-spectral platforms, often leveraging shared instrumentation grant funding.
- Diagnostic Centers:Outpatient imaging facilities prioritize DICOM-compliant systems for PACS integration.
- Clinics:Smaller dermatology and primary care settings concentrate in reimbursed procedure markets.
Hospitals represent the largest installed base; research laboratories are gaining share fastest through accelerated refresh cycles.
Product Type:
Hardware margins compress as software and consumable revenue streams attract strategic investment from platform vendors.
- Imaging Systems:Integrated photoacoustic-ultrasound platforms dominate clinical procurement, with FUJIFILM VisualSonics and iThera Medical anchoring distinct market tiers through vertical transducer fabrication and specialized clinical configurations respectively.
- Software:Multi-spectral reconstruction algorithms and AI-assisted diagnostic tools command recurring licensing revenue from hospital IT departments.
- Accessories:Specialized transducer arrays and optical coupling gels support system customization.
- Consumables:Exogenous contrast agents and single-use acoustic coupling materials generate repeat purchase volume.
Imaging systems retain the dominant revenue share; software is expanding most quickly as vendors pivot toward subscription monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where reimbursement frameworks for hybrid imaging are most developed, while United States procurement remains fragmented across academic medical center departmental silos.
United States
Oncology departments at academic medical centers drive system deployment for intraoperative tumor margin assessment. The FDA's breakthrough device designation pathway compresses clinical validation timelines for novel photoacoustic modalities. Boston and San Francisco clusters host principal investigator laboratories with accelerated refresh cycles from single-wavelength to multi-spectral platforms.
Germany
Hospital procurement committees allocate dedicated budgets for hybrid photoacoustic-ultrasound examinations. The Institut für das Entgeltsystem im Krankenhaus evaluates permanent procedure codes to unlock hospital budget allocation. Munich and Heidelberg anchor specialized clinical-grade platform development for dermatology and oncology applications.
Japan
Domestic system integrators accelerate product localization following PMDA's 2023 laser medical device guidance revision. Japan's distinct JIS C 6802 laser safety classification standards shape product localization requirements for Asian market entry. Tokyo and Osaka medical device distributors report rising inquiries for coronary imaging systems.
China
Research institutions pursue deep-brain imaging studies where microwave-photoacoustic configurations penetrate beyond optical scattering limits. The country's national medical device regulator maintains evolving technical standards for laser safety classification. Shanghai and Beijing academic consortia sustain demand for deep-tissue research applications.
United Kingdom
Tertiary referral centers evaluate multi-spectral platforms for treatment response monitoring in oncologic workflows. The Medicines and Healthcare products Regulatory Agency aligns with EMA Medical Device Regulation standards for clinical adoption. London and Cambridge research laboratories concentrate preclinical imaging system deployment.
Photoacoustic Tomography Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in photoacoustic tomography. Vertically integrated laser-source manufacturers command premium positioning through captive transducer fabrication, while system integrators compete on modular platform configurability. The vendor base separates into three strategic archetypes: preclinical imaging specialists, clinical-grade platform developers, and component suppliers. Competitive moves center on regulatory science investments for real-world evidence generation and direct-to-hospital sales model displacement of traditional distributor networks.
Within the clinical-grade platform tier, iThera Medical GmbH and Seno Medical Instruments occupy distinct positioning through specialized application focus. FUJIFILM VisualSonics Inc. anchors the preclinical imaging segment. These three represent the dominant competitive anchors shaping procurement patterns across hospital capital committees and principal investigator laboratories.
| Leading Market Players |
|---|
| FUJIFILM VisualSonics Inc. |
| Seno Medical Instruments |
| Advantest Corporation |
| iThera Medical GmbH |
| TomoWave Laboratories, Inc. |
| Kibero GmbH |
| OPOTEK LLC |
| illumiSonics Inc. |
| Aspectus GmbH |
| Others |
Value Network & Pricing Analysis
Multi-year service contracts with capacity reservation clauses dominate procurement between original equipment manufacturers and academic medical centers, locking in laser source allocation and insulating installed-base pricing from spot-market volatility in single-crystal piezoelectric materials.
Pricing Analysis
The customization-premium spread between configured-to-order multi-spectral platforms and standard single-wavelength systems runs wide across hospital procurement tiers. Subscription-based software licensing for AI-assisted diagnostic tools is displacing perpetual licenses, while hardware margins compress due to unbundled service contract negotiations. Price differentiation hinges on FDA breakthrough device designation status and vertical integration depth in transducer fabrication. Cost compression in solid-state laser diodes is intensifying as near-infrared manufacturers achieve production scale, though high-performance acoustic arrays maintain pricing power due to limited specialty ceramic foundry capacity. Research laboratories exhibit highest price sensitivity due to fragmented grant funding, while tertiary oncology departments prioritize clinical validation over capital cost.
Supply Chain Analysis
Inventory buffers for single-crystal piezoelectric materials extend lead times beyond six months as Japanese and German specialty ceramic foundries operate at constrained capacity. Laser diode production concentrates in the United States, Japan, and Germany, while microwave excitation components source primarily from Chinese and South Korean electromagnetic component suppliers. The supply chain rests on high-purity optical substrates, precision-machined acoustic housings, and medical-grade laser safety interlocks. Single-source vulnerability in piezoelectric material supply creates procurement risk for system integrators lacking backward integration. Distribution runs through direct-to-hospital sales teams for clinical-grade platforms and specialized research distributors for preclinical configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoacoustic tomography is approaching a platform-economics inflection where DICOM conformance and PACS interoperability determine vendor lock-in, shifting competitive advantage from hardware specifications to software ecosystem integration.
For Market Incumbents: Consolidate control over transducer fabrication through captive supply agreements with Japanese specialty ceramic foundries, insulating against input concentration risk. Deepen regulatory science investments for real-world evidence generation to defend reimbursement coding advantages against emerging entrants pursuing FDA breakthrough device fast-tracks. Prioritize backward integration into laser source manufacturing to capture margin compression from solid-state diode cost curves. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers the most penetrable regulatory pathway for cardiovascular imaging platforms targeting lipid-rich plaque characterization. White-space opportunities concentrate in microwave-photoacoustic configurations for deep-brain research consortia and robotic surgical integration for real-time oncologic resection guidance. Go-to-market execution should emphasize direct-to-hospital sales models displacing traditional distributor networks in academic medical center clusters. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated platform developers with captive transducer fabrication and established regulatory affairs infrastructure. Long-term viability across the projection horizon favors vendors bridging preclinical research installed bases toward clinical reimbursement rather than pure hardware manufacturers facing software commoditization. The signal to monitor is permanent procedure code establishment by Germany's InEK and analogous national health technology assessment bodies, which would trigger hospital budget allocation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates clinical validation timelines for novel photoacoustic modalities seeking reimbursement codes. |
| Multi-Spectral Platform Launch | Enables simultaneous hemoglobin and oxygen saturation quantification for oncology treatment monitoring. |
| Backward Integration into Laser Sources | Captures margin compression from solid-state near-infrared diode production scale economies. |
| Hospital System Partnership | Secures preferred vendor status in academic medical centers unbundling capital from service contracts. |
| Software Companion Development | Generates recurring licensing revenue from AI-assisted diagnostic tools and PACS integration modules. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital purchasing committee chairs, laser safety officers, and principal investigators anchored the qualitative base. Primary interviews across these stakeholder categories combined with secondary validation from FDA 510(k) filings, PMDA laser medical device guidance documents, hospital procurement databases, and CMS reimbursement coding decisions. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates across technology platforms and application segments.
Sensitivity analysis tested forecast robustness against laser source cost curve trajectories, reimbursement coding timeline scenarios, and academic research funding volatility. The analytical framework modeled segmentation across technology type, clinical application, end-user channel, and regional regulatory cluster throughout the projection horizon. CAGRs derived from weighted average growth contributions across these dimensions, incorporating procedure code establishment probabilities and replacement cycle dynamics for single-wavelength to multi-spectral platform upgrades.
Decision-makers should treat outputs as directional under assumptions of stable regulatory pathways for hybrid imaging modalities and continued academic medical center capital deployment; material deviation in reimbursement coding timelines or research funding priorities would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Low-Light Imaging Market
Imaging
Event Camera Market
Imaging
Industrial Computed Tomography Market
Imaging
Global Panoramic Camera Market
Imaging
Thermal Imaging Market
Imaging
Facial Recognition Machine Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Japan Digital X-Ray Market
Imaging
Video Capture Card Market
Imaging
Light Field Market
Imaging
Document Imaging Market
Imaging
Camera Stabilizer Market
Imaging
Camera Technology Market
Imaging
Cooled IR Camera Market
Imaging
Compact Camera Module Market