
 North America Instant Noodles Market | 2026-2036
North America Instant Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Instant Noodles Market Intelligence
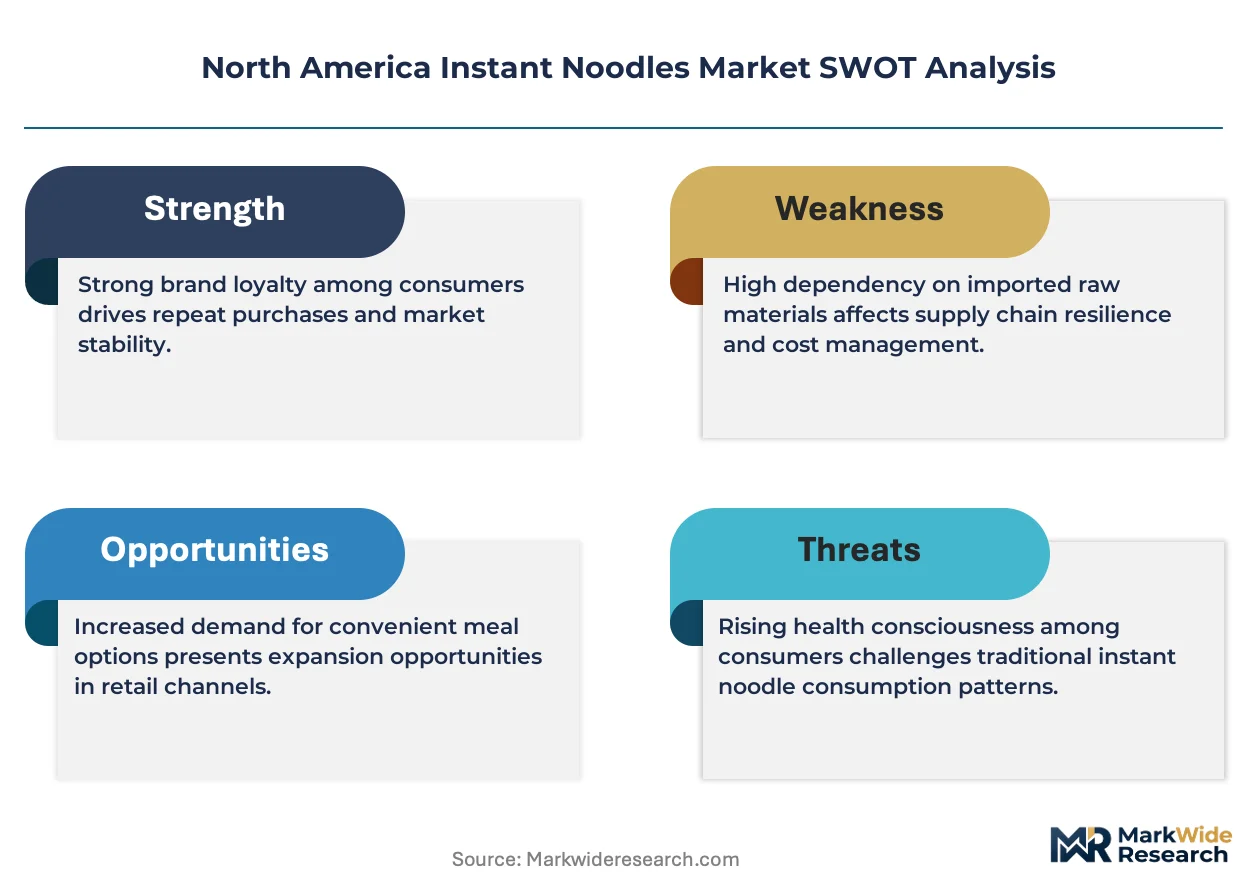
Buyer concentration across the North America Instant Noodles Market is shifting from traditional grocery channels toward convenience stores and online retail platforms. Nissin Foods Holdings Co., Ltd. leverages its cup noodle manufacturing scale to dominate the single-serve format segment. Maruchan Inc. anchors shelf presence through deep distribution partnerships with mass retailers across the United States. Nongshim Co., Ltd. differentiates through spicy flavor innovation that captures growing Korean-food interest among younger consumers.
Instant noodles comprise wheat-based alkaline noodles that undergo steaming, oil-frying or hot-air drying, then packaging with dehydrated seasoning and oil packets for reconstitution in boiling water within three minutes. Cup noodles lead the product type segment due to built-in convenience and minimal cleanup requirements, while stand-up pouches gain traction among sustainability-conscious retailers seeking reduced packaging waste. Block noodles occupy the value-tier position in hypermarkets, whereas instant soup variants command premium placement in specialty Asian grocery channels.
The FDA governs sodium disclosure and nutrient content claims across the United States, while Health Canada enforces front-of-package labeling regulations that pressure sodium reduction in instant noodle formulations. Both frameworks elevate R&D spending toward clean-label seasonings and alternative sodium technologies. Stakeholders must monitor evolving trans-fat restrictions and single-use packaging bans at the state and provincial level, as these rules will determine which product formats retain shelf access and which require fundamental reformulation investments.
Market Dynamics
Reformulation pressure from sodium disclosure mandates is compressing legacy recipes while opening shelf space for clean-label alternatives across the United States, Mexico, and Canada.
Growth Catalysts
- FDA sodium disclosure rules:Front-of-package labeling requirements accelerate R&D investment into reduced-sodium seasoning technologies and alternative salt substitutes.
- College enrollment corridors:Campus-adjacent convenience stores and meal-plan partnerships create dedicated distribution channels for single-serve cup formats.
- Hot-air drying processes:Non-fried noodle production methods reduce oil content and align with Health Canada's trans-fat restrictions, enabling premium positioning.
Market Restraints
- Wheat price volatility:Input cost swings for hard red winter wheat squeeze margin structures across block noodle value tiers.
- Single-use packaging bans:Provincial regulations in British Columbia and state-level restrictions in California threaten cup noodle format viability.
- Fresh prepared meal substitution:Refrigerated noodle bowls and hot-bar offerings at mass retailers capture convenience-seeking buyers.
Strategic Opportunities
- Mexico urban corridors:Guadalajara and Monterrey metro areas show underpenetrated distribution relative to per-capita consumption potential.
- Clean-label seasonings:Health Canada front-of-package regulations create first-mover advantage for brands with simplified ingredient panels.
- Direct-to-campus subscriptions:Semester-based meal kit partnerships bypass traditional grocery slotting fees and build recurring revenue.
Industry Challenges
- Sodium reduction R&D timelines:Reformulation cycles for clean-label seasonings extend product development windows beyond traditional 12-month benchmarks.
- Legacy equipment retooling:Transition from oil-frying to hot-air drying lines demands capital deployment that mid-tier manufacturers struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Instant Noodles Market |
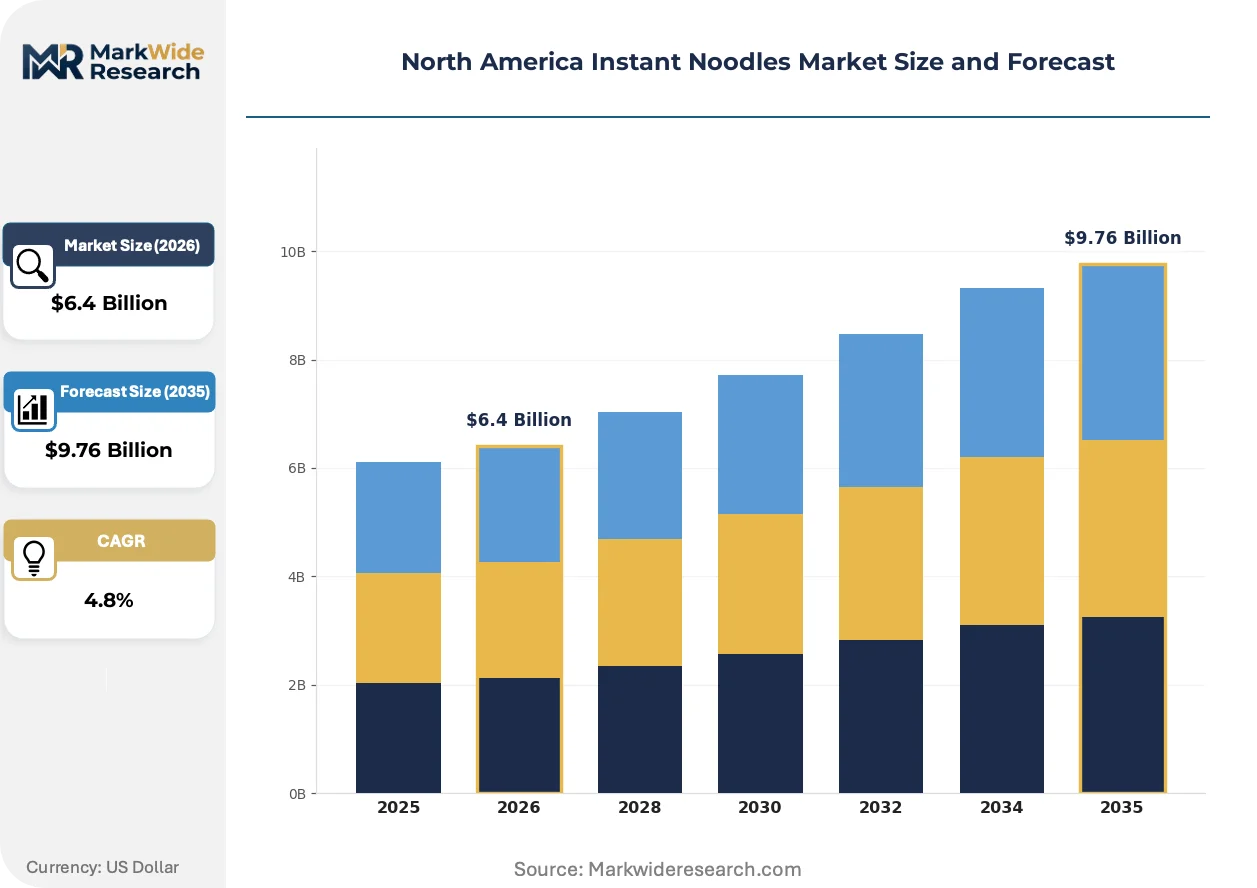
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cup Noodles, Stand-up Pouches, Instant Soup, Block Noodles Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Hypermarkets Flavor Profile: Spicy, Chicken, Beef, Vegetarian Packaging Type: Plastic, Paper, Foam, Aluminum |
| Companies Covered | Nestlé S.A., Samyang Foods Co., Ltd., Nissin Foods Holdings Co., Ltd., Ajinomoto Co., Ltd., Toyo Suisan Kaisha, Ltd., Maruchan Inc., Campbell Soup Company, Unilever PLC, Nongshim Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Instant Noodles Market Strategic Shifts & Innovations
Product architecture is splitting between convenience-maximizing formats and sustainability-compliant alternatives, with regulatory pressure accelerating both tracks simultaneously.
Hot-air drying technology is unifying production efficiency with health-positioning requirements. Equipment suppliers in the United States report 40% capacity expansion orders from manufacturers seeking non-fried output. This convergence is compressing the cost gap between traditional fried noodles and premium-positioned alternatives.
Health Canada's front-of-package sodium labeling regulations force disclosure thresholds that disqualify standard seasoning formulations. Manufacturers are responding with potassium-chloride blends and umami-enhancing yeast extracts. The single-serve cup segment faces the steepest compliance burden due to concentrated serving sizes.
Campus procurement offices are consolidating vendor relationships into exclusive semester-length contracts. This channel compression displaces fragmented convenience store distribution with direct institutional supply. The pattern is most visible across large public university systems in the United States, where dining services seek simplified SKU management.
North America Instant Noodles Market Segmentation
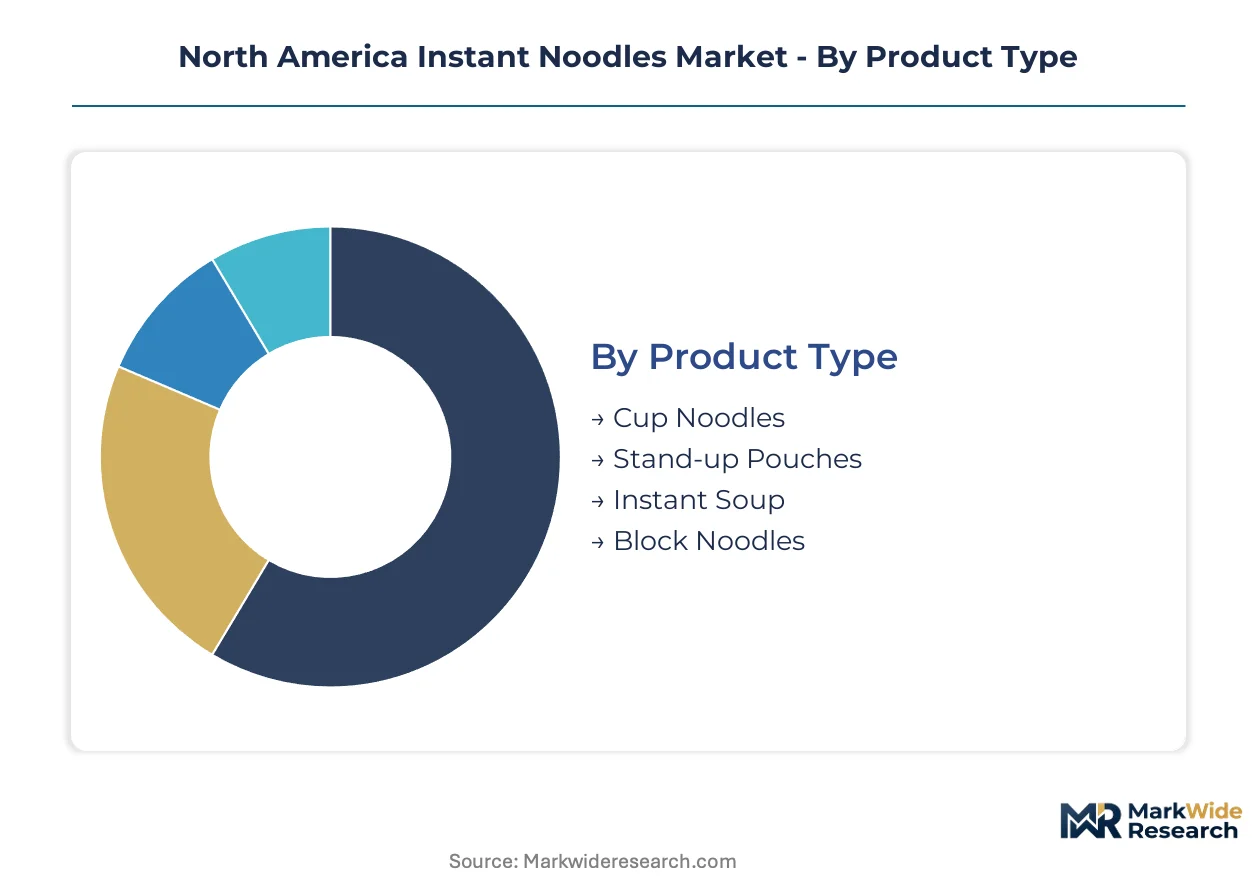
Format selection in the North America Instant Noodles Market determines shelf placement economics and regulatory exposure. Buyers trade off preparation speed against packaging waste concerns, while retailers calibrate assortment depth to local sodium labeling enforcement intensity.
Product Type:
Convenience expectations and cleanup tolerance drive format selection across college, professional, and household buyer pools.
- Cup Noodles:Self-contained vessels integrate dehydrated noodles, seasoning, and oil within a single heat-stable container requiring only hot water addition. Campus-adjacent convenience stores in the United States stock cup formats as default single-serve solutions, though California and British Columbia packaging bans threaten this positioning.
- Stand-up Pouches:Flexible laminated structures reduce material weight by approximately 60 percent versus rigid cup equivalents while maintaining barrier properties against moisture and oxygen. Sustainability-conscious retailers in Canada allocate expanded shelf space to pouch formats ahead of single-use plastic restrictions.
- Instant Soup:Broth-forward formulations emphasizing liquid base over noodle mass, typically merchandised in premium placement within specialty Asian grocery channels.
- Block Noodles:Compressed rectangular nests packaged with separate seasoning sachets, occupying value-tier positioning in United States hypermarkets where price-per-ounce drives assortment decisions.
Cup Noodles leads on scale; Stand-up Pouches leads on momentum.
Distribution Channel:
Channel economics in the North America Instant Noodles Market concentrate margin capture between slotting-fee-heavy mass retail and direct-to-consumer digital routes.
- Supermarkets:Traditional grocery chains maintain broad flavor and format assortments through centralized category management, with sodium-reduced SKUs gaining facings in response to FDA disclosure mandates.
- Online Retail:Digital platforms enable subscription-based replenishment and bulk purchasing that bypasses physical shelf constraints, particularly for specialized Korean and Japanese import varieties unavailable in conventional grocery.
- Convenience Stores:Limited assortment focused on cup formats and recognized domestic brands, with location strategy targeting highway corridors and university-adjacent trade areas.
- Hypermarkets:High-volume, low-margin block noodle sales driven by family-pack sizing and promotional pricing cycles.
Supermarkets dominate absolute volume; Online Retail shows the steepest expansion trajectory.
Flavor Profile:
Taste preference mapping in the North America Instant Noodles Market reveals generational divergence between established domestic profiles and ethnically specific imports.
- Spicy:Chili-oil and capsaicin-forward formulations drawing from Korean and Sichuan culinary traditions, capturing younger consumer cohorts through social media visibility and heat-level marketing.
- Chicken:Mild, poultry-based seasoning systems representing the historical volume base across United States mass retail, now facing reformulation pressure for sodium reduction.
- Beef:Rich, umami-heavy profiles maintaining stable demand among traditional instant noodle consumers in Mexico and older United States demographics.
- Vegetarian:Mushroom and vegetable-based alternatives addressing lacto-ovo and plant-forward dietary requirements, with Health Canada front-of-package regulations accelerating clean-label development.
Chicken retains the largest buyer base; Spicy gains share fastest.
Packaging Type:
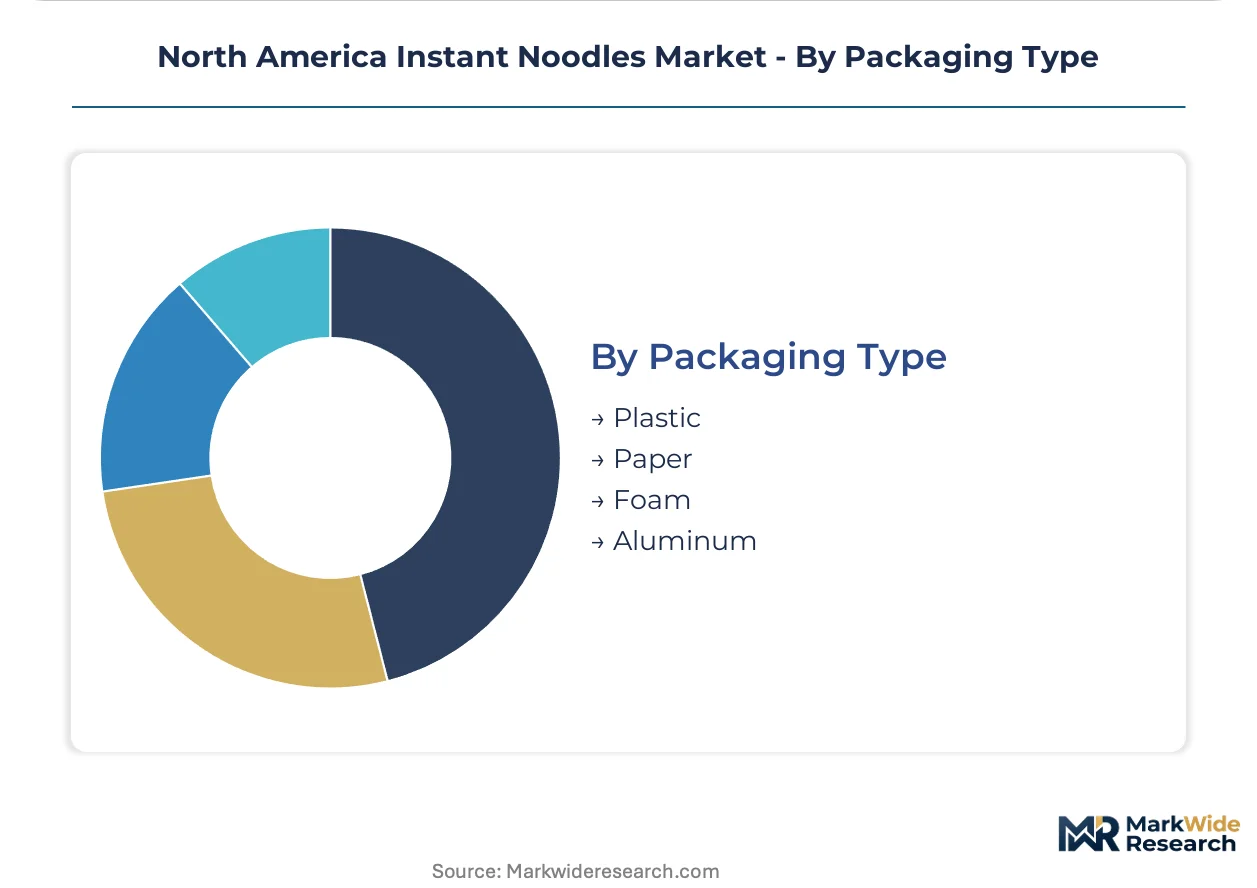
Material selection in the North America Instant Noodles Market increasingly reflects compliance cost accounting for pending extended producer responsibility frameworks.
- Plastic:Polypropylene and polyethylene structures offering moisture barrier and microwave compatibility, now requiring reformulation for recyclability claims under emerging state-level mandates.
- Paper:Fiber-based alternatives with polymer lining for liquid containment, positioned for regulatory advantage in jurisdictions advancing single-use plastic restrictions.
- Foam:Expanded polystyrene cup bodies facing active phase-out in California, New York, and British Columbia due to environmental persistence concerns.
- Aluminum:Metallized films and foil lids providing superior oxygen barrier for premium and import varieties with extended shelf-life requirements.
Plastic maintains installed manufacturing scale; Paper climbs the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
College students and young professionals across the United States, Canada, and Mexico anchor geographic demand concentration. Campus-adjacent convenience stores and meal-plan partnerships create dedicated distribution corridors for single-serve formats. Metropolitan density in university towns and urban professional hubs determines regional sales velocity.
United States
Campus procurement offices at large public university systems consolidate vendor relationships into exclusive semester-length contracts. FDA sodium disclosure mandates pressure reformulation toward reduced-salt recipes. California's single-use packaging bans and trans-fat restrictions threaten cup noodle format viability in the nation's largest state market.
Canada
Health Canada front-of-package labeling regulations enforce sodium thresholds that disqualify standard seasoning formulations. Toronto and Vancouver metropolitan areas show concentrated demand among international student populations. British Columbia's provincial single-use plastic restrictions accelerate retailer shift toward stand-up pouch formats.
Mexico
Guadalajara and Monterrey metro areas demonstrate underpenetrated distribution relative to per-capita consumption potential. Domestic regulators monitor sodium content in processed foods with increasing scrutiny. Mexico City anchors national volume through hypermarket block noodle sales and convenience store cup format penetration.
North America Instant Noodles Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across format and flavor positioning tiers. The vendor base organizes around three strategic archetypes: multinational food conglomerates leveraging cross-category distribution, Asian-origin specialists capitalizing on authentic flavor credibility, and domestic mass-market brands optimizing shelf presence through retailer partnerships. Competitive moves concentrate on sodium-reduction R&D licensing and hot-air drying equipment upgrades.
Among Japanese-origin specialists, Nissin Foods Holdings Co., Ltd. and Toyo Suisan Kaisha, Ltd. exemplify the cup noodle manufacturing scale archetype. Nongshim Co., Ltd. anchors the Korean-origin spicy flavor innovation segment that captures younger consumer cohorts through heat-level marketing.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Samyang Foods Co., Ltd. |
| Nissin Foods Holdings Co., Ltd. |
| Ajinomoto Co., Ltd. |
| Toyo Suisan Kaisha, Ltd. |
| Maruchan Inc. |
| Campbell Soup Company |
| Unilever PLC |
| Nongshim Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Hard red winter wheat futures volatility propagates through block noodle value tiers into retail shelf pricing, with flour cost swings compressing margins for mid-tier manufacturers while premium hot-air dried formats absorb input spikes through brand positioning power.
Pricing Analysis
Packaging-integrated cup formats versus component-separated block noodles defines the unbundled-bundled split across North American retail. Three-tier pricing structure across premium, standard, and economy levels tracks preparation method—hot-air dried non-fried SKUs command shelf premiums over oil-fried equivalents, while sodium-reduced clean-label variants extract additional markups through Health Canada and FDA compliance positioning. Pricing pressure stems from wheat commodity volatility and single-use packaging compliance costs in California and British Columbia. College students exhibit highest price sensitivity, gravitating toward multi-pack block formats, whereas young professionals absorb premiums for cup convenience and ethnic import authenticity.
Supply Chain Analysis
Cross-border freight costs from Midwest grain elevators to West Coast manufacturing clusters and Mexican distribution centers anchor logistics expenditure for wheat flour and dehydrated seasoning inputs. Production concentrates in the United States, Mexico, and South Korea—domestic manufacturers source hard red winter wheat from Kansas and Nebraska elevators, while Korean-origin specialists import pre-mixed seasoning bases through Port of Long Beach corridors. Supply chain risk centers on tariff exposure for aluminum foil lid components and expanded polystyrene cup bodies facing phase-out timelines. Distribution runs through mass retailer centralized category management, with direct-to-campus institutional contracts bypassing traditional slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Instant Noodles Market compounds steadily as regulatory reformulation mandates perpetuate R&D spending cycles that defend incumbent positions while raising barriers for undercapitalized challengers.
For Market Incumbents: Hedge sodium reduction compliance costs through dual-track R&D partnerships with alternative salt technology suppliers and umami-enhancing yeast extract developers. Acquire hot-air drying equipment capacity ahead of Health Canada trans-fat enforcement expansion. Secure exclusive semester-length campus procurement contracts before channel consolidation locks out secondary brands. For New Entrants and Emerging Players: Launch via direct-to-campus subscription models that bypass supermarket slotting fee barriers and build recurring revenue visibility. Target Guadalajara and Monterrey metro corridors where per-capita consumption potential exceeds current distribution penetration. Lead with clean-label seasoning simplicity that satisfies Health Canada front-of-package disclosure thresholds ahead of legacy brand reformulation timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack capital access for oil-frying to hot-air drying line conversions. The 5-10 year viability window favors equipment-retrofitted specialists with institutional channel lock-in. Watch for California and British Columbia single-use packaging ban enforcement acceleration as inflection signal for format mix restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Sodium Reduction R&D Partnership | Health Canada and FDA disclosure mandates force collaborative seasoning reformulation to retain shelf placement. |
| Hot-Air Drying Equipment Upgrade | Non-fried production lines unlock premium positioning while satisfying trans-fat restrictions across jurisdictions. |
| Direct-to-Campus Subscription Launch | Semester-length institutional contracts bypass grocery slotting fees and establish recurring revenue streams. |
| Clean-Label Seasoning Development | Simplified ingredient panels capture first-mover advantage under front-of-package sodium labeling regulations. |
| Mexico Urban Corridor Expansion | Guadalajara and Monterrey distribution buildout captures underpenetrated consumption potential relative to market size. |
Research Approach
Bottom-up campus procurement and convenience store velocity modeling reconciled against top-down wheat input cost and manufacturing capacity tracking forms the analytical core. Primary interviews with category buyers at mass retailers, supply planners at seasoning suppliers, dining services procurement officers at public university systems, and R&D directors at noodle manufacturers combined with secondary validation from FDA sodium disclosure filings, Health Canada front-of-package regulation drafts, USDA wheat production reports, and Nielsen retail audit data. Triangulation across these sources grounds volume estimates in observed channel flow rather than modeled demand alone.
Input-output matrices map wheat flour, palm oil, seasoning base, and packaging material costs through frying versus hot-air drying production methods into format-specific price tier outputs across the projection horizon. Segmentation dimensions include product type, distribution channel, flavor profile, and packaging material, with CAGRs derived from enrollment-driven campus demand curves and regulatory compliance investment cycles. Forecast inputs incorporate Health Canada sodium threshold enforcement timing and California single-use packaging ban implementation schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated provincial packaging restrictions or wheat commodity spike scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Salad Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Packaged Food Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Canned Beans Market
Packaged Foods
Morning Goods Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Dried Honey Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Canned Goods Market
Packaged Foods
Ready-To-Eat Food Market
Packaged Foods
US Packaged Food Market