
 Canned Beans Market | 2026-2036
Canned Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Beans Market Analytics
Single-serve cup configurations is repositioning household purchasing behavior away from bulk can formats toward portion-controlled convenience. Conagra Brands sustains manufacturing scale across multi-format production lines. Goya Foods dominates Hispanic market shelf space through specialized regional distribution. Bonduelle Group navigates European private-label demand with controlled channel positioning.
Canned beans comprise thermally processed legumes sealed in hermetically sealed containers with internal lacquer coatings, preserved through retort sterilization at temperatures exceeding 121 degrees Celsius to achieve commercial sterility and extended ambient shelf stability. The product serves as a ready-to-use protein and fiber source for food manufacturing and direct consumption. Chickpeas lead volume contribution due to hummus category expansion and plant-based protein formulation demand. Single-serve cups represent the fastest-growing packaging type as convenience-oriented households reduce leftover waste. Standard cans retain mature margin pools through food service procurement scale.
FDA food contact notification requirements and EU REACH compliance on epoxy-based can coatings constrain supplier material choices and elevate qualification costs for new entrants. BIS certification in India and CDSCO food safety standards add parallel compliance layers for export-oriented processors. Stakeholders must monitor evolving regulatory timelines for per- and polyfluoroalkyl substance restrictions in food packaging across multiple jurisdictions.
Market Dynamics
Food service operators are consolidating procurement around shelf-stable protein formats that reduce kitchen labor and standardize portion output. This operational imperative is compressing supplier margins while rewarding multi-format manufacturing scale.
Growth Catalysts
- EU REACH compliance on epoxy coatings:BPA-free lining mandates are accelerating supplier qualification timelines and favoring processors with established regulatory infrastructure.
- Plant-based protein formulation demand:Food manufacturers are integrating chickpea and bean isolates into meat alternatives, pulling volume from traditional retail channels into industrial ingredient supply.
- Latin American protein diversification:Mexican and Brazilian consumers are expanding consumption beyond rice and corn staples, creating new category entry points for shelf-stable legumes.
Market Restraints
- Steel can input cost volatility:Tinplate and aluminum pricing fluctuations compress margin predictability for standard-format producers.
- Retort sterilization capex concentration:Commercial sterility equipment requires substantial capital deployment, limiting new entrant capacity expansion.
- Fresh and frozen legume substitution:Refrigerated supply chain improvements in developed markets are eroding ambient-stable positioning in premium retail tiers.
Strategic Opportunities
- Indian export processing zones:BIS certification infrastructure and FSSAI alignment are enabling duty-advantaged supply to Middle Eastern and African markets.
- Single-serve cup channel innovation:Convenience-oriented households are reducing leftover waste through portion-controlled formats, opening shelf space beyond traditional canned goods aisles.
- CDSCO food safety standard harmonization:Indian regulatory alignment with Codex frameworks is streamlining cross-border qualification for export-oriented processors.
Industry Challenges
- Retort process engineering talent scarcity:Thermal processing expertise is concentrating among legacy operators, constraining new facility commissioning timelines.
- Multi-jurisdiction coating compliance:Parallel FDA notification and EU food contact material rules are extending product qualification cycles and elevating reformulation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Beans Market |
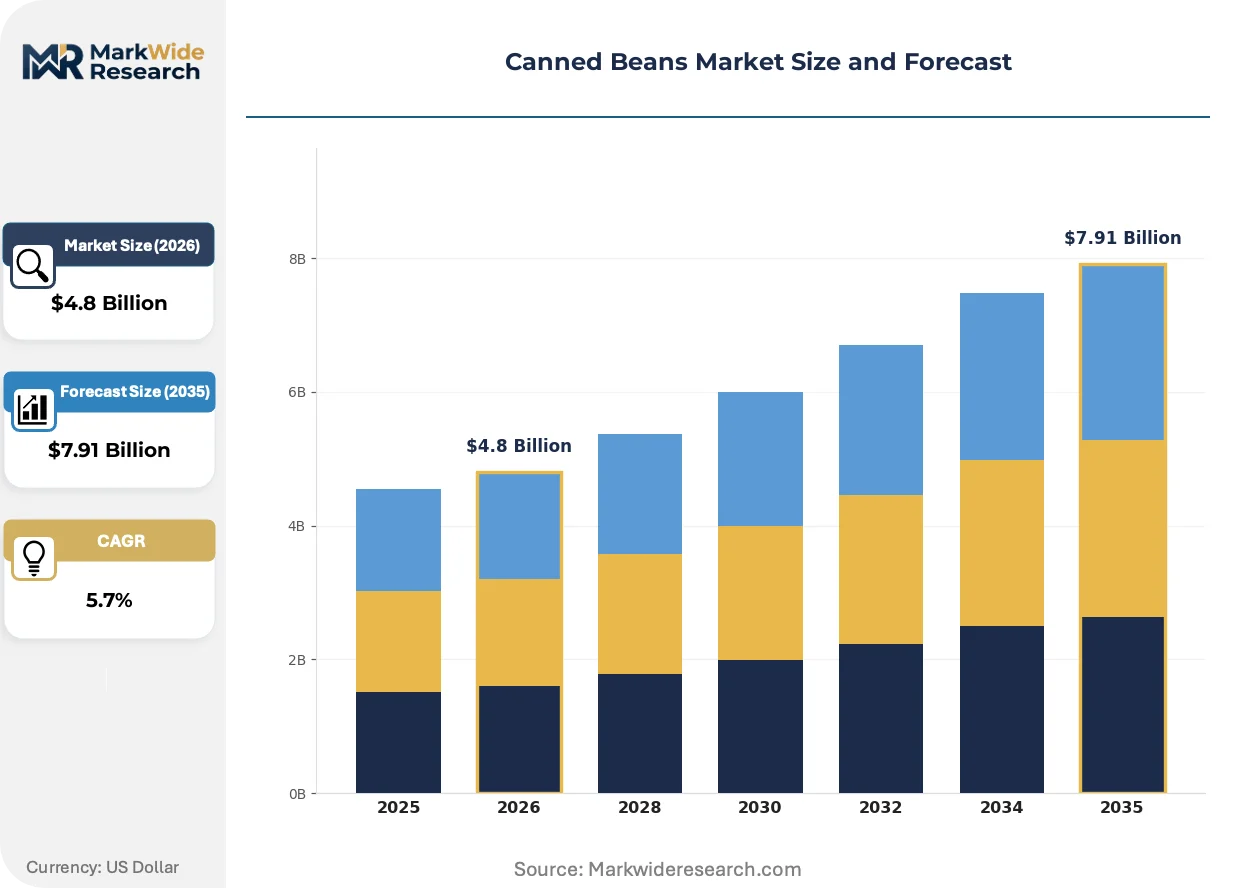
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Beans, Kidney Beans, Pinto Beans, Chickpeas Packaging Type: Standard Cans, Family Size Cans, Single-Serve Cups, Pouches End User: Households, Restaurants, Food Service, Canteens Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | Conagra Brands, Inc., General Mills, Kraft Heinz Company, B&G Foods, Inc., Eden Foods, Inc., Bush Brothers & Company, Del Monte Foods, Inc., Bonduelle Group, Goya Foods, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Beans Market Evolving Landscape
Processing technology and packaging formats are converging to address labor reduction priorities across food service and retail channels simultaneously. Regulatory pressure on coating chemistry is forcing material science investment ahead of mandate timelines.
High-barrier polymer cup technology is expanding into ambient-stable legume packaging. Convenience-oriented retailers are allocating incremental shelf space to single-serve formats that reduce household food waste. This shift is compressing demand for standard 15-ounce can configurations while expanding margin pools for portion-controlled alternatives.
EU REACH restrictions on per- and polyfluoroalkyl substances are accelerating lining material transitions across European supply chains. Food contact notification requirements from FDA are creating parallel compliance obligations for exporters serving both markets. Dual-qualified suppliers are capturing procurement preference from multinational food manufacturers seeking simplified vendor bases.
Food service procurement consolidation is displacing fragmented distributor relationships with direct manufacturer contracts. Large contract feeding operators are negotiating volume commitments against guaranteed supply security and format flexibility. This concentration is most visible in North American institutional feeding channels where labor cost pressures are most acute.
Canned Beans Market Segmentation
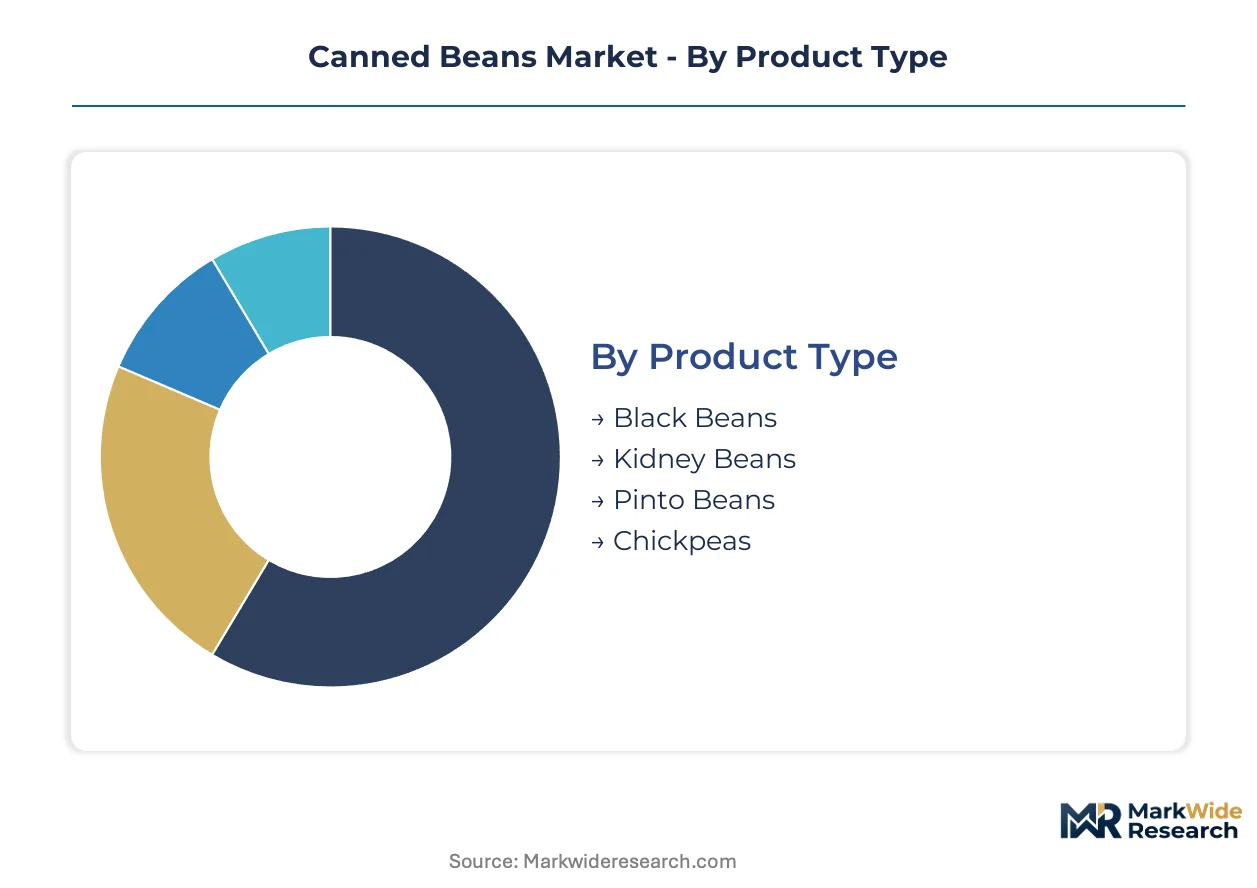
Segmentation in the canned beans market reveals how protein sourcing preferences and operational requirements diverge across buyer types. Food service operators prioritize labor reduction and portion consistency, while households balance convenience against unit economics and storage constraints.
Product Type:
Buyers select legume varieties based on regional cuisine traditions and formulation requirements for downstream processing.
- Chickpeas:These round, beige legumes undergo thermal processing to achieve commercial sterility while maintaining structural integrity for hummus production and plant-based protein isolates. Demand concentrates in North American and European manufacturing channels where food companies formulate meat alternatives and Mediterranean-style prepared foods.
- Black Beans:Small, oval-shaped legumes with dense flesh that holds shape through retort sterilization cycles. Mexican and Brazilian retail markets drive procurement volume as consumers diversify protein intake beyond traditional corn and rice staples.
- Kidney Beans:Large, kidney-shaped red legumes processed for chili formulations and salad applications.
- Pinto Beans:Mottled pink legumes common in refried bean preparations and Latin American household cooking.
Chickpeas lead on scale; black beans lead on momentum.
Packaging Type:
Format selection hinges on consumption occasion, household size, and retail channel placement constraints.
- Single-Serve Cups:High-barrier polymer containers enable ambient shelf stability without traditional metal substrates. Convenience-oriented households in US and UK markets are reducing leftover waste through portion-controlled formats, opening shelf space beyond conventional canned goods aisles.
- Standard Cans:Cylindrical tinplate or aluminum containers with epoxy-based internal lacquer coatings, thermally processed at 121 degrees Celsius. Food service procurement consolidation across North American institutional feeding channels sustains mature margin pools through volume commitments.
- Family Size Cans:Larger-format metal containers targeting multi-person households and bulk preparation scenarios.
- Pouches:Flexible laminated film structures offering reduced shipping weight and retail display flexibility.
Standard cans dominate procurement tonnage; single-serve cups are climbing the fastest.
End User:
Operational priorities separate commercial buyers from household purchasers around labor inputs and menu engineering needs.
- Restaurants:Full-service and limited-service operators requiring consistent portion output and reduced back-of-house preparation time. US and Canadian chains are consolidating procurement around shelf-stable protein formats that compress supplier margins while demanding multi-format manufacturing flexibility.
- Households:Individual and family consumers making trade-offs between unit cost, storage convenience, and preparation speed. Single-serve cup adoption is accelerating among smaller households seeking waste reduction.
- Food Service:Contract feeding operators managing institutional cafeterias, hospitals, and corporate dining facilities.
- Canteens:Military, educational, and industrial feeding operations with high-volume, cost-sensitive procurement profiles.
Restaurants command the steepest expansion trajectory; households anchor absolute volume.
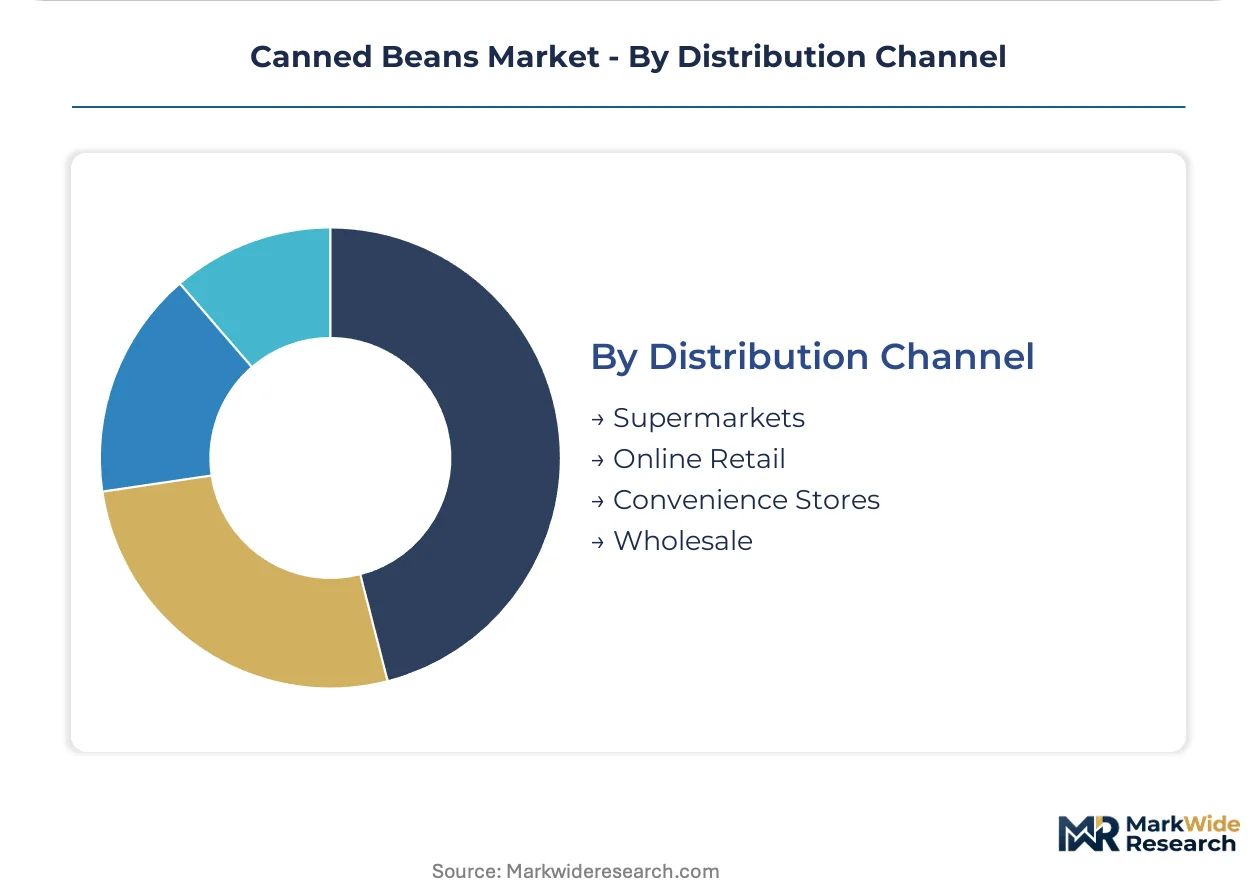
Distribution Channel:
Channel selection reflects buyer urgency, basket composition, and price sensitivity across consumption occasions.
- Supermarkets:Full-assortment retail environments with dedicated canned goods aisles and promotional calendar dependencies. Mexican and Brazilian chains are expanding shelf-stable legume facings as consumer protein diversification accelerates beyond traditional staples.
- Online Retail:Digital platforms enabling subscription models and bulk purchasing for pantry stocking. Convenience-oriented fulfillment is gaining traction among urban households seeking delivery efficiency.
- Convenience Stores:Limited-assortment outlets targeting immediate consumption and emergency replenishment scenarios.
- Wholesale:Volume-focused distributors serving food service and institutional buyers with case-lot minimums.
Supermarkets maintain the widest reach; online retail shows the sharpest growth curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial canning of legumes originated in the United States during the late nineteenth century, establishing processing infrastructure that would later diffuse to Europe and Latin America. Today, demand concentrates in markets where protein diversification intersects with established retail distribution networks.
United States
Food service procurement consolidation drives volume as institutional feeding operators prioritize labor reduction and menu consistency. FDA food contact notification requirements for BPA-free can linings accelerate supplier qualification timelines. Midwest processing clusters around Nebraska and Minnesota leverage regional pulse crop proximity to maintain input cost advantages.
Mexico
Household protein diversification beyond traditional corn and rice staples creates new category entry points for shelf-stable legumes. NOM-051 food labeling regulations mandate front-of-pack nutritional warnings, influencing product formulation strategies. Mexico City Metro anchors retail distribution while Nuevo León industrial corridors support contract manufacturing for export markets.
Brazil
Expanding middle-class consumption patterns pull volume toward convenient protein formats in urban centers. ANVISA food safety standards align with Codex frameworks to streamline import qualification for processed legumes. São Paulo state concentrates both retail demand and processing capacity, with Paraná emerging as a secondary production hub.
Germany
Private-label demand from discount retail chains shapes competitive positioning around cost-engineered formulations. EU REACH compliance on epoxy-based can coatings constrains supplier material choices and elevates reformulation costs. Bavaria and North Rhine-Westphalia host the core of European processing infrastructure, with Hamburg anchoring import logistics.
India
Export-oriented processors leverage BIS certification and FSSAI alignment to access Middle Eastern and African markets. CDSCO food safety standard harmonization with Codex frameworks streamlines cross-border qualification. Maharashtra and Gujarat concentrate processing capacity within designated export zones, with Karnataka emerging as a secondary cluster.
Canned Beans Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating compliance and format flexibility capabilities. The vendor base separates into three tiers: multinational conglomerates with multi-format manufacturing scale, regional specialists dominating ethnic market shelf space, and private-label suppliers serving retail chain proprietary brands. Consolidation pressure intensifies as food service procurement concentrates around fewer direct manufacturer relationships. Dominant competitive moves include portfolio diversification into single-serve cup formats and backward integration into pulse crop sourcing.
Within the multinational conglomerate tier, Conagra Brands, Inc. and Kraft Heinz Company exemplify scale-driven positioning across North American retail and food service channels. Goya Foods, Inc. occupies a distinct archetype as a regional specialist with concentrated presence in Hispanic market distribution. Bonduelle Group represents European private-label orientation with controlled channel positioning across continental retail networks.
| Leading Market Players |
|---|
| Conagra Brands, Inc. |
| General Mills |
| Kraft Heinz Company |
| B&G Foods, Inc. |
| Eden Foods, Inc. |
| Bush Brothers & Company |
| Del Monte Foods, Inc. |
| Bonduelle Group |
| Goya Foods, Inc. |
| Others |
Value Network & Pricing Analysis
Tinplate and aluminum input costs cascade through three distinct pricing tiers as steel can volatility compresses margin predictability for standard-format producers while single-serve cup premiums capture convenience-oriented household demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates BPA-free certified suppliers from conventional lining processors from private-label contract manufacturers. Price differentiation hinges on FDA food contact notification compliance status and volume scale commitments from food service operators. Pricing pressure stems from retort sterilization capex concentration limiting new entrant capacity expansion. Food service procurement teams exhibit highest price sensitivity due to consolidated direct contracting, while premium retail channels absorb modest premiums for coating-certified formats.
Supply Chain Analysis
Certification gating through FDA notification requirements and EU REACH compliance on epoxy-based coatings constrains supplier material choices and elevates qualification costs for new entrants. Geographic supply concentrates in the United States, Mexico, and Brazil where regional pulse crop proximity and established retort infrastructure anchor production. Raw material dependencies include tinplate substrate, aluminum sheet, and high-barrier polymer resins for cup formats. Single-source vulnerability around retort process engineering talent scarcity constrains facility commissioning timelines. Distribution runs through food service direct contracts, supermarket retail networks, and wholesale institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification infrastructure and FSSAI alignment create cost-advantaged export processing capacity against European REACH compliance burdens, positioning geographic arbitrage between regulatory cost structures as the defining strategic calculus.
For Market Incumbents: Acquire retort sterilization engineering talent pools to compress facility commissioning timelines against new entrant capacity threats. Expand backward integration into pulse crop sourcing in Nebraska and Minnesota clusters to defend margin position against steel can input volatility. Prioritize dual FDA-EU coating qualification to capture multinational food manufacturer procurement consolidation favoring simplified vendor bases. For New Entrants and Emerging Players: Enter via single-serve cup format innovation targeting UK and US convenience-oriented households reducing leftover waste through portion-controlled alternatives. White-space concentrates in Indian export processing zones serving Middle Eastern and African markets where BIS certification enables duty-advantaged supply. Pursue direct retail shelf placement beyond traditional canned goods aisles as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-format manufacturing scale intersects with established regulatory infrastructure, favoring processors with simultaneous FDA and EU qualification capabilities. Long-term viability frames around coating chemistry transition timing and single-serve format adoption curves. Target acquisition archetypes include regional specialists with concentrated ethnic market distribution and private-label suppliers with retail chain proprietary brand relationships. Watch EU per- and polyfluoroalkyl substance restriction timelines as the critical inflection signal for lining material transition capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulse Crop Sourcing | Captures input cost advantages in Nebraska and Minnesota processing clusters against steel volatility. |
| Dual FDA-EU Coating Qualification Investment | Positions suppliers for multinational food manufacturer procurement consolidation favoring simplified vendor bases. |
| Single-Serve Cup Format Expansion | Opens shelf space beyond traditional canned goods aisles in UK and US convenience-oriented retail channels. |
| Indian Export Processing Zone Establishment | Leverages BIS certification and FSSAI alignment for duty-advantaged supply to Middle Eastern and African markets. |
| Retort Process Engineering Talent Acquisition | Compresses new facility commissioning timelines against industry-wide thermal processing expertise concentration. |
Research Methodology
Direct dialogue with food service procurement directors, canned goods plant managers, retail category buyers, and regulatory affairs specialists combined with secondary validation from FDA food contact notifications, EU ECHA substance databases, customs trade records, and SEC processor filings. Bottom-up volume modeling triangulated against top-down category expenditure estimates across product type, packaging format, end user, and distribution channel dimensions.
Segment-level CAGRs derived from elasticity modeling against protein diversification indices and food service labor cost trends throughout the forecast period. Analytical framework incorporated retort capacity utilization rates, coating reformulation cost curves, and single-serve cup adoption velocity as industry-specific forecast inputs across chickpea, black bean, kidney bean, and pinto bean varieties.
Inputs from FDA notification databases and EU REACH registration archives were available through the study window; gaps in real-time food service contract pricing introduce uncertainty bands around food service channel value estimates. Deviation in EU per- and polyfluoroalkyl substance restriction timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Global Packed Food Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Spreads Market
Packaged Foods
Ready Meals Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Canned Food Market
Packaged Foods
Packaged Corn on the Cob Market