
 Dried Honey Market | 2026-2036
Dried Honey Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Honey Market Analysis
Asset-light contract manufacturing and toll-processing arrangements are fragmenting competitive barriers in dried honey production, enabling smaller ingredient specialists to scale without capital-intensive spray-drying infrastructure. ADM leverages its integrated agricultural supply chain to secure bulk honey feedstock at scale across multiple origination points. Ohly sustains competitive positioning through specialized malt and honey extract expertise that extends into dried formats for savory and beverage applications. Specialty Products and Technology anchors its presence in custom spray-drying services, occupying a niche between commodity processors and branded ingredient marketers.
Dried honey consists of dehydrated bee-derived nectar reduced to low-moisture particulate forms—typically below 5% water activity—through spray-drying, drum-drying, or vacuum evaporation processes, yielding shelf-stable sweeteners that retain enzymatic and aromatic properties for industrial formulation. Powdered honey dominates current volume flows due to its dispersibility in dry mixes and instant beverage applications, while granulated honey commands premium positioning in artisanal baking channels where crystalline texture signals authenticity. The food industry end-user segment leads absolute consumption, though nutraceuticals represents the fastest-growing demand pool as supplement manufacturers incorporate honey solids into immune-support and sports-nutrition formulations.
The FDA governs dried honey labeling under 21 CFR 101.4, requiring accurate declaration of added sugars and country-of-origin documentation that shapes importer compliance costs and domestic sourcing incentives. USDA organic certification and state-level apiary inspection protocols in California, Florida, and North Dakota further segment supply eligibility for premium-positioned products. Stakeholders must monitor evolving EU REACH compliance for imported pollen residues and emerging state pollinator-health regulations that could constrain regional honey availability and dried product cost structures.
Market Dynamics
Clean-label reformulation mandates from FDA's updated Nutrition Facts labeling requirements for added sugars are forcing food manufacturers to restructure sweetener procurement strategies across North American processed food categories. This regulatory pressure concentrates competitive advantage among ingredient suppliers capable of delivering standardized honey solids with verified low-moisture specifications and full traceability documentation.
Growth Catalysts
- Clean-Label Regulatory Pressure:FDA's added sugars disclosure rules under 21 CFR 101.4 are compelling bakery and confectionery formulators to replace corn syrup and refined sugar with recognizable honey-derived ingredients that require minimal explanatory labeling.
- Spray-Drying Technology Maturation:Advanced atomization and temperature-control systems now preserve enzymatic activity in honey powders at commercial scale, opening formulation possibilities previously restricted to liquid honey.
- United States:Craft bakery clusters in California, Texas, and North Carolina are building direct procurement relationships with regional apiaries, creating dedicated supply channels that bypass commodity ingredient distributors.
Market Restraints
- Feedstock Cost Volatility:Colony collapse disorder and varroa mite infestations in Florida and North Dakota apiaries are constraining domestic honey yields, elevating raw material costs for processors dependent on North American origin claims.
- Substitution Threat:Coconut sugar and date syrup solids are capturing price-sensitive bakery accounts with comparable clean-label positioning and superior moisture-binding performance in certain applications.
- Technical Limitation:Honey's hygroscopic nature creates caking and flowability problems in powder form above 3% residual moisture, limiting shelf-stable packaging formats and complicating automated handling systems.
Strategic Opportunities
- Sports Nutrition Formulations:Supplement manufacturers are incorporating honey solids into pre-workout and recovery products, leveraging the ingredient's dual carbohydrate profile and natural positioning to differentiate from synthetic maltodextrin.
- California State Pollinator Health Initiatives:Legislative funding for habitat restoration and breeding programs could expand regional honey production capacity, creating captive supply advantages for processors with established apiary partnerships.
- Direct-to-Manufacturer E-Commerce:Specialized ingredient marketplaces are enabling smaller spray-drying operations to reach craft food producers without distributor markups, compressing customer acquisition costs for regional players.
Industry Challenges
- Organic Certification Timeline:USDA organic honey certification requires three-year forage documentation and state apiary inspection protocols that extend qualification cycles to 18-24 months, delaying premium product launches.
- Cross-Contamination Control:Shared spray-drying facilities handling dairy, soy, or gluten-containing ingredients must implement validated cleanout procedures that add 4-6 hours of downtime between honey-dedicated production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Honey Market |
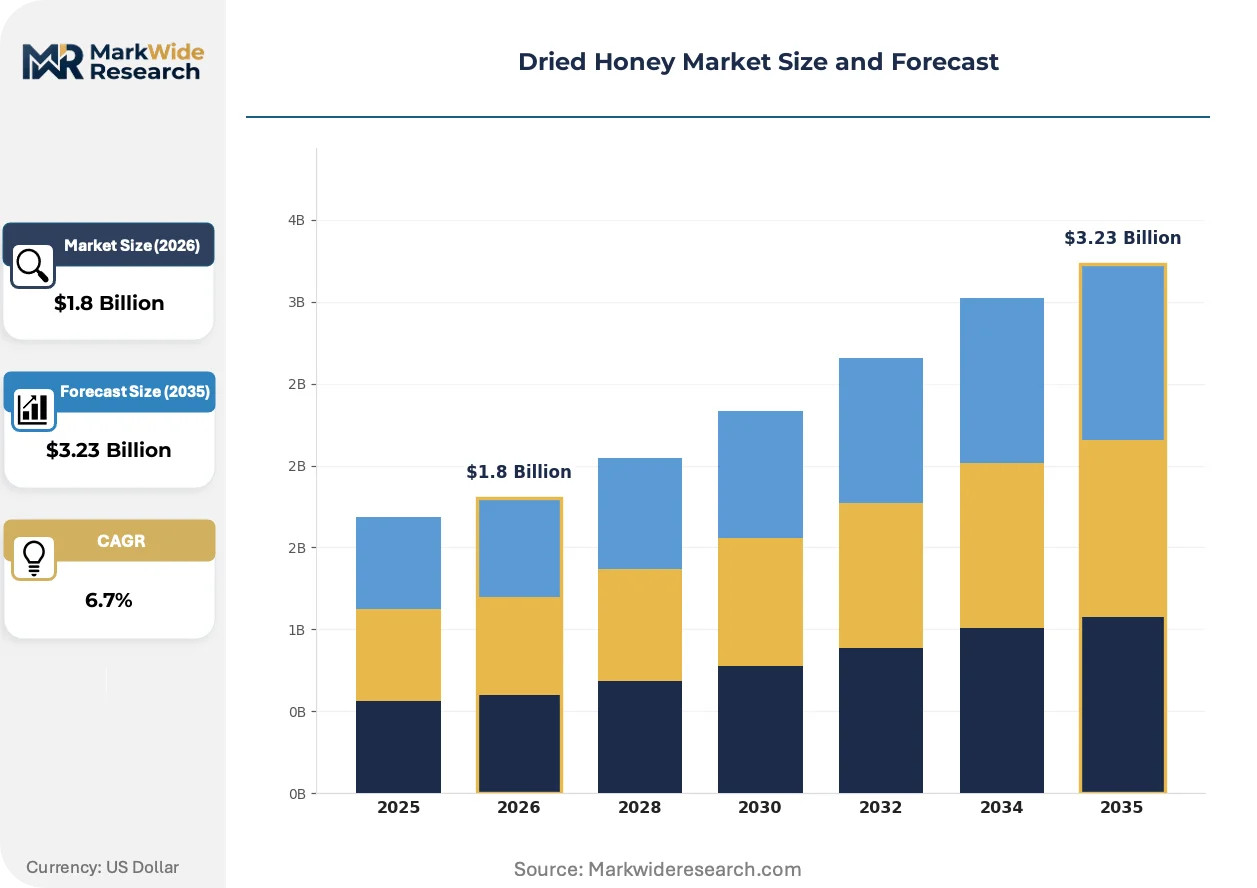
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulated Honey, Powdered Honey, Crystallized Honey, Honey Flakes Application: Baking, Confectionery, Beverages, Health Supplements End User: Households, Food Industry, Nutraceuticals, Food Service Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | ADM, Ohly, Norevo, AmTech Ingredients, Fytexia, Specialty Products and Technology, Best Ground International, Hoosier Hill Farm, Domino Specialty Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Honey Market Emerging Trajectories
Processing technology convergence with precision agriculture data systems is reshaping how dried honey producers secure feedstock quality and optimize dehydration parameters. These developments are compressing the gap between artisanal apiary practices and industrial-scale ingredient manufacturing.
Advanced inline refractometry and moisture-sensing instrumentation is digitizing real-time process control in spray-drying operations. Commercial food manufacturers operating high-throughput baking lines are adopting these sensor-integrated systems to guarantee batch-to-batch consistency in honey powder dissolution rates. This capability is digitizing quality assurance workflows that previously required offline laboratory testing, reducing release cycle times from hours to minutes.
California's state-level pollinator health regulations are mandating habitat buffer zones and pesticide reporting for apiaries supplying certified honey. These rules are elevating compliance costs for small-scale beekeepers while creating sourcing advantages for vertically integrated operations with controlled forage acreage. Nutraceutical manufacturers seeking immune-support positioning are responding by requiring documented provenance that traces honey solids to specific apiary locations and bloom cycles.
Ingredient procurement teams at mid-sized bakery operations are consolidating supplier relationships to reduce qualification overhead and secure volume commitments. This consolidation is displacing fragmented spot purchasing through commodity brokers, favoring toll-processors with dedicated honey-drying capacity and established food safety certifications. The shift is most visible in the southeastern United States, where regional bakery cooperatives are negotiating multi-year supply agreements directly with North Dakota and Florida processors.
Dried Honey Market Segmentation
Dried honey procurement cycles vary dramatically by segment, with industrial food manufacturers negotiating annual contracts while nutraceutical startups sample quarterly batches. Understanding these velocity differentials helps suppliers align inventory positions with actual consumption patterns rather than aggregated demand signals.
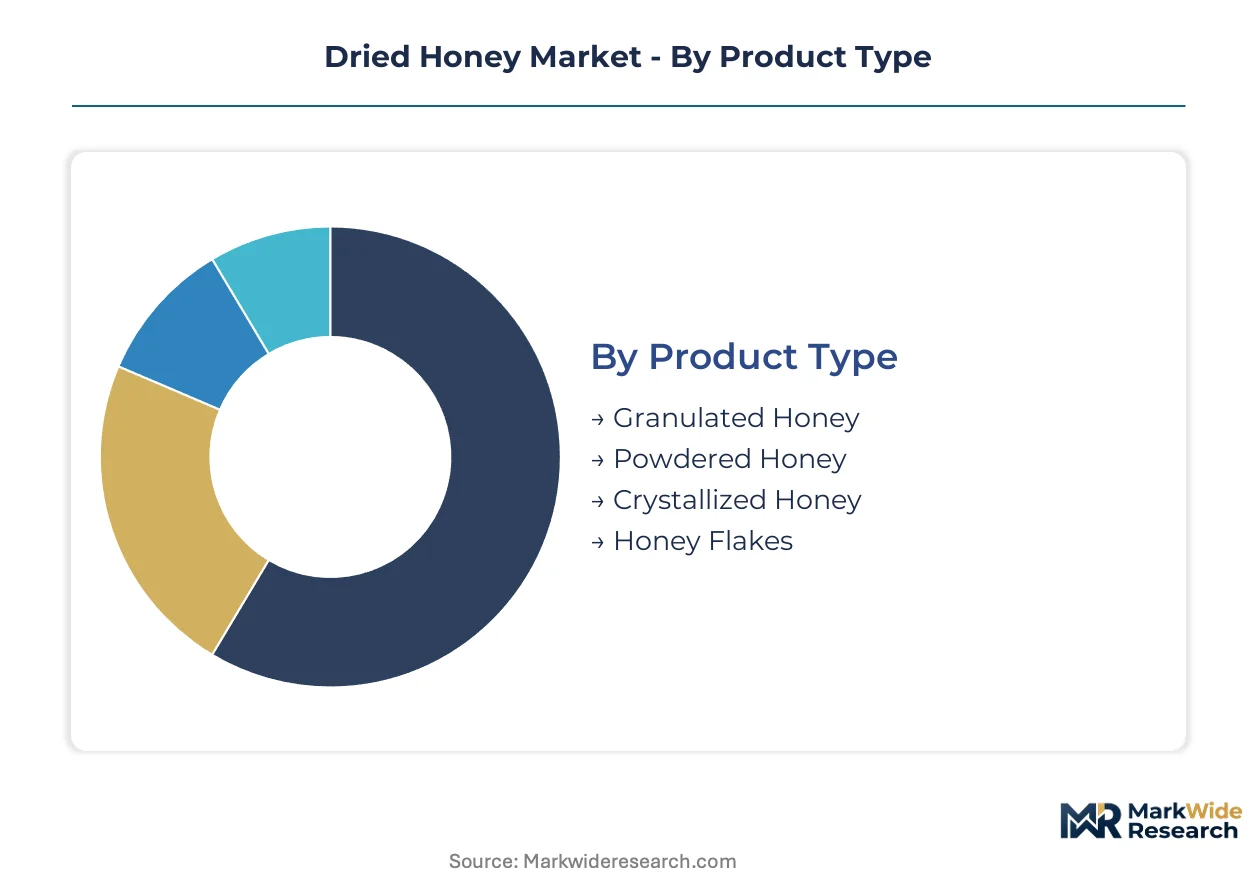
Product Type:
Powdered honey turns inventory fastest in beverage manufacturing lines, while crystallized honey sits longest in artisanal bakery channels. The cycle-time spread between formats exceeds eighteen months in some supply chains.
- Powdered Honey:Spray-dried particulates below 5% moisture activity dissolve rapidly in dry mixes and instant beverages. California beverage manufacturers and Texas baking cooperatives drive the highest throughput volumes for this format.
- Granulated Honey:Crystalline structure signals authenticity in premium baking applications where texture visibility matters. North Carolina craft bakeries and Florida confectionery specialists specify this grade for clean-label positioning.
- Crystallized Honey:Semi-solid state preserves more aromatic compounds than fully dried alternatives. Specialty European importers and domestic apiary-direct channels move this format slowly.
- Honey Flakes:Drum-dried thin sheets rehydrate for cereal coatings and snack bar binding. Limited commercial scale restricts availability to niche nutraceutical applications.
Powdered honey anchors the volume base while granulated honey gains share at the steepest rate.
Application:
Cost-tier stratification separates commodity bakery procurement from premium supplement formulation. Beverage applications occupy the mid-tier with standardized specification requirements.
- Baking:Dry honey replaces corn syrup in clean-label reformulations for cookies, breads, and pastry glazes. Industrial bakeries in the southeastern United States specify certified low-moisture powders for automated handling systems.
- Confectionery:Hard candies and molded sweets utilize honey solids for humectancy and browning control. FDA added-sugar disclosure rules under 21 CFR 101.4 are accelerating substitution away from refined sucrose.
- Beverages:Instant drink mixes and dry smoothie bases leverage honey powder dispersibility. Sports nutrition manufacturers in California incorporate the ingredient for dual carbohydrate profiles.
- Health Supplements:Immune-support capsules and pre-workout formulations command premium positioning. Three-year USDA organic forage documentation extends supplier qualification timelines to twenty-four months.
Baking commands absolute volume while health supplements expand most quickly.
End User:
Customer-type concentration determines margin structure, with food industry accounts extracting volume discounts and nutraceutical buyers paying certification premiums.
- Food Industry:Processed food manufacturers integrate honey solids into sauces, marinades, and prepared meals. Clean-label mandates from major retail chains are restructuring sweetener procurement specifications.
- Food Service:Commercial kitchens and bakery chains source bulk formats through dedicated distribution. Regional cooperatives in Texas and North Carolina negotiate multi-year supply agreements directly with processors.
- Nutraceuticals:Supplement brands require documented provenance tracing honey solids to specific apiary locations and bloom cycles. California state pollinator health regulations are elevating compliance costs for small-scale suppliers.
- Households:Consumer packaged goods through retail channels represent the smallest volume pool. Specialty stores and online marketplaces serve this fragmented demand base.
Food industry procurement anchors the volume base while nutraceuticals climb the fastest.
Distribution Channel:
Supply concentration favors direct manufacturer relationships, with intermediary margins compressing as procurement teams consolidate supplier bases.
- Wholesalers:Ingredient distributors serve mid-sized bakery operations with mixed-product orders. Consolidation among regional bakery cooperatives is displacing fragmented spot purchasing through this channel.
- Online Retail:Specialized ingredient marketplaces enable smaller spray-drying operations to reach craft producers. Customer acquisition costs are dropping for regional players bypassing traditional distributor markups.
- Supermarkets:Consumer-packaged honey solids occupy limited shelf space in conventional grocery. Private-label expansion is capturing price-sensitive household demand.
- Specialty Stores:Natural products retailers stock organic-certified formats at premium price points. Three-year forage documentation requirements restrict certified product availability.
Wholesalers anchor the volume base while online retail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's updated Nutrition Facts labeling requirements under 21 CFR 101.4 are restructuring procurement patterns across North American processed food categories. This regulatory pressure is accelerating clean-label reformulation investments in specific national markets where honey-derived ingredients offer compliant sweetness solutions.
United States
California craft bakeries and Texas commercial foodservice operators drive procurement volume for powdered honey formats. The FDA's added sugars disclosure rules compel reformulation away from corn syrup in southeastern industrial baking clusters. Regional apiary partnerships in North Dakota and Florida are creating dedicated supply channels that bypass commodity distributors.
Germany
EU REACH compliance requirements for imported pollen residues are elevating documentation costs for honey solids entering German confectionery supply chains. The country's federal food safety authority enforces strict origin verification protocols that favor domestic apiary sourcing. Bavarian baking cooperatives are consolidating supplier relationships to reduce qualification overhead for organic-certified honey powders.
France
ANSM oversight of nutraceutical formulations is driving demand for documented honey provenance tracing solids to specific bloom cycles. The country's pharmaceutical-grade ingredient standards extend into immune-support supplement manufacturing near Lyon and Strasbourg. French apiary cooperatives are investing in controlled forage acreage to secure premium positioning for dried honey exports.
China
SAMR food labeling standards are converging with international clean-label trends in Shanghai and Guangzhou processed food manufacturing. The country's dual carbon goals are pressuring energy-intensive spray-drying operations to adopt efficiency upgrades. Yangtze River Delta beverage manufacturers are sampling honey powders for instant drink mix formulations targeting domestic premium segments.
India
FSSAI enforcement of added sugars disclosure on packaged foods is opening formulation opportunities for honey-derived alternatives in Mumbai and Bangalore bakery chains. The PLI scheme incentives for food processing infrastructure are attracting toll-drying investments in Gujarat and Maharashtra. Domestic apiary consolidation in Punjab and Haryana is improving feedstock standardization for industrial honey powder production.
Dried Honey Market Vendor Landscape
On the supply side, the industry is fragmenting across asset-light contract manufacturers and integrated agricultural processors with captive feedstock access. Spray-drying capacity constraints are creating tiered competitive positions between commodity-scale operators and specialized toll-processors. Three strategic archetypes dominate: integrated agribusinesses with multi-origination honey sourcing, ingredient specialists with malt and extract expertise extending into dried formats, and custom spray-drying service providers occupying niche positions between commodity processors and branded marketers. Dominant competitive moves include backward integration into apiary partnerships and portfolio diversification into organic-certified product lines.
Within the integrated agribusiness tier, ADM leverages its agricultural supply chain infrastructure across multiple honey origination points. Ohly sustains positioning through specialized extract expertise that extends into dried honey formats for savory and beverage applications. Specialty Products and Technology anchors a niche in custom spray-drying services between commodity-scale processors and branded ingredient marketers.
| Leading Market Players |
|---|
| ADM |
| Ohly |
| Norevo |
| AmTech Ingredients |
| Fytexia |
| Specialty Products and Technology |
| Best Ground International |
| Hoosier Hill Farm |
| Domino Specialty Ingredients |
| Others |
Supply Flow & Price Mechanics
Spray-drying capacity underutilization in the North Dakota corridor is pressuring toll-processors to accept compressed margins while simultaneously incentivizing California-based apiary partnerships that command premium positioning. This utilization asymmetry between commodity-scale operators and specialized regional processors is bifurcating supplier behavior and pricing power across the dried honey value chain.
Pricing Analysis
Certification level creates the primary spread in dried honey procurement, with USDA organic certification and state apiary inspection protocols in California, Florida, and North Dakota segmenting supply into three distinct pricing tiers. Powdered honey for industrial baking commands standardized contract rates, while granulated formats for artisanal channels extract substantial premiums for crystalline texture verification. Cost compression in commodity-grade powders is intensifying as coconut sugar and date syrup solids capture price-sensitive bakery accounts, leaving nutraceutical buyers as the least price-sensitive segment due to extended qualification timelines and provenance documentation requirements.
Supply Chain Analysis
Colony collapse disorder exposure across Florida and North Dakota apiaries dominates supply chain risk assessments for North American dried honey processors. Feedstock sourcing draws from domestic apiary clusters in California, Texas, and the upper Midwest, with supplemental volumes entering from Argentine and Ukrainian origins to satisfy organic-certified demand. Spray-drying equipment and maltodextrin carrier materials constitute critical input dependencies, while single-source vulnerability concentrates in regional apiary partnerships that lack geographic diversification. Distribution runs through consolidated direct-manufacturer relationships and specialized ingredient marketplaces that are displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dried honey market presents a defensive-moat story anchored in regulatory entrenchment: FDA's 21 CFR 101.4 added sugars disclosure rules and state-level pollinator health protocols create compliance barriers that favor established processors with validated documentation systems and multi-year apiary contracts.
For Market Incumbents: Entrench positioning through backward integration into controlled forage acreage in California and North Dakota, securing captive honey supply that satisfies three-year organic certification timelines. Augment spray-drying capacity with inline refractometry systems that guarantee batch-to-batch enzymatic activity preservation, creating switching costs for bakery and nutraceutical accounts dependent on dissolution rate consistency. The substitution threat from coconut sugar and date syrup solids demands continuous R&D investment in honey powder flowability improvements that address hygroscopic caking limitations above residual moisture thresholds. For New Entrants and Emerging Players: Sports nutrition formulations in California and direct-to-manufacturer e-commerce channels represent the most penetrable entry points for asset-light toll-processors lacking commodity-scale infrastructure. Mid-sized bakery cooperatives in Texas and North Carolina are consolidating supplier relationships and seeking regional processors with dedicated honey-drying capacity and established food safety certifications. A go-to-market angle emphasizing documented provenance tracing honey solids to specific apiary locations and bloom cycles addresses nutraceutical manufacturer requirements that incumbent commodity processors often neglect. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across custom spray-drying services as asset-light contract manufacturing fragments competitive barriers and enables smaller ingredient specialists to scale without infrastructure ownership. Long-term viability over the next decade hinges on acquisition targets possessing established apiary partnerships in pollinator-health-regulated states and validated cleanout procedures for shared facilities handling allergen-containing ingredients. The signal to watch is California state legislative funding for habitat restoration and breeding programs, which could expand regional honey production capacity and shift sourcing economics toward vertically integrated operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Apiary Partnerships | Controlled forage acreage in California satisfies three-year USDA organic certification requirements. |
| Spray-Drying Technology Upgrade | Advanced atomization systems preserve enzymatic activity for sports nutrition formulation applications. |
| Direct-to-Manufacturer E-Commerce Platform | Specialized marketplaces compress customer acquisition costs for regional toll-processing operations. |
| Organic Certification Investment | State apiary inspection protocols in Florida and North Dakota segment supply eligibility for premium positioning. |
| Multi-Year Supply Agreement Negotiation | Southeastern bakery cooperatives consolidate procurement to reduce qualification overhead and secure volume commitments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with spray-drying facility operators, procurement leads at bakery and nutraceutical manufacturers, apiary cooperative managers, and food safety certification specialists; and secondary validation through FDA 21 CFR filings, USDA organic certification databases, state apiary inspection records, and customs trade data for honey feedstock imports. Bottom-up volume estimates from processor capacity utilization rates and top-down demand segmentation from end-use consumption patterns were triangulated to establish market sizing.
Forecast inputs include spray-drying technology maturation curves, clean-label regulatory enforcement trajectories under FDA and state pollinator health initiatives, and substitution elasticity between honey-derived and alternative natural sweeteners. Segmentation dimensions modeled encompass product type, application category, end-user archetype, and distribution channel across the projection horizon. CAGRs were derived from fitted growth curves incorporating feedstock cost volatility assumptions and capacity expansion timelines for toll-processing infrastructure.
Macroeconomic conditions sit as an overlay; deviation in commodity honey prices, energy costs for dehydration operations, or pollinator health regulation stringency would shift the trajectory. Forecasts reflect documented assumptions about colony collapse disorder incidence and organic certification timeline completion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
India Packaged Food Products Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Packaged Food Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Convenience Food Market
Packaged Foods
Wet Food Pouch Market