
 Prepared Flour Mixes Market | 2026-2036
Prepared Flour Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Prepared Flour Mixes Market Analysis
Indonesia is reshaping regional supply dynamics through new milling and blending capacity aimed at Southeast Asian export markets. General Mills leverages its North American distribution infrastructure to sustain shelf-space dominance in mass retail channels. Lesaffre anchors European supply through specialized yeast-integrated flour formulations that reduce proofing time for industrial bakeries. ADM competes on grain sourcing scale, controlling wheat procurement corridors from the Great Plains to Atlantic port terminals.
Prepared flour mixes denote pre-blended combinations of refined wheat flour, leavening agents, emulsifiers, and functional additives formulated to specific hydration ratios and protein contents, typically requiring only the addition of water, eggs, or oil before baking or cooking. These formulations standardize output consistency across commercial and home kitchens while reducing labor input and ingredient inventory. Bread mix and cake mix command the largest volume positions, though pizza dough mixes generate superior per-unit margins through food-service contracts and frozen-dough supply chains. Online retail channels represent the fastest-expanding distribution vector, particularly for premium gluten-free and organic variants that bypass conventional supermarket slotting constraints.
FDA standards for enriched flour fortification and EFSA additive authorizations under Regulation (EC) No 1333/2008 govern compositional limits across major markets, while BIS certification requirements in India create non-tariff barriers for imported blend formulations. These frameworks elevate compliance costs for new entrants but simultaneously protect established suppliers with in-house regulatory affairs capabilities. Stakeholders must monitor evolving front-of-pack labeling mandates and fortification thresholds, as these rules will determine which product portfolios retain shelf access in key jurisdictions.
Market Dynamics
Clean-label mandates from EFSA and FDA are forcing manufacturers to reformulate additive portfolios while commercial bakeries across Southeast Asia accelerate conversion from scratch-based operations to pre-mixed solutions, compressing traditional supply relationships.
Growth Catalysts
- EFSA Reduced Sodium Mandates:Regulatory pressure on sodium content in baked goods is creating replacement demand for optimized salt-reduction formulations that maintain dough functionality without taste compromise.
- Street-Food Vendor Conversion:Small bakeries and mobile food vendors in Indonesia and Vietnam are abandoning scratch-based production for instant bread and cake mixes to shorten production cycles and reduce labor.
- Enzyme-Assisted Fermentation:Novel enzyme blends are accelerating proofing times for industrial bakeries, reducing capital tied up in fermentation inventory and enabling same-day production scheduling.
Market Restraints
- Wheat Price Volatility:Input cost fluctuations tied to Black Sea supply disruptions and drought cycles in North American growing regions compress margins for standard-grade formulations.
- BIS Certification Barriers:India's mandatory BIS certification for imported blend formulations creates non-tariff friction that elevates compliance costs and extends market entry timelines for foreign suppliers.
- Fresh-Baked Substitution:In-store bakery programs at European retail chains and artisan sourdough revival movements in North American urban centers pull consumers away from packaged mix solutions.
Strategic Opportunities
- Vietnamese Food-Service Expansion:Underpenetrated pizza and bakery chains in secondary Vietnamese cities present whitespace for frozen-dough supply contracts with superior per-unit economics.
- EU Green Deal Alignment:Carbon footprint labeling requirements and sustainable sourcing incentives favor suppliers with certified sustainable wheat procurement and biodegradable packaging transitions.
- Direct-to-Consumer Channels:Online retail bypasses conventional supermarket slotting constraints for premium gluten-free and organic variants, enabling margin capture without retail gatekeeper fees.
Industry Challenges
- Clean-Label Reformulation Complexity:Removing established emulsifiers and preservatives while maintaining shelf stability and texture consistency demands extended R&D cycles and sensory testing protocols.
- Regulatory Affairs Talent Scarcity:Shortage of specialists capable of navigating simultaneous FDA, EFSA, and BIS additive authorization processes delays product launches in multi-jurisdictional portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prepared Flour Mixes Market |
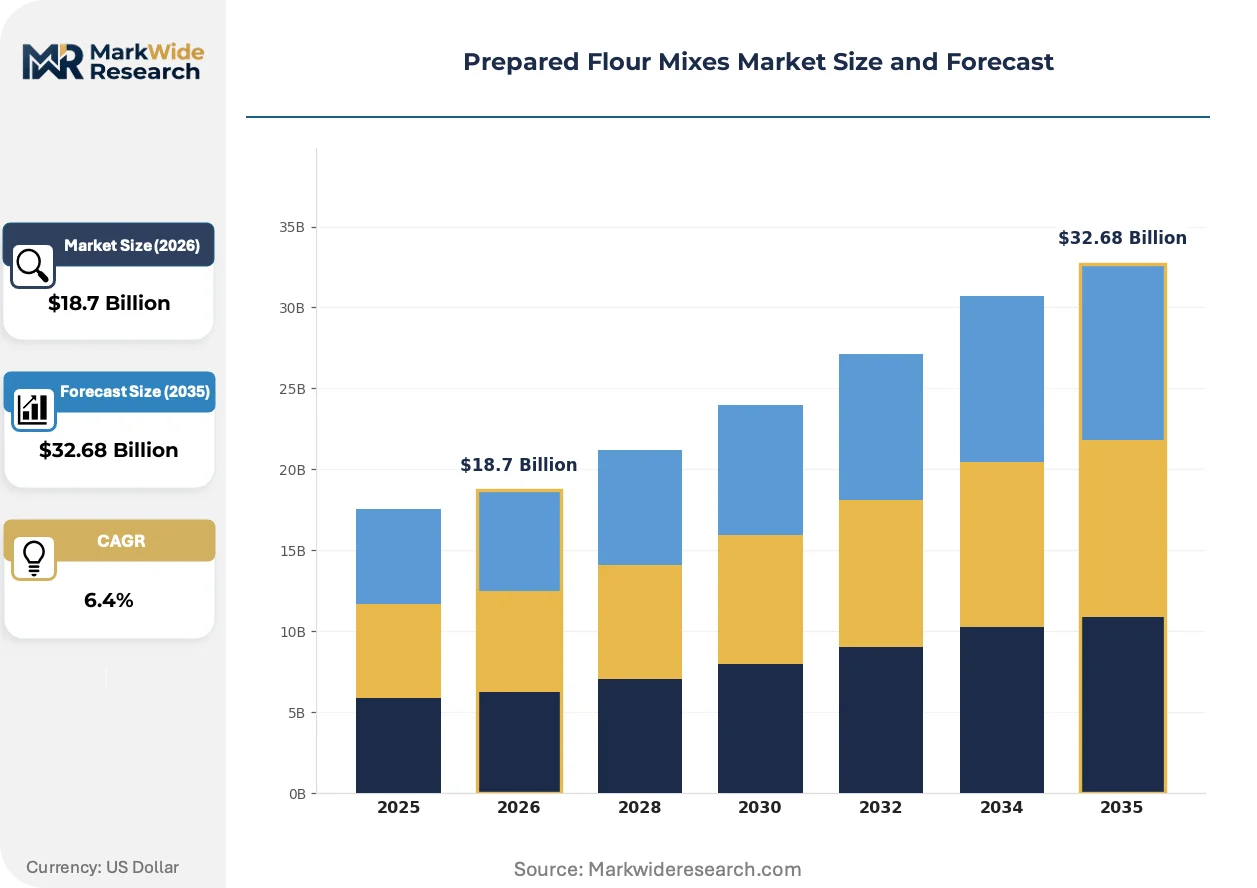
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pancake Mix, Bread Mix, Cake Mix, Pizza Dough Distribution Channel: Online Retail, Supermarkets, Food Service, Specialty Stores End User: Households, Restaurants, Bakeries, Food Manufacturers Packaging Type: Flexible Bags, Rigid Containers, Bulk Packaging, Boxes |
| Companies Covered | Nestlé S.A., Lesaffre, General Mills, Nisshin Seifun Group, Continental Mills, Archer Daniels Midland Company (ADM), PURATOS, Kerry Group, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prepared Flour Mixes Market Emerging Trajectories
Digital process control systems and automated batching technologies are compressing quality variance in industrial mixing operations while regulatory labeling mandates and shifting procurement behaviors reshape competitive requirements across formulation tiers.
Smart blending equipment equipped with real-time moisture sensors and automated protein-adjustment modules is digitizing quality control in commercial bakery operations. Large-scale industrial bakeries in Germany and Japan are deploying these systems to eliminate batch-to-batch variation. This standardization is digitizing the specification process between flour mills and downstream buyers, reducing arbitration disputes and contract renegotiation frequency.
EFSA's evolving stance on enzyme additives under Regulation (EC) No 1333/2008 is compressing the approved substance list for clean-label formulations. Manufacturers must reformulate around restricted processing aids while maintaining functional equivalence in dough handling and finished product texture. European industrial bakeries are responding by consolidating supplier relationships with enzyme houses capable of rapid regulatory dossier preparation and novel solution development.
Food-service procurement is consolidating around outcome-based specifications rather than ingredient-grade purchasing, with contract bakers demanding guaranteed yield rates and finished-product consistency metrics. Large pizza chains in the United States are shifting from flour procurement to fully-managed dough programs where suppliers assume inventory risk and quality liability. This behavioral shift is most visible in the quick-service restaurant vertical, where procurement teams prioritize total cost of ownership over per-pound input pricing.
Prepared Flour Mixes Market Segmentation
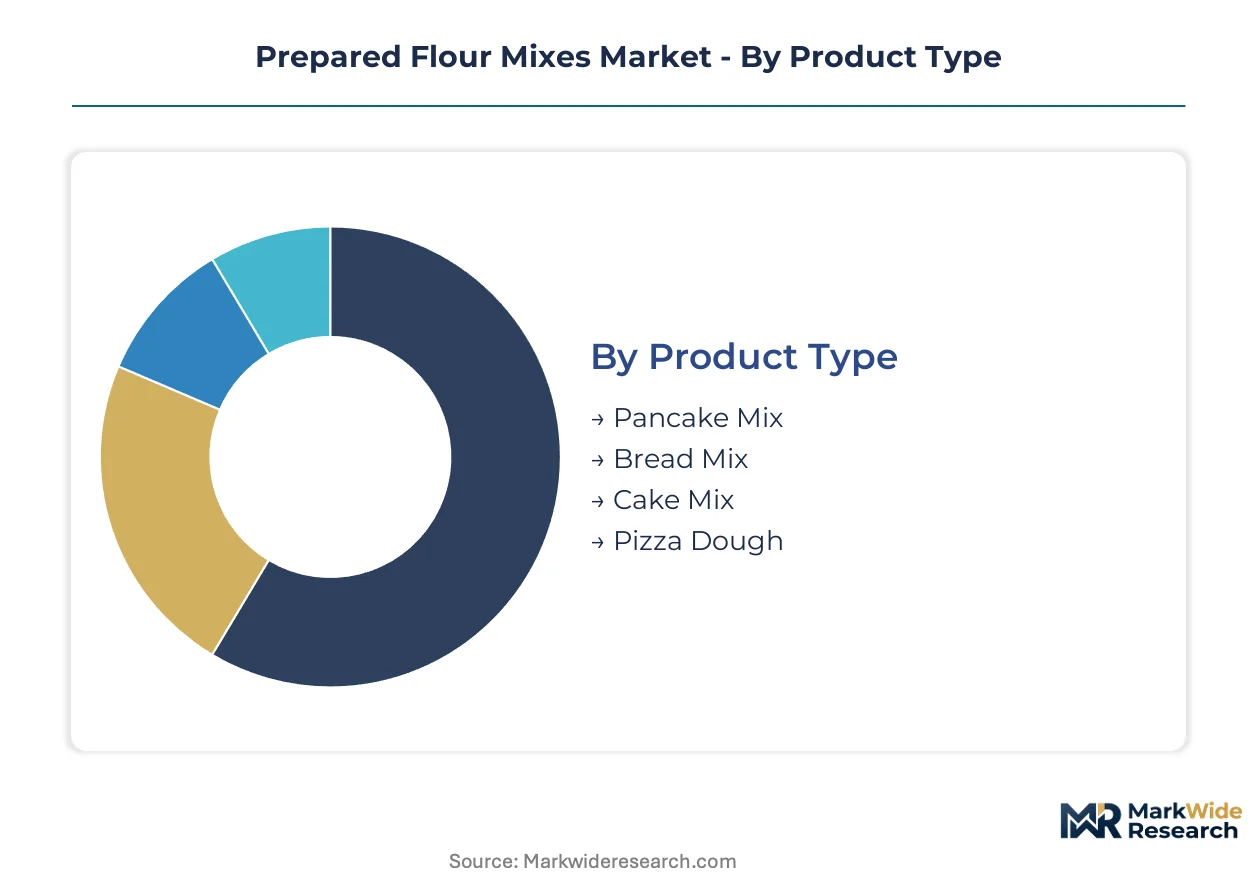
Segmentation in prepared flour mixes reveals distinct performance profiles across formulation types and procurement channels. Understanding these divides helps suppliers align R&D investment with where margin compression and expansion actually occur.
Product Type:
Mature formulations dominate shelf turnover while emerging applications reshape contract economics for industrial buyers.
- Bread Mix:Standardized combinations of refined wheat flour, yeast, and dough conditioners formulated to specific protein contents between 11-14%. Commercial bakeries across Indonesia and Vietnam are converting from scratch production to instant bread mixes to compress fermentation cycles and reduce labor headcount.
- Cake Mix:Pre-blended formulations incorporating emulsifiers, leavening agents, and sugar calibrated for specific hydration ratios. Street-food vendors in Southeast Asian urban centers are adopting these mixes to eliminate ingredient weighing and shorten preparation windows during peak demand periods.
- Pizza Dough:Frozen-dough supply chains generate superior per-unit margins through food-service contracts with quick-service restaurant chains.
- Pancake Mix:Home kitchen applications concentrate demand in North American mass retail channels with seasonal promotional cycles.
Bread Mix retains volume leadership; Pizza Dough holds the steepest expansion curve.
Distribution Channel:
Channel cost structures determine which formulation tiers can sustain viable economics.
- Food Service:Procurement is consolidating around outcome-based specifications with contract bakers demanding guaranteed yield rates and finished-product consistency metrics. Large pizza chains in the United States are shifting from flour procurement to fully-managed dough programs where suppliers assume inventory risk and quality liability.
- Online Retail:Digital channels bypass conventional supermarket slotting constraints for premium gluten-free and organic variants that would face gatekeeper barriers in brick-and-mortar retail.
- Supermarkets:Mass retail channels sustain shelf-space dominance for standard-grade formulations through promotional velocity and brand recognition.
- Specialty Stores:Curated retail environments capture premium pricing for clean-label and artisan-positioned mix formulations.
Food Service commands the highest contract values; Online Retail is climbing the fastest.
End User:
User sophistication determines specification complexity and supplier relationship intensity.
- Restaurants:Commercial kitchens prioritize batch consistency and labor reduction over per-pound input pricing, driving demand for pre-calibrated hydration ratios.
- Bakeries:Industrial operations deploy smart blending equipment with real-time moisture sensors to eliminate batch-to-batch variation and reduce arbitration disputes with flour mills.
- Food Manufacturers:Large-scale processors require certified sustainable wheat procurement and biodegradable packaging transitions to meet EU Green Deal alignment requirements.
- Households:Convenience-oriented consumers in North American and European markets sustain demand for single-step preparation formats.
Restaurants generate the most specification-intensive demand; Food Manufacturers are gaining share fastest.
Packaging Type:
Packaging format selection tracks handling requirements from industrial scale down to retail shelf.
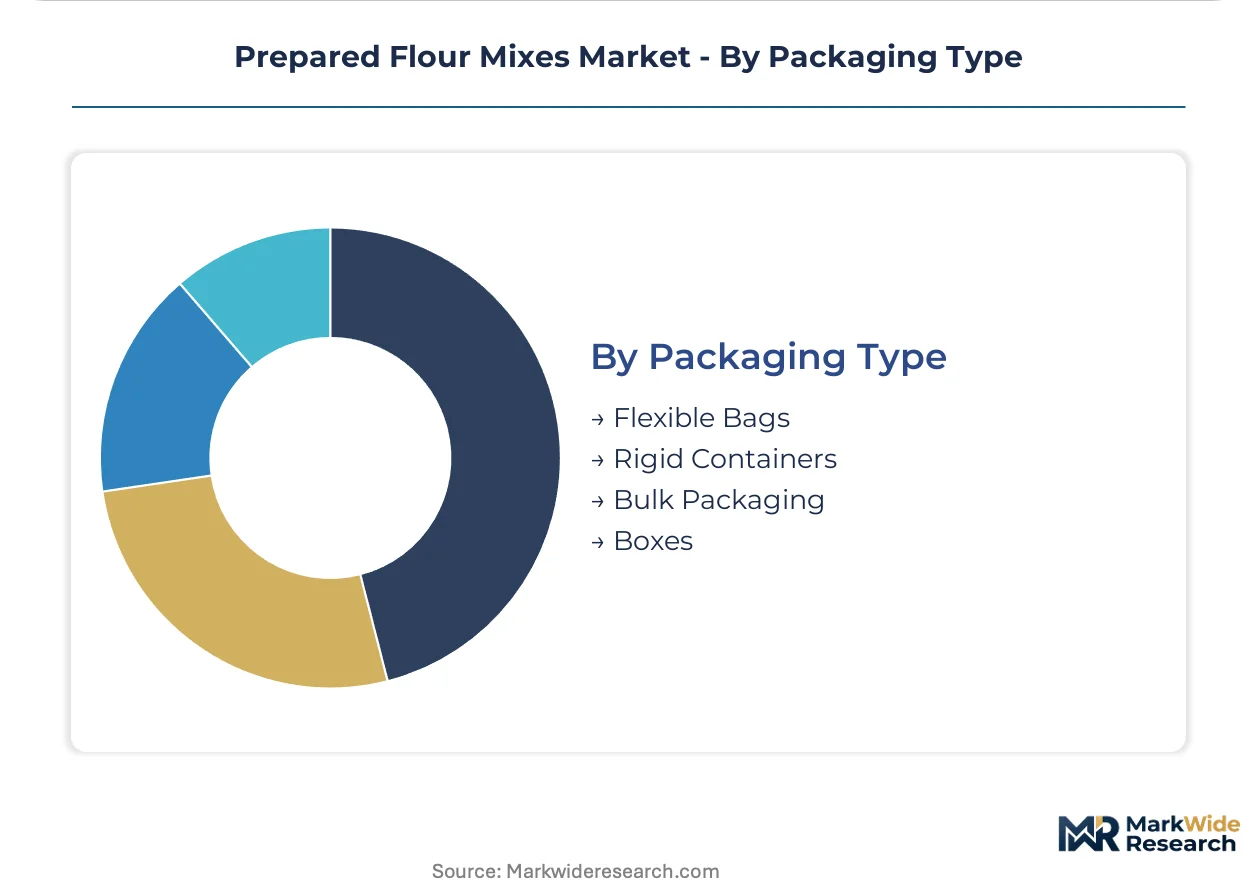
- Bulk Packaging:Tanker and tote formats serve industrial bakeries with high-throughput production lines and automated ingredient handling systems.
- Flexible Bags:Multi-wall paper and plastic laminates balance moisture protection with pallet efficiency for mid-scale commercial users.
- Rigid Containers:Pails and drums provide stack stability and resealability for food-service operators with variable consumption rates.
- Boxes:Retail-ready cartons with portion-controlled inner pouches target household consumers seeking pantry organization and portion precision.
Bulk Packaging retains volume leadership; Flexible Bags hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA fortification standards and EFSA additive authorizations anchor regulatory frameworks across the dominant geographies, while street-food vendor conversion and clean-label mandates reshape procurement patterns in emerging markets.
United States
Commercial bakeries and quick-service restaurant chains drive bulk procurement of pizza dough and bread mixes, prioritizing labor reduction and batch consistency. FDA enriched flour standards govern compositional requirements, creating compliance barriers for imported formulations. Chicago and Dallas industrial corridors concentrate frozen-dough supply contracts with food-service operators demanding guaranteed yield rates.
Indonesia
Small bakeries and street-food vendors in Jakarta and Surabaya accelerate conversion from scratch-based operations to instant bread and cake mixes, compressing fermentation cycles. BIS certification requirements for imported blends create non-tariff friction that elevates compliance costs for foreign suppliers. New milling and blending capacity in Java targets Southeast Asian export markets.
Germany
Industrial bakeries deploy smart blending equipment with real-time moisture sensors to eliminate batch-to-batch variation and digitize quality control. EU Green Deal carbon footprint labeling requirements favor suppliers with certified sustainable wheat procurement. Bavarian and North Rhine-Westphalia production clusters anchor European supply through specialized yeast-integrated formulations.
Vietnam
Underpenetrated pizza and bakery chains in Ho Chi Minh City and secondary urban centers present whitespace for frozen-dough supply contracts. Street-food vendors adopt pre-mixed solutions to shorten preparation windows during peak demand periods. Local procurement teams prioritize total cost of ownership over per-pound input pricing in quick-service contracts.
India
Food manufacturers and mid-scale commercial bakeries expand procurement of standardized formulations to reduce ingredient inventory and labor headcount. BIS mandatory certification for imported blend formulations extends market entry timelines for foreign suppliers. Maharashtra and Gujarat industrial corridors concentrate demand from contract bakers and processed food exporters.
Prepared Flour Mixes Market Vendor Landscape
Global diversified food conglomerates and specialized yeast-integrated formulation suppliers split the market between mass retail shelf-space dominance and industrial bakery technical partnerships. The vendor base organizes around three strategic archetypes: multinational consumer packaged goods houses with North American distribution infrastructure, European enzyme and fermentation specialists with regulatory dossier capabilities, and grain-sourcing majors controlling procurement corridors from growing regions to port terminals. Capacity expansion in Southeast Asian milling operations and strategic partnerships for clean-label reformulation represent the dominant competitive moves across tiers.
Within the multinational packaged goods tier, General Mills and Nestlé S.A. occupy positions anchored by mass retail channel access and brand recognition in household segments. Among specialized fermentation suppliers, Lesaffre exemplifies the European archetype with yeast-integrated formulations targeting industrial bakery proofing time reduction. At the agricultural commodity end, Archer Daniels Midland Company (ADM) represents scale-driven sourcing advantages across wheat procurement corridors.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Lesaffre |
| General Mills |
| Nisshin Seifun Group |
| Continental Mills |
| Archer Daniels Midland Company (ADM) |
| PURATOS |
| Kerry Group |
| Conagra Brands |
| Others |
Supply Flow & Price Mechanics
Java's new milling and blending capacity expansion is compressing regional supply costs and redistributing pricing power toward Southeast Asian production clusters serving Indonesian and Vietnamese bakery conversions.
Pricing Analysis
Price spreads between North American and Southeast Asian supply corridors reflect freight differentials and tariff exposure rather than quality variance. Three-tier pricing structure across premium gluten-free, standard industrial-grade, and economy bulk formulations tracks certification complexity and volume scale. Pricing pressure stems from wheat price volatility tied to Black Sea supply disruptions, with commercial bakeries in Indonesia and Vietnam exhibiting highest price sensitivity due to thin margin structures.
Supply Chain Analysis
Tariff exposure between North American growing regions and Asian processing hubs elevates landed costs for imported wheat and enzyme additives. Supply concentrates in the United States, Germany, and Indonesia, with raw material dependencies on hard red winter wheat, specialized enzyme blends, and yeast cultures. Single-source vulnerability around Black Sea grain corridors threatens input security. Distribution runs through bulk tanker networks for industrial bakeries and flexible bag formats for mid-scale commercial users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label mandates from EFSA and FDA are accelerating formulation disruption, creating competitive openings for suppliers with rapid regulatory dossier capabilities and enzyme innovation pipelines.
For Market Incumbents: Build regulatory affairs moats through in-house BIS certification expertise and EFSA additive authorization capabilities. Consolidate supplier relationships with enzyme houses capable of rapid clean-label reformulation. Expand backward integration into certified sustainable wheat procurement corridors to meet EU Green Deal alignment requirements and defend margin position against commodity volatility. For New Entrants and Emerging Players: Pursue underpenetrated pizza dough supply contracts in secondary Vietnamese cities where frozen-dough programs remain nascent. Target direct-to-consumer channels for premium organic variants bypassing supermarket slotting constraints. Anchor go-to-market strategy around outcome-based specifications with guaranteed yield rates for quick-service restaurant procurement teams. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with fully-managed dough programs assuming inventory risk and quality liability for large food-service chains. Long-term viability favors specialized fermentation houses with regulatory dossier capabilities and geographic diversification beyond single-source wheat corridors. Watch for inflection signals in BIS certification timeline compression for imported blend formulations entering Indian market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EFSA additive restrictions under Regulation (EC) No 1333/2008 demand rapid enzyme substitution without texture compromise. |
| Southeast Asian Capacity Expansion | Java milling clusters target export supply to Indonesian and Vietnamese bakery conversions accelerating pre-mix adoption. |
| Direct-to-Consumer Channel Development | Online retail bypasses supermarket slotting constraints for premium gluten-free and organic variant margin capture. |
| Outcome-Based Supply Contracts | Large pizza chains shift from per-pound flour procurement to yield-guaranteed fully-managed dough programs. |
| Sustainable Sourcing Certification | EU Green Deal carbon footprint labeling favors suppliers with certified wheat procurement and biodegradable packaging transitions. |
Methodological Framework
Cross-validation between primary interviews with industrial bakery operations managers and secondary trade data anchors the qualitative findings. Stakeholder consultations encompassed procurement leads at quick-service restaurant chains, regulatory affairs directors at enzyme houses, plant managers at Southeast Asian milling facilities, and category buyers at mass retail channels. Secondary sources included FDA enrichment standards documentation, EFSA additive authorization registers, BIS certification procedural filings, and customs records tracking wheat and prepared mix trade flows. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Calibration against historical volume trajectories and elasticity assumptions shaped the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, distribution channel, end-user sophistication tier, and packaging format. CAGRs derived from spline interpolation between anchor points with sensitivity testing around wheat price volatility scenarios and regulatory timeline assumptions. Industry-specific inputs included enzyme-assisted proofing time reduction adoption curves and street-food vendor conversion rates in Indonesian urban centers.
Macroeconomic conditions sit as an overlay; deviation in wheat commodity indices, freight rate volatility, or currency exchange fluctuations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline stability and clean-label reformulation R&D cycle durations. Material shifts in EFSA enzyme authorization stance or BIS certification procedural changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Instant Rice Market
Packaged Foods
Sausage Casing Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Morning Goods Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
Dried Honey Market
Packaged Foods
US Canned Foods Market
Packaged Foods
Eco Bowls Market