
 Global Morel Mushroom Market | 2026-2036
Global Morel Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Global Morel Mushroom Market Outlook
Market Context
Modular retail packs pairing dried morels with reconstitution instructions is expanding buyer choice across e-commerce and specialty grocers. South Mill Champs leverages its integrated cultivation network to supply consistent fresh volumes to food service distributors. West Coast Wild Foods anchors its position through direct relationships with Pacific Northwest foraging cooperatives. Kashmir Walnut Group differentiates via Himalayan-origin dried product lines targeting premium export channels.
Technical Definition and Segment Structure
Morel mushrooms (Morchella spp.) are edible ascomycete fungi characterized by honeycomb-patterned caps with hollow, brittle stipes; they fruit in temperate forests during spring thaws and require specific mycorrhizal or saprobic substrates for propagation. Their primary commercial purpose centers on high-value culinary applications where umami depth and textural distinction command premium positioning. Dried product lines dominate export value chains due to extended shelf stability and concentrated flavor profiles, while fresh segments capture highest per-unit margins through restaurant and direct channels. Pharmaceutical and nutraceutical applications represent emerging demand pools as bioactive compound research advances.
Regulatory Framework and Outlook
USDA organic certification and FDA food safety protocols govern interstate commerce, while EU EFSA novel food classifications shape market access for cultivated variants in European member states. China's SAMR and GB standards regulate import thresholds and pesticide residue limits for cross-border dried shipments. Stakeholders must monitor evolving foraging rights legislation and traceability mandates that increasingly determine premium market eligibility.
Market Dynamics
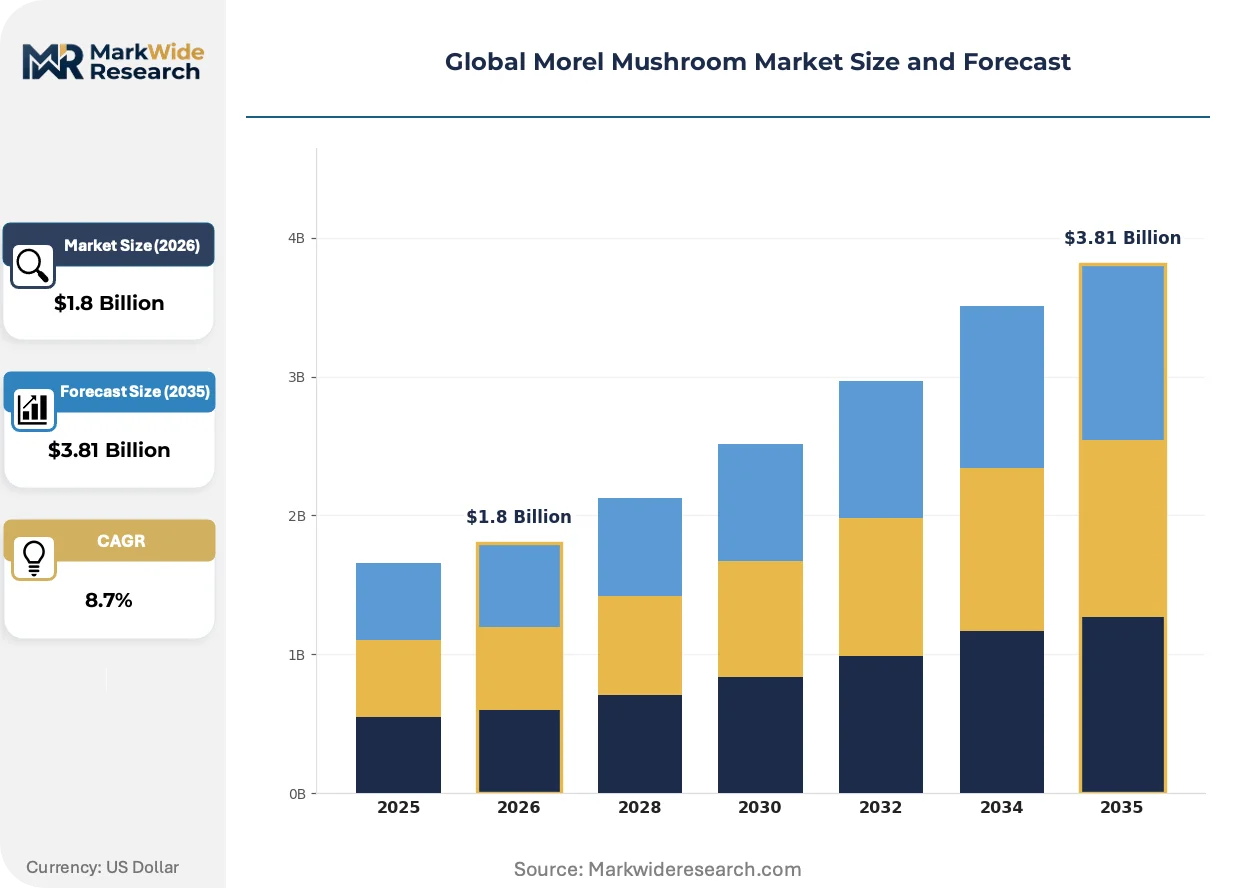
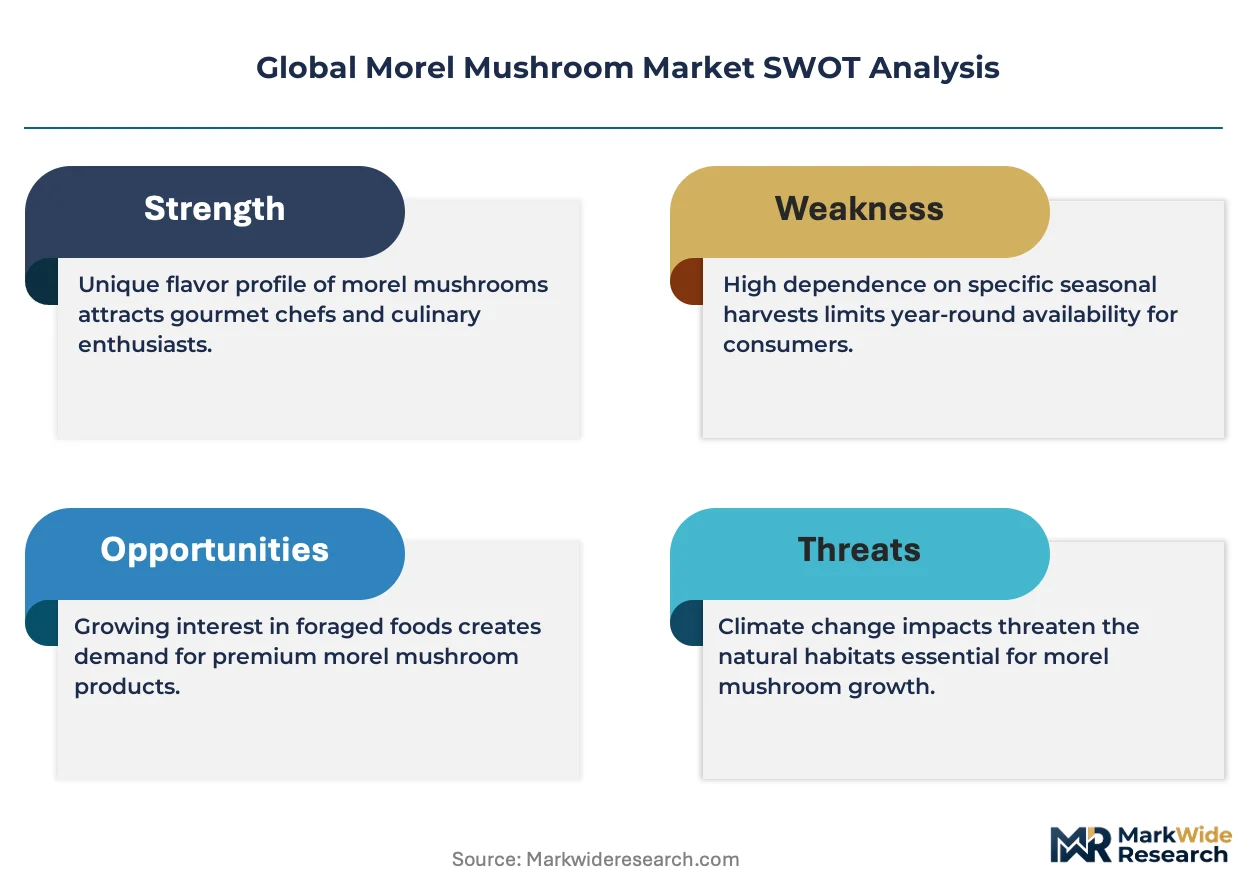
The global morel mushroom market pivots on the tension between wild-foraged supply scarcity and laboratory cultivation scale-up, with EFSA novel food classifications determining which cultivators can access European retail channels.
Growth Catalysts
- EFSA Novel Food Pathways:The EU's streamlined assessment procedures for cultivated morel variants are accelerating commercial shelf access for domesticated Morchella strains previously restricted under traditional food categories.
- Gourmet Food Service Expansion:Michelin-starred restaurants across France, Japan, and the United States are embedding fresh morels into seasonal tasting menus, creating pull-through demand for consistent supply contracts.
- Spring Foraging Tourism:Pacific Northwest cooperatives in Oregon and Washington are packaging guided harvest experiences with direct-to-consumer dried product sales, capturing value at both experience and commodity layers.
Market Restraints
- Substrate Cost Volatility:Hardwood sawdust and agricultural waste inputs for indoor cultivation fluctuate with regional lumber processing volumes, compressing margin predictability for scale operators.
- Pacific Northwest Weather Dependency:Wild harvest volumes concentrate in Oregon and Washington burn zones and riparian corridors where spring temperature and precipitation patterns determine annual yield.
- Substitution by Shiitake and Maitake:Restaurant procurement teams substitute dried Asian specialty mushrooms when morel prices spike, limiting sustained premium capture during shortage periods.
Strategic Opportunities
- Indian Export Channel Development:Kashmir Walnut Group's Himalayan sourcing infrastructure positions suppliers to capture growing Middle Eastern and Southeast Asian demand for premium dried lines.
- Nutraceutical Bioactive Extraction:Research into morel polysaccharides and antioxidant compounds is opening pharmaceutical applications beyond culinary use, with South Korean and Japanese wellness brands testing incorporation.
- Direct E-Commerce Subscription Models:Specialty grocers in Germany and the Netherlands are piloting seasonal fresh morel boxes with reconstitution guidance, bypassing traditional distributor markups.
Industry Challenges
- Mycologist Talent Scarcity:Commercial-scale sterile culture propagation requires specialized fungal biology expertise that outpaces university training pipeline output in China and the United States.
- Organic Certification Timelines:USDA three-year transition requirements for wild-foraged land designation delay premium pricing access for newly enrolled Pacific Northwest cooperative members.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Morel Mushroom Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Dried, Pickled, Frozen Application: Culinary, Pharmaceuticals, Nutraceuticals, Cosmetics Distribution Channel: Retail, Wholesale, Online, Direct End User: Restaurants, Food Services, Households, Food Manufacturers |
| Companies Covered | South Mill Champs, West Coast Wild Foods, Kashmir Walnut Group, Misty Mountain Wild Mushroom Products, Forbes Wild Foods, Gourmet Mushroom Products, Himflavours, The Danish Morel Project, Forest Mushrooms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Morel Mushroom Market Strategic Shifts
Bioreactor-based cultivation systems and precision environmental controls are compressing the production cycle for previously uncultivable morel species, while regulatory frameworks race to categorize these outputs.
Controlled-environment agriculture using sensor-networked fruiting chambers is consolidating fragmented wild supply into year-round production. Japanese pharmaceutical and food conglomerates are deploying these systems at pilot scale. The technology is consolidating seasonal price volatility into predictable contract structures that displace spot-market wild harvest dependency.
China's SAMR is tightening GB standard pesticide residue thresholds for dried mushroom imports, forcing Himalayan and Pacific Northwest exporters to deploy spectroscopy-based batch testing. The regulation is compressing informal supplier networks that previously operated without traceability documentation. European distributors are responding by demanding blockchain-verified chain-of-custody records from Chinese customs-cleared shipments.
Chef procurement teams are compressing their supplier rosters to vertically integrated cultivators capable of delivering both fresh and dried formats under single contract terms. This consolidation displaces the traditional layered structure of forager-to-cooperative-to-distributor relationships. The shift is most visible in California and New York metropolitan restaurant markets where volume consistency outweighs provenance storytelling.
Global Morel Mushroom Market Segmentation
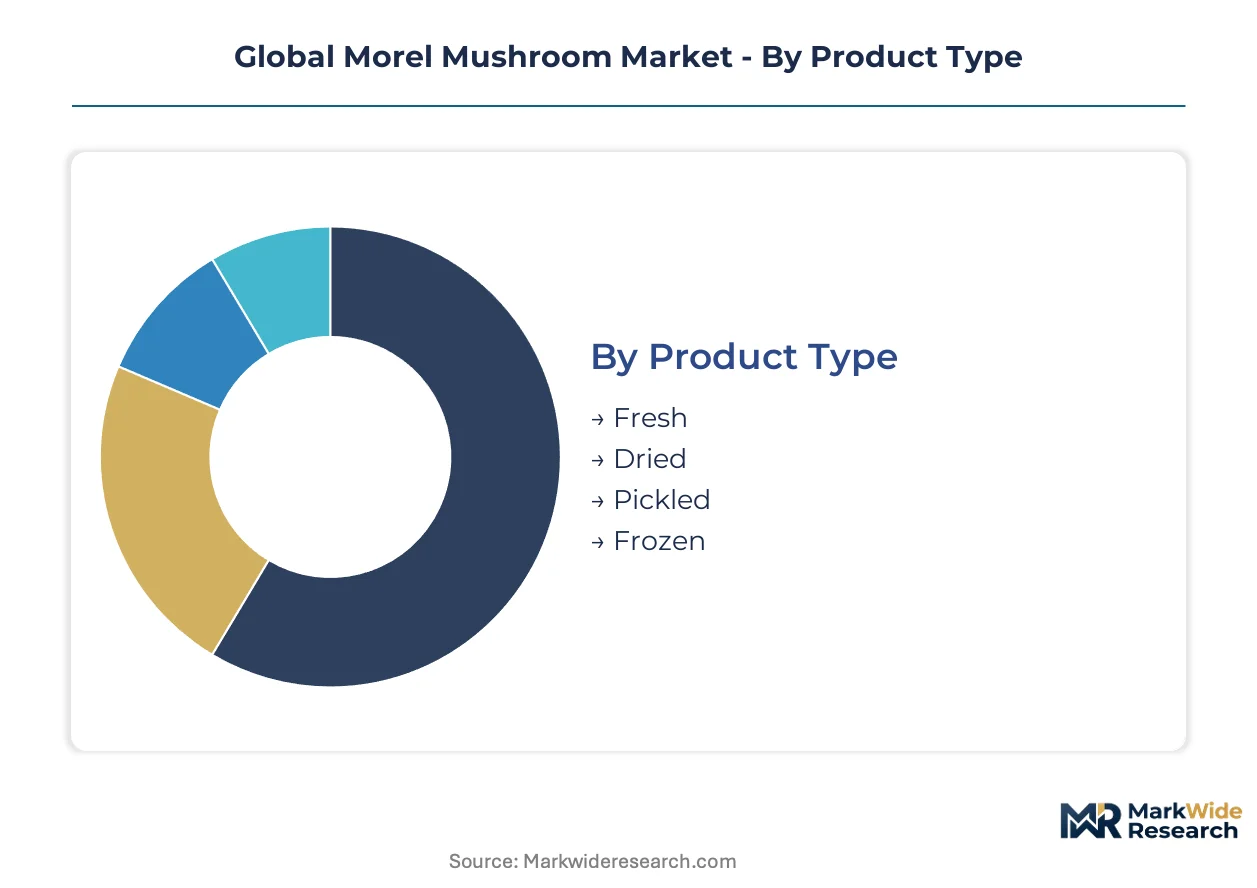
Morel mushroom buyers diverge sharply by preservation state, end-use sophistication, and procurement channel access. Each segment carries distinct margin profiles and regulatory exposure that reshape supplier positioning across value chains.
Product Type:
Buyers in this category separate by shelf-life requirements and flavor concentration needs, with premium kitchen operations willing to pay steep premiums for fresh availability.
- Fresh:Whole caps with intact honeycomb structure deliver peak umami intensity and textural distinction. Michelin-starred restaurants in France, Japan, and the United States lock in seasonal supply contracts months before spring harvests. Fresh morels command the highest per-kilogram pricing but require cold-chain logistics and tolerate zero inventory buffer.
- Dried:Dehydrated morels concentrate flavor compounds into shelf-stable formats ideal for export channels. Himalayan suppliers and Pacific Northwest cooperatives dominate this segment, with Middle Eastern and German importers driving volume. Reconstitution protocols now ship with retail packaging to reduce preparation barriers for home cooks.
- Pickled:Brine-preserved morels occupy niche appetizer and charcuterie applications, primarily in Eastern European and Scandinavian food service.
- Frozen:Flash-frozen morels extend seasonal availability for industrial food manufacturers producing year-round soup and sauce bases.
Volume sits with Dried; growth tilts toward Fresh as controlled-environment cultivation compresses seasonality.
Application:
End-use sophistication spans from commodity ingredient sourcing to bioactive compound extraction, with regulatory pathways determining market access tiers.
- Culinary:High-value restaurant plating and premium retail ingredient sales absorb the majority of harvested volume. Seasonal tasting menus at establishments across the United States, France, and Japan embed fresh morels as signature spring components. Procurement teams substitute dried formats when fresh prices spike beyond menu cost targets.
- Pharmaceuticals:Polysaccharide and antioxidant research is opening therapeutic applications beyond nutrition. South Korean and Japanese wellness brands are testing morel-derived formulations in immune-support and anti-aging product lines. EFSA novel food classifications and FDA IND pathways govern commercialization timelines.
- Nutraceuticals:Dietary supplement manufacturers incorporate dried morel powder into capsule and functional food formats targeting antioxidant-conscious consumers.
- Cosmetics:Extracts appear in premium skincare lines emphasizing natural fungal bioactives, though volumes remain marginal.
Revenue concentrates in Culinary; the steepest expansion trajectory belongs to Pharmaceuticals as clinical validation advances.
Distribution Channel:
Channel selection reflects buyer scale, geographic concentration, and tolerance for supply inconsistency.
- Retail:Specialty grocers and gourmet food stores stock dried morels with reconstitution guidance packaging. German and Dutch retailers pilot seasonal fresh subscription boxes that bypass traditional distributor markups.
- Wholesale:Food service distributors aggregate volumes from multiple cooperatives to supply restaurant chains and institutional kitchens. South Mill Champs leverages integrated cultivation networks to secure consistent wholesale contracts.
- Online:Direct-to-consumer platforms connect Himalayan and Pacific Northwest producers with global buyers, with blockchain-verified provenance increasingly required by European purchasers.
- Direct:Foraging cooperatives in Oregon and Washington sell harvests straight to restaurant chefs and experience tourists, capturing full margin but capping volume.
Wholesale handles the largest tonnage; Online is gaining share fastest as traceability technology matures.
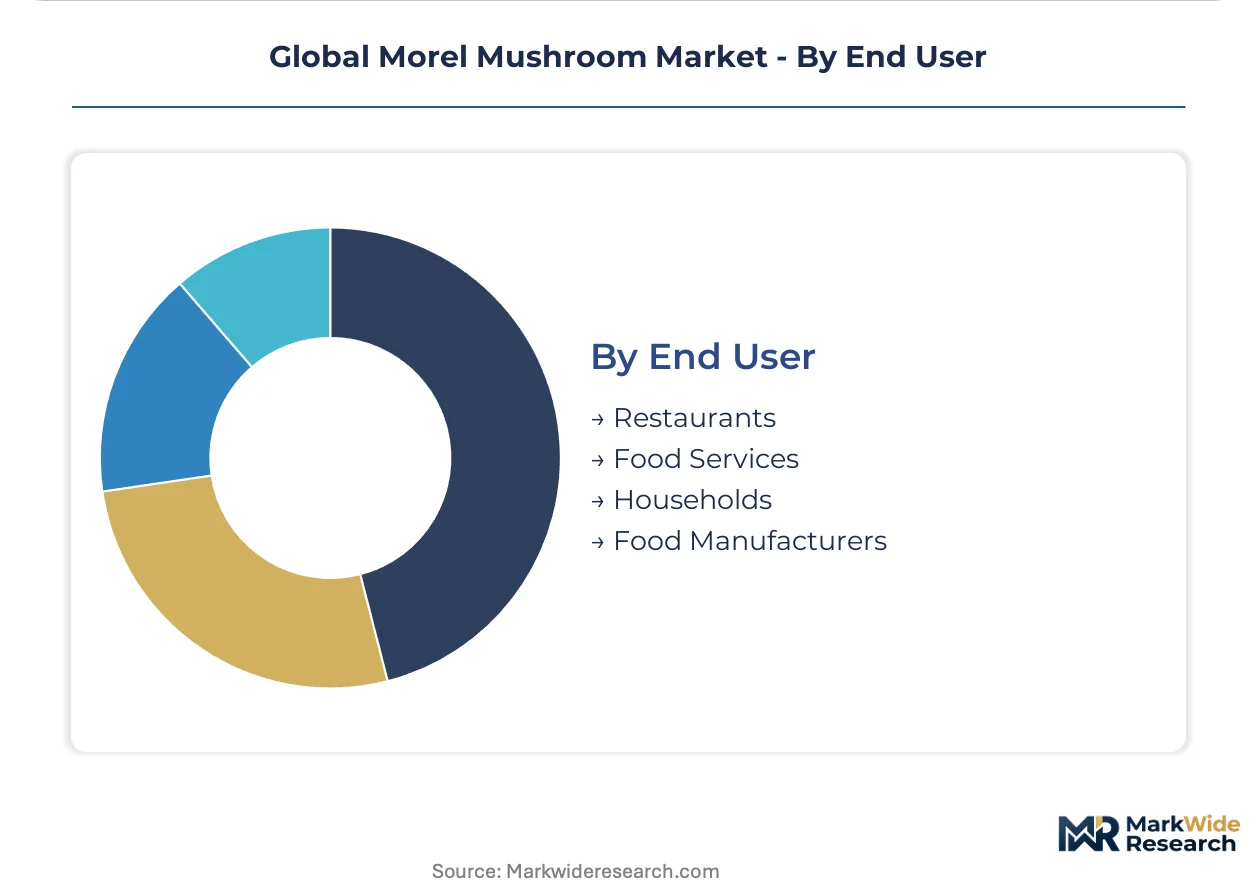
End User:
Final demand splits between experience-driven premium consumption and ingredient-cost-sensitive manufacturing.
- Restaurants:Seasonal menu integration at fine-dining establishments creates pull-through demand for consistent fresh supply. California and New York metropolitan markets consolidate procurement to vertically integrated cultivators capable of dual-format delivery.
- Food Services:Contract caterers and institutional kitchens substitute dried morels into standardized recipes when fresh availability fails.
- Households:Home cooks purchase dried retail packs for special-occasion preparation, with reconstitution instruction quality determining repeat purchase rates.
- Food Manufacturers:Processors of premium soups, sauces, and ready meals source frozen or dried inputs under annual volume contracts with price adjustment clauses.
Restaurants anchor premium pricing; Food Manufacturers drive baseline volume with tight cost specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wild harvests dominate supply from the Pacific Northwest of the United States and Himalayan Kashmir, while consumption concentrates in French, Japanese, and German restaurant markets. Cultivation scale-up in China and Denmark is compressing seasonal price volatility. Regulatory divergence between FDA food safety protocols and EFSA novel food classifications is fragmenting market access pathways.
United States
Oregon and Washington host the densest foraging cooperative networks, supplying fresh morels to California and New York metropolitan restaurant markets. FDA food safety protocols and USDA organic certification govern interstate commerce, with three-year transition timelines delaying premium pricing for newly enrolled wild harvesters. The Pacific Northwest burn zone ecology produces concentrated spring yields that fluctuate with precipitation patterns.
France
Michelin-starred restaurants in Paris and Lyon anchor European fresh morel demand through seasonal tasting menu integration. EFSA novel food classifications determine which cultivated Morchella strains access retail channels, favoring domesticated variants with completed safety assessments. The Rhône-Alpes region hosts specialized distributors bridging Alpine foraging zones with high-end food service procurement.
Germany
Specialty grocers in Berlin and Munich pilot direct-to-consumer fresh morel subscription boxes that bypass traditional distributor markups. REACH chemical safety regulations and EU organic standards govern import thresholds for dried Himalayan shipments. Bavarian food manufacturers source frozen inputs for year-round soup and sauce production under annual volume contracts.
China
SAMR and GB standards regulate pesticide residue limits for dried morel exports, forcing spectroscopy-based batch testing at Himalayan and Pacific Northwest origin points. Sichuan and Yunnan provinces host pilot-scale bioreactor cultivation facilities deploying sensor-networked fruiting chambers. Domestic consumption concentrates in Shanghai and Beijing premium restaurant markets.
India
Kashmir Walnut Group anchors Himalayan-origin dried product lines targeting Middle Eastern and Southeast Asian export channels. FSSAI food safety standards and DGFT export documentation requirements govern cross-border shipment eligibility. The Kashmir Valley's altitude-dependent fruiting ecology produces concentrated spring harvests with distinct provenance signaling for premium positioning.
Global Morel Mushroom Market Competitive Environment
The competitive structure tilts toward vertically integrated cultivators capable of delivering dual-format supply under single contract terms. Wild-foraging cooperatives retain margin capture advantages in fresh segments but face volume caps from ecological constraints. Three archetypes dominate: Pacific Northwest cooperative aggregators, Himalayan dried exporters, and controlled-environment cultivation specialists. Competitive moves center on backward integration into sterile culture propagation and geographic expansion through distributor partnership networks.
Among North American cooperative aggregators, South Mill Champs and West Coast Wild Foods occupy positions spanning cultivation networks and direct forager relationships. Kashmir Walnut Group exemplifies the Himalayan-origin dried export archetype with premium channel focus. At the controlled-environment cultivation end, The Danish Morel Project represents European laboratory-scale domestication efforts navigating EFSA regulatory pathways.
| Leading Market Players |
|---|
| South Mill Champs |
| West Coast Wild Foods |
| Kashmir Walnut Group |
| Misty Mountain Wild Mushroom Products |
| Forbes Wild Foods |
| Gourmet Mushroom Products |
| Himflavours |
| The Danish Morel Project |
| Forest Mushrooms |
| Others |
Value Chain & Pricing Dynamics
Bioreactor-based cultivation systems are compressing production cycles for previously uncultivable Morchella species while simultaneously redistributing cost economics from wild-foraged scarcity premiums toward predictable contract pricing. This technological shift concentrates supply power among controlled-environment operators capable of year-round output, fragmenting the traditional Pacific Northwest cooperative dominance.
Pricing Analysis
Margin tightening in fresh segments reflects the expansion of controlled-environment capacity in China and Denmark. Three-tier pricing structure across premium wild-foraged, standard cultivated fresh, and economy dried formats stratifies buyer access. Cost-down pressure on dried Himalayan exports accelerates because China's SAMR is tightening GB standard pesticide residue thresholds. Food manufacturers exhibit highest price sensitivity, while Michelin-starred restaurants absorb premium wild-foraged premiums without volume elasticity.
Supply Chain Analysis
USDA organic certification and EFSA novel food classifications gate market access for suppliers targeting European and North American premium channels. Wild harvest concentration in Oregon, Washington, and Kashmir feeds from burn zone ecology and altitude-dependent spring fruiting patterns. Hardwood sawdust substrate costs fluctuate with regional lumber processing volumes, creating single-source vulnerability for indoor cultivators. Distribution runs through food service distributors in California and New York metropolitan markets, with direct-to-consumer platforms gaining share in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-environment agriculture is displacing wild-foraged dependency as the dominant supply paradigm, with sensor-networked fruiting chambers replacing seasonal burn zone harvesting.
For Market Incumbents: Lock in sterile culture propagation expertise through university pipeline partnerships before mycologist talent scarcity worsens. Secure dual-format supply contracts with California and New York restaurant procurement teams consolidating vendor rosters. Invest in blockchain-verified traceability systems before European distributors mandate chain-of-custody documentation.
For New Entrants and Emerging Players: EFSA novel food streamlined assessment procedures in Europe open a window for laboratory-domesticated Morchella strains previously restricted from retail channels. Target pharmaceutical and nutraceutical applications in South Korea and Japan where bioactive compound research is advancing commercialization timelines. Deploy direct e-commerce subscription models in German and Dutch markets bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of controlled-environment cultivation specialists with completed regulatory dossiers. Five-to-ten year viability hinges on bioreactor scale-up economics achieving cost parity with wild-foraged premiums. Watch for EFSA novel food classification approvals as inflection indicators for European market access valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Cultivation Scale-Up | Sensor-networked fruiting chambers in Sichuan and Yunnan compress seasonal price volatility into predictable contract structures. |
| Regulatory Approval Pathway | EFSA novel food classifications determine which domesticated Morchella strains access European retail and food service channels. |
| Backward Integration | In-house sterile culture propagation reduces dependency on university-trained mycologists facing pipeline shortages. |
| Direct-to-Consumer Launch | Seasonal fresh subscription boxes in Berlin and Munich bypass traditional food service distributor markups. |
| Blockchain Traceability Investment | Verified chain-of-custody records satisfy European distributor demands following China's SAMR GB standard tightening. |
Study Parameters
Document review covered FDA food safety protocols, EFSA novel food classification registers, and China's SAMR GB standards, complemented by interviews with foraging cooperative managers, food service procurement directors, specialty grocer category buyers, and controlled-environment cultivation technicians. Secondary sources included USDA organic certification databases, customs and trade flow records, and restaurant industry procurement surveys. Bottom-up volume estimates from cultivation facility outputs were triangulated against top-down demand assessments from food service distributor contracts.
Cross-referencing historical price volatility patterns against expert panel inputs on bioreactor adoption timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include preservation state, end-use application, distribution channel, and geographic regulatory cluster. CAGRs were derived from supply-side capacity buildouts and demand-side menu integration rates. Key inputs included spring precipitation patterns in Pacific Northwest burn zones and EFSA assessment completion timelines for cultivated variants.
The model assumes a particular technology adoption path for bioreactor-based cultivation; alternative pathways for wild-foraged supply stabilization would alter the outlook. Forecasts reflect assumptions about regulatory approval velocities and substrate cost trajectories. A model refresh is warranted upon material change in EFSA novel food classification throughput or Pacific Northwest burn zone ecology regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Global Garcinia Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
Dry Beans Market
Fruits and Vegetables
APAC Frozen Fruits and Vegetables Market
Fruits and Vegetables
Mexico Fruits & Vegetables Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Banana Puree Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
United States Frozen Fruits and Vegetables Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Date Fruit Market