
 Canned Goods Market | 2026-2036
Canned Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Goods Market Insights
BRCGS Food Safety certification is reorganizing supplier eligibility across European retail channels, forcing smaller canneries into costly upgrade cycles. Nestle sustains category leadership through its frozen-to-ambient portfolio bridge and retailer co-development programs. Bonduelle anchors the vegetable segment with its vertically controlled agricultural supply base across northern France. Campbell Soup Company navigates private-label compression by specializing in premium condensed formats with heritage positioning.
Canned goods comprise thermally processed foodstuffs sealed in hermetic metal, glass, or composite containers to achieve commercial sterility, typically involving retort temperatures of 116–121°C to eliminate Clostridium botulinum spores and enable ambient shelf stability from 12 to 60 months depending on acidity and packaging barrier properties. Steel can formats retain dominant volume share in fish and meat categories where oxygen barrier demands are highest, while aluminum and Tetra Pak alternatives are gaining fastest in fruit and ready-meal segments where lightweighting and microwave compatibility drive substitution. Retailers capture the largest margin pools in private-label vegetable and fruit lines, whereas branded meat and fish products command premium positioning through species provenance claims.
EU F-Gas Regulation and REACH compliance on epoxy-based can coatings are redirecting capital toward polyester and oleoresin lining R&D, with EFSA migration limits setting the technical boundary for new material validation. National regulators in Germany, France, and Italy enforce divergent deposit-return and extended producer responsibility schemes that fragment packaging compliance costs across the value chain. Stakeholders must monitor pending revisions to the EU Packaging and Packaging Waste Regulation to determine whether recycled content mandates will favor steel over aluminum sourcing strategies.
Market Dynamics
EU Packaging Directive revisions and REACH-mandated BPA phase-outs are forcing simultaneous material transitions across steel can linings, polyester coating R&D, and oleoresin validation protocols. This regulatory compression is reshaping capital allocation priorities for European canneries.
Growth Catalysts
- Ambient-ready meal penetration:Retailers in Germany and France are dedicating expanded shelf space to ready-to-eat canned formats as household adoption accelerates for convenience-oriented meal solutions.
- REACH compliance acceleration:Epoxy-based lining restrictions under ECHA mandates are redirecting investment toward polyester and oleoresin alternatives, creating first-mover advantages for compliant suppliers.
- Private-label procurement restructuring:Supermarket chains are consolidating vegetable and fruit sourcing through vertically integrated canneries, compressing supplier counts while raising volume commitments.
Market Restraints
- Steel price volatility:Tinplate and electrolytic chromium-coated steel input costs fluctuate with energy-intensive smelting economics, squeezing margin predictability for metal-dependent formats.
- Coating migration limits:EFSA technical boundaries on substance migration from can linings extend validation timelines for new materials, delaying commercialization of BPA-free alternatives.
- Deposit-return fragmentation:Divergent extended producer responsibility schemes across Germany, France, and Italy complicate packaging compliance cost allocation and reverse logistics design.
Strategic Opportunities
- Microwave-compatible aluminum expansion:Lightweight aluminum formats with modified barrier properties are capturing ready-meal share from steel as convenience-oriented consumers prioritize reheating speed.
- Recycled content mandates:Pending EU Packaging and Packaging Waste Regulation revisions may favor steel sourcing strategies with higher post-consumer scrap incorporation rates.
- E-commerce ambient fulfillment:Direct-to-consumer subscription models for specialty canned fish and heritage-positioned condensed soups are bypassing traditional retail margin capture.
Industry Challenges
- BRCGS certification timelines:Smaller canneries face 12-18 month upgrade cycles to meet Food Safety certification requirements for European retail channel eligibility, straining working capital.
- Retort equipment reconfiguration:Transitioning from steel to aluminum or composite formats requires capital-intensive autoclave modifications for pressure-temperature profile compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Goods Market |
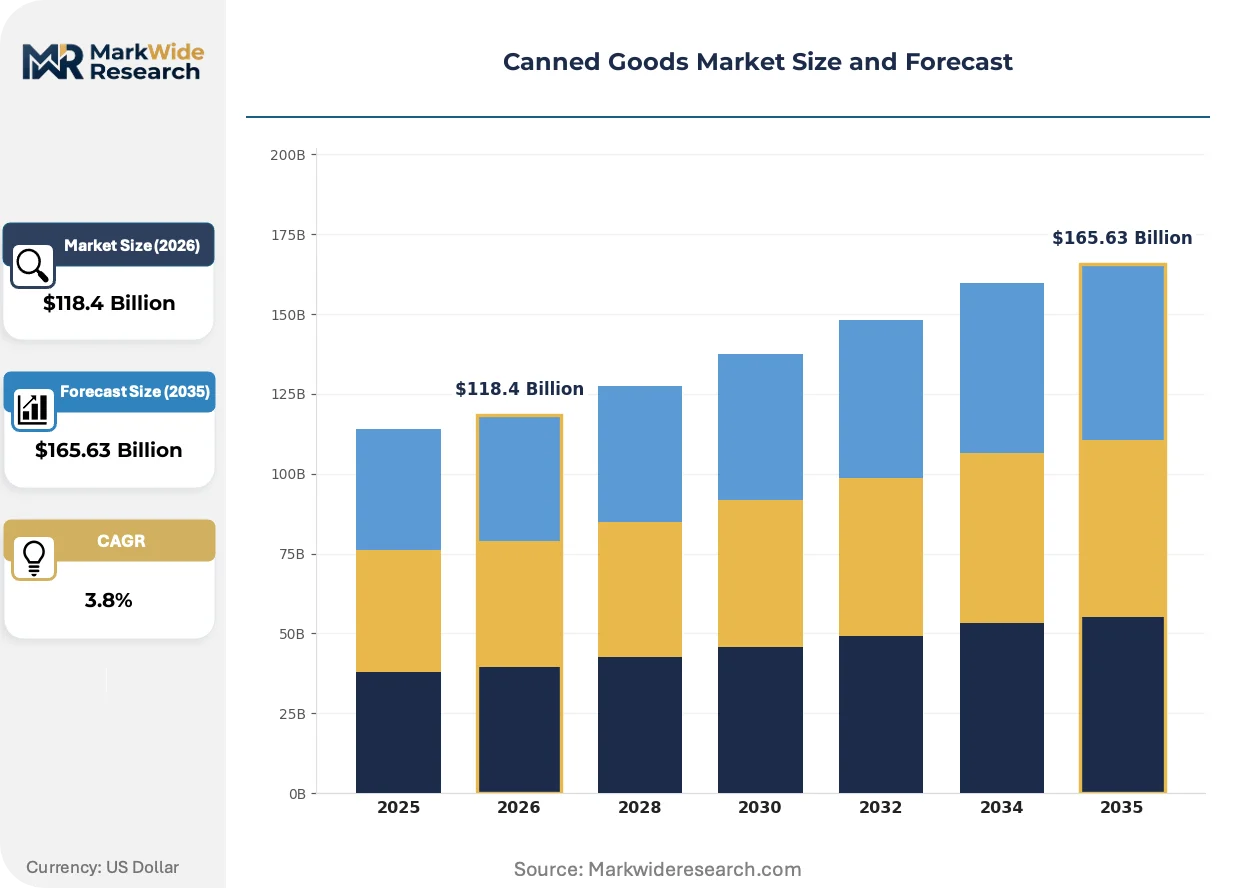
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $165.63 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Fruits, Meat, Fish Packaging Type: Aluminum Can, Steel Can, Glass Jar, Tetra Pak End User: Retailers, Food Service, Households, Institutions Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesale |
| Companies Covered | Hormel Foods Corporation, Bolton Group, Kraft Heinz Company, Nestle, General Mills, Campbell Soup Company, Del Monte Pacific Limited, Bonduelle, Conagra Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Goods Market Trends and Innovations
Material science advances and regulatory chemistry constraints are splitting the canning industry into divergent technical pathways. Coatings, substrates, and thermal processing methods are evolving along separate trajectories.
Polyester-oleoresin hybrid linings are bifurcating the barrier coatings segment as EFSA migration limits harden technical boundaries. Premium meat and fish canneries are accelerating validation of these alternatives to maintain retail access, while value-oriented vegetable processors delay transition pending cost parity. This technical divergence is compressing mid-tier suppliers unable to fund dual-track R&D portfolios.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon availability for industrial refrigeration across cannery cold chains. Processing facilities in northern France and northern Italy are retrofitting ammonia-based systems or investing in transcritical CO2 infrastructure. Fish canneries with high throughput dependence on blast freezing capacity face the steepest compliance cost escalations.
Retailer co-development programs are displacing arm's-length supplier relationships in private-label vegetable and ready-meal categories. German and UK supermarket chains are embedding technical staff directly within cannery operations to synchronize NPD timelines with seasonal agricultural supply. This channel consolidation is visible most acutely in the United Kingdom, where four retail groups now control over sixty percent of ambient vegetable procurement volume.
Canned Goods Market Segmentation
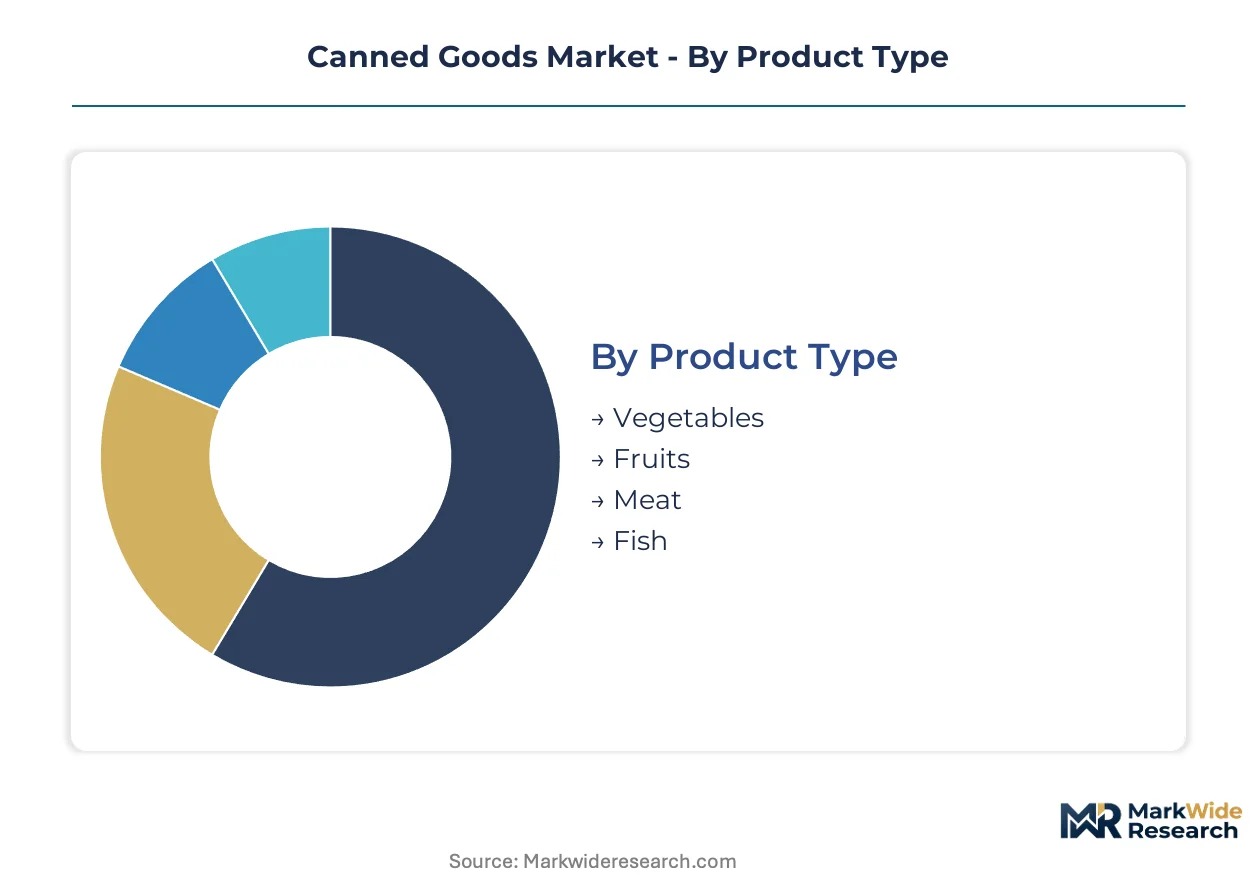
Segmentation in the canned goods market reveals divergent margin structures and channel access patterns. Each dimension—product composition, packaging substrate, end-use application, and distribution pathway—carries distinct regulatory burdens and capital intensity profiles that reshape supplier positioning.
Product Type:
Channel mix varies sharply across product categories, with vegetable and fruit lines dominating private-label supermarket penetration while meat and fish formats concentrate in branded premium positioning.
- Vegetables:Thermally processed legumes, tomatoes, and mixed greens sealed in hermetic containers with 24-36 month ambient stability. Demand concentrates in German and French retail channels where Bonduelle's vertically integrated northern French agricultural base supplies major supermarket chains under co-development arrangements. EFSA migration limits on epoxy linings are accelerating polyester-oleoresin validation for acidic tomato varieties.
- Fish:Tuna, sardine, and mackerel products requiring oxygen-barrier steel formats to prevent lipid oxidation. Norwegian and Spanish canneries anchor supply, with ECHA BPA phase-outs forcing simultaneous lining transitions across high-acid oil-packed and brine-packed formats. EU F-Gas Regulation compliance costs hit hardest here due to blast freezing dependence.
- Fruits:Peaches, pears, and tropical varieties in syrup or juice, increasingly packed in lightweight aluminum for single-serve convenience. Migration from steel is accelerating in German discount retail channels.
- Meat:Corned beef, ham, and poultry products with heritage positioning in UK and Irish markets. Condensed soup formats in this category command premium shelf placement through provenance claims.
Vegetables dominate installed base. Fish is where expansion concentrates.
Packaging Type:
Cost tier stratification separates commodity steel formats from premium aluminum and composite alternatives, with capital equipment requirements determining supplier eligibility.
- Steel Can:Tinplate and electrolytic chromium-coated steel with epoxy or emerging polyester-oleoresin linings. Retains dominant share in fish and meat categories where oxygen barrier demands are highest. German and Italian canneries face 12-18 month BRCGS Food Safety certification upgrade cycles to maintain retail channel access.
- Aluminum Can:Lightweight two-piece drawn formats with modified barrier coatings enabling microwave compatibility. French and UK ready-meal segments are adopting these for reheating speed, though EFSA migration validation timelines delay full BPA-free conversion.
- Glass Jar:Premium fruit and vegetable presentations for specialty retail and direct-to-consumer subscription channels. Higher freight costs limit penetration in mass-market wholesale.
- Tetra Pak:Aseptic carton formats gaining share in fruit and ready-meal segments through lightweighting advantages. Deposit-return scheme fragmentation across Germany, France, and Italy complicates reverse logistics design for this substrate.
Steel commands volume economics. Aluminum is climbing the fastest on convenience-driven substitution.
End User:
Customer type determines specification stringency, with institutional procurement requiring BRCGS certification while household direct-to-consumer channels bypass traditional retail margin capture.
- Retailers:Supermarket chains and discount operators controlling ambient shelf space allocation. German and UK retail groups now direct over sixty percent of vegetable procurement through embedded technical staff in cannery operations.
- Households:Individual consumers purchasing through supermarkets, convenience stores, and emerging e-commerce subscription models for specialty fish and heritage condensed soups.
- Food Service:Restaurants, cafeterias, and catering operations sourcing institutional-size formats with simplified procurement specifications.
- Institutions:Hospitals, schools, and military procurement requiring highest-tier food safety certification and documented supply chain traceability.
Retailers anchor volume commitments. Households are gaining share fastest through e-commerce ambient fulfillment.
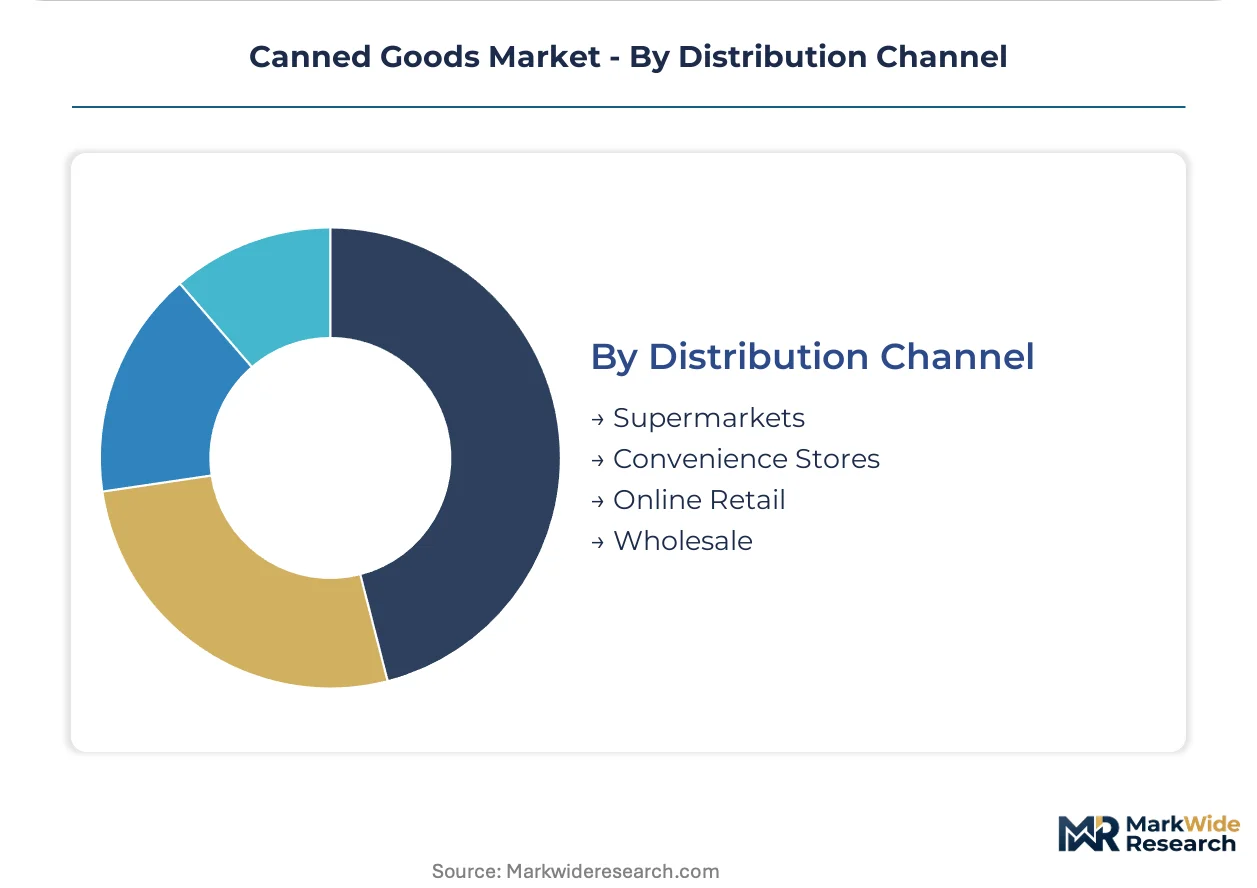
Distribution Channel:
Geographic concentration of procurement power shapes channel strategy, with northern European supermarket consolidation forcing supplier consolidation in response.
- Supermarkets:Full-service retail chains in Germany, France, and the United Kingdom dedicating expanded shelf space to ambient-ready meals. Private-label vegetable and fruit lines capture the largest margin pools here.
- Online Retail:Direct-to-consumer platforms enabling heritage-positioned condensed soups and specialty canned fish to bypass traditional retail margin structures. Subscription models are emerging in UK and German urban clusters.
- Convenience Stores:Urban and transit-oriented formats prioritizing single-serve aluminum formats for immediate consumption.
- Wholesale:Cash-and-carry and food service distributors handling institutional volumes with lower certification barriers but compressed pricing.
Supermarkets dominate procurement concentration. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supermarket procurement concentration defines geographic demand patterns. German, French, and British retail groups control ambient shelf allocation through embedded technical staff. National deposit-return schemes and coating compliance timelines fragment supplier economics.
Germany
Discount retail chains drive private-label vegetable volume through vertically integrated northern European suppliers. The country's national packaging regulator enforces strict extended producer responsibility schemes that elevate steel can recycling compliance costs. The Hamburg-Bremen port cluster handles bulk tomato and legume imports for processing facilities across Lower Saxony.
France
Co-development arrangements between supermarket chains and canneries dominate ready-meal procurement. ECHA mandates on epoxy-based linings accelerate polyester-oleoresin validation for acidic tomato varieties. The Hauts-de-France agricultural belt anchors Bonduelle's captive vegetable supply base.
United Kingdom
Four retail groups now direct over sixty percent of ambient vegetable procurement through technical staff embedded in supplier operations. BRCGS Food Safety certification requirements compress smaller canneries into twelve-to-eighteen month upgrade cycles. London and the Southeast concentrate e-commerce subscription models for heritage-positioned condensed soups.
Italy
Fish canneries face steep EU F-Gas Regulation compliance costs due to blast freezing dependence in tuna and sardine processing. The national environmental ministry enforces divergent deposit-return timelines that complicate aluminum format reverse logistics. Ligurian and Sicilian coastal facilities retrofit ammonia-based refrigeration systems.
Spain
Galician and Basque canneries anchor European tuna and mackerel supply with oxygen-barrier steel formats. EFSA migration limits extend validation timelines for BPA-free lining alternatives. Barcelona and Valencia ports facilitate bulk fish imports for high-throughput processing operations.
Canned Goods Market Competitive Landscape
Player mix skews toward diversified food conglomerates with frozen-to-ambient portfolio bridges and vertically integrated agricultural specialists. The vendor base concentrates around three strategic archetypes: multinational packaged food corporations with retailer co-development programs, regional canneries with captive supply bases, and private-label specialists serving supermarket consolidation. Competitive dynamics center on BRCGS certification acquisition and coating technology transitions rather than price warfare.
Among diversified food conglomerates, Nestle and Kraft Heinz occupy positions defined by portfolio breadth and retail channel access. Bonduelle exemplifies the vertically integrated agricultural archetype with its northern French supply base. Campbell Soup Company sits within the heritage-positioned premium tier. These three anchors represent distinct competitive vectors: multinational scale, upstream supply control, and brand equity in condensed formats.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| Bolton Group |
| Kraft Heinz Company |
| Nestle |
| General Mills |
| Campbell Soup Company |
| Del Monte Pacific Limited |
| Bonduelle |
| Conagra Brands |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day tinplate order lead times concentrate procurement leverage among German and French retail groups with volume commitments, compressing margin recovery for smaller canneries caught between steel price volatility and fixed-price private-label contracts. This inventory-to-pricing feedback loop rewards backward integration into northern French vegetable supply bases while penalizing spot-market metal sourcing.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange tinplate benchmarks dominate German and French supermarket procurement, with quarterly price adjustments passing through energy-intensive smelting cost swings. Three-tier pricing structure across premium heritage-positioned condensed soups, standard private-label vegetables, and economy discount fruit lines separates Bonduelle's co-development arrangements from commodity spot suppliers. Pricing pressure stems from REACH-mandated BPA lining transitions extending polyester-oleoresin validation timelines and elevating R&D amortization. Discount retail chains exhibit highest price sensitivity, while heritage-positioned UK meat canneries maintain lowest elasticity through provenance claims.
Supply Chain Analysis
Strategic stockpiling of tinplate and electrolytic chromium-coated steel prevails among northern French and German canneries facing energy-intensive smelting volatility, while just-in-time aluminum sourcing dominates UK ready-meal processors prioritizing lightweighting flexibility. Supply concentrates in Germany, France, and Spain, with Galician fish canneries and Hauts-de-France vegetable processors anchoring European volume. Raw material dependencies rest on Malaysian tin ore, Brazilian iron ore, and Gulf petrochemical feedstocks for coating resins. Single-source vulnerability in epoxy lining chemistry creates compliance risk as ECHA phase-outs accelerate. Distribution runs through Rotterdam and Hamburg port clusters feeding supermarket consolidation in Germany, France, and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ambient-ready meal penetration in German and French households signals early-cycle expansion, with retailer co-development programs creating durable volume commitments for compliant suppliers. This adoption tailwind favors capital deployment into BPA-free lining validation and BRCGS certification acquisition ahead of regulatory enforcement tightening.
For Market Incumbents: Consolidate procurement relationships through embedded technical staff arrangements mirroring UK supermarket consolidation patterns, while accelerating polyester-oleoresin lining validation to capture REACH-compliant shelf space before smaller competitors complete 12-18 month BRCGS upgrade cycles. Threat from aluminum format substitution in ready-meal segments demands microwave-compatible barrier coating R&D investment. Priority lever: backward integration into northern French or Spanish agricultural supply bases to secure volume commitments under co-development structures. For New Entrants and Emerging Players: Lead with direct-to-consumer subscription models for heritage-positioned condensed soups and specialty canned fish, bypassing supermarket margin capture concentrated among four UK retail groups. White-space targets include e-commerce ambient fulfillment in London and German urban clusters, plus microwave-compatible aluminum formats for convenience-oriented ready-meal segments. Most penetrable entry point: online retail channels where BRCGS certification requirements are less stringent than institutional procurement. Go-to-market angle: provenance storytelling paired with deposit-return scheme compliance for German environmental regulator adherence. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with frozen-to-ambient portfolio bridges, particularly vegetable and fruit canneries lacking vertical integration into agricultural supply. Long-term viability over a 5-10 year horizon hinges on REACH compliance completion and retailer co-development program penetration. Acquisition archetype: mid-cap canneries with validated polyester-oleoresin linings and existing BRCGS certification. Signal to watch: EU Packaging and Packaging Waste Regulation recycled content mandate revisions favoring steel sourcing strategies with higher post-consumer scrap incorporation rates.| Strategic Initiative | Industry Significance |
|---|---|
| Polyester-Oleoresin Lining Validation | REACH compliance secures retail channel access under ECHA epoxy phase-out mandates. |
| Retailer Co-Development Program Expansion | Embedded technical staff arrangements lock in volume commitments from German and French supermarket chains. |
| Microwave-Compatible Aluminum Format Launch | Convenience-oriented reheating speed captures ready-meal share from steel formats in UK urban markets. |
| Direct-to-Consumer E-Commerce Buildout | Subscription models bypass supermarket margin compression for heritage-positioned condensed soups. |
| Backward Integration into Agricultural Supply | Captive northern French vegetable bases replicate Bonduelle's procurement leverage with retail chains. |
Research Methodology
Cross-validation between primary interviews with cannery operations directors, supermarket category buyers, coating R&D specialists, and cold chain logistics managers and secondary sources including EFSA migration limit databases, ECHA REACH substance restrictions, and EU F-Gas Regulation phase-down schedules anchors the qualitative findings. Bottom-up triangulation across product-type volume estimates and top-down validation against retail audit data from Nielsen and Circana ensures segmentation integrity. Customs records for tinplate and aluminum can imports through Rotterdam and Hamburg ports provide substrate-level demand calibration.
Sensitivity analysis around steel price volatility bands, REACH compliance timeline scenarios, and retailer procurement consolidation rates frames the forecast uncertainty. The analytical framework models demand across product type, packaging substrate, end-user category, and distribution channel dimensions throughout the projection horizon. CAGRs derive from segment-level volume trajectories weighted by price realization trends in private-label versus branded channels. Industry-specific inputs include EFSA migration limit enforcement intensity and EU Packaging Directive recycled content mandate adoption curves.
Forecasts assume regulatory continuity in REACH, EU F-Gas Regulation, and national extended producer responsibility schemes; material policy shifts would require re-modeling. Specific risks include accelerated BPA lining prohibitions, divergent deposit-return scheme harmonization failures across Germany, France, and Italy, and energy cost spikes disrupting tinplate smelting economics. Revision becomes warranted when aluminum format substitution rates in ready-meal segments exceed baseline assumptions or when BRCGS certification delays compress compliant supplier counts below critical retail channel access thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
India Instant Noodles Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Ready-To-Eat Food Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Canned Soup Market
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Brio Bowls Market