
 Packaged Salad Market | 2026-2036
Packaged Salad Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Salad Market Intelligence
Health-conscious millennials is redrawing demand patterns across the packaged salad category, pulling volume from traditional household grocery buyers toward foodservice operators seeking premium pre-washed blends. Taylor Farms leverages its coast-to-coast processing network to dominate supply contracts with major restaurant groups. Dole Food Company Inc. sustains brand recognition through retail bagged lines that anchor shelf space in conventional supermarkets. Gotham Greens differentiates through controlled-environment agriculture, positioning its hyperlocal greens as a premium alternative to field-grown competitors.
Packaged salad consists of pre-washed, cut, and blended leafy vegetables—typically maintained at 34–38°F through cold-chain distribution to preserve crispness and nutritional density—designed for immediate consumption without further preparation. Mixed Greens leads product type volume due to broad consumer familiarity and menu versatility across both retail and foodservice channels, while Single-Serve packaging captures the fastest expansion as on-the-go meal occasions multiply. Clamshell formats command margin pools among organic SKUs where visual quality verification drives purchase decisions.
The FDA enforces the Food Safety Modernization Act's Produce Safety Rule, mandating agricultural water testing and harvest equipment sanitation that elevates compliance costs for smaller growers. USDA Organic certification shapes demand by restricting synthetic pesticide use and requiring third-party verification, creating a dual-track market structure. Stakeholders must monitor how state-level extended producer responsibility laws for plastic packaging reshape material choices across bagged and clamshell formats.
Market Dynamics
The FDA's updated Leafy Greens Safety Rule is compressing processing margins while concentrating supply contracts among operators with coast-to-coast cold-chain infrastructure. This regulatory tightening is redrawing competitive boundaries between integrated processors and regional growers lacking traceability systems.
Growth Catalysts
- Foodservice Expansion:Quick-service restaurant chains are pulling volume from retail channels through premium pre-washed blends designed for immediate menu deployment. This channel rotation is accelerating contract consolidation among multi-location operators.
- Controlled-Environment Agriculture:Hydroponic and greenhouse production systems are insulating supply from climate volatility while enabling year-round harvest cycles. These facilities are capturing urban demand clusters previously served by field-grown imports.
- USDA Organic Certification:Third-party verification restricting synthetic pesticide use is creating price-premium capture opportunities for growers with compliant acreage. Dual-track market structures now separate certified and conventional supply pools.
Market Restraints
- Agricultural Input Volatility:Fertilizer and irrigation energy costs are squeezing field-grown margins, particularly for Central Valley operators dependent on surface water allocations.
- Processing Concentration Risk:Coast-to-coast processing networks are controlled by a handful of integrated operators, creating single-source vulnerability for restaurant groups without redundant supplier relationships.
- Perishability Constraints:The 34–38°F cold-chain requirement limits distribution radius and elevates spoilage losses for smaller distributors lacking temperature-controlled logistics.
Strategic Opportunities
- Single-Serve Format Expansion:On-the-go meal occasions are multiplying across urban employment centers, creating white space for portable clamshell formats in convenience retail channels.
- Extended Producer Responsibility Laws:State-level mandates for plastic packaging recovery are incentivizing fiber-based alternatives and reusable container programs that differentiate premium SKUs.
- Hyperlocal Urban Production:Rooftop greenhouse installations are collapsing farm-to-fork distance in metropolitan markets, capturing freshness premiums from consumers with traceability preferences.
Industry Challenges
- Traceability System Integration:Harvest equipment sanitation logs and agricultural water testing records must interface with blockchain-based tracking platforms, demanding IT infrastructure investments beyond smaller grower capabilities.
- Sanitation Compliance Timeline:The Produce Safety Rule's harvest equipment mandates are compressing seasonal preparation windows, requiring capital deployment for wash-line upgrades ahead of planting cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Salad Market |
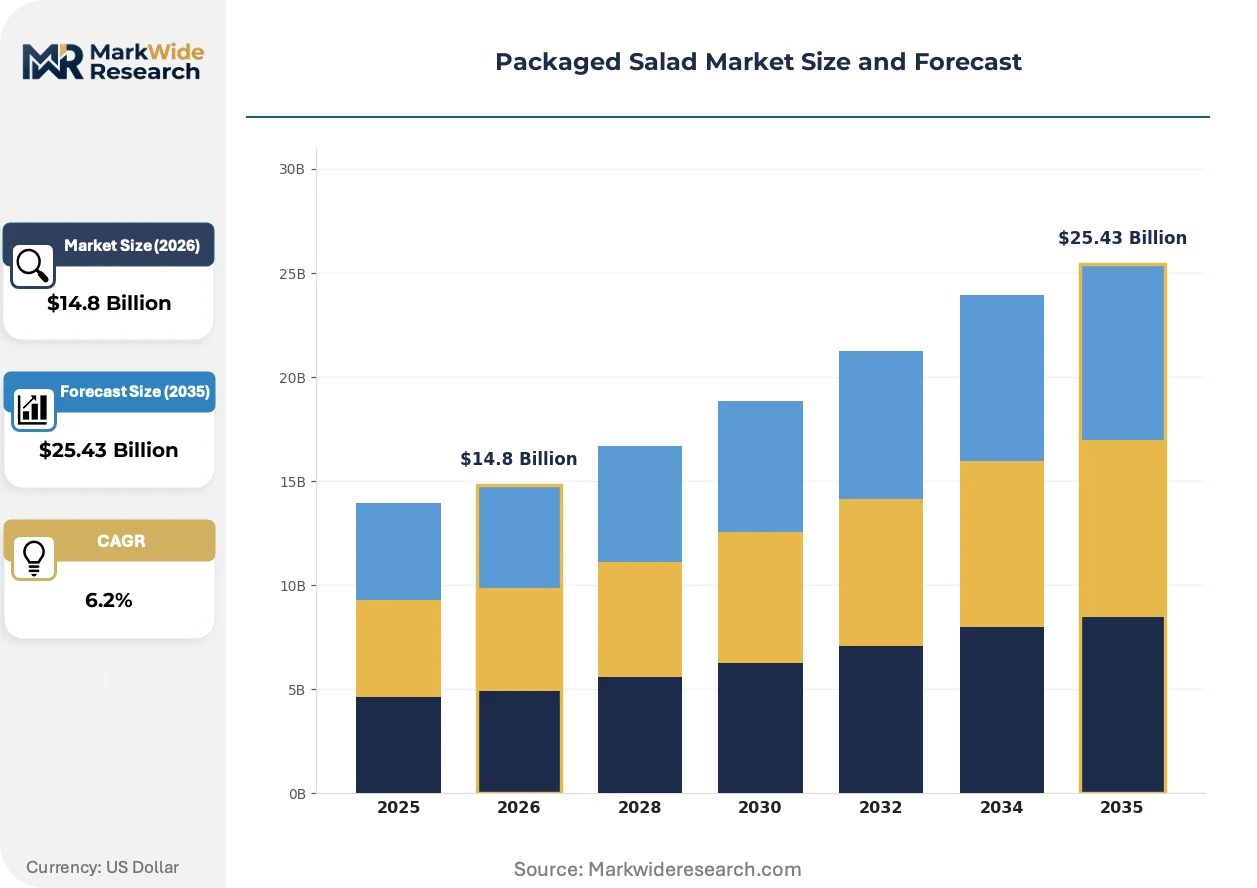
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mixed Greens, Spinach, Kale, Arugula Packaging Type: Bagged, Clamshell, Tray, Single-Serve Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Farmers' Markets End User: Households, Restaurants, Cafeterias, Catering Services |
| Companies Covered | Mann Packing Co., Inc., BrightFarms, Inc., Fresh Express, Incorporated, Taylor Farms, Earthbound Farm, Dole Food Company Inc., Gotham Greens, organicgirl, Bonduelle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Salad Market Strategic Shifts & Innovations
Active reshaping across the packaged salad category is compressing traditional field-to-shelf timelines while elevating automation and data capture throughout the value chain. These shifts are redrawing operational requirements for competitive participation.
Modified-atmosphere packaging systems are extending shelf life through oxygen-scavenging film layers that preserve chlorophyll integrity. Foodservice distributors are adopting these formats at accelerated pace to reduce waste in multi-stop delivery routes. This technology is displacing conventional perforated bags in premium retail placements where visual freshness signals drive purchase decisions.
California's Central Valley production cluster is adapting to the FDA's agricultural water testing mandates through on-farm treatment systems and alternative irrigation sourcing. The rule's harvest equipment sanitation requirements are elevating capital barriers for smaller growers without integrated wash-line facilities. Organic-certified operations are responding fastest due to pre-existing third-party audit infrastructure.
Restaurant procurement departments are consolidating supplier relationships around operators with verified cold-chain documentation and lot-level traceability. Multi-unit chains are replacing fragmented local sourcing with national distribution agreements that standardize quality specifications. This concentration is most visible in quick-service salad platforms scaling across metropolitan markets with uniform menu execution requirements.
Packaged Salad Market Segmentation
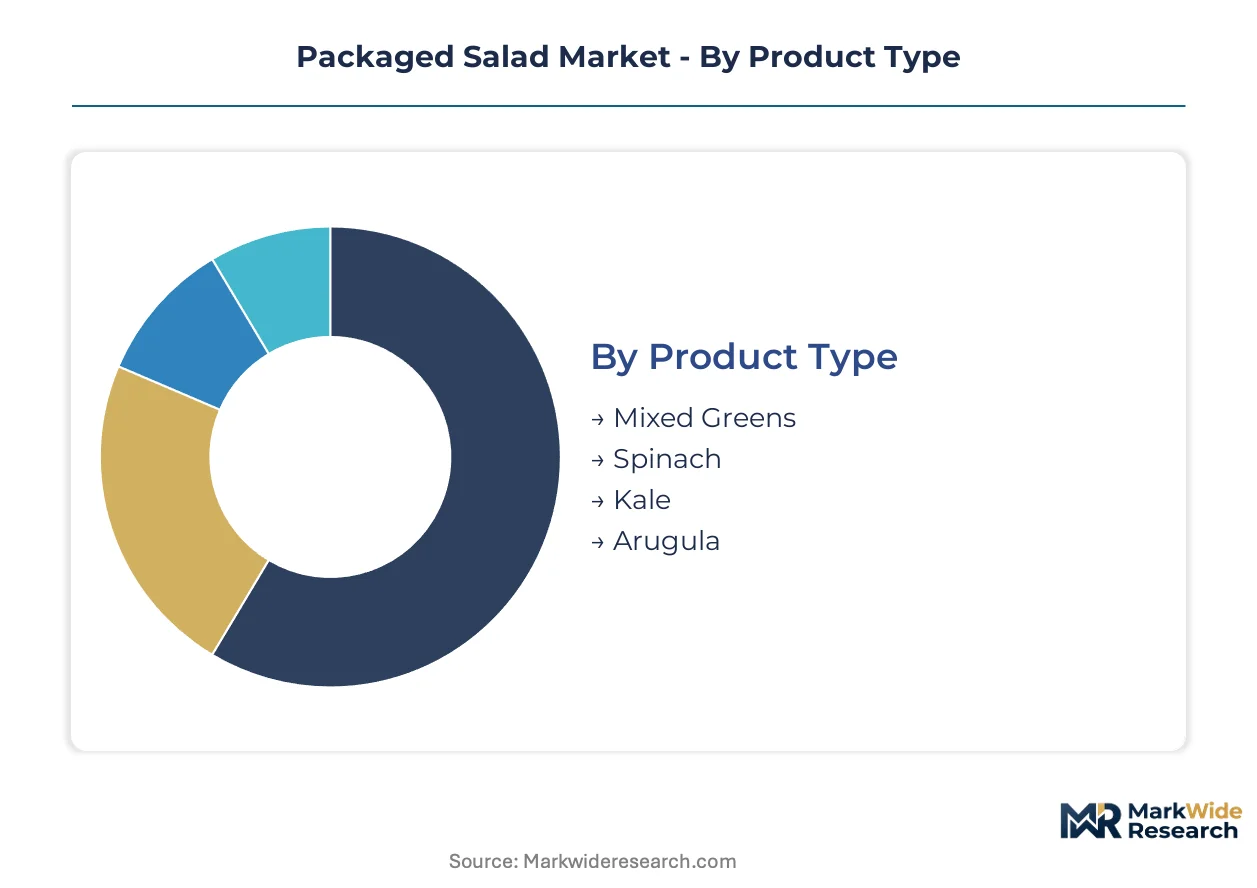
Segmentation in packaged salads reveals how substitution pressures reshape procurement decisions across channels. Product format, packaging technology, and end-use application each create distinct margin pools and compliance burdens that operators must navigate strategically.
Product Type:
Substitution pressure runs strongest against commodity field-grown categories where controlled-environment alternatives now capture urban demand clusters.
- Mixed Greens:Pre-washed blends of lettuce varieties, romaine, and tender leaf bases dominate foodservice procurement for menu versatility. Quick-service restaurant chains in the United States specify these blends for consistent portion control across multi-state operations.
- Spinach:Flat-leaf and baby spinach varieties carry higher perishability risk due to moisture sensitivity. California's Central Valley production cluster supplies conventional volume while greenhouse operators in New York and Illinois capture premium organic demand.
- Kale:Curly and lacinato varieties serve health-positioned retail SKUs and juice bar supply chains. Tougher leaf structure extends cold-chain tolerance compared to softer greens.
- Arugula:Peppery flavor profile commands specialty retail placement and fine-dining garnish applications. Shorter harvest cycles favor controlled-environment production near metropolitan consumption centers.
Mixed Greens anchors the volume base while Arugula gains share at the steepest rate as flavor differentiation commands price premiums in specialty retail.
Packaging Type:
Cost tier stratification separates commodity bagged formats from premium clamshell investments that visual quality verification demands.
- Bagged:Perforated polyethylene films dominate retail volume with modified-atmosphere layers extending shelf life. Dole Food Company Inc. and Taylor Farms deploy high-speed form-fill-seal lines across coast-to-coast processing networks for supermarket distribution efficiency.
- Clamshell:Rigid polyethylene terephthalate containers enable visual inspection of organic SKUs where browning or moisture damage triggers rejection. The FDA's traceability requirements favor clamshell lot codes for restaurant group compliance documentation.
- Tray:Expanded polystyrene or molded fiber bases with overwrap film serve foodservice bulk portions. Cafeteria and catering procurement favors this format for kitchen prep flexibility.
- Single-Serve:Individual clamshell or bowl formats target convenience retail and grab-and-go meal occasions. Urban employment centers in Chicago, Los Angeles, and Dallas drive placement in refrigerated checkout displays.
Bagged formats anchor the volume base while Single-Serve expands most quickly as on-the-go consumption patterns multiply across metropolitan markets.
Distribution Channel:
Volume concentration in multi-location retail chains shapes supplier qualification requirements and cold-chain documentation standards.
- Supermarkets:Conventional and natural grocery chains control the largest volume flows through centralized distribution centers. Kroger, Albertsons, and Whole Foods Market specify temperature logging and lot traceability for vendor approval.
- Convenience Stores:Refrigerated grab-and-go sections in 7-Eleven, Circle K, and regional chains expand single-serve placement. Limited shelf space favors turn velocity over SKU breadth.
- Online Retail:Amazon Fresh, Instacart fulfillment, and direct-to-consumer subscription services demand packaging resilience for last-mile delivery. Modified-atmosphere formats reduce spoilage claims in ambient transit conditions.
- Farmers' Markets:Direct producer-to-consumer sales bypass conventional cold-chain infrastructure. Local greenhouse operators including Gotham Greens leverage this channel for freshness positioning and traceability storytelling.
Supermarkets anchor the volume base while Online Retail climbs the fastest as fulfillment infrastructure penetrates suburban markets previously served only by physical retail.
End User:
Customer type segmentation separates household preparation flexibility from foodservice operational constraints that standardized specifications address.
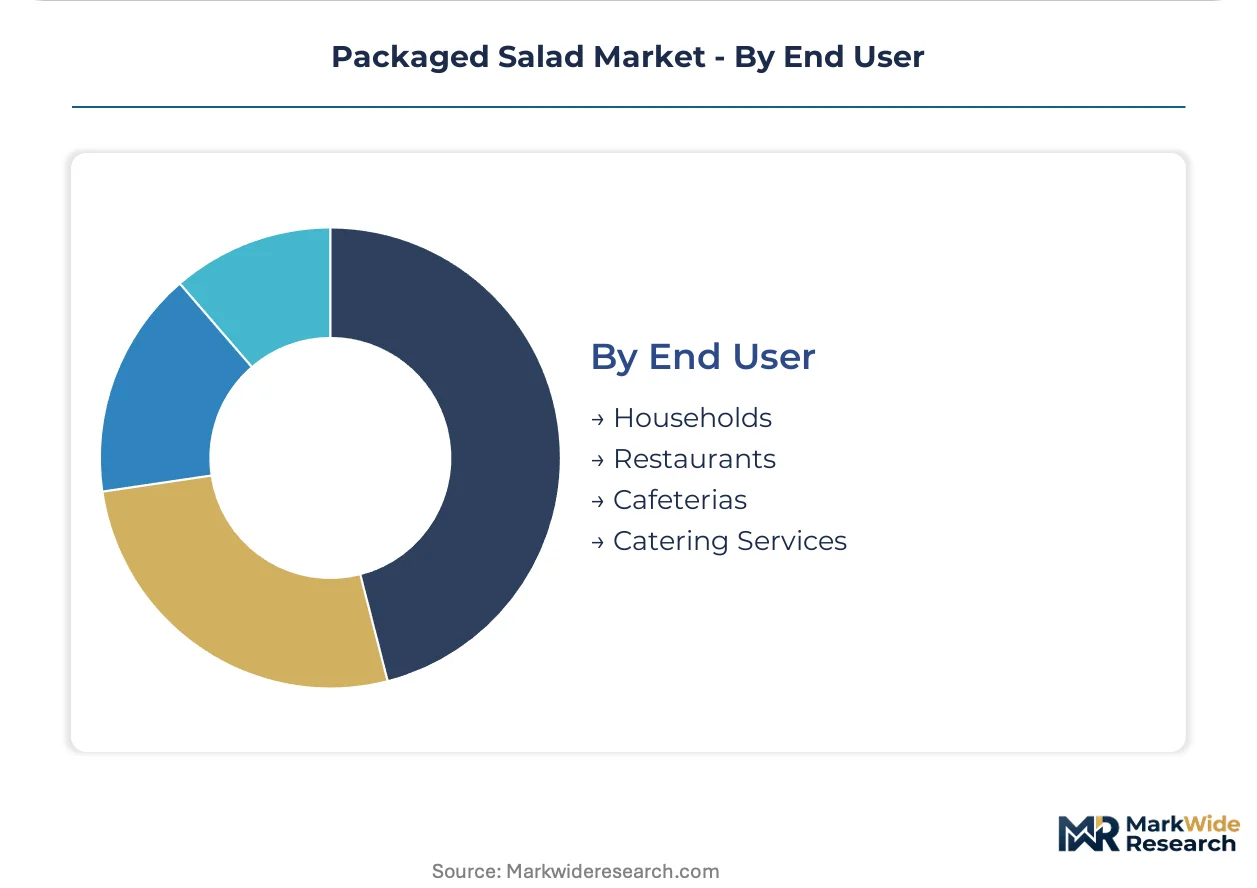
- Households:Retail purchasers prioritize convenience and visual freshness signals for immediate consumption or short-term meal planning. Organic certification and wash-line safety claims drive premium SKU selection.
- Restaurants:Quick-service chains and casual dining groups consolidate procurement around national distribution agreements with verified cold-chain documentation. Uniform menu execution requirements favor pre-washed blends with consistent specifications.
- Cafeterias:Corporate, university, and healthcare foodservice operations specify bulk formats with food safety certifications. The USDA's commodity procurement programs influence vendor selection for institutional accounts.
- Catering Services:Event-based demand requires flexible portion scaling and rapid delivery windows. Regional processors with localized production capacity capture this fragmented demand pool.
Households anchor the volume base while Restaurants gain share at the steepest rate as chain expansion concentrates procurement among integrated processors with national distribution reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Interstate 5 corridor underwrites North American packaged salad distribution, connecting Central Valley production fields to cold-chain logistics hubs serving retail and foodservice channels across the continent.
United States
Quick-service restaurant chains and institutional foodservice operators drive volume concentration in the United States. The FDA's Leafy Greens Safety Rule mandates agricultural water testing and harvest equipment sanitation that elevates compliance costs. California's Central Valley production cluster dominates field-grown supply, while greenhouse operators in New York and Illinois capture premium urban demand.
Canada
Retail consolidation around Loblaw and Sobeys chains shapes supplier qualification requirements in Canada. Health Canada's Safe Food for Canadians Regulations enforce preventive control plans and traceability documentation for fresh produce imports. Greenhouse production in Leamington, Ontario supplies year-round volume to Toronto and Montreal metropolitan markets.
Mexico
Export-oriented production in Baja California and Sonora supplies North American foodservice channels during winter months. Mexico's Federal Commission for the Protection against Sanitary Risk enforces Good Agricultural Practices certification for export-bound operations. The Guanajuato highlands cluster specializes in organic baby leaf production for US retail private label programs.
Germany
Discounter dominance through Aldi and Lidl chains compresses retail pricing bandwidth in Germany. The EU's Farm to Fork Strategy under the European Green Deal targets pesticide reduction and sustainable packaging mandates. The Lower Saxony greenhouse belt around Oldenburg supplies controlled-environment production for central European distribution.
Netherlands
Advanced greenhouse technology and automated processing infrastructure anchor Dutch export competitiveness. The EU's Single-Use Plastics Directive drives fiber-based packaging substitution in retail channels. The Westland region's glasshouse cluster supplies year-round baby leaf and herb blends to British and German supermarket chains.
Packaged Salad Market Key Industry Players
Concentration sits with integrated processors commanding coast-to-coast cold-chain infrastructure and national distribution contracts. The vendor base stratifies between multi-facility operators with traceability systems and regional growers serving localized demand pools. Three archetypes dominate: integrated processors with vertical control from field to distribution center, controlled-environment specialists leveraging urban proximity for freshness positioning, and retail-brand licensors anchoring shelf space through supermarket partnerships. Competitive moves center on capacity consolidation through facility acquisitions and strategic partnerships securing exclusive supply agreements with quick-service restaurant chains.
Within the integrated processor tier, Taylor Farms and Dole Food Company Inc. exemplify scale-driven operators with multi-state processing networks and national distribution reach. Gotham Greens occupies a position among controlled-environment specialists, representing the archetype of urban greenhouse operators collapsing farm-to-fork distance through metropolitan production facilities. Earthbound Farm anchors the organic-certified segment, sitting within the tier of growers with pre-existing third-party audit infrastructure that accelerates compliance with evolving safety regulations.
| Leading Market Players |
|---|
| Mann Packing Co., Inc. |
| BrightFarms, Inc. |
| Fresh Express, Incorporated |
| Taylor Farms |
| Earthbound Farm |
| Dole Food Company Inc. |
| Gotham Greens |
| organicgirl |
| Bonduelle |
| Others |
Cost & Logistics Intelligence
Five-day field-to-fork lead times for Central Valley greens concentrate pricing power with integrated processors commanding national distribution contracts, while perishability constraints compress margin capture for regional operators lacking redundant cold-chain nodes.
Pricing Analysis
Volume-discount tiering structures separate contract foodservice pricing from spot retail procurement, with quick-service restaurant chains extracting favorable terms through multi-year supply agreements. Premium-mid-economy pricing differentiation rests on USDA Organic certification and controlled-environment provenance. Cost compression in conventional field-grown tiers is intensifying because agricultural water treatment investments elevate fixed-cost burdens. Price sensitivity peaks among institutional cafeterias operating under USDA commodity procurement programs, while specialty retailers absorb premiums for hyperlocal greenhouse supply.
Supply Chain Analysis
California's Interstate 5 corridor underwrites North American packaged salad distribution, connecting Central Valley production fields to cold-chain logistics hubs serving retail and foodservice channels across the continent. Raw material inputs draw from lettuce seedstock suppliers in the Netherlands, polyethylene film converters in Texas, and refrigerated trailer fleets concentrated in the Midwest. Single-source vulnerability concentrates around coast-to-coast processing networks controlled by a handful of integrated operators. Distribution runs through supermarket centralized distribution centers and foodservice redistribution warehouses with temperature-logging mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaged salad market exhibits cyclical recovery characteristics as quick-service restaurant chain expansion drives demand normalization following pandemic-era channel disruption.
For Market Incumbents: Shield market position through backward integration into controlled-environment acreage near metropolitan demand clusters, insulating supply from climate volatility and FDA agricultural water testing mandates. Prioritize wash-line automation investments ahead of seasonal planting cycles to compress sanitation compliance timelines. Consolidate supplier relationships with national restaurant groups around verified lot-level traceability documentation. For New Entrants and Emerging Players: Lead with hyperlocal urban greenhouse production in secondary metropolitan markets where farm-to-fork distance collapse commands freshness premiums from traceability-conscious consumers. Target convenience retail single-serve placement in Chicago, Dallas, and Atlanta employment centers where grab-and-go meal occasions multiply fastest. Deploy direct-to-consumer subscription models bypassing conventional supermarket slotting fee barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates seeking to divest non-core fresh produce assets lacking integrated cold-chain infrastructure. Long-term viability favors operators with coast-to-coast processing networks and pre-existing third-party audit frameworks accelerating FDA compliance. Monitor quick-service restaurant procurement consolidation signals as inflection indicators for contract concentration trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Capacity Expansion | Greenhouse installations near metropolitan markets capture freshness premiums from traceability-focused buyers. |
| Wash-Line Automation Upgrade | Harvest equipment sanitation compliance compresses seasonal preparation windows for smaller growers. |
| Foodservice Contract Consolidation | National distribution agreements with quick-service chains standardize quality specifications across multi-state operations. |
| Single-Serve Format Introduction | Portable clamshell formats penetrate convenience retail channels in urban employment centers. |
| Fiber-Based Packaging Transition | State-level extended producer responsibility laws incentivize sustainable material alternatives to plastic clamshells. |
Research Approach
A spread of perspectives from agricultural operations managers, quick-service restaurant procurement directors, supermarket category buyers, and cold-chain logistics coordinators converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation through FDA enforcement documentation, USDA organic certification databases, and supermarket distribution center temperature compliance records. Bottom-up volume estimates triangulated against top-down channel sizing across the analysis window.
Segmentation dimensions modeled include product type, packaging format, distribution channel, and end-use application across the projection horizon. CAGRs derived from historical shipment data, planting acreage trends, and foodservice channel penetration rates. Industry-specific forecast inputs incorporated FDA compliance timeline assumptions and quick-service restaurant expansion trajectories.
The analysis sits within stated boundaries; outcomes outside sustained foodservice channel recovery or accelerated regulatory enforcement would require recalibration. Forecasts reflect documented assumptions regarding agricultural input cost trajectories and cold-chain infrastructure investment cycles. Practitioners should keep alternative scenarios live as FDA Leafy Greens Safety Rule implementation timelines and state-level packaging mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Canned Legumes Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
Burritos Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
North America Pasta Market
Packaged Foods
Canned Goods Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Ready Meals Market
Packaged Foods
Impulse Ice-Cream Market