
 North America Pasta and Noodles Market | 2026-2036
North America Pasta and Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pasta and Noodles Market Analytics
Clean-label extrusion technology is narrowing the gap between artisanal and mass-market pasta quality, enabling scaled production of additive-free noodles with traditional texture profiles. Barilla Holding SpA leverages its vertically integrated durum wheat supply chain to sustain premium positioning across North American retail channels. General Mills anchors the mid-market segment through broad distribution reach and value-oriented product lines. Nestlé SA competes in the instant noodle category with specialized manufacturing capabilities tailored to North American flavor preferences.
North America pasta and noodles comprise wheat-based or alternative-flour doughs extruded, rolled, or cut into defined shapes, then dried or pre-cooked for shelf-stable or refrigerated distribution, with protein content typically ranging from twelve to fourteen percent for optimal cooking performance. These products serve as carbohydrate foundations for household meals, restaurant menus, and institutional food programs across the continent. Spaghetti and penne occupy mature volume positions in retail, while fettuccine and macaroni capture differentiated demand through sauce compatibility and preparation versatility. Food service operators represent the fastest-growing end user segment as away-from-home pasta consumption expands across quick-service and casual dining channels.
The FDA enforces nutrition labeling and allergen disclosure requirements that shape product formulation and packaging communication strategies for pasta and noodle manufacturers operating in the United States. Health Canada and the Canadian Food Inspection Agency administer parallel standards for sodium content, whole grain claims, and gluten-free labeling that influence cross-border product development decisions. USDA organic certification and Non-GMO Project verification create tiered market access conditions that reward investment in certified supply chains. Stakeholders must monitor evolving clean-label standards and alternative protein integration pathways as determinants of competitive positioning in North American pasta and noodles.
Market Dynamics
Clean-label reformulation pressure from FDA sodium reduction mandates is forcing durum wheat processors to rebuild extrusion workflows without texture-compromising additives, compressing margins for mid-tier producers while rewarding vertically integrated suppliers.
Growth Catalysts
- Quick-service pasta expansion:Food service operators in Texas and California are adding made-to-order noodle bowls to capture lunch traffic, pulling volume through centralized commissary kitchens.
- USDA organic certification pathways:Streamlined approval processes for whole-grain claims are enabling smaller mills to access premium retail shelf placement previously reserved for national brands.
- High-protein durum varieties:Seed breeders in the northern Great Plains are commercializing wheat strains with 15% protein content, reducing cooking loss and improving sauce adhesion for food service buyers.
Market Restraints
- Durum wheat supply concentration:North Dakota and Saskatchewan account for over 80% of continentally grown high-protein durum, creating weather-driven input volatility.
- Gluten-free formulation barriers:Rice and legume flour blends lack the viscoelastic properties of wheat gluten, limiting shape retention in long-cut noodles.
- FDA added-sugar disclosure rules:Pre-sauced instant noodle products face reformulation costs or front-of-package penalty positioning.
Strategic Opportunities
- Canadian alternative-protein noodles:Pea and lentil flour processing infrastructure in Saskatchewan offers white-space positioning for plant-based pasta lines targeting Health Canada protein claim standards.
- Direct-to-restaurant distribution:Specialty importers are bypassing broadline distributors to deliver fresh-frozen artisanal shapes to independent Italian restaurants in New York and Chicago.
- Dual carbon labeling convergence:California's forthcoming climate disclosure requirements and voluntary carbon-neutral certifications are creating tiered pricing power for low-emission supply chains.
Industry Challenges
- Extrusion engineer scarcity:Food science programs produce fewer specialists in traditional pasta die design than automated snack extrusion, slowing clean-label product development timelines.
- Cross-border label harmonization:Divergent FDA and Health Canada serving-size definitions force dual packaging SKUs for products distributed in both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pasta and Noodles Market |
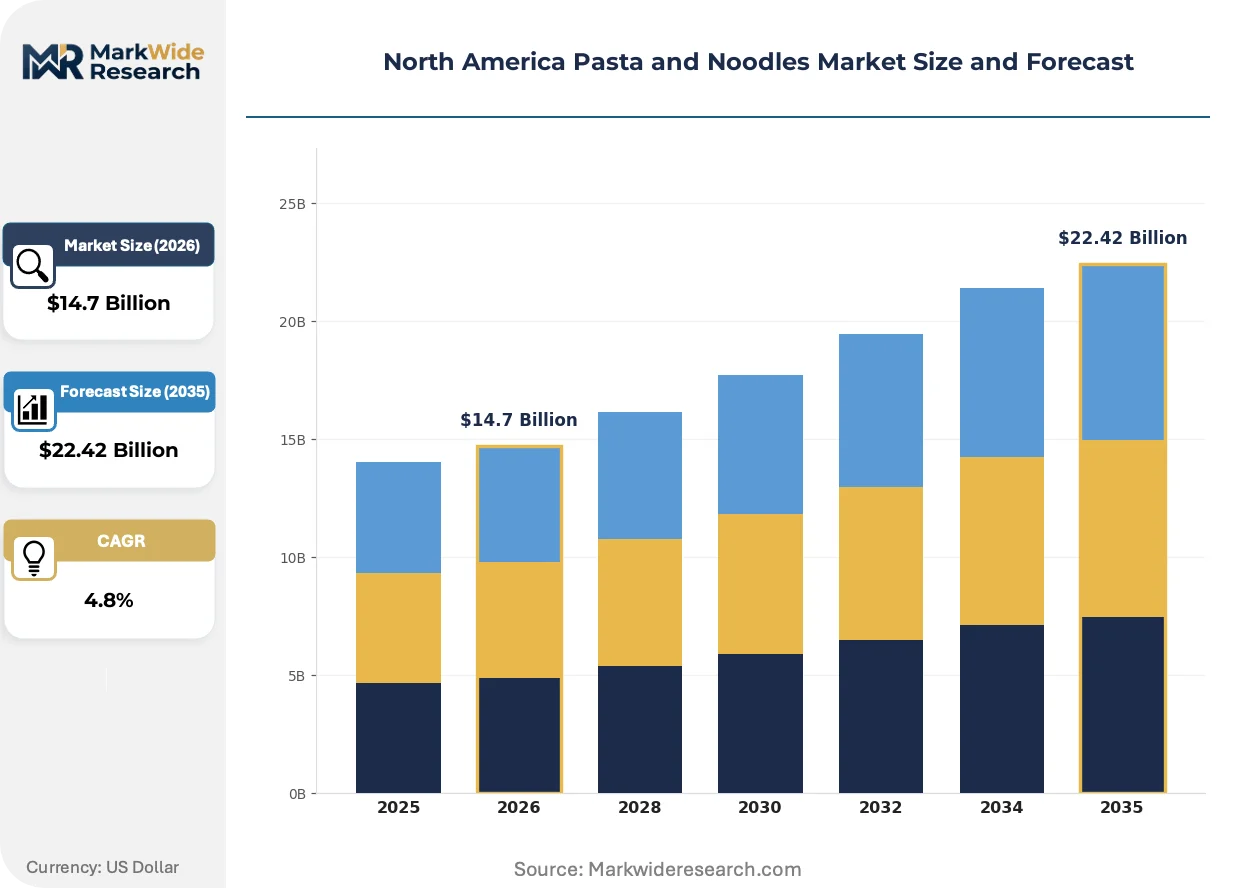
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spaghetti, Penne, Fettuccine, Macaroni Packaging Type: Bags, Boxes, Tubs, Jars End User: Households, Restaurants, Food Service Operators, Retailers Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Ebro Foods SA, Toyo Suisan Kaisha Ltd, Barilla Holding SpA, General Mills, Unilever PLC, Nestlé SA, Nissin Foods Holdings Co., Ltd., Conagra Foods, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pasta and Noodles Market Evolving Landscape
Extrusion automation and alternative-flour processing are converging to redefine quality benchmarks across retail and food service channels, compressing the traditional trade-off between scale and craftsmanship.
Low-temperature extrusion technology is collapsing the quality gap between artisanal bronze-die pasta and high-volume Teflon-extruded products. Regional pasta cooperatives in California and Quebec are adopting these systems to supply independent restaurants with additive-free fresh-frozen noodles at mid-market price points. The structural consequence is margin compression for legacy mass-market brands dependent on emulsifier-dependent formulations.
FDA updated Nutrition Facts labeling requirements and parallel Health Canada sodium reduction frameworks are mandating front-of-package sodium disclosure for prepared noodle products. Manufacturers are responding by reformulating broth bases and seasoning sachets with potassium chloride blends and umami-enhancing yeast extracts. The instant noodle segment faces the steepest compliance costs due to its reliance on salt-preserved flavor stability.
Food service procurement is consolidating toward single-source pasta programs with guaranteed volume commitments and co-developed exclusive shapes. Broadline distributors in Texas and Illinois are losing share to direct mill relationships as chain restaurants seek supply security and custom die investments. This pattern concentrates most visibly in the fast-casual Italian segment, where operators differentiate through proprietary noodle formats.
North America Pasta and Noodles Market Segmentation
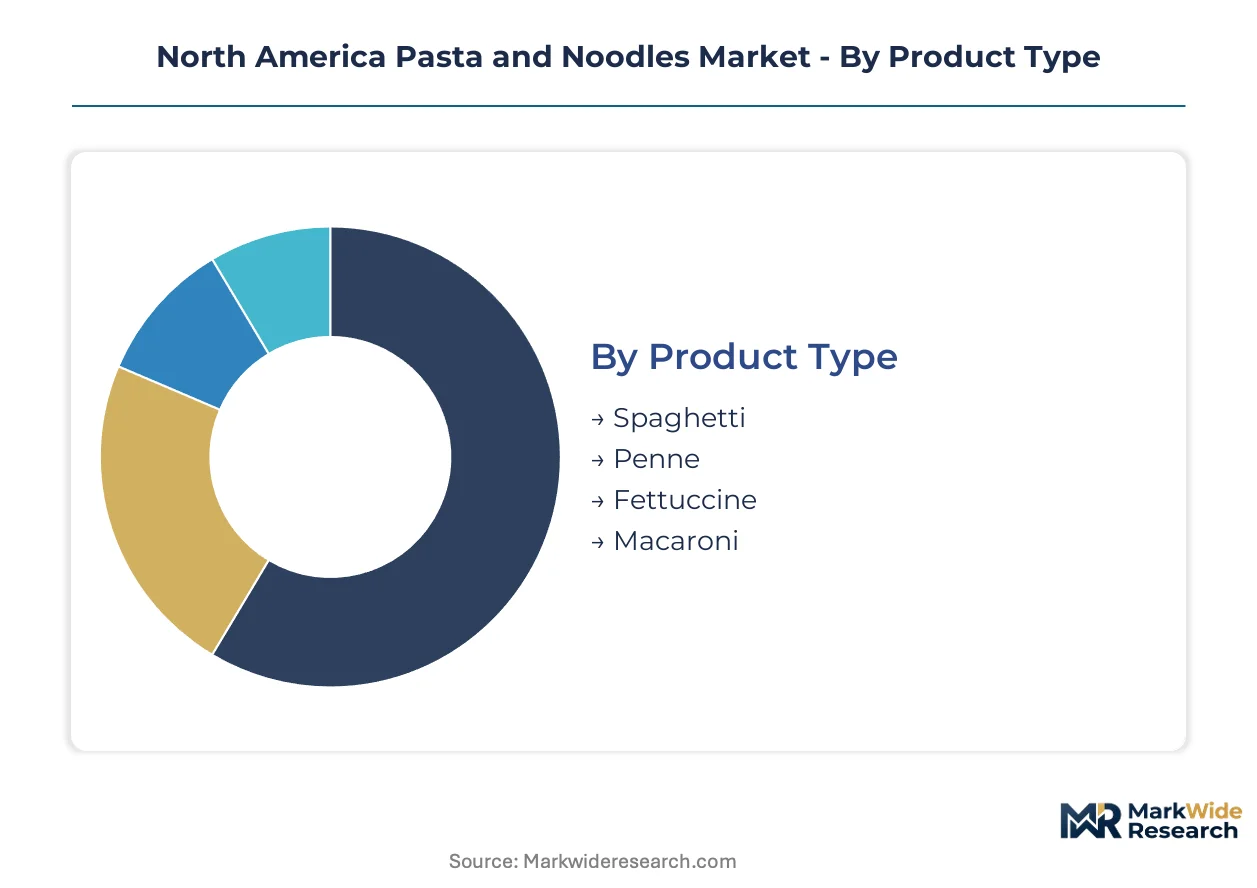
Segmentation in North American pasta and noodles reveals how product form, packaging economics, and channel access determine margin capture. Each dimension carries distinct regulatory, operational, and competitive imperatives that shape supplier strategy across the United States and Canada.
Product Type:
Cost tier stratification separates commodity shapes from premium-positioned formats, with protein content and die material driving price positioning.
- Spaghetti:Long cylindrical strands extruded through Teflon or bronze dies serve as the volume baseline across retail and food service. California and Texas households anchor consumption through broad retail distribution, though private-label competition compresses branded margins in this mature segment.
- Penne:Diagonal-cut tubular shapes with ridged exteriors optimize sauce retention for institutional food programs and casual dining chains. Food service operators in Illinois and New York specify 14% protein durum for reduced cooking loss in high-volume kitchens.
- Fettuccine:Flat ribbon formats command premium shelf placement through perceived artisanal authenticity.
- Macaroni:Curved elbow shapes dominate prepared salad and casserole applications in the Midwest and Southeast.
Spaghetti commands the established base. The steepest expansion runs through penne as food service procurement consolidates around standardized shapes.
Packaging Type:
Application requirements dictate material selection, with shelf stability, portion control, and retail visibility each favoring distinct container economics.
- Bags:Flexible polyethylene and paper laminates minimize unit cost for high-velocity dry pasta SKUs in club and mass retail. Supermarket chains in Texas and Arizona favor gusseted stand-up formats for vertical shelf efficiency and resealability.
- Boxes:Recyclable paperboard with window panels protects long-cut shapes while enabling brand communication through front-facing graphics. Premium positioning in Northeast retail relies on matte finishes and FSC certification callouts to justify price premiums over bagged alternatives.
- Tubs:Rigid polypropylene containers dominate fresh-refrigerated and pre-cooked segments requiring moisture barriers.
- Jars:Glass packaging serves instant noodle and ready-to-eat broth applications where thermal processing demands hermetic seals.
Boxes retain the volume anchor in dry retail. Bags are gaining share fastest through private-label expansion and club format growth.
End User:
Customer type determines formulation specifications, with protein content, shape complexity, and delivery format calibrated to operational constraints.
- Restaurants:Independent Italian establishments and fast-casual chains in Chicago and New York specify bronze-extruded shapes with 13-14% protein for superior sauce adhesion and al dente tolerance. Direct mill relationships bypass broadline distributors to secure volume commitments and custom die investments.
- Food Service Operators:Institutional kitchens, centralized commissaries, and contract feeding programs prioritize 10-pound bulk packs with consistent cook times. Quick-service chains expanding noodle bowl menus in California and Texas drive demand for pre-portioned fresh-frozen formats with extended holding stability.
- Households:Retail consumers select across price tiers based on preparation occasion and dietary positioning.
- Retailers:Private-label program development and exclusive brand partnerships shape shelf allocation and promotional calendars.
Households anchor absolute volume. Restaurants are expanding most quickly as away-from-home pasta consumption accelerates.
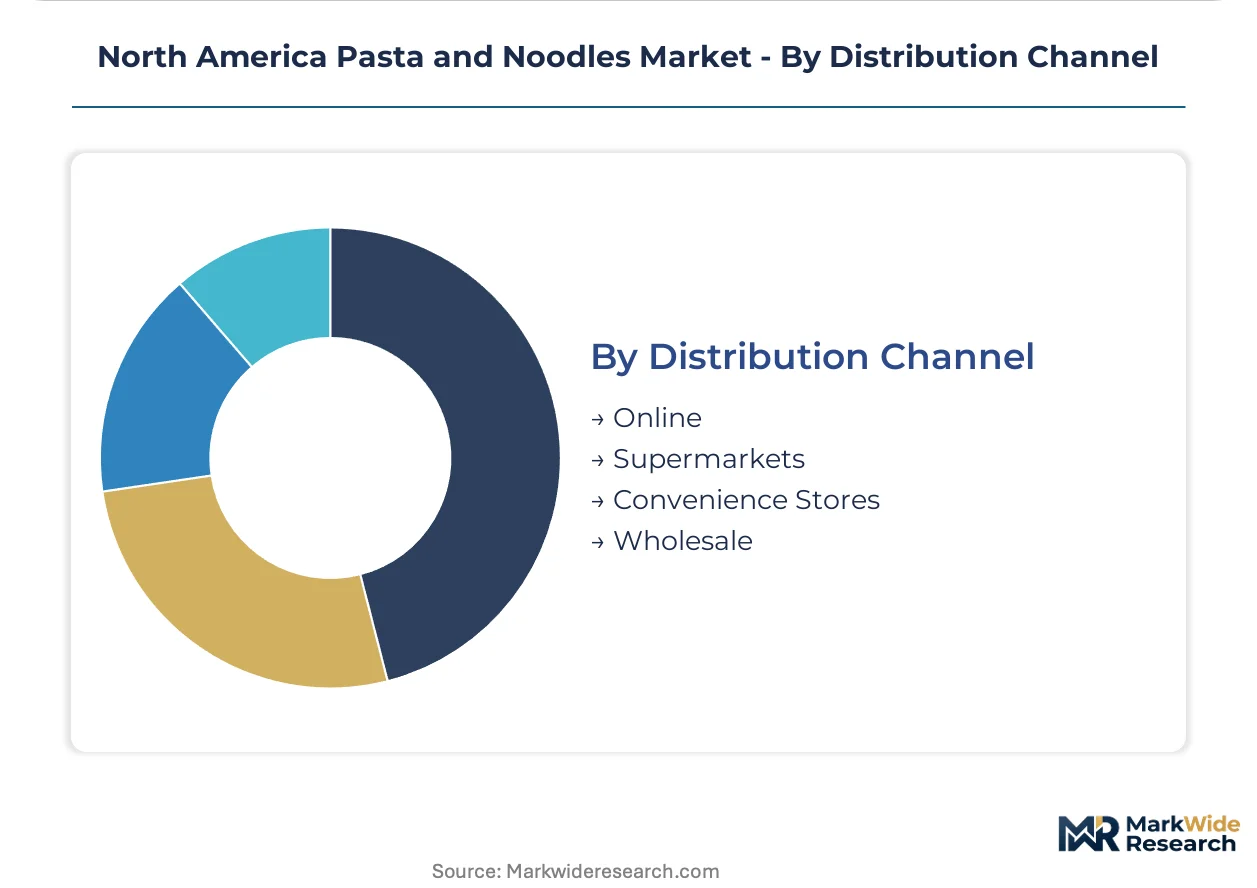
Distribution Channel:
Supply concentration and margin structure vary sharply by channel, with inventory velocity and buyer concentration determining supplier economics.
- Supermarkets:Traditional grocery chains and mass merchandisers in the United States and Canada maintain pasta as a high-velocity staple category with promotional-driven demand spikes. Slotting fees and trade promotion budgets concentrate supplier resources on defending shelf position against private-label encroachment.
- Wholesale:Broadline distributors and specialty foodservice purveyors aggregate demand from independent restaurants, institutional kitchens, and regional chains. Texas and Illinois distribution centers face displacement pressure as direct mill relationships and specialty importers capture share in the fast-casual segment.
- Online:E-commerce platforms enable subscription models and bulk purchasing for pantry stocking.
- Convenience Stores:Limited assortment formats focus on instant noodle cups and single-serve microwaveable products.
Supermarkets retain the volume foundation. Wholesale faces structural pressure as procurement patterns fragment toward direct sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food service procurement teams and retail category managers concentrate demand in coastal metropolitan corridors and prairie wheat belts. Buyer archetypes split between institutional volume contracts and premium artisanal sourcing.
United States
California and Texas food service operators drive fresh-frozen noodle demand through quick-service expansion. FDA sodium reduction mandates reshape instant noodle formulation requirements. Chicago and New York house independent Italian restaurant clusters sourcing bronze-extruded shapes through direct mill relationships.
Canada
Health Canada protein claim standards enable Saskatchewan pea and lentil flour processors to enter plant-based pasta manufacturing. Prairie durum wheat exports supply US mills while domestic retail concentrates in Ontario and Quebec. Montreal and Toronto anchor specialty food distribution networks serving independent restaurants.
Mexico
Instant noodle consumption concentrates in Mexico City and Guadalajara metropolitan zones with strong convenience retail penetration. Local regulators align labeling standards with US FDA frameworks for cross-border product flows. Northern border states host maquiladora operations producing pasta for US private-label programs.
North America Pasta and Noodles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered price positioning. The structure consolidates around three to five integrated multinationals commanding retail shelf space and broadline distribution, while mid-scale regional mills capture food service specialty contracts. Strategic archetypes include vertically integrated wheat processors, brand-marketing conglomerates, and cooperative milling associations. Dominant competitive moves encompass direct-to-restaurant distribution bypass and clean-label extrusion technology licensing.
Among Italy-based durum specialists, Barilla Holding SpA exemplifies premium retail positioning through controlled wheat supply chains. Swiss conglomerate Nestlé SA and US-based General Mills occupy distinct tier positions—Nestlé within instant noodle manufacturing and General Mills across mid-market retail distribution. These three entities represent contrasting integration models: captive agriculture, diversified FMCG portfolios, and grain-processing scale.
| Leading Market Players |
|---|
| Ebro Foods SA |
| Toyo Suisan Kaisha Ltd |
| Barilla Holding SpA |
| General Mills |
| Unilever PLC |
| Nestlé SA |
| Nissin Foods Holdings Co., Ltd. |
| Conagra Foods |
| Campbell Soup Company |
| Others |
Value Network & Pricing Analysis
The Great Lakes rail corridor carries durum wheat from North Dakota elevators to Buffalo and Chicago mills, with freight cost swings compressing margins for non-integrated processors while amplifying price differentiation between captive-supply brands and spot-market dependent competitors.
Pricing Analysis
Cost-plus contracts indexed to Minneapolis Grain Exchange durum futures dominate procurement between prairie growers and mill operators, creating predictable input cost pass-through for integrated players. Price differentiation separates USDA-certified organic lines from conventional bulk SKUs, with bronze-extruded artisanal formats commanding shelf premiums over Teflon-extruded commodity shapes. Pricing pressure stems from private-label expansion in Texas and California club retail, eroding branded mid-tier margins. Food service buyers exhibit lowest price sensitivity due to sauce adhesion and cook-time specifications, while household retail consumers shift aggressively toward promotional private-label bags.
Supply Chain Analysis
Upstream durum wheat production concentrates in North Dakota, Saskatchewan, and Montana, with the northern Great Plains accounting for over four-fifths of continentally grown high-protein varieties. Milling operations draw from this geographic cluster while sourcing specialty durum from Italy and Turkey for premium bronze-extruded lines. Single-source vulnerability runs through weather-driven yield volatility in the Red River Valley, where drought or fusarium outbreaks ripple through North American pasta pricing within one growing season. Distribution runs through broadline foodservice purveyors in Illinois and Texas, though direct mill-restaurant relationships are displacing traditional wholesale channels in fast-casual segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American pasta and noodles sit in early-cycle expansion as away-from-home consumption penetrates quick-service formats and clean-label extrusion technology collapses quality-cost trade-offs that previously constrained mid-market positioning.
For Market Incumbents: Pre-empt share erosion from Saskatchewan pea-protein entrants by securing exclusive varietal contracts with North Dakota seed breeders and licensing low-temperature extrusion systems to regional cooperatives. Lock in multi-year volume commitments with California and Texas quick-service chains before alternative-flour processors achieve sauce-adhesion parity. Channel control through direct-restaurant distribution represents the critical defensive lever against broadline distributor displacement. For New Entrants and Emerging Players: Pursue white-space positioning in Health Canada-certified plant-based protein noodles, where Saskatchewan lentil flour infrastructure offers feedstock proximity absent from US Midwest competitors. Target independent Italian restaurants in Chicago and New York with fresh-frozen bronze-extruded shapes delivered through bypass distribution models. A direct-to-chef sampling program with guaranteed cook-time specifications offers the most penetrable go-to-market angle against entrenched broadline relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified FMCG parents with underperforming pasta assets lacking vertical wheat integration or clean-label extrusion capabilities. The five-to-ten year viability window favors processors with captive durum supply and FDA-compliant sodium-reduction formulation expertise. Watch for inflection signals in Saskatchewan alternative-protein processing capacity announcements, which would validate plant-based pasta as a scalable category rather than niche positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Durum Wheat Supply | Captive North Dakota and Saskatchewan acreage secures protein consistency against weather-driven spot market volatility. |
| Low-Temperature Extrusion Licensing | Technology transfer to California and Quebec cooperatives collapses artisanal-mass market quality gaps at mid-tier price points. |
| Direct-to-Restaurant Distribution Bypass | Mill-direct relationships with Chicago and New York independents displace broadline distributor margins and enable custom die investments. |
| Health Canada Protein Claim Certification | Saskatchewan pea and lentil flour processors unlock plant-based pasta shelf placement with regulatory-validated positioning. |
| FDA Sodium Reduction Reformulation | Potassium chloride and umami yeast extract substitution preserves flavor stability in instant noodle broth bases ahead of disclosure mandates. |
Research Methodology
Initial hypotheses were tested against primary input from pasta mill operations directors, food service procurement managers at quick-service chains, retail category buyers in Texas and California, and durum wheat elevator cooperatives in North Dakota, then refined against secondary validation from USDA crop reports, FDA labeling guidance documents, Minneapolis Grain Exchange futures data, and Health Canada regulatory filings. Bottom-up volume estimates from SKU-level retail audit data were triangulated with top-down wheat consumption models across the analysis window.
Demand-supply balance framing anchored the forecast framework, with segmentation modeled across product type, packaging format, end user archetype, and distribution channel throughout the projection horizon. CAGRs were derived from wheat acreage trends, food service outlet expansion rates, and clean-label adoption curves. Key inputs included FDA sodium reduction compliance timelines and Saskatchewan alternative-protein processing capacity buildout announcements.
Macroeconomic conditions sit as an overlay; deviation in freight rail rates, prairie growing season precipitation, and consumer protein substitution preferences would shift the trajectory. Forecasts reflect documented assumptions about extrusion technology diffusion and regulatory compliance pacing. Cross-checking against USDA National Agricultural Statistics Service wheat production estimates and food service industry traffic indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Food and Beverages Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Freekeh Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Ready Meals Market