
 Global Aseptic Packaging in Food Market | 2026-2036
Global Aseptic Packaging in Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aseptic Packaging in Food Market Foresight
Software-defined filling-line optimization is rebalancing how OEMs monetize aseptic packaging equipment, shifting revenue from hardware sales toward predictive maintenance subscriptions and throughput-guarantee contracts. Tetra Pak dominates this service-layer transition through its integrated plant-management platforms. SIG Combibloc competes with modular retrofit kits that extend legacy line lifecycles. Greatview Aseptic Packaging anchors Chinese dairy supply chains with localized carton sleeve production.
Aseptic packaging in food sterilizes product and package separately before sealing in a controlled environment, typically achieving commercial sterility through hydrogen peroxide vapor or UV-C treatment of paperboard-polyethylene-aluminum laminate structures; this eliminates refrigeration dependency while preserving nutritional integrity for six to twelve months. Carton packs occupy the largest volume position across dairy and juice applications, while flexible pouches represent the fastest-growing format in ready-to-eat meals and baby food segments where lightweight logistics and microwave compatibility command premium positioning. Rigid containers and bottles retain structural importance in soups and sauces where stackability and resealability determine retail shelf economics.
FDA regulations governing low-acid canned food equivalents and EPA standards for sterilizing agent residuals shape North American product approval pathways, while EFSA and EU MDR frameworks enforce migration limits for polyethylene and ethylene vinyl alcohol layers entering European food contact applications. China's NMPA and GB standards impose parallel testing protocols that delay market entry for unvalidated laminate constructions. Stakeholders must monitor evolving extended producer responsibility mandates in multiple jurisdictions, as post-consumer carton recycling infrastructure becomes a licensing condition for brand placement in major retail channels.
Market Dynamics
Software-defined filling-line architectures are reconfiguring how OEMs capture value, compressing hardware margins while expanding recurring revenue from throughput guarantees and predictive maintenance subscriptions across dairy and beverage processing networks.
Growth Catalysts
- EU F-Gas Regulation:Tightening refrigerant phase-down schedules are forcing food processors toward ambient distribution chains, eliminating cold-chain dependency through hydrogen peroxide vapor sterilization systems.
- Plant-based dairy expansion:Oat, almond, and soy milk manufacturers are adopting aseptic carton formats to achieve twelve-month shelf stability without refrigeration, concentrating new filling-line investments in China and Germany.
- Extended producer responsibility mandates:France, Germany, and Italy now require post-consumer carton recycling infrastructure as a licensing condition for retail shelf placement, accelerating investment in polyethylene-aluminum separation technologies.
Market Restraints
- Aluminum laminate supply concentration:Three European suppliers control high-barrier foil production for aseptic cartons, creating input volatility when energy costs spike.
- GB standards validation timelines:China's NMPA requires eighteen-month parallel testing protocols for unvalidated laminate constructions, delaying market entry for novel barrier materials.
- Retort pouch substitution:High-pressure processing equipment is gaining traction in ready-to-eat meals, compressing addressable volume for aseptic flexible formats in certain protein applications.
Strategic Opportunities
- Rural India penetration:ambient distribution networks for UHT milk remain underdeveloped in Bihar and Uttar Pradesh, creating white space for localized sleeve production and mobile filling units.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive packaging materials will favor domestic European aseptic carton production over Asian imports by 2026.
- RFID-integrated smart packaging:Converging printed electronics with aseptic barrier structures enables real-time cold-chain verification for premium organic dairy exports to Japan and South Korea.
Industry Challenges
- Electromechanical technician scarcity:Software-defined filling lines require hybrid mechanical-automation skills that vocational programs in Brazil and Mexico have not scaled to match equipment deployment rates.
- Legacy line integration complexity:Retrofitting 1990s-era sterilization tunnels with IoT sensors and predictive analytics platforms demands custom engineering that extends commissioning timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aseptic Packaging in Food Market |
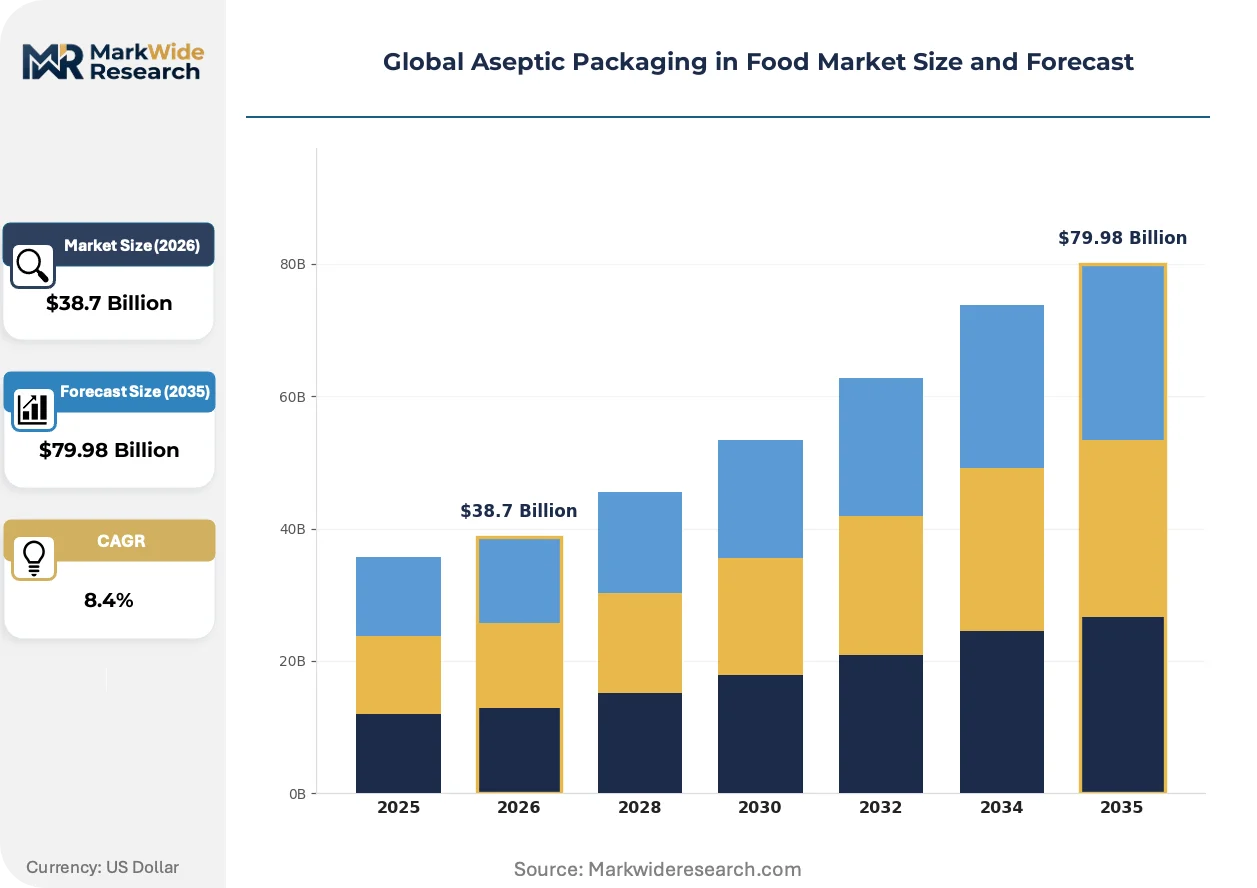
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carton Packs, Flexible Pouches, Rigid Containers, Bottles, Cups Application: Dairy Products, Juices & Beverages, Soups & Sauces, Baby Food, Ready-to-Eat Meals Packaging Material: Paperboard, Aluminum Foil, Polyethylene, Polypropylene, Ethylene Vinyl Alcohol End User: Food & Beverage Manufacturers, Private Label Brands, Food Processing Units, Nutritional Product Makers |
| Companies Covered | Greatview Aseptic Packaging, Schott, Tetra Pak, Reynolds Group Holdings, Robert Bosch, SIG Combibloc, Elopak, ELOPak Group, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aseptic Packaging in Food Market Shifts & Advancements
Paperboard-polyethylene-aluminum laminate structures are undergoing material substitution pressure while digital twins and outcome-based service contracts restructure how processors procure filling capacity.
Mono-material polyethylene structures are absorbing volume from traditional aluminum-barrier cartons in juice and plant-milk segments where twelve-month shelf life requirements are relaxing to six months. German and Dutch dairy cooperatives are piloting these formats to preempt EU Green Deal recyclability mandates. The shift is absorbing capital from foil lamination equipment toward extrusion coating lines.
REACH authorization requirements for hydrogen peroxide sterilizing agents are tightening residual limits for paperboard food contact materials entering European markets. EFSA migration testing protocols now demand expanded analytical scope for polyethylene and ethylene vinyl alcohol layers. Juice concentrate importers from Turkey and Egypt are restructuring supply chains to secure pre-certified laminate sources.
After-sales service unbundling is fragmenting how food processors contract for filling-line uptime. Tier-one dairy multinationals in China are negotiating throughput-guarantee contracts that transfer mechanical risk to OEMs, displacing traditional time-and-materials maintenance agreements. The model is most visible in Shandong and Hebei provinces where domestic dairy giants operate concentrated aseptic capacity.
Global Aseptic Packaging in Food Market Segmentation
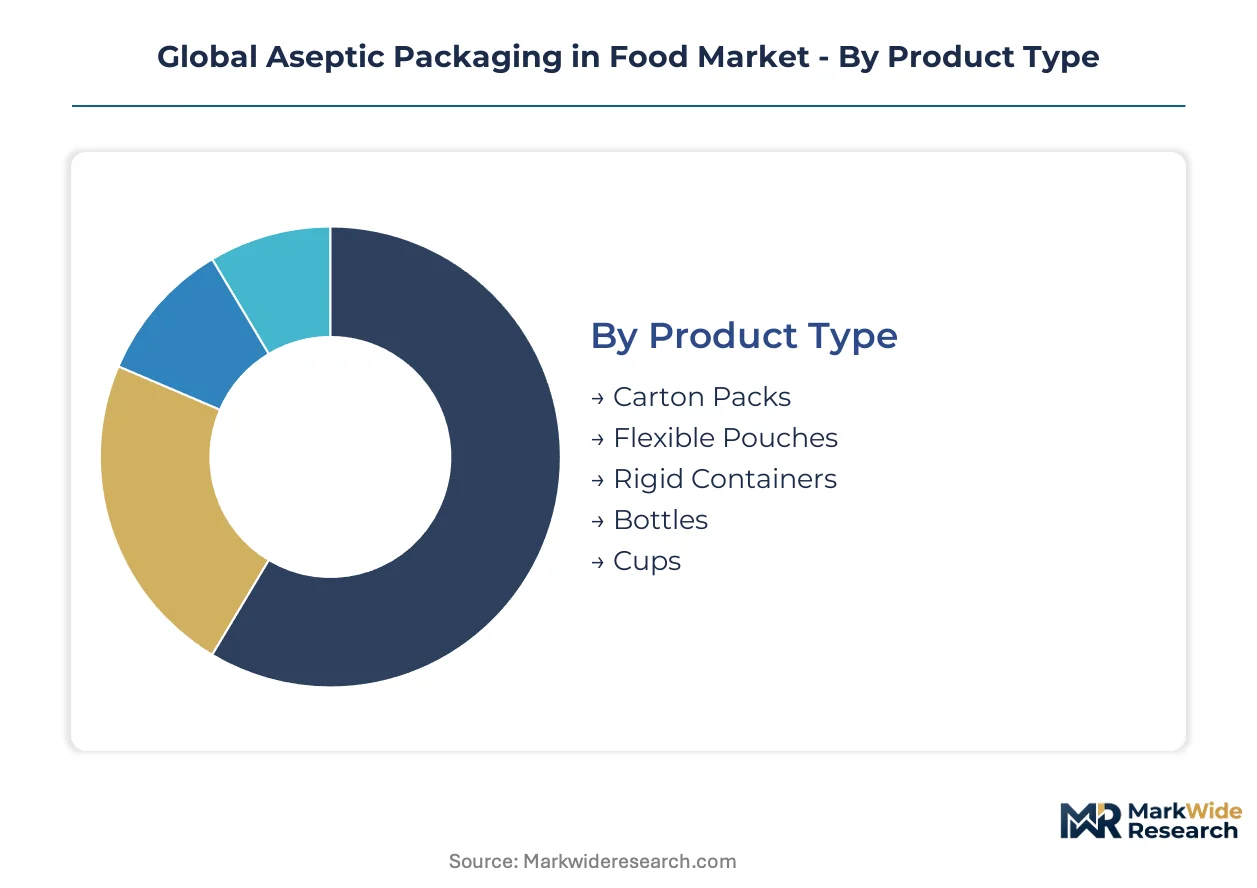
Segmentation in aseptic packaging reveals how sterilization requirements, shelf-life targets, and distribution economics reshape format selection across food categories. Material choices and end-user procurement power further stratify competitive positioning among equipment suppliers and laminate converters.
Product Type:
Carton packs function as standalone ambient distribution systems, while bottles and cups embed into broader multi-format filling operations requiring flexible line reconfiguration.
- Carton Packs:Paperboard-polyethylene-aluminum laminate structures achieve commercial sterility through hydrogen peroxide vapor treatment. Dairy processors in Germany and China concentrate filling investments here for UHT milk and oat-based alternatives, driven by twelve-month shelf stability requirements and EU F-Gas refrigerant phase-downs.
- Flexible Pouches:Multilayer coextruded films with ethylene vinyl alcohol barriers enable microwave compatibility and lightweight logistics. Ready-to-eat meal producers in Japan and South Korea are expanding pouch adoption fastest, though high-pressure processing equipment is compressing addressable volume in certain protein applications.
- Rigid Containers:Polypropylene tubs with foil lidding serve soups and sauces where stackability determines retail shelf economics.
- Bottles:HDPE and PET structures with sterile blow-fill-seal integration support resealable beverage formats.
- Cups:Single-serve yogurt and dessert applications favor pre-formed cup sterilization for portion control.
Carton packs lead volumes today; flexible pouches are gaining share fastest.
Application:
Cost tier stratification separates premium organic positioning from commodity ambient distribution, with sterilization intensity scaling across acid and low-acid food categories.
- Dairy Products:UHT milk, flavored dairy beverages, and plant-based alternatives dominate aseptic carton consumption. Chinese dairy giants in Shandong and Hebei provinces are building concentrated filling capacity, while German cooperatives pilot mono-material polyethylene formats to preempt EU Green Deal recyclability mandates.
- Juices & Beverages:NFC and concentrate formats require varying barrier specifications. Turkish and Egyptian juice importers are restructuring supply chains to secure EFSA pre-certified laminate sources amid REACH hydrogen peroxide residual tightening.
- Soups & Sauces:Low-acid sterilization protocols favor rigid container formats with retort-equivalent thermal processing.
- Baby Food:Stringent migration limits for polyethylene and ethylene vinyl alcohol layers concentrate demand among validated European and North American suppliers.
- Ready-to-Eat Meals:Flexible pouch adoption is climbing fastest in Asian markets, though retort substitution pressure persists.
Dairy applications anchor revenue concentration; ready-to-eat meals show the steepest expansion trajectory.
Packaging Material:
Supply concentration for high-barrier inputs creates margin pressure, with domestic substitution accelerating in China and carbon border adjustments reshaping European sourcing.
- Paperboard:Bleached kraft pulp structures provide rigidity and print surface for retail differentiation. Swedish and Finnish suppliers dominate virgin fiber sourcing, while recycled content integration is advancing to meet extended producer responsibility mandates in France, Germany, and Italy.
- Aluminum Foil:Three European suppliers control high-barrier foil production for aseptic cartons. Energy cost volatility in 2022-2023 exposed input concentration risk, accelerating investment in polyethylene-aluminum separation technologies for recycling compliance.
- Polyethylene:Extrusion coating and lamination layers are absorbing capital from foil equipment as mono-material structures gain trial.
- Polypropylene:Rigid container and cap applications favor clarity and thermal resistance for hot-fill compatibility.
- Ethylene Vinyl Alcohol:Oxygen barrier coextrusions face expanded EFSA migration testing scope, delaying validation for novel laminate constructions.
Paperboard-aluminum laminates dominate installed base; polyethylene mono-materials are climbing the fastest.
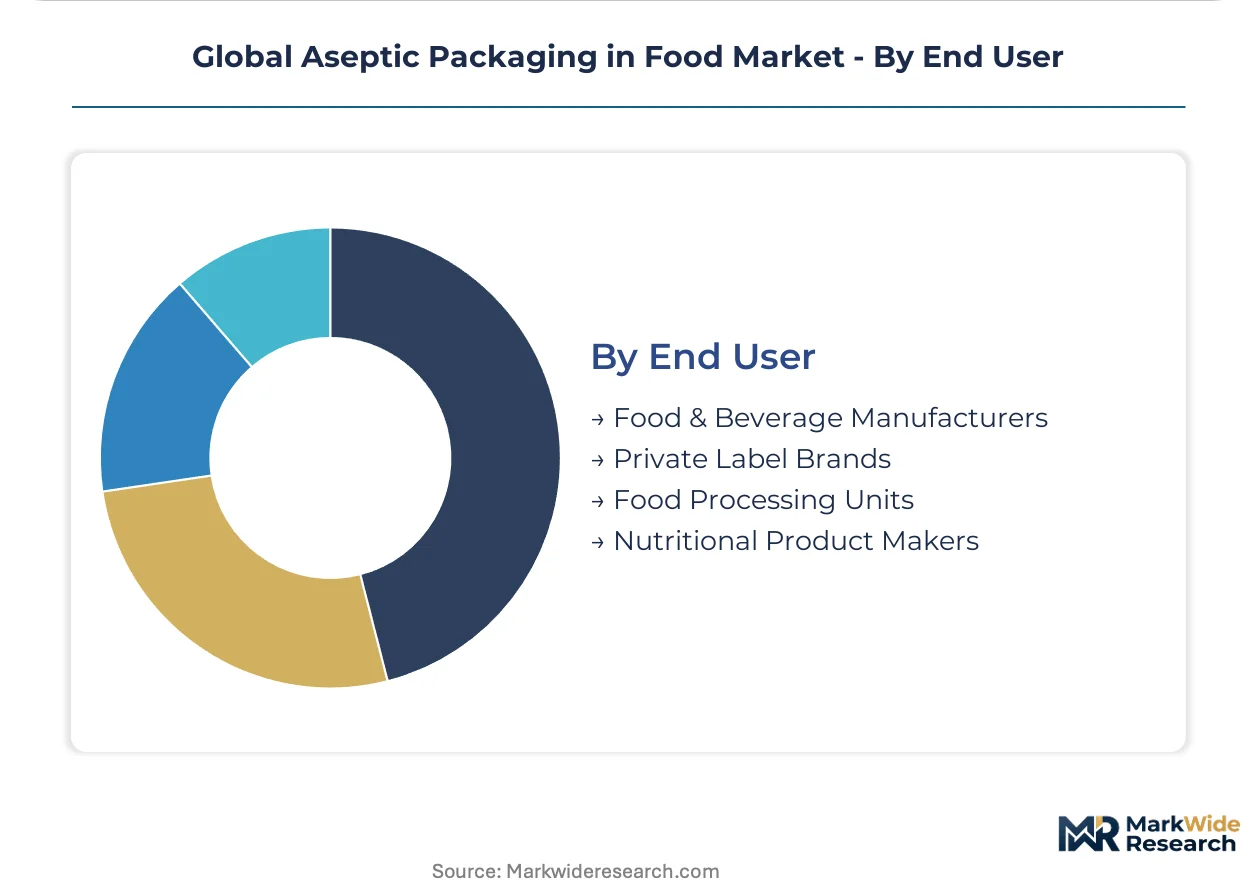
End User:
Procurement scale and technical capability stratify how filling-line risk is contracted, with throughput-guarantee models displacing traditional maintenance agreements among volume leaders.
- Food & Beverage Manufacturers:Tier-one multinationals negotiate outcome-based service contracts transferring mechanical risk to OEMs. Tetra Pak's integrated plant-management platforms and SIG Combibloc's modular retrofit kits compete for this segment's software-defined filling-line investments.
- Private Label Brands:Retailer-owned labels concentrate sleeve procurement through Greatview Aseptic Packaging's Chinese dairy supply chain integration, leveraging localized production for cost positioning.
- Food Processing Units:Mid-scale operators in Brazil and Mexico face electromechanical technician scarcity, extending commissioning timelines for IoT-enabled legacy line retrofits.
- Nutritional Product Makers:Clinical and sports nutrition formats demand validated barrier performance for extended shelf stability.
Food and beverage manufacturers command the largest procurement volumes; private label brands are expanding sourcing flexibility fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting aseptic packaging investment toward jurisdictions where ambient distribution infrastructure and carbon-border compliance create cost-of-compliance advantages for exporters. Production capacity is concentrating in regions with integrated pulp supply, established filling-line ecosystems, and favorable extended-producer-responsibility frameworks.
China
Domestic dairy giants and beverage multinationals are building regional aseptic filling capacity in Shandong and Hebei provinces. NMPA and GB standards impose eighteen-month parallel testing protocols for unvalidated laminate constructions, delaying market entry for novel barrier materials. Localized carton sleeve production through Greatview Aseptic Packaging anchors Chinese dairy supply chains with cost-competitive positioning.
Germany
Dairy cooperatives pilot mono-material polyethylene formats to preempt EU Green Deal recyclability mandates while expanding oat and soy milk aseptic carton adoption. EFSA migration testing protocols and REACH authorization requirements for hydrogen peroxide sterilizing agents tighten residual limits for paperboard food contact materials. Filling-line investments concentrate in Bavaria and North Rhine-Westphalia where technical service infrastructure supports software-defined architectures.
United States
FDA regulations governing low-acid canned food equivalents and EPA standards for sterilizing agent residuals shape product approval pathways for extended-shelf-life milk and plant-based alternatives. Ambient distribution networks for UHT milk remain underdeveloped in rural markets, creating white space for mobile filling units. Dairy processors in the Midwest and California dominate procurement volumes for carton pack formats.
India
UHT milk penetration lags in Bihar and Uttar Pradesh, creating expansion opportunities for localized sleeve production and distributed filling capacity. FSSAI standards for food contact materials impose testing requirements that favor established laminate suppliers with validated barrier performance. Electromechanical technician scarcity extends commissioning timelines for IoT-enabled legacy line retrofits across mid-scale operators in western and southern states.
France
Extended producer responsibility mandates require post-consumer carton recycling infrastructure as a licensing condition for retail shelf placement, accelerating investment in polyethylene-aluminum separation technologies. EU F-Gas Regulation refrigerant phase-downs force food processors toward ambient distribution chains. Dairy and juice processors in the Île-de-France and Auvergne-Rhône-Alpes regions concentrate aseptic filling investments to serve export markets.
Global Aseptic Packaging in Food Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEMs capturing premium-tier positions through outcome-based service contracts while regional converters compete on sleeve procurement cost. The vendor base stratifies into three tiers: full-system providers with plant-management platforms, modular retrofit specialists extending legacy asset lifecycles, and localized sleeve converters anchoring domestic supply chains. Consolidation pressure concentrates among aluminum laminate suppliers where energy cost volatility exposed input concentration risk. Dominant competitive moves include strategic partnerships for recycling infrastructure development and geographic expansion into underpenetrated ambient distribution markets.
Among integrated full-system providers, Tetra Pak and SIG Combibloc occupy positions exemplifying divergent approaches to software-defined filling-line monetization. Tetra Pak represents the service-layer transition through integrated plant-management platforms, while SIG Combibloc anchors the modular retrofit segment with legacy line lifecycle extension. Greatview Aseptic Packaging sits within the localized converter tier, anchoring Chinese dairy supply chains through domestic sleeve production capacity.
| Leading Market Players |
|---|
| Greatview Aseptic Packaging |
| Schott |
| Tetra Pak |
| Reynolds Group Holdings |
| Robert Bosch |
| SIG Combibloc |
| Elopak |
| ELOPak Group |
| Amcor |
| Others |
Supply & Pricing Matrix
EU F-Gas refrigerant phase-down mandates are forcing dairy processors toward ambient distribution chains, compelling laminate suppliers to absorb hydrogen peroxide sterilization equipment costs while OEMs shift toward throughput-guarantee contracts that compress hardware margins.
Pricing Analysis
Distributor margins for aseptic carton sleeves compress when energy volatility spikes aluminum foil input costs. Three-tier pricing structure across premium, standard, and economy levels separates EFSA pre-certified laminate sources from unvalidated constructions facing eighteen-month GB testing delays. Pricing pressure stems from mono-material polyethylene substitution in juice and plant-milk segments where six-month shelf life requirements relax barrier specifications. Private label brands anchored through Greatview's Chinese supply chain integration exhibit highest price sensitivity, while tier-one dairy multinationals in Shandong province prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Swedish and Finnish virgin fiber suppliers dominating bleached kraft pulp sourcing for paperboard rigidity. High-barrier foil production draws from three European suppliers concentrated in Germany and Austria, while polyethylene extrusion coating capacity expands fastest in China and the Netherlands. Supply chain risk centers on energy cost volatility exposing aluminum laminate concentration. Distribution runs through regional sleeve converters co-located with dairy processing clusters in Hebei province and Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in aseptic packaging hinges on software-defined service-layer monetization displacing capital-intensive hardware sales, with predictive maintenance subscriptions capturing recurring revenue from throughput-guarantee contracts.
For Market Incumbents: To counter SIG Combibloc's modular retrofit kits extending legacy line lifecycles, Tetra Pak should deepen plant-management platform integration while securing exclusive recycling infrastructure partnerships in France and Germany. Backward integration into polyethylene-aluminum separation technologies defends margin position against EU Green Deal carbon border adjustments. For New Entrants and Emerging Players: Begin with underdeveloped ambient distribution networks in Bihar and Uttar Pradesh, where UHT milk penetration lags and localized sleeve production paired with mobile filling units addresses electromechanical technician scarcity. Target mid-scale Brazilian operators facing commissioning delays for IoT-enabled retrofits with outcome-based service contracts that transfer mechanical risk. For Investors and Strategic Acquirers: Asymmetric upside sits with regional sleeve converters possessing validated EFSA barrier performance and co-location with dairy processing clusters. Five-to-ten year viability favors converters integrating recycled content to meet extended producer responsibility mandates. Watch for NMPA GB standards harmonization accelerating novel laminate validation timelines as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Filling-Line Platform | Enables predictive maintenance subscriptions that displace time-and-materials contracts for dairy processors. |
| Mono-Material Polyethylene Transition | Preempts EU Green Deal recyclability mandates while redirecting capital from foil lamination toward extrusion coating. |
| Polyethylene-Aluminum Separation Technology | Satisfies France and Germany's post-consumer carton recycling infrastructure licensing conditions. |
| Mobile Filling Unit Deployment | Penetrates rural India ambient distribution gaps without fixed-line infrastructure investment. |
| RFID-Integrated Smart Packaging | Enables real-time cold-chain verification for premium organic dairy exports to Japan and South Korea. |
Research Methodology
Bottom-up dairy processor procurement modeling reconciled against top-down laminate converter capacity tracking forms the analytical core. Primary interviews with filling-line OEM technical directors, dairy cooperative procurement leads, EFSA regulatory affairs specialists, and recycling infrastructure operators combined with secondary validation from SEC equipment supplier filings, EU F-Gas Regulation implementation reports, and Chinese NMPA GB standards documentation. Triangulation across these sources ensures supply-side and demand-side estimates converge.
Historical trendline analysis of UHT milk and plant-based beverage volume growth informs the projection framework across the analysis window. Segmentation dimensions modeled include product format, application category, barrier material composition, and end-user procurement scale. CAGRs derive from installed filling-line capacity expansion rates, regional dairy consumption elasticity, and regulatory compliance cost trajectories. Forecast inputs incorporate EU carbon border adjustment implementation timelines and NMPA validation protocol evolution.
Caveats apply where NMPA GB standards harmonization, REACH hydrogen peroxide residual limit tightening, or aluminum foil energy cost volatility could materially shift the outlook. Forecasts reflect documented assumptions about software-defined service contract adoption rates and extended producer responsibility mandate enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Instant Soup Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Instant Rice Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Europe Ready Meals Market