
 Pre-Packaged Food Market | 2026-2036
Pre-Packaged Food Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Packaged Food Market Analytics
The EU Green Deal is restructuring demand across European pre-packaged food supply chains by mandating recyclability thresholds and extended producer responsibility. Nestlé anchors its position through backward integration into sustainable packaging R&D. PepsiCo differentiates via direct-to-consumer channel investments and health-oriented portfolio reformulation. General Mills navigates cost volatility through long-term agricultural sourcing partnerships.
Pre-packaged food encompasses industrially processed items sealed in protective packaging to extend shelf life, maintain sensory quality, and enable distribution without immediate refrigeration. Manufacturing employs retort sterilization, modified atmosphere packaging, or blast freezing to achieve microbial stability and texture preservation for commercial resale. Frozen meals capture premium margin pools as consumers trade up to restaurant-quality convenience at home. Ready-to-eat meals sustain volume leadership in urban commuter corridors with limited cooking time. Flexible pouches displace rigid containers in snack packs as brands reduce material weight and logistics cost.
FDA nutrition labeling rules and EPA food waste reduction targets shape product formulation and portion architecture in the United States. EFSA additive safety assessments and REACH chemical compliance govern material selection for European exporters. Stakeholders must monitor evolving extended producer responsibility schemes and carbon border adjustments that will redefine cost-competitive sourcing geography.
Market Dynamics
The EU Green Deal's packaging waste directives are forcing material transitions across European pre-packaged food supply chains, while convenience-seeking working households in urban centers accelerate format innovation and channel restructuring.
Growth Catalysts
- Urban Commuter Density:Time-constrained professionals in metropolitan corridors sustain volume leadership for ready-to-eat meal formats as cooking time compresses.
- REACH Chemical Compliance:Material safety assessments in Europe are accelerating substitution toward bio-based barrier coatings and mono-material films.
- Retort Sterilization Advancement:High-pressure processing and advanced thermal technologies extend shelf-stable protein categories without refrigeration infrastructure.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin costs fluctuate with crude oil benchmarks, compressing margin predictability for flexible packaging converters.
- Extended Producer Responsibility Schemes:EU member states impose varying fee structures for packaging recovery, creating compliance fragmentation for pan-European brands.
- Refrigerated Last-Mile Constraints:Frozen meal penetration remains capped by cold chain gaps in secondary cities and rural distribution networks.
Strategic Opportunities
- Carbon Border Adjustment Mechanism:EU import levies on embodied carbon create first-mover advantage for regional producers with verified low-emission supply chains.
- Direct-to-Consumer Subscription Channels:Health-oriented meal kit platforms bypass traditional retail slotting fees and capture lifetime value through recurring revenue models.
- Modified Atmosphere Packaging Convergence:Integration of oxygen scavengers and intelligent freshness indicators enables premium positioning in unstaffed retail formats.
Industry Challenges
- Food Technologist Talent Scarcity:Formulation expertise combining clean-label requirements with extended shelf-life engineering commands premium compensation and lengthens R&D timelines.
- Multi-Material Separation Infrastructure:Existing municipal recycling systems cannot process laminated barrier films, forcing brands to fund dedicated collection and chemical recycling pilots.
- Legacy ERP Integration Friction:Traceability mandates for ingredient provenance require retrofitting decades-old manufacturing execution systems with blockchain-enabled audit layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Packaged Food Market |
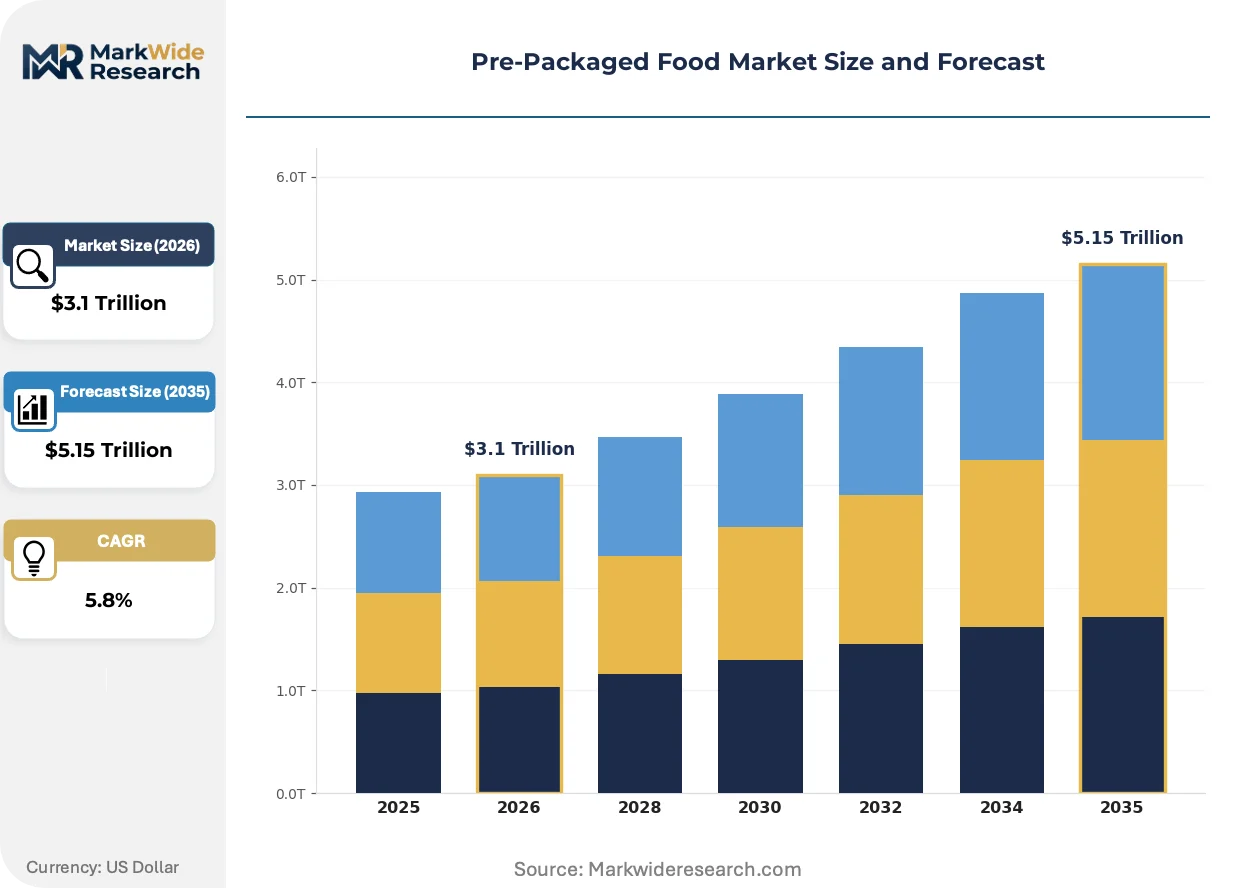
| Market Size in 2026 | $3.1 Trillion |
| Market Size in 2035 | $5.15 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Snack Packs, Ready-to-Eat Meals, Canned Foods End User: Households, Restaurants, Cafes, Catering Services Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Food Shops Packaging Type: Single-Serve Packs, Bulk Containers, Vacuum-Sealed Bags, Flexible Pouches |
| Companies Covered | Kellogg Company, PepsiCo, Danone SA, Mars, Inc., Conagra Brands, Inc., The Kraft Heinz Company, Nestlé, Tyson Foods, General Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Packaged Food Market Evolving Landscape
Active packaging technologies and regulatory pressure on single-use plastics are compressing development cycles and reshaping competitive positioning across format categories and geographic markets.
Mono-material polyethylene pouches with enhanced barrier coatings are absorbing volume share from multi-layer aluminum laminates in snack and sauce applications. Mid-tier brands in Germany and the United States are converting production lines at accelerated pace. The shift is absorbing capital that previously flowed into conventional rigid container equipment, consolidating supplier influence among specialized film extruders.
EFSA additive safety reassessments are triggering reformulation waves across preservative-dependent categories. Manufacturers are replacing synthetic antioxidants with rosemary extract and tocopherol blends in shelf-stable meats and oils. Ready-to-eat meal exporters to Europe face compressed certification timelines as the regulator tightens acceptable daily intake thresholds for legacy preservatives.
Dark store fulfillment networks are fragmenting retail concentration and shortening order-to-delivery windows for frozen and chilled categories. Quick-commerce platforms in urban China and the United States are capturing impulse meal occasions previously owned by convenience retail. The shift is most visible in Shanghai and New York metropolitan zones where 15-minute delivery guarantees now anchor customer acquisition strategies.
Pre-Packaged Food Market Segmentation
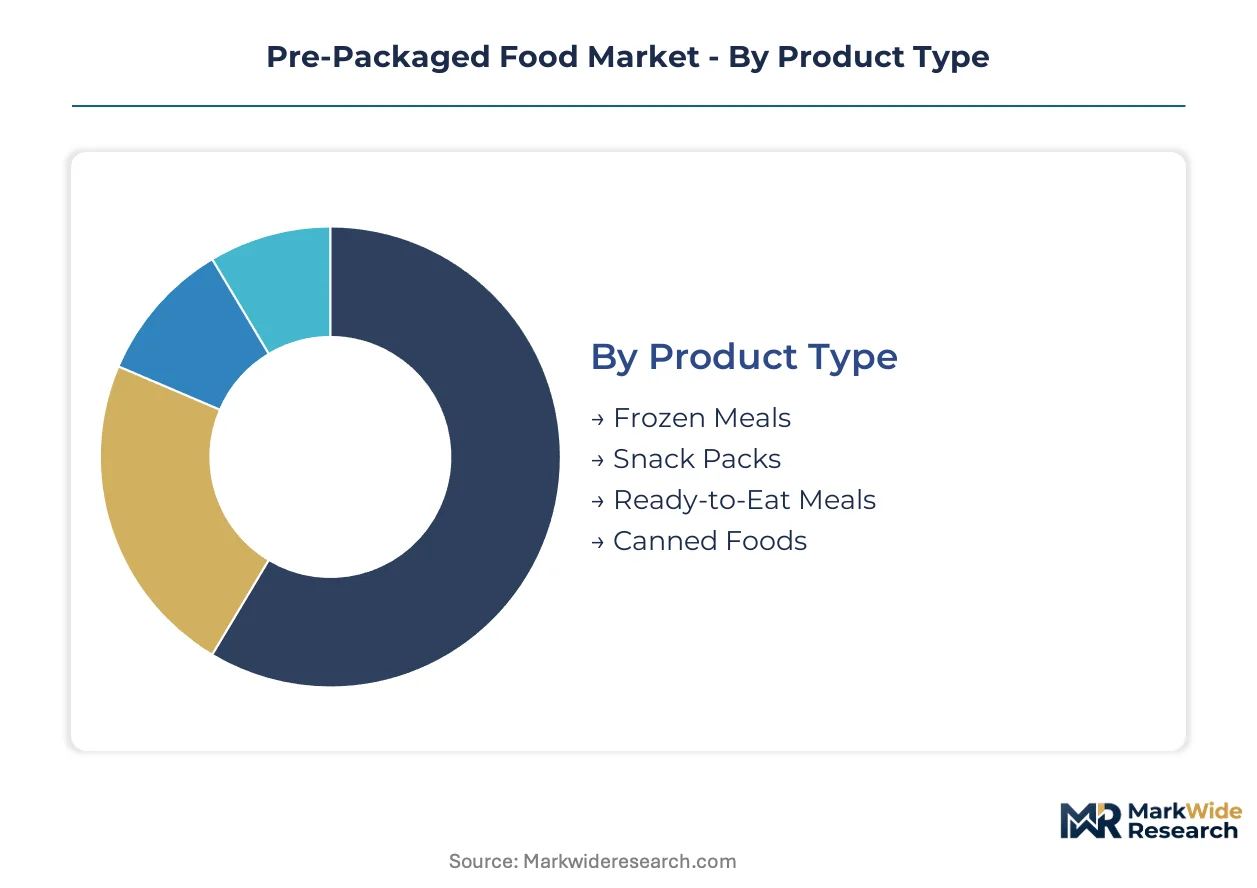
Pre-packaged food manufacturers calibrate portfolio allocation across four intersecting dimensions. Product format determines capital intensity and cold chain requirements. End-user concentration shapes pricing architecture and promotional cadence. Channel mix dictates packaging specifications and shelf-life engineering. Material selection governs regulatory compliance exposure and logistics economics.
Product Type:
Cost tier separates buyers seeking meal solutions from those prioritizing portion-controlled indulgence.
- Frozen Meals:Complete entrees requiring blast freezing and sustained cold chain integrity. Demand concentrates in United States metropolitan commuter corridors where restaurant-quality convenience commands premium positioning against time-starved professionals.
- Ready-to-Eat Meals:Shelf-stable or chilled preparations requiring no preparation beyond opening. Adoption accelerates in German urban centers under EU Green Deal packaging mandates that favor reduced refrigeration energy intensity.
- Snack Packs:Portion-controlled savory or sweet items targeting impulse consumption occasions.
- Canned Foods:Retort-sterilized vegetables, proteins, and prepared dishes in rigid metal containers.
Volume sits with ready-to-eat formats; growth tilts toward frozen meals.
End User:
Application context distinguishes procurement scale and specification stringency.
- Households:Individual and family units purchasing for home consumption. Chinese tier-one city households drive format innovation as quick-commerce platforms fragment traditional retail concentration and compress delivery windows.
- Restaurants:Foodservice operations sourcing pre-portioned ingredients or finished components. Kitchen labor scarcity across United States urban markets accelerates adoption of sous-vide proteins and pre-composed bases.
- Cafes:Beverage-forward establishments requiring complementary food offerings with minimal preparation footprint.
- Catering Services:Event and institutional food providers demanding batch consistency and transport durability.
Households anchor volume; catering services expand most quickly.
Distribution Channel:
Customer type determines fulfillment infrastructure and margin architecture.
- Supermarkets:Full-assortment retail formats with dedicated frozen and chilled sections. German chains Edeka and REWE are consolidating supplier relationships under extended producer responsibility schemes that penalize non-recyclable packaging.
- Online Retail:Digital-native platforms with home delivery fulfillment. Dark store networks in Shanghai and New York metropolitan zones now guarantee 15-minute delivery for frozen and chilled categories.
- Convenience Stores:Small-format urban retail targeting immediate consumption occasions.
- Specialty Food Shops:Curated assortments emphasizing provenance, dietary certification, or artisan positioning.
Supermarkets retain volume leadership; online retail climbs the fastest.
Packaging Type:
Supply concentration among specialized converters shapes material availability and cost trajectories.
- Flexible Pouches:Multi-layer or mono-material films replacing rigid containers across snack and sauce applications. Mid-tier brands in Germany and the United States are absorbing capital previously allocated to conventional rigid equipment.
- Vacuum-Sealed Bags:Barrier films with oxygen exclusion extending refrigerated protein shelf life. REACH chemical compliance is accelerating substitution toward bio-based barrier coatings in European supply chains.
- Single-Serve Packs:Individual portions targeting portion control and waste reduction mandates.
- Bulk Containers:Large-format packaging for foodservice and institutional procurement.
Flexible pouches capture volume; vacuum-sealed formats gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, the United States, and China, while consumption concentrates in urban corridors across these same markets. Cold chain infrastructure gaps separate high-penetration metropolitan zones from underdeveloped secondary cities.
United States
Time-starved professionals in New York and Los Angeles metropolitan zones sustain premium frozen meal demand. FDA nutrition labeling rules and EPA food waste reduction targets reshape portion architecture and formulation standards. Chicago anchors Midwest production with Tyson Foods maintaining protein processing dominance and General Mills operating cereal and snack manufacturing at scale.
Germany
EU Green Deal packaging mandates accelerate mono-material transitions across ready-to-eat categories. EFSA additive safety reassessments compress certification timelines for preservative-dependent imports. The Rhine-Ruhr industrial corridor hosts concentrated flexible packaging converter capacity serving pan-European supply chains.
China
Quick-commerce platforms in Shanghai and Beijing fragment traditional retail concentration with 15-minute delivery guarantees. SAMR food safety standards and dual carbon goals pressure domestic manufacturers toward cleaner production methods. The Yangtze River Delta clusters dark store fulfillment networks capturing impulse meal occasions from convenience retail.
Japan
Aging demographics and single-person households expand shelf-stable and single-serve format penetration. METI circular economy guidelines and plastic resource recycling laws mandate design-for-recyclability in packaging systems. The Kanto region around Tokyo concentrates premium convenience store innovation and automated retail format testing.
India
Tier-one city households in Mumbai and Delhi drive format experimentation as quick-commerce platforms compress delivery windows. FSSAI labeling regulations and PLI scheme incentives for food processing infrastructure attract capital investment. Gujarat and Maharashtra host emerging contract manufacturing clusters serving both domestic and Middle East export markets.
Pre-Packaged Food Market Competitive Landscape
The competitive structure tilts toward diversified multinationals with portfolio breadth spanning frozen, shelf-stable, and snack categories. Tiered concentration separates global scale players from regional specialists and private-label suppliers. Strategic archetypes include backward-integrated ingredient controllers, direct-to-channel disruptors, and health-positioning reformulators. Capacity expansion and packaging material transitions dominate competitive moves as firms absorb EU regulatory compliance costs.
Among diversified multinationals, Nestlé, PepsiCo, and General Mills occupy distinct positioning vectors. Nestlé exemplifies the backward-integrated archetype through captive supply chain control. PepsiCo represents channel diversification momentum with health-oriented portfolio evolution. General Mills anchors the Midwest production base with long-term agricultural sourcing partnerships. Each occupies a definable tier without overlapping strategic territory.
| Leading Market Players |
|---|
| Kellogg Company |
| PepsiCo |
| Danone SA |
| Mars, Inc. |
| Conagra Brands, Inc. |
| The Kraft Heinz Company |
| Nestlé |
| Tyson Foods |
| General Mills, Inc. |
| Others |
Value Network & Pricing Analysis
Urban commuter households in United States and German metropolitan corridors concentrate procurement scale for ready-to-eat formats, anchoring contract-based pricing with annual volume commitments that lock in slotting fees and promotional allowances across supermarket and quick-commerce channels.
Pricing Analysis
Cost compression in flexible packaging tiers reflects polypropylene and polyethylene resin volatility tied to crude oil benchmarks, forcing converters to absorb margin erosion or renegotiate annual contracts with frozen meal brands. Three-tier pricing structure across premium restaurant-quality, standard family-portion, and economy value-tier entrees separates buyers by preparation time sensitivity and ingredient provenance claims. Price differentiation traces to clean-label certification intensity and cold chain delivery guarantees. Quick-commerce subscribers in Shanghai and New York demonstrate lowest price sensitivity; rural secondary-city distributors face highest switching propensity.
Supply Chain Analysis
EU Green Deal packaging certification gates supplier qualification, requiring mono-material recyclability documentation and extended producer responsibility fee structures before listing approval at Edeka, REWE, and Carrefour banners. Supply concentrates in Germany, the United States, and China, with the Rhine-Ruhr corridor hosting specialized film extruders and the Yangtze River Delta clustering dark store fulfillment infrastructure. Raw material dependencies center on bio-based barrier coatings, food-grade polyethylene resins, and retort-sterilization equipment. Single-source vulnerability sits with European flexible packaging converters lacking chemical recycling partnerships. Distribution runs through supermarket centralized distribution centers, quick-commerce dark stores, and foodservice redistribution depots.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-packaged food manufacturing is transitioning from multi-layer aluminum laminates to mono-material polyethylene systems, with active packaging technologies displacing legacy preservative-dependent formulations across frozen and shelf-stable categories.
For Market Incumbents: Deploy backward integration into sustainable packaging R&D to capture EU Green Deal compliance premiums before 2025 regulatory deadlines. Nestlé's captive supply chain model demonstrates defensive value against raw material volatility. Incumbents must retrofit legacy ERP systems with blockchain-enabled traceability layers to defend slotting fee structures against quick-commerce platform disintermediation. For New Entrants and Emerging Players: EU Green Deal packaging mandates in Germany open a window for mono-material pouch specialists to capture share from rigid container incumbents. White-space targets include unstaffed retail formats in Japanese metropolitan zones and dark store supply partnerships in Chinese tier-one cities. Go-to-market positioning should emphasize oxygen-scavenger integration and intelligent freshness indicators for premium convenience channels. For Investors and Strategic Acquirers: The window for entry favors mid-tier brands with verified low-emission supply chains positioned for EU Carbon Border Adjustment Mechanism advantages. Acquisition targets should demonstrate scalable modified atmosphere packaging capabilities and established quick-commerce distribution partnerships. Signal to monitor: EFSA additive safety reassessment timelines compressing certification windows for preservative-dependent import categories.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Transition | EU Green Deal compliance locks in supplier relationships at Edeka and REWE chains. |
| Direct-to-Consumer Channel Expansion | Subscription meal kits bypass supermarket slotting fees and capture recurring revenue pools. |
| Active Packaging Technology Integration | Oxygen scavengers and freshness indicators enable premium positioning in unstaffed retail. |
| Backward Integration into Bio-Based Barriers | REACH chemical compliance accelerates substitution toward captive coating production. |
| Dark Store Fulfillment Partnership | 15-minute delivery guarantees in Shanghai and New York anchor customer acquisition strategies. |
Research Methodology
Document review covered FDA nutrition labeling guidance, EFSA additive safety assessments, EU Green Deal packaging directives, and customs trade data for polyethylene resin imports, complemented by interviews with frozen meal brand managers, flexible packaging procurement leads at Tier 1 converters, supermarket category buyers at German and United States chains, quick-commerce supply chain directors, and food technology R&D heads. Secondary validation drew from SEC 10-K filings, Nielsen retail audit data, and industry association reports. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Segmentation outputs reflect product type, end-user concentration, distribution channel mix, and packaging material selection dimensions across the projection horizon. CAGRs were derived from regression analysis against urban commuter density indices, cold chain infrastructure penetration rates, and regulatory compliance cost absorption curves. Industry-specific inputs included EFSA reassessment timelines, EU member state extended producer responsibility fee structures, and quick-commerce platform expansion trajectories in Chinese and United States metropolitan zones.
The model assumes a particular technology adoption path for mono-material flexible packaging; alternative pathways for multi-layer chemical recycling would alter the outlook for incumbent converter equipment valuations. Forecasts reflect assumptions regarding EU regulatory implementation timing and petrochemical feedstock price stabilization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Chestnut Flour Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Dried Honey Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Packaged Rice Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Europe Breakfast Cereals Market