
 US Packaged Food Market | 2026-2036
US Packaged Food Market Size, Share, and Industry Trends Forecast 2026-2036
US Packaged Food Market Intelligence
The gap between premium, clean-label products and value-focused commodity staples is broadening within the US packaged food sector, creating distinct competitive arenas. This divergence forces brands to choose between ingredient transparency and cost leadership. Kraft Heinz Company leverages its extensive distribution network to sustain market presence for its core brands. In contrast, PepsiCo differentiates through significant investment in snack and beverage innovation to capture shifting consumer preferences.
Packaged food encompasses items processed and sealed in containers before sale to offer preservation, convenience, and safety. These products often undergo processes like pasteurization, freezing, or aseptic packaging to extend shelf life and ensure microbial stability. Their primary purpose is to provide ready-to-eat or easy-to-prepare meals and ingredients for retail consumers and foodservice operators. Analysis of product types shows that the snacks category continues to drive innovation, while frozen meals offer consistent margin opportunities for established manufacturers.
The US Food and Drug Administration (FDA) and the US Department of Agriculture (USDA) enforce stringent food safety and labeling standards. Regulations such as the Food Safety Modernization Act (FSMA) mandate preventive controls across the entire supply chain. The Federal Trade Commission (FTC) also governs marketing claims related to health benefits and nutritional content. Producers must now decide whether to invest in clean-label reformulations or compete primarily on price and convenience within their chosen segments.
Market Dynamics
The divergence between health-focused and value-driven consumer segments is the central force shaping the US packaged food market. This pressure compels brands to make clear strategic choices regarding ingredient sourcing, product formulation, and price positioning.
Growth Catalysts
- Demand for Convenience:Strong demand for portion-controlled, easy-to-prepare foods within the US foodservice channel, particularly in quick-service restaurants and institutional catering, drives volume for specific product categories like frozen meals and snacks.
- Plant-Based Adoption:Consumer preference for plant-based and free-from food options, with demand concentrated in major metropolitan areas across states like California and Texas, creates new product development opportunities.
- Regulatory-Driven Reformulation:The FDA's updated nutrition labeling rules create a market for reformulated products that can transparently advertise health-oriented attributes like lower sugar or higher fiber content.
Market Restraints
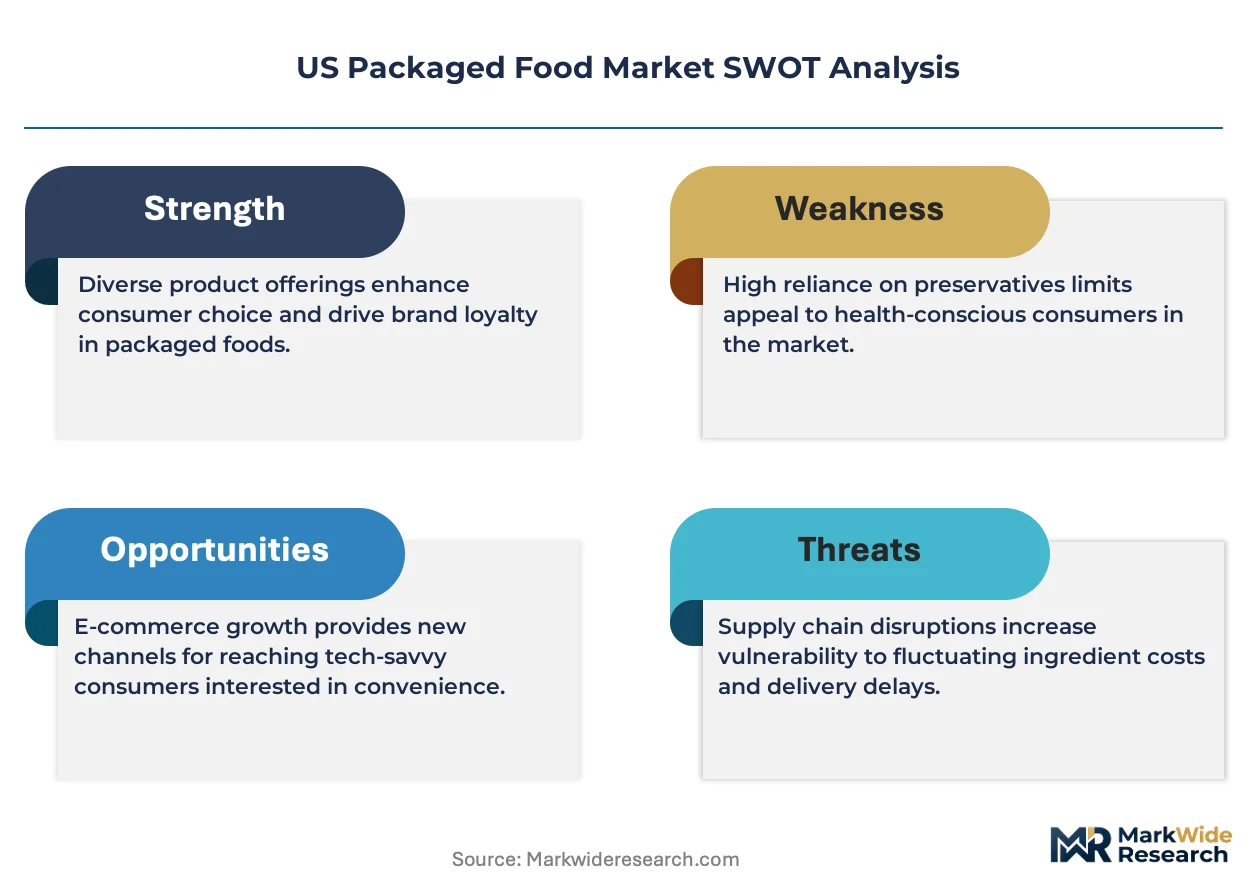
- Input Cost Volatility:Price fluctuations for essential agricultural commodities, including wheat, corn, and edible oils, create significant margin pressure and complicate long-term cost management for manufacturers.
- Regulatory Compliance Burden:The high cost and operational complexity of implementing and documenting the preventive controls required by the Food Safety Modernization Act (FSMA) pose a barrier for smaller producers.
- Substitution by Fresh Alternatives:Growing competition from non-packaged meal kits and fresh prepared foods available in retail stores appeals to consumers actively seeking alternatives to shelf-stable or frozen processed items.
Strategic Opportunities
- Direct-to-Consumer Channels:Utilizing e-commerce platforms to market niche, premium, or specialized packaged foods directly to consumers allows brands to bypass retail gatekeepers and build direct relationships with their customer base.
- Smart Packaging Integration:Incorporating technologies like QR codes on packaging provides consumers with enhanced product transparency, including ingredient sourcing, allergen information, and sustainability metrics, meeting demand for traceability.
- Foodservice Customization:Developing customized packaged ingredients and meals for specific foodservice segments, such as healthcare and education, addresses their unique nutritional guidelines and operational needs.
Industry Challenges
- Supply Chain Reconfiguration:The operational friction and investment required to reconfigure supply chains to secure a consistent supply of certified organic, non-GMO, or sustainably sourced ingredients is a major hurdle.
- Flexible Manufacturing Investment:High capital expenditure is needed to upgrade or install new manufacturing lines that can handle greater ingredient diversity and support smaller, more frequent production runs for niche products.
- Labeling Compliance Execution:The administrative burden of updating thousands of individual product labels to comply with the FDA's evolving nutrition and menu labeling rules across a vast and diverse product portfolio.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Packaged Food Market |
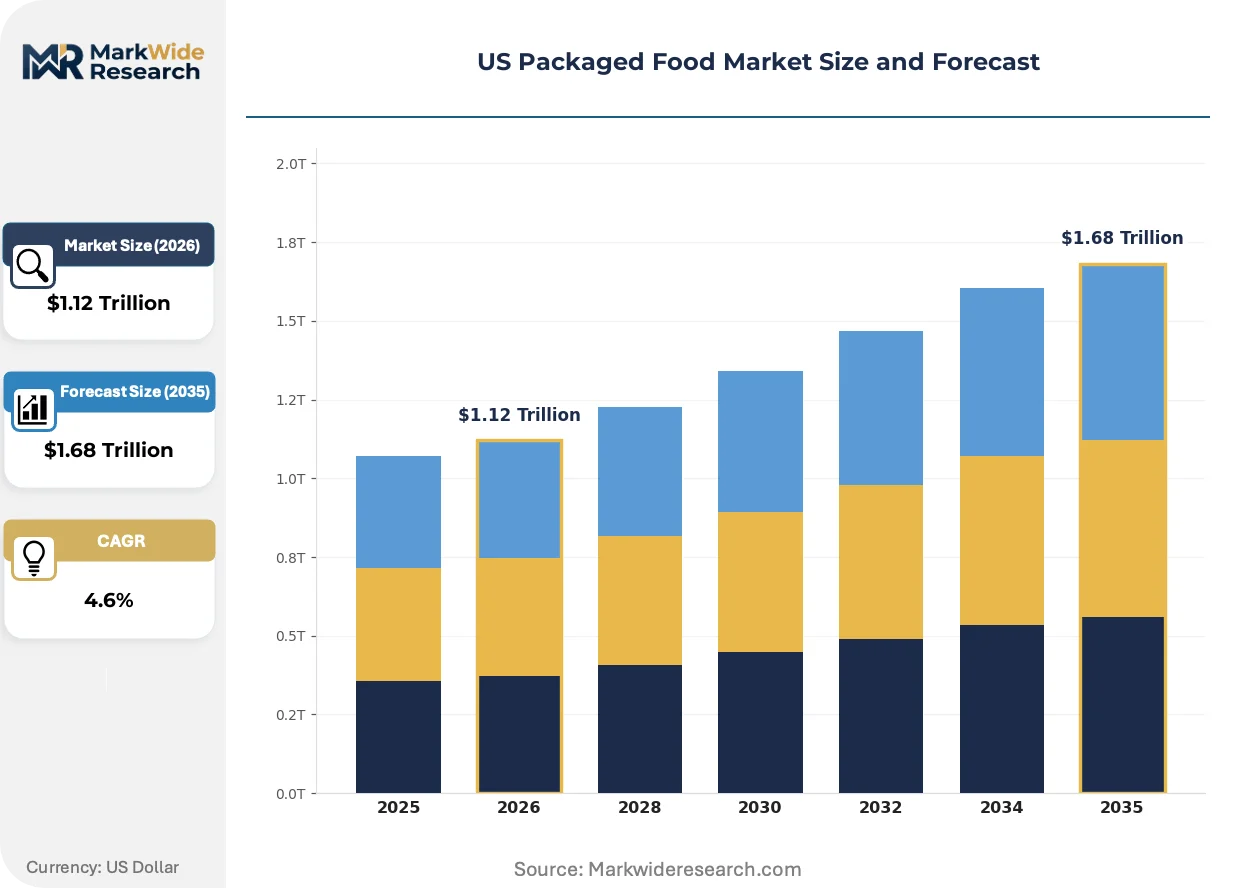
| Market Size in 2026 | $1.12 Trillion |
| Market Size in 2035 | $1.68 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Goods, Frozen Meals, Snacks, Condiments End User: Retail Consumers, Foodservice, Wholesalers, Institutions Packaging Type: Flexible Packaging, Rigid Packaging, Glass Containers, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Bulk Distributors |
| Companies Covered | The Coca-Cola Company, Kraft Heinz Company, PepsiCo, Mars, Tyson Foods, Unilever USA, General Mills, Nestlé, Mondelēz International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Packaged Food Market Strategic Shifts & Innovations
Product development is increasingly guided by a dual focus on nutritional science and supply chain transparency. Innovations in food processing and packaging materials are enabling manufacturers to meet consumer demands for both clean-label ingredients and extended shelf stability in the US market.
High-Pressure Processing (HPP) is a non-thermal pasteurization technique that preserves the nutritional value and sensory qualities of food. Premium food manufacturers are adopting it for products like cold-pressed juices and ready-to-eat meals. This technology is expanding into categories such as plant-based dips and sauces, enabling brands to market clean-label items without chemical preservatives.
The US Food and Drug Administration’s mandate for disclosing "added sugars" on the Nutrition Facts panel is a significant regulatory driver. This rule forces manufacturers to rethink formulations that rely heavily on sweeteners for flavor and texture. The snack and beverage segments are most impacted, accelerating research into natural, low-calorie sugar alternatives and prompting shifts toward smaller portion sizes.
Consumer purchasing behavior is shifting towards curated, subscription-based services for specialty and staple food items. This direct-to-consumer model disrupts the traditional grocery channel by offering personalized selections and convenience, reducing reliance on in-store discovery. The behavior is most pronounced among households in urban centers on the West Coast and in the Northeast, particularly for ethnic and wellness-oriented products.
US Packaged Food Market Segmentation
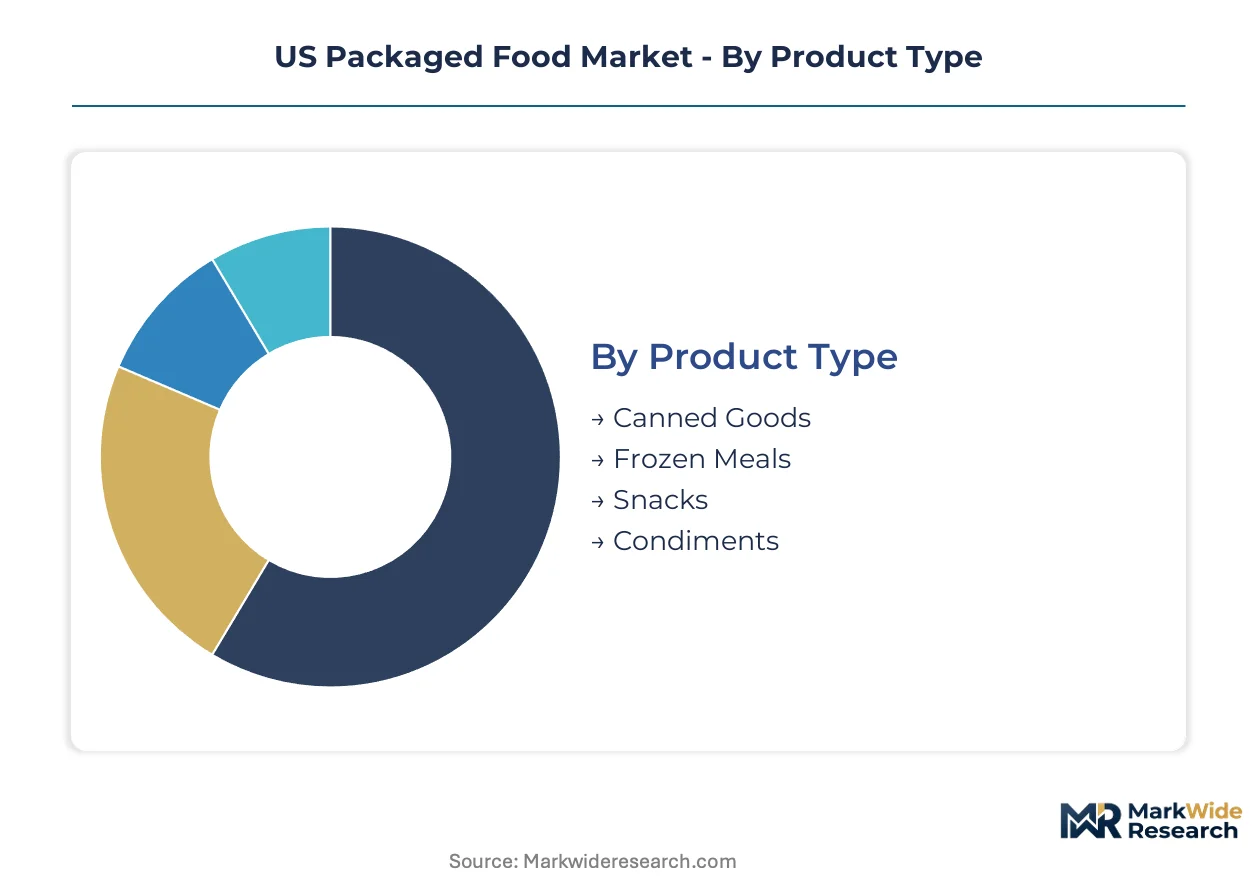
The US packaged food market is highly diverse, necessitating a detailed segmentation analysis to understand the varying consumer needs and operational demands. This dissection reveals distinct competitive landscapes and strategic opportunities across product categories, end-user groups, packaging innovations, and distribution channels. Understanding these segments helps brands tailor their offerings to specific market dynamics.
Product Type:
Consumer purchasing decisions for packaged food products in the US are heavily influenced by meal occasion, preparation time, and perceived nutritional value.
- Snacks:Snacks encompass a broad array of ready-to-eat items, including chips, crackers, confectionery, and nutrition bars, designed for immediate consumption. Demand for convenient, portion-controlled snack options is concentrated in metropolitan areas, driven by busy consumer lifestyles and the need for on-the-go sustenance.
- Frozen Meals:Frozen meals consist of pre-prepared, often multi-component food items that require only heating, preserving freshness through freezing technology. Established manufacturers find consistent margin opportunities in this category, particularly as foodservice operators seek easy-to-prepare solutions for institutional catering.
- Canned Goods:Canned goods, sealed in airtight containers and heat-treated, provide extended shelf stability for fruits, vegetables, meats, and soups, offering long-term pantry staples.
- Condiments:Condiments include sauces, dressings, and spices used to enhance the flavor of prepared foods, with consumer preferences shifting towards healthier and ethnic varieties.
Volume sits with Canned Goods due to their staple nature; growth tilts toward Snacks.
End User:
The application of packaged food products varies significantly across different customer types, dictating product formats and procurement strategies.
- Retail Consumers:Retail consumers purchase packaged food items directly from grocery stores, online platforms, and convenience outlets for in-home preparation and consumption. Demand for health-oriented and plant-based options is particularly strong among retail consumers in major metropolitan areas like California and Texas.
- Foodservice:Foodservice operators, including restaurants, cafes, and catering companies, utilize packaged ingredients and ready-to-serve items to streamline kitchen operations. The foodservice channel exhibits strong demand for portion-controlled and easy-to-prepare foods, influencing product development for this segment.
- Wholesalers:Wholesalers act as intermediaries, distributing bulk quantities of packaged food products to smaller retailers and independent foodservice establishments.
- Institutions:Institutions, such as hospitals, schools, and corporate cafeterias, require customized packaged food solutions that meet specific dietary guidelines and operational needs.
The segment exhibiting the steepest expansion trajectory is Foodservice, while Retail Consumers maintain a foundational role.
Packaging Type:
The choice of packaging material is often a function of product preservation requirements, cost efficiency, and consumer convenience.
- Flexible Packaging:Flexible packaging includes bags, films, and wraps made from materials like plastic or foil, offering lightweight, cost-effective, and adaptable solutions for various food items. This type of packaging is widely adopted for snacks and frozen foods, contributing to reduced transportation costs and extended shelf life through barrier properties.
- Rigid Packaging:Rigid packaging encompasses containers like plastic tubs, cartons, and metal cans, providing robust protection, stackability, and often resealable features for products. Manufacturers utilize rigid formats for items requiring structural integrity, such as dairy products, ready meals, and some beverages, ensuring product safety and integrity.
- Glass Containers:Glass containers offer inertness and premium perception for products like sauces, jams, and baby food, providing excellent barrier properties and recyclability.
- Pouches:Pouches, including stand-up and spouted varieties, are a growing segment offering convenience, reduced material usage, and portion control for items like purees and sauces.
Demand for Pouches is gaining share fastest, with Flexible Packaging holding substantial market presence.
Distribution Channel:
Access to packaged food products for US consumers is determined by the reach and specialized offerings of diverse distribution networks.
- Supermarkets:Supermarkets represent the primary retail channel, offering a vast assortment of packaged food products from various brands, catering to diverse consumer needs. Kraft Heinz Company leverages its extensive distribution network through these stores to maintain a strong market presence for its core brands across the US.
- Online Retail:Online retail platforms facilitate direct-to-consumer sales, allowing brands to offer specialized or niche packaged foods and subscription services. This channel is particularly strong among households in urban centers on the West Coast and Northeast for ethnic and wellness-oriented products.
- Convenience Stores:Convenience stores provide quick access to impulse purchases and essential packaged food items, serving consumers seeking immediate consumption options.
- Bulk Distributors:Bulk distributors supply large quantities of packaged food products to foodservice operators and institutions, optimizing logistics for high-volume procurement.
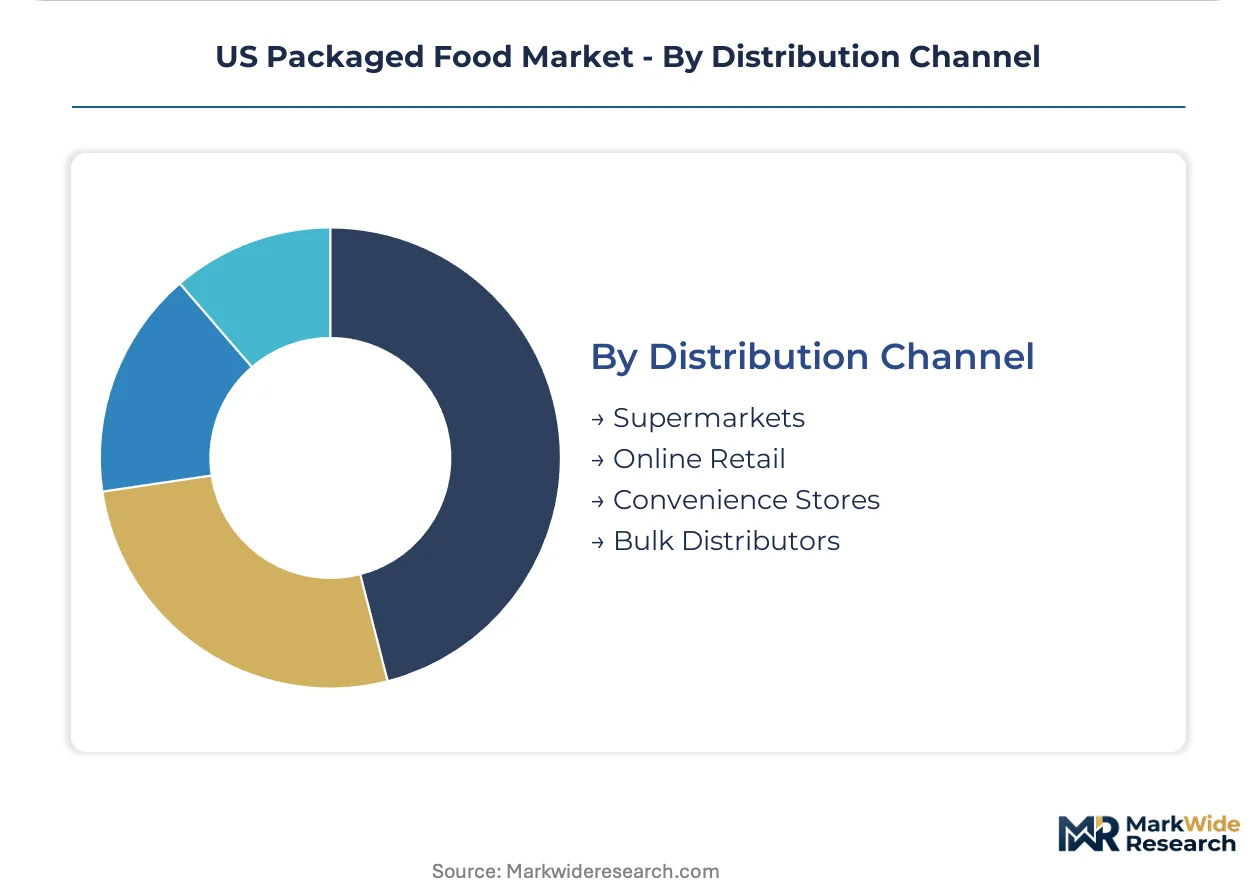
The largest volume of transactions occurs through Supermarkets, while Online Retail demonstrates significant expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles and San Francisco drive significant demand for health-oriented and plant-based packaged foods. These urban centers influence product innovation and retail trends across the US West Coast. Consumer preferences in these areas often set benchmarks for national market shifts.
California
California consumers exhibit strong preferences for plant-based and free-from food options, particularly in major metropolitan areas. The California Food Safety Act influences ingredient sourcing and transparency for manufacturers operating in the state. Product development in the San Francisco Bay Area often focuses on premium, clean-label packaged foods. This region also leads in subscription-based services for specialized food items.
Texas
Texas metropolitan areas like Dallas and Houston show robust demand for convenient, easy-to-prepare packaged foods, including frozen meals and snacks. The state's Department of State Health Services enforces food safety standards for local producers and distributors. Foodservice customization is a strategic opportunity for brands targeting the growing institutional catering sector in Austin. This demand profile supports both value-focused and health-conscious offerings.
New York Metro
New York City consumers prioritize convenience and diverse ethnic food options within the packaged food market. The New York State Department of Agriculture and Markets oversees food labeling and safety compliance for regional manufacturers. Online retail platforms in Manhattan and Brooklyn facilitate the growth of niche, wellness-oriented products. This dense urban environment encourages innovation in portion-controlled and ready-to-eat formats.
Midwest
Midwestern states, including Illinois and Ohio, demonstrate consistent demand for commodity staples and value-focused packaged goods. The USDA's inspection programs ensure quality and safety for meat and dairy products produced in states like Wisconsin. Chicago serves as a major distribution hub, supporting extensive supply chains for frozen meals and canned goods. Manufacturers in this region often leverage established distribution networks.
US Packaged Food Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the US packaged food market, creating distinct competitive arenas. The market exhibits a tiered structure, with large, established corporations coexisting with agile, niche players focused on specific consumer segments. Strategic archetypes include diversified conglomerates leveraging extensive distribution, specialized premium brands emphasizing clean labels, and cost-efficient commodity providers. Companies often engage in portfolio diversification and strategic partnerships to expand market reach and adapt to evolving consumer preferences.
Within the diversified conglomerate tier, Kraft Heinz Company and PepsiCo exemplify broad market penetration across multiple packaged food categories. Kraft Heinz Company represents a player leveraging extensive distribution networks for its core brands, maintaining a strong presence in traditional retail channels. PepsiCo, a New York-headquartered corporation, occupies a position defined by significant investment in snack and beverage innovation to capture shifting consumer preferences. Nestlé, a global food and beverage giant, anchors the premium and health-oriented segments, often through strategic acquisitions and specialized product lines in the US.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Kraft Heinz Company |
| PepsiCo |
| Mars |
| Tyson Foods |
| Unilever USA |
| General Mills |
| Nestlé |
| Mondelēz International |
| Others |
Cost & Logistics Intelligence
The Food Safety Modernization Act (FSMA) mandates preventive controls, gating access to qualified suppliers and influencing premium-tier product pricing. Compliance costs for food safety and labeling impact pricing power across the value chain.
Pricing Analysis
Value-based pricing anchors around convenience and perceived health benefits for packaged foods. Price differentiation stems from clean-label certifications, brand premium for health-oriented products, and customization for foodservice. Pricing softness reflects input cost volatility for commodity staples, impacting value-focused offerings across retail channels. Retail consumers are highly price-sensitive for basic goods, while foodservice operators prioritize consistency, portion control, and specific dietary compliance.
Supply Chain Analysis
FDA and USDA certifications gate ingredient sourcing and processing capabilities for US packaged foods, impacting small and large producers. The supply chain sources agricultural commodities from the US, Canada, and Mexico. Key dependencies include wheat, corn, and various edible oils, creating commodity price volatility risk for manufacturers. Downstream distribution primarily involves supermarkets, online retail, and bulk distributors for foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US packaged food market is supply-constrained, with flexible manufacturing capacity for niche products representing a key bottleneck. This scarcity props up pricing power for specialized and clean-label offerings.
For Market Incumbents: To counter competition from fresh alternatives, incumbents should deepen vertical integration into specialized ingredient sourcing. Consolidate distribution networks to optimize logistics for high-volume staples. Invest in flexible manufacturing lines to adapt to diverse product portfolios, mitigating market share erosion.
For New Entrants and Emerging Players: Enter via direct-to-consumer e-commerce platforms, targeting niche premium or specialized packaged foods. Focus on urban centers for wellness-oriented products, offering transparency through smart packaging. Develop customized packaged ingredients for specific foodservice segments like healthcare.
For Investors and Strategic Acquirers: Regulatory-driven reformulation is the leading indicator that clean-label and health-oriented product segments will drive long-term value creation. Target agile, mid-cap specialists with established plant-based or free-from product lines. Monitor consumer adoption rates for subscription-based food services as a proxy for shifting retail channel dominance.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand High-Pressure Processing (HPP) Capacity | This preserves nutritional value and sensory qualities for premium clean-label products like cold-pressed juices. |
| Acquire Plant-Based Ingredient Suppliers | Securing consistent supply of certified organic or non-GMO ingredients reduces supply chain friction for manufacturers. |
| Develop Foodservice-Specific Product Lines | Customizing packaged ingredients for institutional catering addresses unique nutritional guidelines and operational needs. |
| Invest in Smart Packaging Technologies | Integrating QR codes provides enhanced product transparency, meeting consumer demand for traceability and allergen information. |
| Optimize E-commerce Logistics for DTC | Efficient direct-to-consumer channels allow brands to bypass traditional retail gatekeepers and build customer relationships. |
Research Approach
US Food and Drug Administration (FDA) guidelines, US Department of Agriculture (USDA) reports, and Federal Trade Commission (FTC) marketing claims formed the secondary backbone for this analysis. Insights were triangulated with primary interviews involving brand managers, R&D directors, foodservice procurement leads, and retail category buyers. This approach integrated both bottom-up market sizing and top-down validation of segment trends.
A bottom-up analytical framework projected market growth across the analysis window, validated by top-down industry trends. Segmentation dimensions modeled included product type, end-user, packaging type, and distribution channel. Compound annual growth rates were derived from historical data and projected shifts in consumer preferences. Input cost volatility and regulatory compliance burdens informed future market trajectory.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant shifts in consumer health trends or agricultural commodity prices. These forecasts reflect current market assumptions. A model refresh is warranted upon material change in FDA labeling regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Canned Beans Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Hummus Market
Packaged Foods
Convenience Food Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Club Store Packs Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
North America Pasta Market
Packaged Foods
Spreads Market