
 Maple Extracts Market | 2026-2036
Maple Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Maple Extracts Market Foresight
Clean-label extraction technology is fragmenting traditional processing methods across the maple extracts supply chain. B&G Foods leverages its retail distribution network to sustain shelf presence in mainstream grocery channels. LB Maple Treat anchors its competitive position through deep vertical integration from Quebec sugar bushes to finished goods. Runamok Maple differentiates via small-batch artisan positioning and direct-to-consumer channel control.
Maple extracts comprise concentrated flavor compounds and sugars derived from Acer saccharum sap through reverse osmosis and thermal evaporation, yielding products with brix levels typically exceeding 66 degrees for syrup formulations. These extracts function as natural sweeteners and flavoring agents across food and beverage manufacturing. Pure Maple Syrup occupies the dominant value share within product type segmentation, while Maple Butter captures premium margin pools in specialty retail. The bakery sector represents the fastest-growing end user segment as commercial producers reformulate away from artificial vanillin. Pouches emerge as the fastest-expanding packaging format within foodservice and single-serve channels.
Health Canada and the Canadian Food Inspection Agency enforce grade standards and maple product identity regulations that shape export eligibility and labeling claims. The FDA maintains standards of identity for maple syrup in the United States, while the USDA administers organic certification pathways that command price premiums. The EU's EFSA evaluates novel food applications for maple-derived ingredients entering European formulations. Stakeholders must monitor evolving clean-label enforcement intensity and organic certification backlogs as determinants of competitive access across priority demand corridors.
Market Dynamics
Clean-label extraction technology is fragmenting traditional processing methods across the maple extracts supply chain, forcing producers to abandon conventional thermal evaporation in favor of precision concentration systems that preserve volatile aromatic compounds while meeting disclosure mandates.
Growth Catalysts
- Natural flavoring mandates:Beverage manufacturers reformulate away from artificial vanillin under FDA and EFSA clean-label guidance, creating pull-through demand for maple-derived alternatives in carbonated and functional drinks.
- Quebec production clustering:Acer saccharum sugar bush concentration in southeastern Canada generates economies of scale in raw sap collection that downstream extract processors leverage for cost-competitive supply.
- Reverse osmosis diffusion:Membrane concentration technology reduces energy intensity in extraction facilities, lowering operational barriers for mid-scale processors entering specialty ingredient supply.
Market Restraints
- Climate-dependent sap yields:Freeze-thaw cycle volatility in Vermont and Quebec sugar bushes creates raw material availability risk that processors cannot hedge through geographic diversification.
- Organic certification backlogs:USDA and Canada Organic Regime accreditation delays extend time-to-market for premium-positioned extract lines, compressing margin capture windows.
- High-fructose corn syrup substitution:Cost-sensitive industrial bakeries in the United States substitute artificial sweeteners for maple extracts in mass-market formulations, capping volume expansion in price-driven segments.
Strategic Opportunities
- Japanese functional food entry:PMDA novel food consultations for maple polyphenol extracts open pathway into Japan's health claim beverage sector, where Acer saccharum-derived antioxidants command premium positioning.
- Pouch format foodservice penetration:Single-serve flexible packaging displaces rigid containers in quick-service restaurant condiment systems, enabling portion-controlled maple butter and syrup extract distribution.
- EU organic import demand:EFSA evaluations of maple-derived ingredients for organic confectionery applications create regulatory tailwind for Canadian and US producers with certified supply chains.
Industry Challenges
- Membrane technician scarcity:Reverse osmosis system operation and maintenance require specialized fluid separation expertise that extraction facilities struggle to recruit in rural Quebec and Vermont production zones.
- Grade standard harmonization:Divergent USDA, Canadian Grade, and EU quality classifications force multi-destination exporters to maintain parallel inventory pools, complicating logistics and working capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maple Extracts Market |
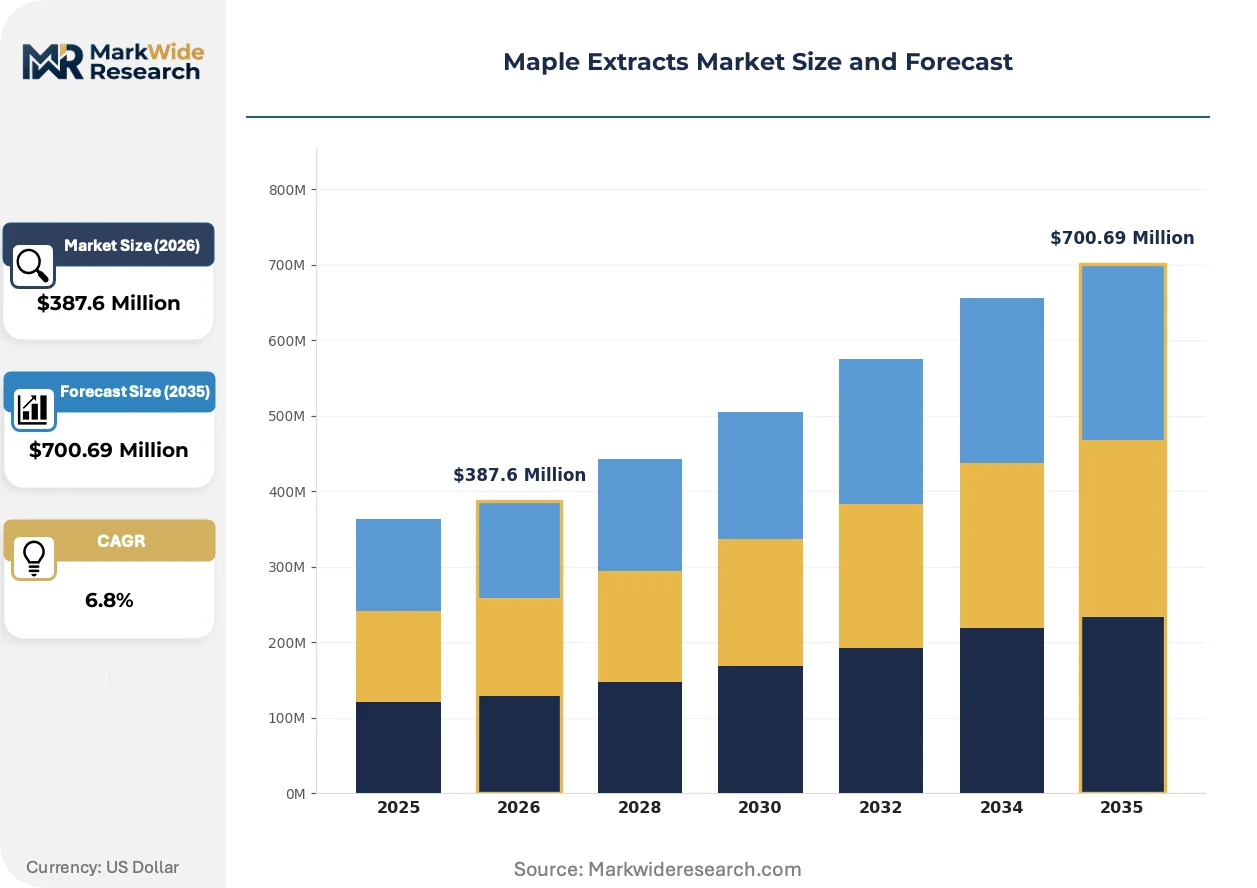
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Maple Syrup, Maple Sugar, Maple Butter, Maple Cream End User: Food Industry, Beverage Producers, Bakery Sector, Retail Consumers Packaging Type: Bottles, Tubs, Pouches, Cans Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Les Industries Bernard et Fils, B&G Foods, LB Maple Treat, Coombs Family Farms, Runamok Maple, Pure Maple, Appalaches Nature, Valeo Foods, dsm-firmenich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maple Extracts Market Shifts & Advancements
Processing technology convergence with clean-label compliance requirements is reconfiguring competitive advantage around extraction precision rather than scale alone, favoring operators who control aromatic compound retention through advanced membrane and thermal hybrid systems.
Membrane filtration is migrating from auxiliary pre-concentration to primary extraction architecture in modern maple processing facilities. Commercial bakeries and beverage compounders now specify brix-stable, flavor-consistent extracts that only hybrid reverse osmosis systems deliver. This technology shift compresses energy costs while enabling year-round production decoupled from seasonal sap flows.
REACH chemical safety registrations for maple-derived flavor precursors are tightening substance documentation requirements for EU-bound shipments. The European Chemicals Agency's expanded dossier demands force Canadian exporters to invest in analytical traceability infrastructure. Small-batch artisan producers face disproportionate compliance burdens relative to vertically integrated Quebec processors with captive laboratories.
Direct-to-consumer channel control is displacing traditional foodservice distribution for premium maple butter and specialty extract lines. Runamok Maple and comparable artisan operators capture margin pools through subscription and specialty retail partnerships that bypass conventional grocery slotting fees. This behavioral shift concentrates in the northeastern United States where regional identity consumption aligns with provenance marketing.
Maple Extracts Market Segmentation
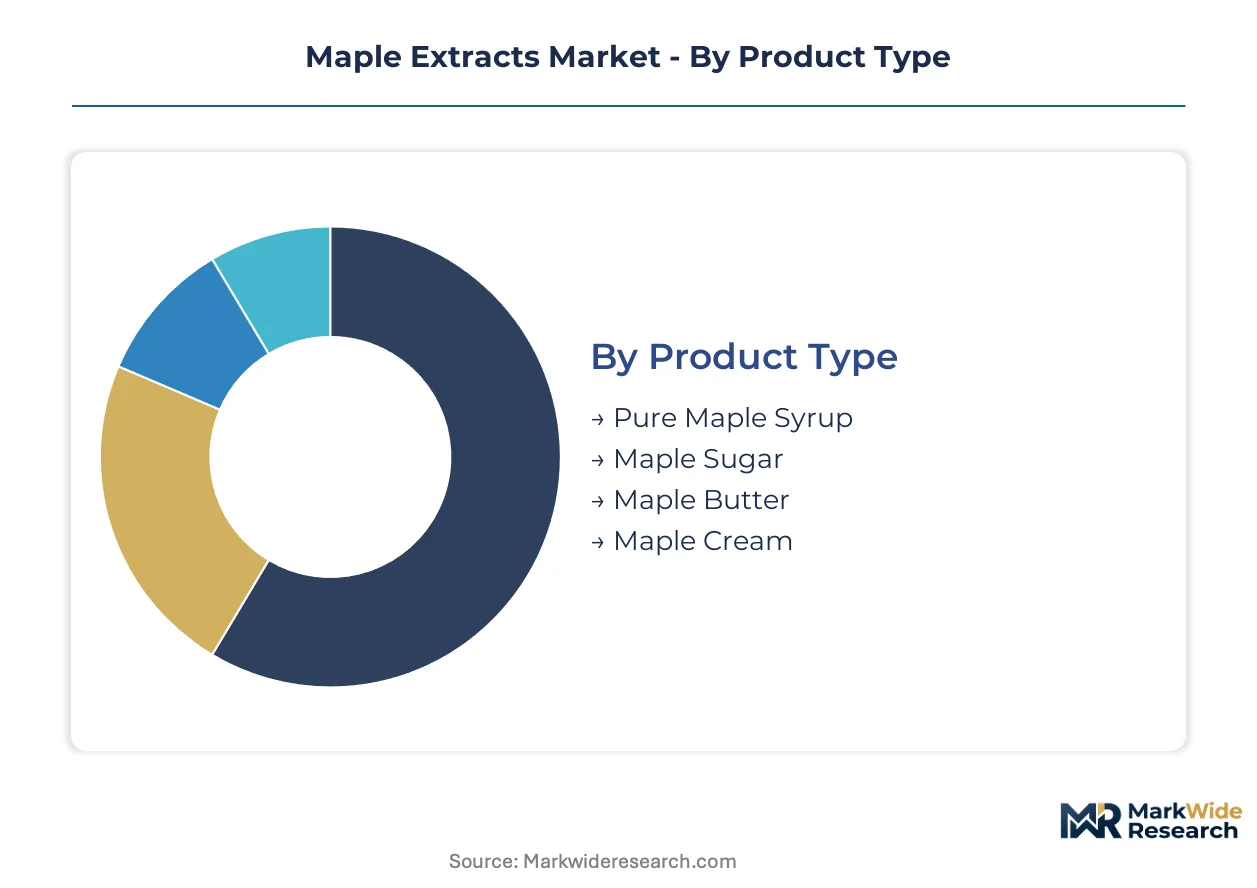
Maple extracts serve divergent functional requirements across industrial formulation and consumer direct use, with each segment demanding distinct brix specifications, stability profiles, and regulatory documentation. Segmentation clarity enables processors to align extraction technology investments with margin structure and channel access requirements.
Product Type:
Product type segmentation spans the full use-case spectrum from bulk industrial sweetening to premium artisan positioning, with each category carrying distinct aromatic compound retention requirements and shelf stability profiles.
- Pure Maple Syrup:Concentrated Acer saccharum sap with brix levels exceeding 66 degrees serves as the foundational industrial sweetener across North American food manufacturing. Commercial bakeries in Vermont and Quebec specify this grade for clean-label reformulation away from artificial vanillin, though climate-dependent sap yields constrain year-round supply security.
- Maple Butter:Aerated crystalline spread with controlled moisture content captures premium margin pools in specialty retail and direct-to-consumer channels. Northeastern United States consumers drive demand through provenance-aligned regional identity consumption, supported by subscription model distribution that bypasses conventional grocery slotting structures.
- Maple Sugar:Dehydrated granular form enables extended shelf stability and precise portion control in industrial confectionery applications.
- Maple Cream:Smooth emulsion format targets artisan bakery finishing and premium foodservice plating applications.
Established volume favors Pure Maple Syrup; emerging adoption favors Maple Butter.
End User:
End user segmentation reflects cost tier stratification, with industrial buyers prioritizing brix consistency and price stability while premium channels absorb certification premiums for organic and single-origin positioning.
- Food Industry:Mass-market manufacturers integrate maple extracts into breakfast cereal, yogurt, and snack bar formulations under FDA clean-label guidance. High-fructose corn syrup substitution pressure caps volume expansion in price-sensitive segments, though natural flavoring mandates sustain baseline demand.
- Beverage Producers:Carbonated and functional drink compounders specify aromatic-stable extracts for flavor systems reformulated away from artificial additives. Japanese health claim beverage sector interest in maple polyphenol antioxidants opens premium positioning pathways for certified supply chains.
- Bakery Sector:Commercial producers represent the steepest expansion trajectory as artificial vanillin phase-out accelerates across North American and European markets.
- Retail Consumers:Direct purchasers concentrate in Quebec and northeastern United States provenance corridors, with channel control shifting toward specialty retail and subscription platforms.
Industrial procurement dominates current volume; beverage reformulation is gaining share fastest.
Packaging Type:
Packaging segmentation tracks supply concentration in foodservice logistics versus retail shelf presence, with format selection determining portion control capability and shipping density economics.
- Pouches:Single-serve flexible format displaces rigid containers in quick-service restaurant condiment systems and foodservice distribution. Portion-controlled maple butter and syrup extract distribution enables waste reduction and inventory precision for commercial kitchen operators.
- Bottles:Traditional glass and PET formats retain dominance in retail grocery and supermarket channels, with Quebec and Vermont producers maintaining parallel inventory pools for divergent USDA and Canadian grade standards.
- Tubs:Wide-mouth containers target foodservice bulk procurement and bakery sector volume purchasing.
- Cans:Metal packaging serves industrial bulk transfer and extended ambient storage requirements for international shipment.
Foodservice logistics favor Pouches; retail shelf presence favors Bottles.
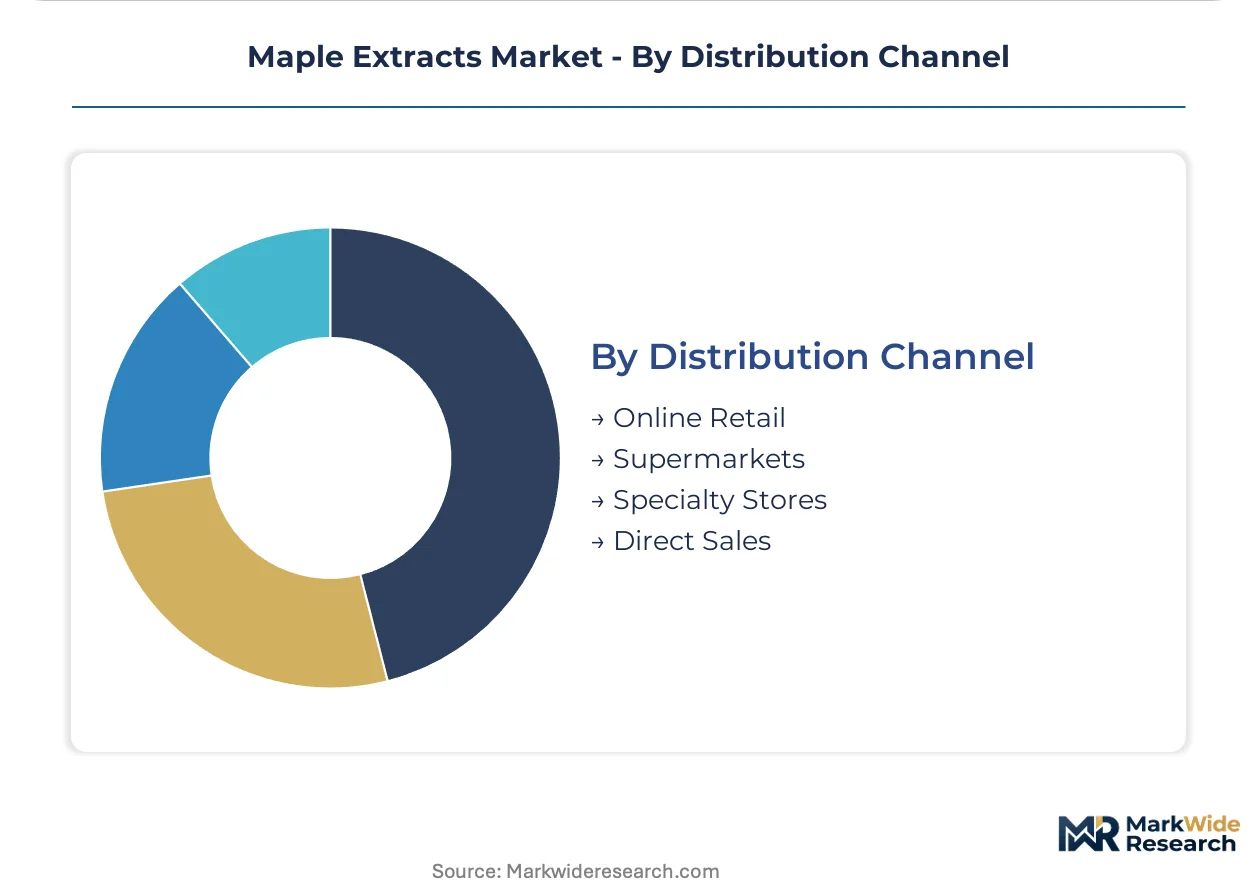
Distribution Channel:
Channel segmentation maps customer type stratification across price-sensitive mass retail, premium specialty positioning, and margin-capturing direct relationships.
- Supermarkets:Mainstream grocery chains in Canada and the northeastern United States provide volume foundation through established slotting fee structures and seasonal promotional programming. B&G Foods and comparable integrated processors leverage retail distribution networks to sustain shelf presence against private label encroachment.
- Direct Sales:Sugar bush-to-consumer relationships enable highest margin capture for Quebec vertical integrators and Vermont artisan operators. LB Maple Treat and comparable producers control provenance narrative and quality documentation through captive collection and processing infrastructure.
- Online Retail:E-commerce platforms concentrate subscription model adoption and gift-oriented purchasing in premium extract and maple butter categories.
- Specialty Stores:Regional gourmet and natural food retailers anchor provenance marketing and organic certification premium realization.
Volume concentration sits with Supermarkets; margin optimization sits with Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate in Canadian outbound shipments to the United States, Japan, and EU markets, with Vermont and Quebec sugar bush clusters supplying the bulk of internationally traded maple-derived ingredients. Trade balances favor Canadian processors who leverage grade standard recognition under bilateral agreements.
Canada
Quebec's southeastern sugar bush concentration generates economies of scale in raw sap collection that downstream extract processors exploit for cost-competitive supply. Health Canada and the Canadian Food Inspection Agency enforce grade standards and maple product identity regulations that shape export eligibility and labeling claims. Montreal and surrounding processing zones host vertically integrated operators controlling provenance narrative from forest to finished goods.
United States
Vermont's freeze-thaw dependent Acer saccharum harvests create raw material availability risk that processors cannot hedge through geographic diversification. The FDA maintains standards of identity for maple syrup while the USDA administers organic certification pathways commanding price premiums. Burlington-area extraction facilities increasingly adopt reverse osmosis membrane systems to reduce energy intensity and enable year-round production decoupled from seasonal sap flows.
Japan
Functional beverage compounders drive import demand for maple polyphenol extracts targeting health claim positioning in antioxidant-enriched drinks. The PMDA evaluates novel food consultations for Acer saccharum-derived ingredients entering Japanese formulations. Tokyo-based importers and health product distributors channel Canadian and US supply into premium retail and foodservice segments.
Germany
Organic confectionery manufacturers source certified maple extracts for clean-label chocolate and bakery applications under EU organic import demand growth. EFSA evaluations of maple-derived ingredients and REACH chemical safety registrations tighten substance documentation requirements for incoming shipments. Hamburg and Rotterdam-adjacent logistics hubs consolidate continental distribution for North American extract suppliers.
United Kingdom
Specialty retail and subscription model platforms absorb premium maple butter and artisan extract lines from direct-to-consumer Quebec and Vermont operators. Divergent Canadian Grade and EU quality classifications force exporters to maintain parallel inventory pools for UK-bound shipments. London and Southeast England gourmet foodservice channels concentrate provenance-marketed product placement.
Maple Extracts Market Competitive Landscape
On the supply side, the industry is structured around vertically integrated Quebec processors, mid-scale US artisan operators, and diversified food conglomerates with maple extract divisions. Strategic archetypes include sugar bush-to-shelf vertical integrators, membrane technology specialists, and retail distribution network leveraged players. Dominant competitive moves span backward integration into raw sap collection infrastructure and direct-to-consumer channel control bypassing conventional grocery slotting structures.
Within the vertically integrated tier, LB Maple Treat exemplifies captive supply chain control from Quebec sugar bushes through finished goods production. Among diversified food conglomerates, B&G Foods occupies a position leveraging established retail distribution networks for mainstream grocery shelf presence. At the artisan-specialist end, Runamok Maple represents small-batch positioning with direct-to-consumer subscription and specialty retail channel focus.
| Leading Market Players |
|---|
| Les Industries Bernard et Fils |
| B&G Foods |
| LB Maple Treat |
| Coombs Family Farms |
| Runamok Maple |
| Pure Maple |
| Appalaches Nature |
| Valeo Foods |
| dsm-firmenich |
| Others |
Supply & Pricing Matrix
Climate-dependent sap yield volatility in Quebec and Vermont sugar bushes determines both pricing tier spreads and supply chain shape across the maple extracts market. Freeze-thaw cycle unpredictability compresses margins for mid-scale processors while concentrating pricing power among vertically integrated operators with captive collection infrastructure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the maple extracts market. Price differentiation centers on organic certification status and brix consistency specifications, with USDA-certified extracts commanding substantial premiums over conventional grades. Pricing pressure stems from high-fructose corn syrup substitution in cost-sensitive bakery applications, eroding margins in mass-market formulations. Foodservice distributors exhibit highest price sensitivity due to volume procurement pressures, while direct-to-consumer channels absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Canadian Food Inspection Agency grade enforcement and FDA standards of identity function as de facto export-control mechanisms limiting cross-border flow flexibility. Geographic supply concentrates in Canada, the United States, and Germany as downstream formulation hubs. Raw material dependencies center on Acer saccharum sap, reverse osmosis membrane systems, and thermal evaporation equipment. Single-source vulnerability pervades the Quebec sugar bush cluster where freeze-thaw volatility creates unhedgeable availability risk. Distribution runs through vertically integrated processors controlling provenance documentation from forest to finished goods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation mandates across North American and European food manufacturing fragment demand into specialty niches, creating structural entry points for differentiated positioning.
For Market Incumbents: Pre-empt membrane technology commoditization by securing exclusive supplier relationships with Quebec sugar bush collectives and investing in hybrid reverse osmosis-thermal systems that preserve volatile aromatic compounds. High-fructose corn syrup substitution in industrial bakeries threatens volume-based revenue streams, necessitating backward integration into organic-certified sap collection to defend premium tier positioning. For New Entrants and Emerging Players: Japanese functional beverage manufacturers seeking maple polyphenol extracts for antioxidant health claims represent the most penetrable entry point for certified supply chains lacking PMDA novel food consultation experience. Mid-scale processors in Vermont with membrane filtration capabilities can capture margin pools through toll extraction arrangements for artisan brands lacking in-house concentration infrastructure. Go-to-market execution should prioritize direct-to-consumer subscription platforms that bypass conventional grocery slotting fee structures. For Investors and Strategic Acquirers: EFSA evaluations of maple-derived ingredients for organic confectionery applications reshape the acquisition landscape toward Canadian operators with certified supply chains and analytical traceability infrastructure. Five-to-ten year viability favors vertically integrated processors controlling sugar bush-to-shelf documentation rather than toll-dependent mid-scale operators. The signal to watch is organic certification backlog resolution at USDA and Canada Organic Regime, which would unlock premium tier capacity expansion and compress acquisition multiples for compliant targets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugar Bush Collection | Captive supply of Acer saccharum sap insulates processors from climate-driven yield volatility. |
| Membrane Technology Capacity Expansion | Reverse osmosis adoption reduces energy intensity and enables year-round production decoupled from seasonal flows. |
| Organic Certification Investment | USDA and Canada Organic Regime accreditation unlocks premium pricing in EU and Japanese import markets. |
| Direct-to-Consumer Channel Development | Subscription platforms bypass grocery slotting fees and capture margin pools in maple butter and specialty extracts. |
| PMDA Novel Food Consultation | Japanese regulatory clearance opens functional beverage positioning for maple polyphenol antioxidant extracts. |
Research Methodology
Operator-level perspectives from extraction facility managers, sugar bush cooperative directors, beverage formulation chemists, and organic certification auditors anchored the qualitative base for this study. Primary interviews combined with secondary validation from Health Canada grade standard documentation, FDA standards of identity filings, USDA organic certification databases, and EFSA novel food evaluation records. Bottom-up volume modeling across product type, end user, and packaging format segments triangulated against top-down trade flow analysis from Canadian and US customs data.
Scenario-bracketing around climate yield volatility, clean-label enforcement intensity, and organic certification throughput informed projection boundaries across the analysis window. Segmentation dimensions modeled include product type tier, end-use industry, packaging format, and regional regulatory cluster. CAGRs derived from slope analysis of historical volume trajectories adjusted for technology diffusion rates in membrane filtration adoption and reformulation cycle timing in target end-use sectors.
Practitioners should monitor freeze-thaw cycle patterns in Vermont and Quebec, EFSA evaluation timelines for maple-derived ingredients, and PMDA consultation backlog resolution for early signals of forecast revision triggers. Material shifts in climate-driven sap availability, regulatory enforcement intensity, or certification system capacity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
Modified Lecithin Market
Flavorings and Food Additives
Africa Food Flavor Market
Flavorings and Food Additives
Global Vanilla (B2B) Market
Flavorings and Food Additives
Chokeberry Extract Market
Flavorings and Food Additives
Africa Food Colorants Market
Flavorings and Food Additives
Water Flavoring Drop Market
Flavorings and Food Additives
Smoked Dextrose Market
Flavorings and Food Additives
Carotenoids Pigment Market
Flavorings and Food Additives
D-Limonene Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Licorice Extract Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Smoked Condensates Market