
 Asparagus Extract Market | 2026-2036
Asparagus Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Asparagus Extract Market Outlook
Peruvian asparagus processing cooperatives is consolidating dried-rhizome supply for extract manufacturers in Asia-Pacific and Europe. Xi'an Tianrui Biotech Co., Ltd leverages its Shaanxi province extraction facility to supply pharmaceutical-grade powder to European dietary supplement brands. Maypro Industries, Inc. anchors North American distribution through its branded ingredient portfolio, while SV Agrofood competes on agronomic traceability from its Indian cultivation partnerships.
Asparagus extract comprises concentrated bioactive compounds derived from Asparagus officinalis, typically standardized to saponin content between 5% and 20% by HPLC assay for reproducible therapeutic dosing. Manufacturers employ ethanol-water maceration followed by spray-drying to preserve heat-labile steroidal saponins for pharmaceutical and nutraceutical applications. Powder formats lead volume shipments due to bulk handling efficiency in contract manufacturing, while capsule segments capture higher margin pools through finished-dose branding. Functional foods represent the fastest-growing application as beverage formulators incorporate water-soluble extracts into ready-to-drink wellness products.
EMA quality guidelines for herbal medicinal products govern European import specifications, while FDA dietary supplement cGMPs enforce identity testing and contaminant thresholds for US-bound shipments. China's NMPA and GB standards regulate domestic extract purity and pesticide residue limits, shaping export competitiveness of Shaanxi and Shandong production clusters. Stakeholders must monitor evolving pharmacopeial monograph revisions and adapt extraction protocols to maintain multi-jurisdictional compliance without redundant qualification runs.
Market Dynamics
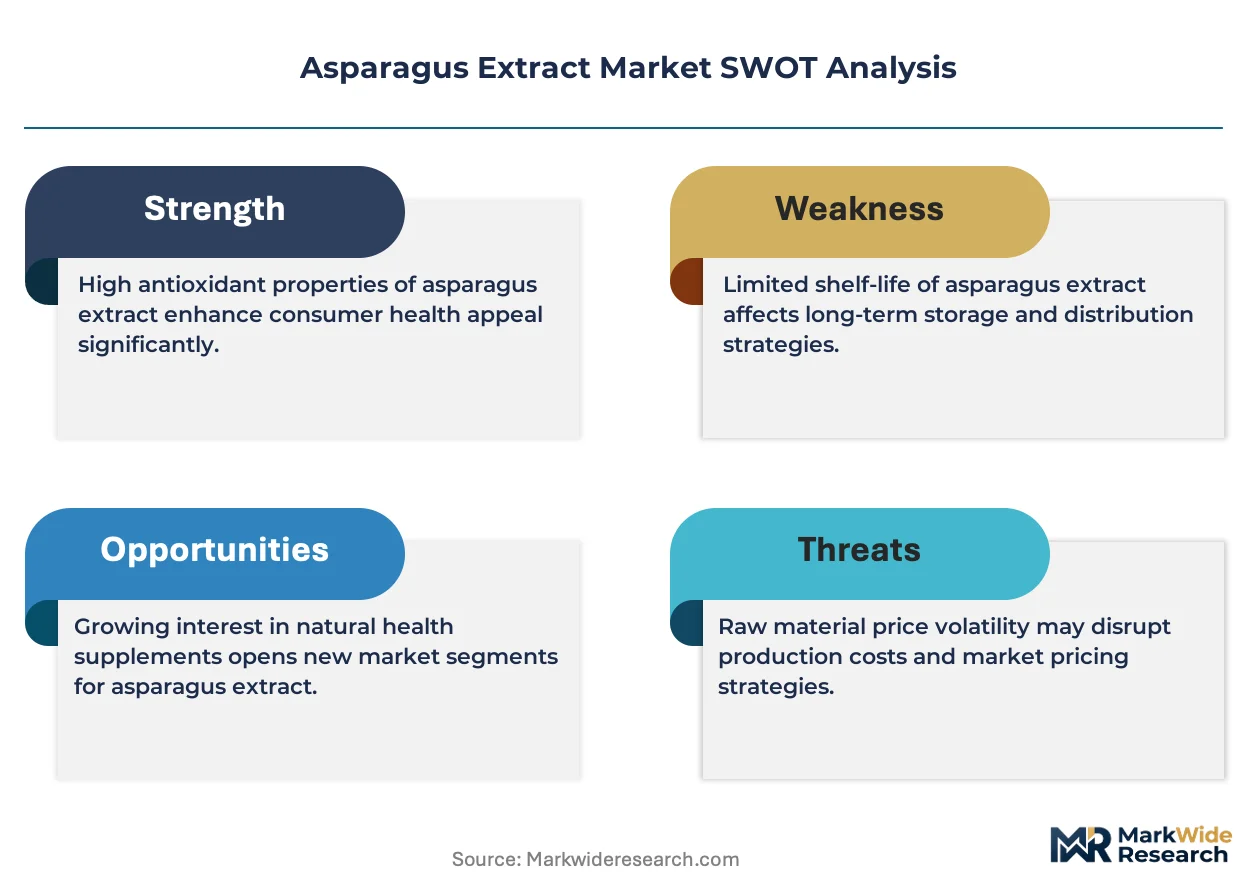
Pharmaceutical standardization requirements are compressing supplier margins while concentrating procurement among extractors capable of EMA-compliant HPLC assay documentation and batch-to-batch saponin consistency.
Growth Catalysts
- EMA Botanical Drug Guidelines:European pharmaceutical formulators now mandate standardized asparagus extract for diuretic preparations, creating qualified demand pools that reward GMP-certified suppliers.
- Functional Beverage Formulation:Ready-to-drink wellness brands in Germany and France incorporate water-soluble extracts, expanding volume absorption beyond traditional capsule applications.
- Peruvian Dried-Rhizome Consolidation:Processing cooperatives in Ica and La Libertad are aggregating raw material supply, reducing lot-to-lot variability for Asian and European extract manufacturers.
Market Restraints
- Input Cost Volatility:Asparagus rhizome prices fluctuate with Peruvian harvest cycles and Chinese cultivation shifts, squeezing extractor margins during low-yield seasons.
- Supply Concentration Risk:Shaanxi and Shandong provinces dominate pharmaceutical-grade extraction capacity, creating geographic vulnerability to regional environmental compliance actions.
- Substitution Threat:Synthetic diuretics and lower-cost botanical alternatives like dandelion extract compete for pharmaceutical and nutraceutical formulator budgets.
Strategic Opportunities
- Underpenetrated US Functional Foods:American beverage brands remain below European adoption rates for asparagus extract fortification, offering first-mover positioning for compliant suppliers.
- CSRD-Driven Traceability:European corporate sustainability reporting mandates reward extractors with certified agronomic partnerships and carbon-accounted supply chains.
- Supercritical CO2 Convergence:Combination of supercritical fluid extraction with spray-drying preserves heat-labile steroidal saponins at yields exceeding traditional ethanol maceration.
Industry Challenges
- Analytical Chemist Scarcity:Extract manufacturers struggle to hire HPLC specialists capable of EMA-compliant saponin quantification and pharmacopeial monograph alignment.
- Multi-Jurisdictional Qualification Runs:Simultaneous compliance with EMA, FDA cGMP, and NMPA GB standards requires redundant testing protocols that extend batch release timelines.
- Legacy Spray-Drying Asset Obsolescence:Capital replacement cycles for heat-sensitive processing equipment strain mid-tier extractors facing pharmaceutical-grade upgrade requirements.
Report Scope
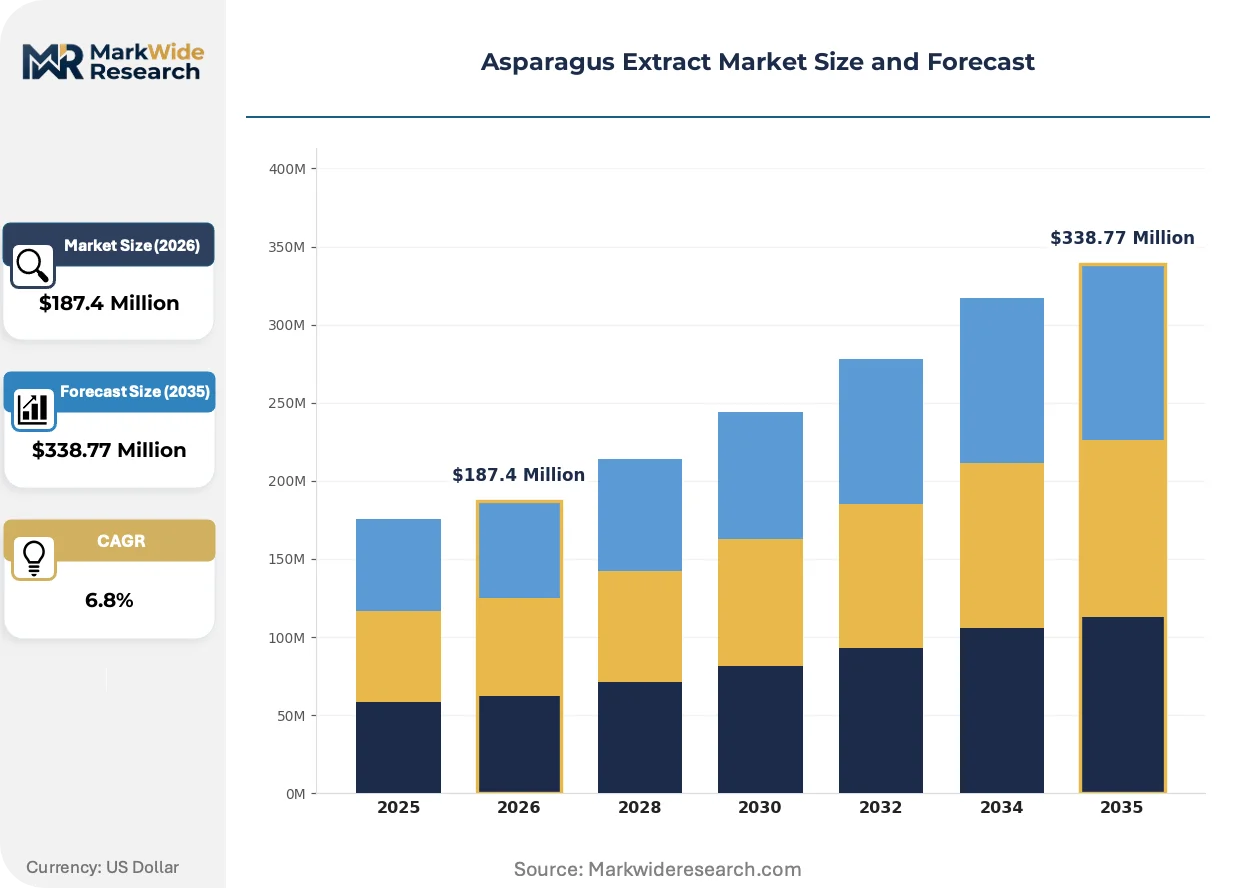
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asparagus Extract Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Capsule, Liquid, Extract Application: Dietary Supplements, Cosmetics, Pharmaceuticals, Functional Foods Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Supermarkets End User: Health Enthusiasts, Athletes, Patients, General Consumers |
| Companies Covered | Chi's Enterprise, Inc., SA Herbal Bioactives LLP, SV Agrofood, Herbo Nutra, Sava Healthcare Limited, Xi'an Tianrui Biotech Co., Ltd, Maypro Industries, Inc., Shreedha Phyto Extracts, Navchetana Kendra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asparagus Extract Market Strategic Shifts
Extraction technology and regulatory traceability requirements are restructuring competitive advantage around verified bioactive standardization rather than raw material scale alone.
Supercritical CO2 extraction systems are rewriting the economics of heat-sensitive botanical processing. German and Swiss pharmaceutical contract manufacturers have adopted these units at accelerating replacement cycles. The technology is compressing traditional ethanol maceration margins while enabling patentable process claims for premium positioning.
REACH and EMA quality guideline revisions are tightening pesticide residue thresholds for herbal medicinal products. European importers now reject shipments exceeding updated maximum residue limits for organophosphates and pyrethroids. Chinese exporters from Shaanxi province are responding with certified organic cultivation partnerships and third-party testing documentation.
Direct-to-manufacturer procurement is displacing traditional ingredient distributor intermediaries in North American nutraceutical sourcing. Large contract manufacturers in California and New Jersey now contract directly with Xi'an and Shandong extraction facilities, compressing channel margins. This pattern is most visible among brands pursuing FDA cGMP certification and lot-level traceability for litigation protection.
Asparagus Extract Market Segmentation
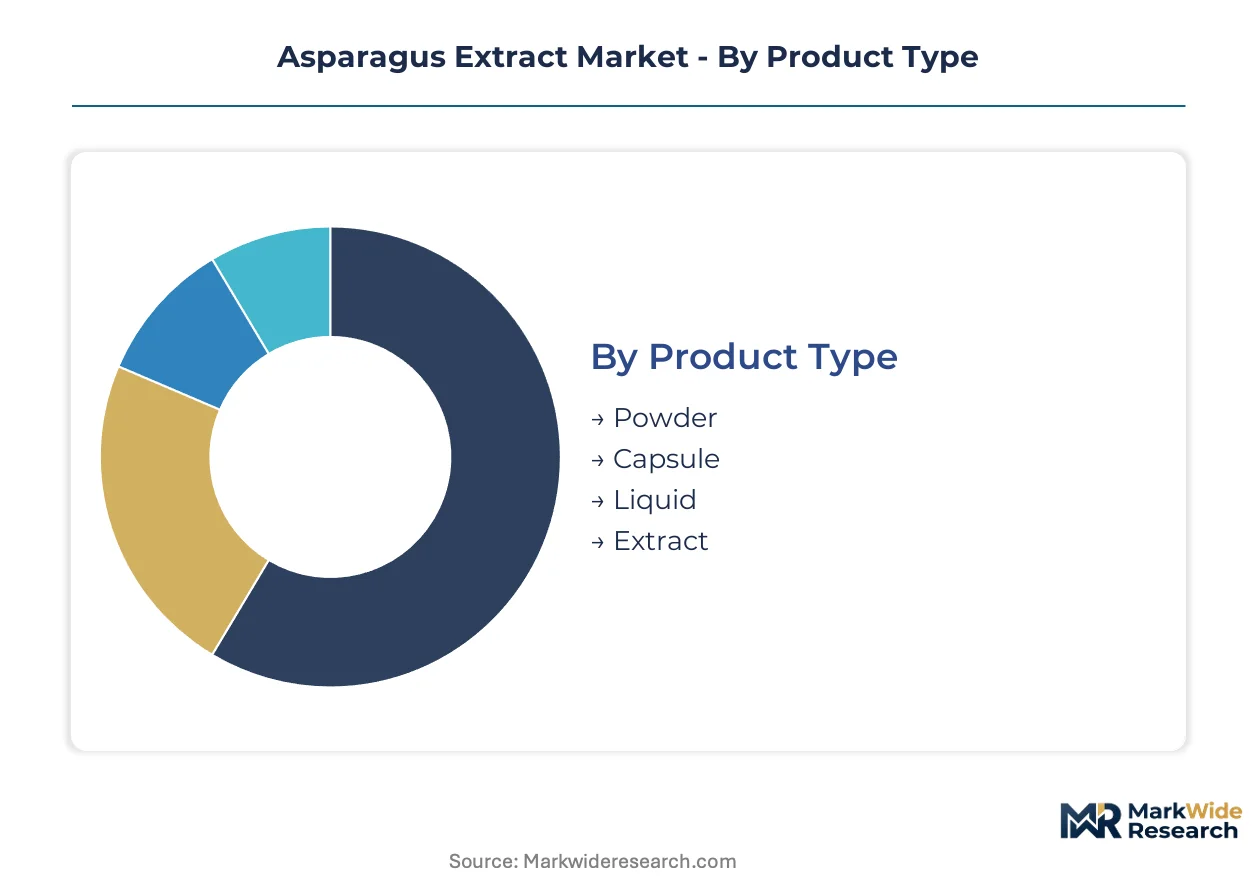
Segmentation in the asparagus extract market reveals distinct certification burdens and margin structures across product formats and end-use channels. Pharmaceutical-grade powder commands EMA-compliant HPLC documentation, while functional food applications face divergent FDA and NMPA purity thresholds.
Product Type:
Powder formats carry the heaviest certification load, requiring EMA botanical drug guidelines compliance for European pharmaceutical procurement and FDA cGMP identity testing for US dietary supplement shipments. Capsule and liquid segments face tiered documentation demands based on finished-dose versus bulk ingredient classification.
- Powder:Spray-dried concentrates standardized to 5-20% saponin content by HPLC assay dominate contract manufacturing procurement. German pharmaceutical formulators source this grade under EMA quality guidelines for diuretic preparations, with Shaanxi province extraction facilities supplying validated batches. The format absorbs volume leadership through bulk handling efficiency in European nutraceutical production.
- Capsule:Finished-dose formats capture premium margin pools through branded positioning and direct-to-consumer channels. California and New Jersey contract manufacturers now bypass traditional distributors to source directly from Xi'an extraction facilities, compressing intermediary margins while enforcing lot-level traceability.
- Liquid:Water-soluble extracts serve ready-to-drink wellness formulations in Germany and France.
- Extract:Concentrated bioactive preparations require ethanol-water maceration protocols with documented steroidal saponin preservation.
Powder sits at the top of the volume ranking, with liquid climbing the fastest as beverage formulators expand fortification programs.
Application:
Cost tier differentiation separates pharmaceutical-grade standardization from commodity nutraceutical sourcing, with functional foods commanding mid-tier pricing for water-soluble extract integration.
- Dietary Supplements:Capsule and tablet applications source bulk powder through direct procurement relationships with Shandong and Shaanxi extraction clusters. The segment concentrates demand among GMP-certified contract manufacturers seeking EMA-compliant documentation for European export.
- Pharmaceuticals:Diuretic and anti-inflammatory preparations require batch-to-batch saponin consistency under EMA botanical drug guidelines. German formulators enforce HPLC assay documentation, compressing supplier margins while rewarding qualified extractors with concentrated procurement volumes.
- Cosmetics:Topical applications utilize lower-concentration extracts for anti-inflammatory positioning in dermal formulations.
- Functional Foods:Beverage fortification in ready-to-drink wellness products expands absorption beyond traditional delivery formats, with German and French brands leading formulation adoption.
Dietary supplements hold volume dominance, while functional foods gain share fastest on beverage innovation pipelines.
Distribution Channel:
Customer type concentration varies sharply by channel, with pharmacies serving patient populations under medical guidance and online retail capturing health enthusiast self-directed purchasing.
- Online Retail:Direct-to-consumer platforms aggregate health enthusiast and athlete demand for branded capsule and powder SKUs. California-based contract manufacturers leverage this channel for litigation-protected lot traceability, displacing traditional distributor intermediaries through direct Xi'an sourcing relationships.
- Pharmacies:Patient-directed procurement of pharmaceutical-grade extracts requires prescription or pharmacist consultation in European markets. EMA quality guideline compliance governs shelf placement, with German and French pharmacy chains enforcing updated pesticide residue thresholds.
- Specialty Stores:Premium positioning targets athlete and health enthusiast segments with certified organic and third-party tested offerings.
- Supermarkets:Mass-market functional food placement drives volume absorption for beverage-fortified extract applications.
Online retail leads volume throughput, with supermarkets expanding most quickly on functional beverage shelf placement.
End User:
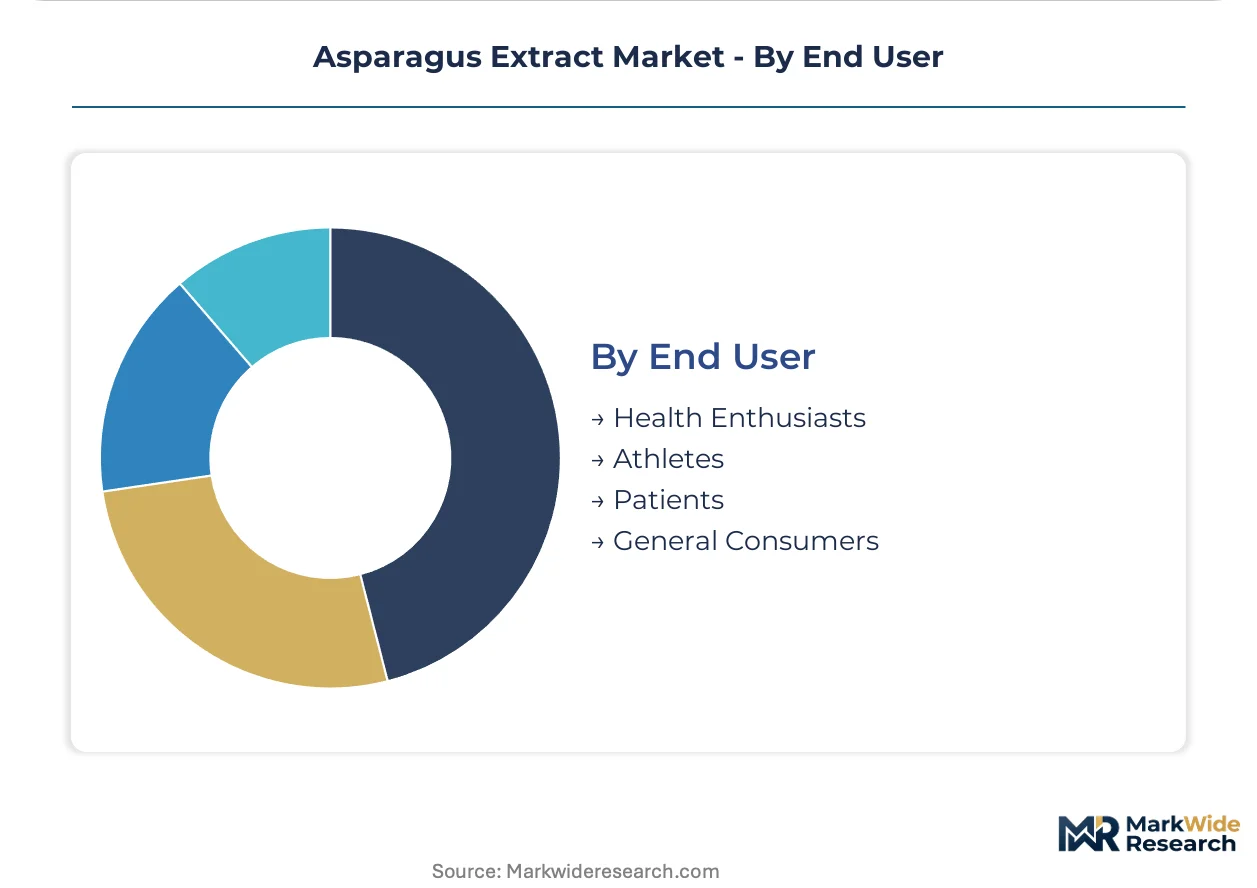
Supply concentration clusters around health enthusiast and athlete demand in North American and European markets, with patient populations requiring pharmaceutical-grade standardization.
- Health Enthusiasts:Self-directed wellness consumers drive capsule and powder demand through online retail and specialty store channels. This segment absorbs the majority of branded ingredient procurement from Maypro Industries' North American distribution portfolio.
- Patients:Medical-guided consumption of diuretic preparations requires EMA-compliant documentation and pharmacist consultation. German pharmaceutical formulators serve this population through standardized extract prescriptions under national healthcare reimbursement frameworks.
- Athletes:Performance-oriented consumers seek anti-inflammatory and recovery positioning in supplement formulations.
- General Consumers:Mass-market functional food adoption expands through ready-to-drink beverage fortification in supermarket channels.
Health enthusiasts command volume leadership, with general consumers climbing fastest on functional beverage mainstreaming.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redrawing production maps as extraction capacity migrates toward jurisdictions with lower compliance costs but sufficient technical capability to meet EMA and FDA documentation standards. Chinese facilities in Shaanxi province now capture pharmaceutical-grade contracts that German formulators once awarded domestically.
Germany
Pharmaceutical formulators in Baden-Württemberg and Bavaria drive standardized extract procurement for diuretic preparations under EMA botanical drug guidelines. The country's national pharmaceutical regulator enforces HPLC assay documentation and batch-to-batch saponin consistency for herbal medicinal products. Stuttgart-based contract manufacturers now source directly from Xi'an extraction facilities, compressing traditional distributor margins while maintaining EMA-compliant traceability.
China
Shaanxi province extraction clusters supply pharmaceutical-grade powder to European dietary supplement brands and North American contract manufacturers. NMPA GB standards regulate domestic extract purity and pesticide residue limits, shaping export competitiveness against REACH and EMA quality thresholds. Xi'an Tianrui Biotech leverages its provincial facility to serve German and French formulators with validated spray-dried concentrates.
United States
California and New Jersey contract manufacturers anchor North American demand for capsule and powder formats serving health enthusiast and athlete segments. FDA dietary supplement cGMPs enforce identity testing and contaminant thresholds for lot-level traceability and litigation protection. Direct procurement from Shandong and Shaanxi extraction facilities is displacing traditional ingredient distributor intermediaries.
Peru
Processing cooperatives in Ica and La Libertad provinces consolidate dried-rhizome supply for Asian and European extract manufacturers. The country's agricultural export regulator monitors pesticide residue compliance for shipments bound for REACH and EMA markets. Coastal cultivation clusters are aggregating raw material supply to reduce lot-to-lot variability for pharmaceutical-grade extraction protocols.
India
Maharashtra and Gujarat cultivation partnerships supply agronomic traceability for extractors competing on certified organic positioning. FSSAI standards govern domestic nutraceutical purity requirements while export shipments face FDA and EMA documentation burdens. SV Agrofood and SA Herbal Bioactives leverage Indian cultivation networks to serve European corporate sustainability reporting mandates.
Asparagus Extract Market Competitive Environment
Chinese producers anchor the volume tier through Shaanxi and Shandong extraction clusters; Indian and North American specialists hold differentiated positions on agronomic traceability and branded ingredient portfolios. Market structure concentrates procurement among GMP-certified extractors capable of multi-jurisdictional compliance documentation. Three archetypes dominate: scale-driven Chinese bulk suppliers, traceability-focused Indian cultivation-integrated players, and North American brand-positioning specialists. Competitive moves center on direct-to-manufacturer procurement relationships and supercritical CO2 extraction technology licensing.
Among China-based extraction specialists, Xi'an Tianrui Biotech Co., Ltd occupies a position exemplifying the pharmaceutical-grade powder archetype serving European formulators. Maypro Industries, Inc. represents the North American branded ingredient distribution model anchoring supply to California and New Jersey contract manufacturers. SV Agrofood sits within the Indian cultivation-integrated tier competing on certified agronomic partnerships and carbon-accounted supply chains for CSRD-compliant European procurement.
| Leading Market Players |
|---|
| Chi's Enterprise, Inc. |
| SA Herbal Bioactives LLP |
| SV Agrofood |
| Herbo Nutra |
| Sava Healthcare Limited |
| Xi'an Tianrui Biotech Co., Ltd |
| Maypro Industries, Inc. |
| Shreedha Phyto Extracts |
| Navchetana Kendra |
| Others |
Value Chain & Pricing Dynamics
REACH and EMA quality guideline revisions gate qualified supply and premium-tier pricing access for asparagus extract, compressing margins for non-compliant suppliers while rewarding certified extractors with concentrated procurement from German pharmaceutical formulators. Compliance documentation costs now separate viable suppliers from commodity players across European and North American markets.
Pricing Analysis
Distributor margin compression is accelerating as California and New Jersey contract manufacturers bypass traditional intermediaries to source directly from Xi'an and Shandong extraction facilities. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-grade, and commodity powder levels reflects EMA-compliant HPLC documentation, FDA cGMP certification, and basic identity testing respectively. Price differentiation hinges on saponin standardization precision and lot-level traceability documentation. Cost compression in mid-tier nutraceutical grades is intensifying because Shaanxi province competitors expand pharmaceutical-grade capacity. Health enthusiast segments through online retail channels exhibit highest price sensitivity, while German pharmaceutical formulators under national healthcare reimbursement frameworks show lowest sensitivity to premium-tier pricing.
Supply Chain Analysis
Single-source vulnerability sits with Shaanxi and Shandong provinces, where pharmaceutical-grade extraction capacity concentrates for EMA-compliant powder production. Raw material supply draws from Peruvian dried-rhizome processing cooperatives in Ica and La Libertad, Indian cultivation partnerships in Maharashtra and Gujarat, and Chinese domestic asparagus farming. Supply chain risk centers on geographic concentration to regional environmental compliance actions by China's MEE. Distribution runs through direct-to-manufacturer procurement relationships displacing traditional ingredient distributor intermediaries, with German and North American contract manufacturers establishing validated supplier partnerships for lot-level traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage economics favor extraction capacity migration to Shaanxi province facilities, where NMPA GB standards compliance costs run below EMA documentation burdens while maintaining sufficient technical capability for European pharmaceutical procurement.
For Market Incumbents: Hedge against synthetic diuretic substitution threats by deepening backward integration into Peruvian dried-rhizome supply through processing cooperative partnerships. Prioritize supercritical CO2 extraction technology licensing to preserve heat-labile steroidal saponin yields exceeding traditional ethanol maceration competitors. Capacity addition in certified organic cultivation clusters strengthens margin defense against REACH pesticide residue threshold tightening. For New Entrants and Emerging Players: Begin with underpenetrated US functional beverage fortification, where American brands remain below European adoption rates for asparagus extract integration. Target direct procurement relationships with California contract manufacturers seeking FDA cGMP-compliant lot traceability for litigation protection. Lead with water-soluble extract formats enabling ready-to-drink wellness product formulation. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier extraction specialists with validated EMA documentation capabilities because pharmaceutical standardization requirements are compressing supplier margins and concentrating procurement among qualified players. Long-term viability frames around CSRD-driven traceability mandates rewarding carbon-accounted supply chains. Watch for supercritical CO2 extraction technology adoption rates as inflection indicator for premium-tier positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Licensing | German pharmaceutical contract manufacturers adopt these units to preserve heat-labile steroidal saponins at superior yields. |
| Direct-to-Manufacturer Procurement | North American contract manufacturers bypass distributors to source validated batches from Xi'an extraction facilities. |
| Certified Organic Cultivation Partnerships | Peruvian and Indian cooperatives aggregate supply to meet REACH pesticide residue thresholds for EMA markets. |
| EMA-Compliant HPLC Documentation Investment | Shaanxi province extractors capture pharmaceutical-grade contracts through batch-to-batch saponin consistency validation. |
| Functional Beverage Format Development | German and French brands incorporate water-soluble extracts into ready-to-drink wellness product pipelines. |
Study Parameters
Direct dialogue with extraction facility technical directors, pharmaceutical formulation scientists, nutraceutical contract manufacturing procurement leads, and EMA regulatory affairs consultants grounded the qualitative foundation of this study. Secondary validation drew from FDA cGMP inspection databases, EMA quality guideline revision documents, NMPA GB standard filings, and Peruvian agricultural export regulator compliance records. Bottom-up triangulation across supplier capacity assessments and top-down demand modeling from end-use consumption patterns ensured analytical consistency.
Segmented outputs across powder, capsule, liquid, and extract product types combined with application splits in dietary supplements, pharmaceuticals, cosmetics, and functional foods structured the analytical framework over the projection horizon. Pharmaceutical-grade, nutraceutical-grade, and commodity-tier pricing bands anchored value calculations, while saponin standardization precision and certification documentation requirements shaped volume-to-value conversion logic. CAGRs derived from fitted growth curves applied to validated baseline consumption estimates.
Several conditions sit outside the modeled scope, including potential EMA botanical drug guideline revisions, abrupt Peruvian harvest cycle disruptions, and synthetic diuretic formulation breakthroughs. Forecasts reflect documented assumptions about regulatory stability and raw material supply continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
China Beer Adjuncts Market
Ingredients
Kilned Malt Market
Ingredients
Low Calorie Cooking Oil Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
Passion Fruit Powder Market
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Fruit Concentrate Market
Ingredients
Lupin Flour Market
Ingredients
Europe Vegetable Oil Market
Ingredients
United States Wheat Protein Market
Ingredients
Ground-Nut Oil Market
Ingredients
Spain Sodium Reduction Ingredient Market
Ingredients
Xylooligosaccharide Market
Ingredients
Gelatin Substitutes Market
Ingredients
North America Malt Ingredients Market
Ingredients
South America Insoluble Dietary Fibers Market