
 South America Breakfast Cereals Market | 2026-2036
South America Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
South America Breakfast Cereals Market Analytics
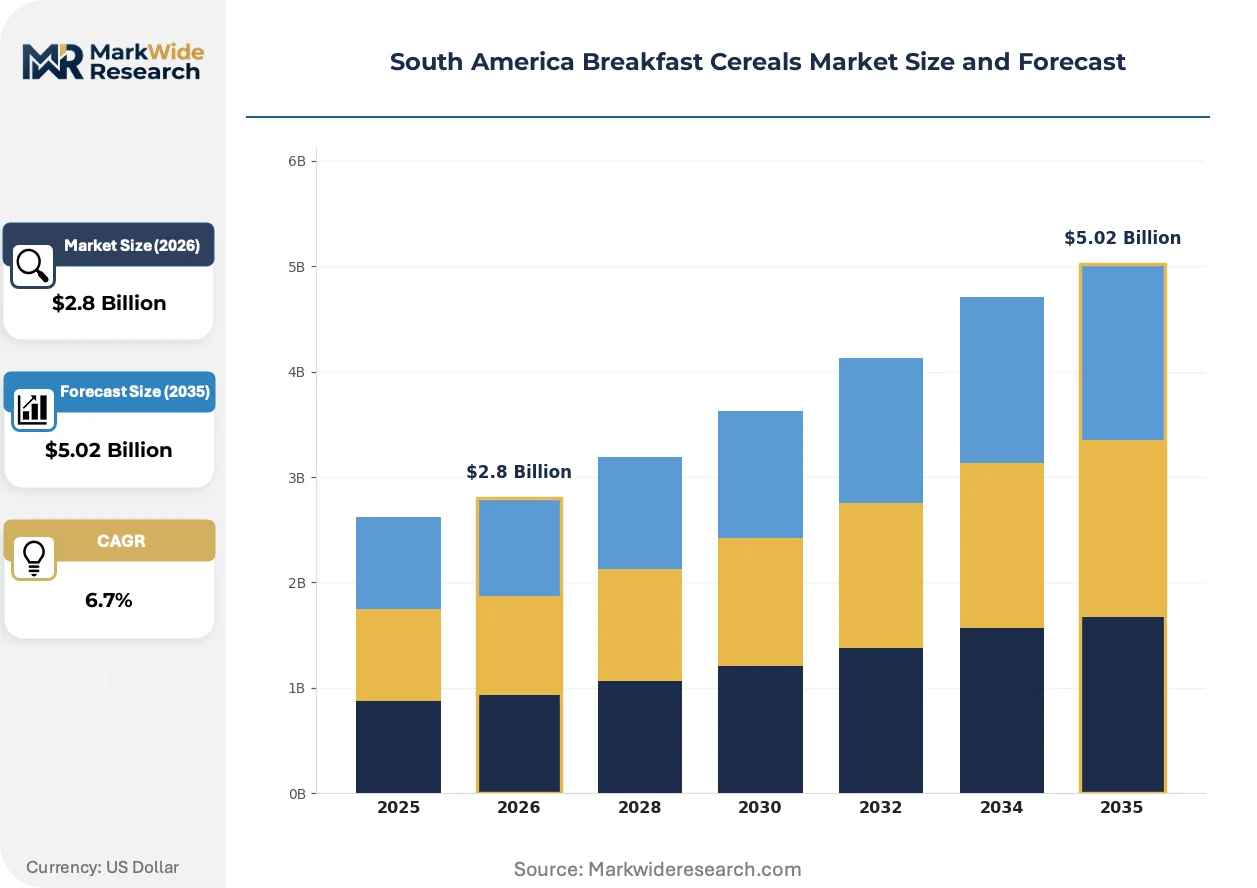
Project finance for automated extrusion and packaging lines is rewriting competitive access across the South America Breakfast Cereals Market, allowing mid-scale entrants to lease capital-intensive equipment rather than purchase outright. Kellogg's leverages its regional manufacturing footprint to sustain supply chain density across Andean corridors. Grupo Nutresa anchors its position through deep backward integration into tropical fruit and grain sourcing. PepsiCo (Quaker Oats) competes on hot cereal portfolios that resonate with traditional morning consumption patterns in Colombia and Peru.
Breakfast cereals comprise processed grain formulations—typically corn, wheat, rice, or oat-based—manufactured through extrusion cooking, flaking, or puffing to achieve specific bulk density and rehydration parameters, serving as convenient, shelf-stable morning nutrition solutions for retail and foodservice channels. Cold cereals dominate volume throughput in supermarkets, where margin pools concentrate in branded, fortification-enhanced offerings targeting children and working adults. Hot cereals and granola segments capture premium positioning through health-positioned formulations, with muesli gaining traction in specialty shops and online retail channels across southern cone markets. Distribution through convenience stores and hotels, restaurants, and cafes channels reflects urbanization-driven consumption fragmentation.
ANVISA fortification mandates and Argentina's national food code shape product composition requirements, compelling reformulation of micronutrient profiles and labeling disclosures across Brazilian and Argentine production facilities. Colombia's INVIMA and Peru's DIGEMID enforce parallel standards on imported cereal shipments, creating compliance layers for cross-border trade within the Andean Community. Chile's front-of-pack warning label law pressures sodium and sugar thresholds, redirecting R&D investment toward clean-label and whole-grain platforms. Stakeholders must monitor evolving Mercosur technical regulations and track divergence between national fortification regimes to optimize regional SKU strategies.
Market Dynamics
ANVISA fortification mandates are compressing formulation timelines across Brazilian production facilities, forcing simultaneous compliance with micronutrient thresholds and front-of-pack disclosure requirements.
Growth Catalysts
- Urbanization in the São Paulo-Rio corridor:Metropolitan household density accelerates ready-to-eat morning consumption patterns. Convenience stores expand cereal shelf space to capture commuter traffic.
- ANVISA fortification standards:Mandatory iron and folic acid inclusion in packaged grains creates differentiated positioning for compliant domestic producers. Reformulation investments now function as competitive moats.
- Extrusion technology leasing:Capital-light equipment access allows mid-scale processors to enter branded cereal production without balance-sheet strain.
Market Restraints
- Tropical grain input volatility:Corn and rice price swings in Mato Grosso and Paraná squeeze margin predictability for extrusion-dependent producers.
- Supply concentration in southeastern Brazil:Three-quarters of national milling capacity clusters within 300 kilometers of São Paulo, creating single-point vulnerability for northern distribution.
- Chile's front-of-pack warning law:Sugar and sodium thresholds block conventional formulations from shelf placement, requiring complete recipe redevelopment for cross-Andean trade.
Strategic Opportunities
- Peru's northern coastal cities:Underdeveloped modern trade penetration in Trujillo and Chiclayo offers first-mover positioning for fortified hot cereal portfolios.
- E-commerce direct-to-consumer channels:Subscription-based granola and muesli deliveries bypass traditional retail slotting fees while capturing health-conscious households.
- Clean-label convergence:Whole-grain positioning aligned with Chile's warning-label compliance creates export-ready SKU architecture for Mercosur expansion.
Industry Challenges
- Extrusion technician scarcity:Specialized operators capable of calibrating twin-screw systems for precise bulk density targets command premium wages that smaller facilities cannot match.
- Multi-jurisdiction label harmonization:Simultaneous compliance with ANVISA, INVIMA, and DIGEMID disclosure formats fragments packaging runs and extends new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Breakfast Cereals Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Cereals, Granola, Muesli, Cold Cereals Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Shops End User: Households, Hotels, Restaurants, Cafes Packaging Type: Boxes, Bags, Pouches, Tubs |
| Companies Covered | Kellogg's, Nestlé, General Mills, PepsiCo (Quaker Oats), Bimbo, Unilever, Grupo Nutresa, Marico, Arcor, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Breakfast Cereals Market Evolving Landscape
Reformulation pressure from warning-label jurisdictions is accelerating ingredient substitution across the South American breakfast cereals landscape, compressing development cycles and redirecting R&D spending toward clean-label platforms.
Near-infrared spectroscopy is digitizing real-time moisture and protein monitoring on extrusion lines. Mid-scale Brazilian processors deploy these sensors to reduce batch-to-batch variation without laboratory delays. The technology is digitizing quality assurance workflows, enabling faster line changeovers between fortified and standard formulations.
Chile's Law 20.606 front-of-pack warning system is forcing sugar reduction across all imported and domestic cereal categories. Manufacturers must reformulate or sacrifice shelf presence in Santiago's dominant supermarket chains. The regulation most acutely affects children's segments, where reformulated products now compete on whole-grain claims rather than sweetness intensity.
Specialty retailers and direct-to-consumer platforms are capturing granola and muesli demand that conventional supermarkets previously monopolized. Health-positioned brands bypass slotting fee structures through subscription models and boutique placement. This channel rotation concentrates in southern cone urban centers where disposable income supports premium positioning.
South America Breakfast Cereals Market Segmentation
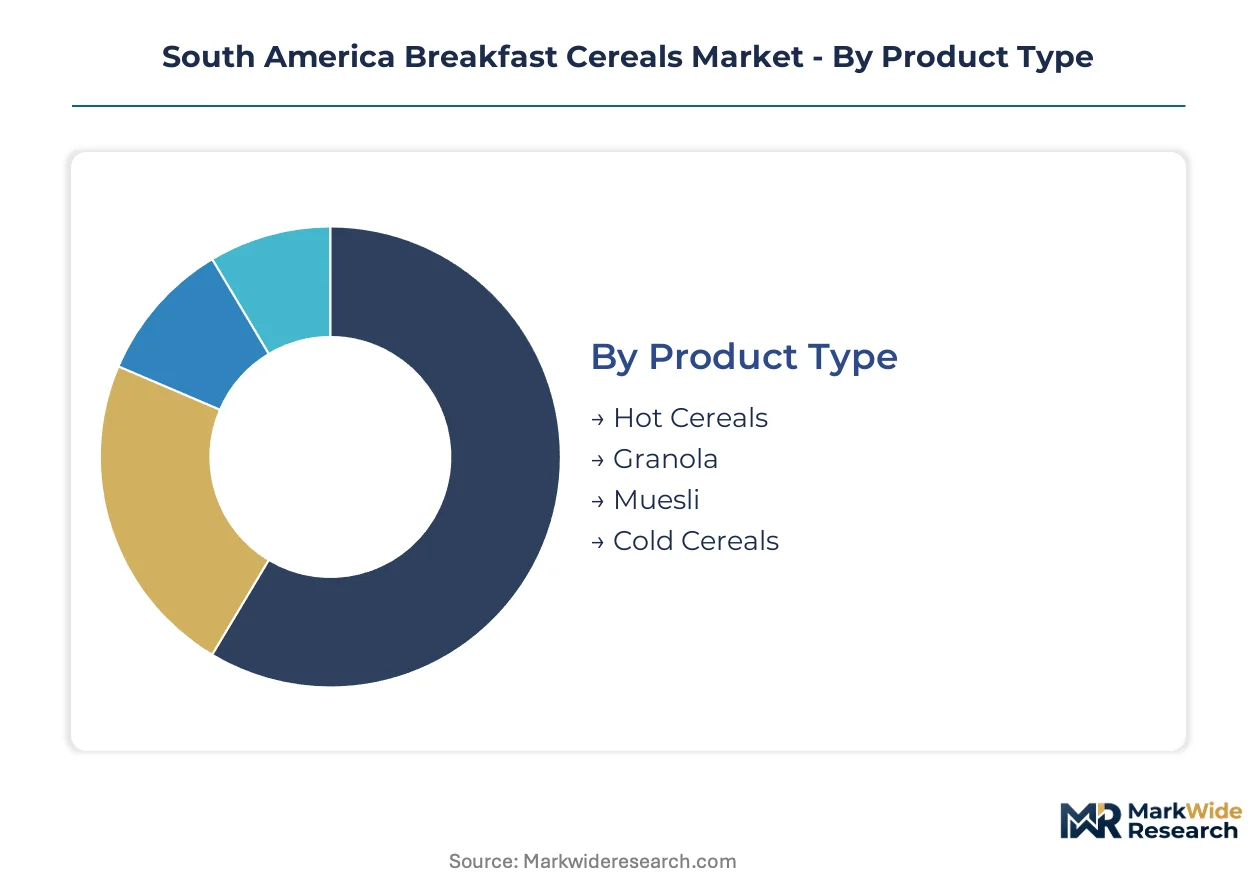
Segmentation in the South America Breakfast Cereals Market reveals how consumption patterns fragment across preparation methods, retail channels, and institutional buyers. Understanding these divisions exposes where margin pools concentrate and where capital-light entrants can bypass incumbent shelf dominance.
Product Type:
Cost tier differentiation separates convenience-oriented formats from premium-positioned health segments, with price elasticity varying sharply across preparation requirements.
- Cold Cereals:Extruded and flaked grain formulations dominate supermarket volume throughput across Brazil's southeastern corridor. São Paulo metropolitan households drive demand for single-serve portion packs targeting commuter consumption.
- Hot Cereals:Oat-based porridges and instant mixes capture traditional morning rituals in Colombian and Peruvian markets, with Quaker Oats leveraging established brand equity in these geographies.
- Granola:Baked clusters with dried tropical fruit integration command premium positioning in specialty channels.
- Muesli:Unbaked oat blends with nut and seed inclusions gain traction through subscription e-commerce in southern cone urban centers.
Cold cereals hold installed capacity. Muesli is rotating up the share rankings.
Distribution Channel:
Application-specific channel strategies determine whether brands capture mass-market volume or premium margins, with each route demanding distinct packaging and promotional investment.
- Supermarkets:Branded shelf space in São Paulo and Rio de Janeiro chains concentrates margin pools for fortification-enhanced children's cereals. Slotting fees and promotional calendars lock out smaller processors without trade marketing budgets.
- Online Retail:Direct-to-consumer platforms enable granola and muesli specialists to bypass traditional retail gatekeepers. Subscription models capture recurring revenue from health-conscious households in Buenos Aires and Santiago.
- Convenience Stores:Single-serve cold cereal packs target commuter traffic in urban corridors.
- Specialty Shops:Boutique placement supports clean-label and organic positioning for imported muesli brands.
Supermarkets anchor volume throughput. Online retail is expanding most quickly.
End User:
Customer type segmentation separates stable household replenishment cycles from volatile foodservice procurement patterns, with contract structures diverging sharply.
- Households:Weekly grocery replenishment drives baseline demand for family-sized cold cereal boxes across Brazilian urban centers. ANVISA fortification compliance functions as a purchase trigger for health-conscious parents.
- Hotels, Restaurants, and Cafes:Single-serve portion packs and bulk dispensers serve institutional breakfast service in tourism-dependent markets. Chile's coastal hotel chains increasingly specify low-sugar formulations to align with front-of-pack warning label compliance.
Households provide demand stability. Hotels, restaurants, and cafes offer volume concentration.
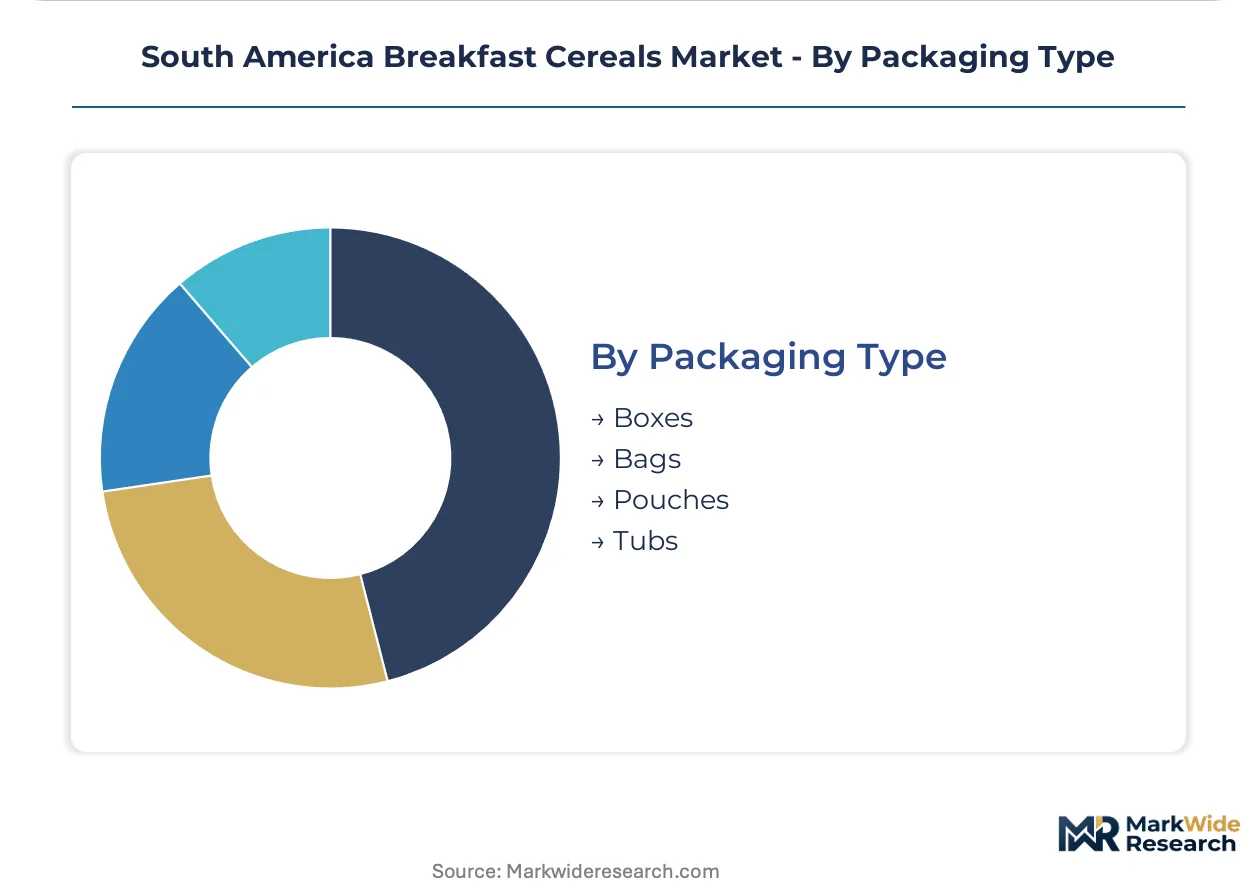
Packaging Type:
Volume and shelf-life requirements dictate material selection, with each format carrying distinct logistics economics and retail placement constraints.
- Boxes:Paperboard cartons with inner liners dominate branded cold cereal presentation in supermarket cereal aisles. Structural rigidity supports vertical stacking and shelf-ready display requirements.
- Bags:Flexible film packaging reduces freight cube for granola and muesli distribution through e-commerce channels.
- Pouches:Stand-up flexible packaging with resealable closures targets convenience store single-serve positioning.
- Tubs:Rigid plastic containers serve hot cereal instant mix formats requiring moisture protection.
Boxes maintain shelf presence dominance. Pouches are gaining share fastest in convenience channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA fortification mandates and Chile's front-of-pack warning label law are redirecting investment flows across South American production corridors. Brazil's southeastern manufacturing belt absorbs the majority of reformulation capital. Argentina, Colombia, and Peru present parallel compliance environments with distinct urban demand profiles.
Brazil
São Paulo's metropolitan corridor drives ready-to-eat consumption among dual-income households. ANVISA mandates iron and folic acid inclusion in packaged grain products. Extrusion capacity clusters within 300 kilometers of São Paulo, creating distribution chokepoints for northern states.
Argentina
Buenos Aires anchors hot cereal traditions that favor oat-based porridges over extruded flakes. The national food code governs micronutrient disclosure and fortification thresholds. Córdoba's agro-industrial belt supplies corn and wheat inputs to processors concentrated around Rosario.
Chile
Santiago's supermarket chains enforce Law 20.606 warning labels that block high-sugar formulations from shelf placement. DIGEMID oversees import compliance for cross-Andean cereal shipments. Concepción's specialty retailers pioneer clean-label granola positioning for health-conscious households.
Colombia
Bogotá and Medellín sustain demand for instant hot cereal mixes aligned with traditional breakfast rituals. INVIMA regulates fortification claims and front-of-pack labeling for domestic and imported products. Cali's food processing zone hosts contract manufacturers serving Andean distribution networks.
Peru
Lima's urban households display rising appetite for fortified cold cereals among working professionals. DIGEMID inspects imported shipments for compliance with national food safety standards. Trujillo and Chiclayo on the northern coast remain underdeveloped for modern trade penetration.
South America Breakfast Cereals Market Competitive Landscape
On the supply side, the industry is consolidating around multinational manufacturing footprints and regional backward integration strategies. Three strategic archetypes dominate: global brand licensors with established extrusion networks, domestic grain processors with captive agricultural supply, and specialty health-positioned entrants leveraging direct-to-consumer channels. Competitive moves center on equipment leasing partnerships that lower entry barriers and reformulation investments that convert regulatory compliance into brand differentiation.
Within the multinational tier, Kellogg's and PepsiCo exemplify scale-driven positioning anchored in regional production density. Grupo Nutresa occupies a distinct archetype as a domestic processor with upstream control over tropical fruit and grain sourcing. These three entities represent contrasting pathways to market presence: licensed global branding, supply chain integration, and portfolio diversification across morning nutrition categories.
| Leading Market Players |
|---|
| Kellogg's |
| Nestlé |
| General Mills |
| PepsiCo (Quaker Oats) |
| Bimbo |
| Unilever |
| Grupo Nutresa |
| Marico |
| Arcor |
| Others |
Value Network & Pricing Analysis
Mato Grosso and Paraná grain belts concentrate corn and rice supply for Brazilian extrusion facilities, anchoring margin pools in São Paulo's branded cold cereal tier where ANVISA fortification compliance commands shelf placement premiums.
Pricing Analysis
Fortification certification level creates the primary spread between ANVISA-compliant domestic production and non-fortified imports. Three-tier pricing structure separates premium whole-grain children's cereals, standard family-format boxes, and economy private-label bags. Pricing pressure stems from tropical grain input volatility squeezing mid-scale processors. Foodservice buyers in Chile's hotel chains display highest price sensitivity due to warning-label compliance costs, while health-positioned households in Buenos Aires tolerate premium subscription granola pricing.
Supply Chain Analysis
Upstream feedstock from Brazil, Argentina, and Colombia supplies corn, wheat, and tropical fruit inputs for regional formulation. Extrusion equipment and packaging films draw from Chinese and German manufacturing hubs. Single-source vulnerability concentrates in southeastern Brazil's milling corridor within 300 kilometers of São Paulo. Distribution runs through supermarket chains in metropolitan corridors, with direct-to-consumer channels bypassing traditional slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA fortification mandates and Chile's front-of-pack warning law constitute a dual regulatory inflection, compressing formulation timelines while opening clean-label white space for compliant producers.
For Market Incumbents: Entrench supply chain density through backward integration into Paraná corn sourcing and captive tropical fruit supply from Colombia's coffee belt. Expand extrusion capacity leasing partnerships to lock out capital-constrained challengers. Prioritize R&D investment in whole-grain platforms that satisfy both ANVISA micronutrient thresholds and Chile's sugar reduction requirements. For New Entrants and Emerging Players: Peru's northern coastal cities of Trujillo and Chiclayo represent the most penetrable entry point, with underdeveloped modern trade penetration and rising working-professional demand for fortified hot cereals. Subscription-based granola deliveries through direct-to-consumer channels bypass São Paulo supermarket slotting fees while capturing health-conscious southern cone households. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale Brazilian processors with ANVISA-compliant production lines and established e-commerce fulfillment infrastructure. Long-term viability hinges on regulatory arbitrage capability across Mercosur technical regimes. Watch for divergence between national fortification standards as the signal for SKU consolidation or geographic specialization plays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tropical Grain Supply | Captive sourcing from Mato Grosso corn belts insulates margin predictability against commodity swings. |
| Clean-Label Platform Launch | Whole-grain positioning aligns with Chile's Law 20.606 warning-label compliance for cross-Andean shelf placement. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass Rio de Janeiro supermarket slotting fees while capturing recurring revenue. |
| Extrusion Technology Leasing Partnerships | Capital-light equipment access enables mid-scale Argentine processors to enter branded production. |
| Multi-Jurisdiction Label Harmonization | Unified packaging formats reduce fragmentation costs across ANVISA, INVIMA, and DIGEMID compliance regimes. |
Research Methodology
A standing panel of extrusion operations managers, supermarket category buyers, ANVISA regulatory affairs specialists, and tropical grain procurement directors provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with facility tours across São Paulo, Rosario, and Bogotá processing plants. Secondary validation drew from ANVISA fortification filings, INVIMA product registrations, Nielsen retail audit data, and Mercosur technical regulation harmonization documents. Bottom-up capacity assessments and top-down consumption estimates were triangulated against trade flow records.
Scenario bracketing anchored the analytical framework across optimistic, baseline, and constrained growth paths over the projection horizon. Segmentation dimensions modeled include preparation method, distribution channel, end-user type, and packaging format alongside fortification compliance tier. CAGRs were derived from elasticity-adjusted volume projections and value-per-unit trends informed by grain input cost trajectories and regulatory compliance cost pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, Argentine inflation volatility, or Chilean consumer confidence indices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory implementation timelines and grain harvest yields. Cross-checking against Andean Community customs records and supermarket scanner data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Europe Food Spread Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Canned Beans Market
Packaged Foods
Club Store Packs Market
Packaged Foods
Iran Breakfast Cereals Market