
 Instant Noodles Market | 2026-2036
Instant Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Noodles Market Analysis
Market Context
Air-drying and flash-frying processing technology is fragmenting into regional specialization patterns as manufacturers optimize for local wheat flour grades and palm oil supply chains. Nissin Foods Holdings Co., Ltd. leverages its Japanese R&D heritage to sustain premium positioning in developed Asian markets. Indofood Sukses Makmur Tbk anchors Indonesian domestic demand through backward integration into wheat milling and seasoning production. Nestlé S.A. competes across multiple continents with localized flavor portfolios tailored to national preferences.
Technical Definition and Structural Segments
Instant noodles consist of wheat-based dough sheets that undergo mechanical sheeting, slitting, and either flash-frying in palm oil at 140-160°C or hot-air drying at 80-100°C to achieve moisture content below 10%, yielding a shelf-stable product reconstitutable in boiling water within three minutes for immediate consumption. Cup Noodles command disproportionate margin pools in urban convenience channels across East Asia, while Packaged Noodles dominates volume in price-sensitive South Asian and African households where bulk purchasing patterns prevail. Online Retailers represent the fastest-expanding distribution channel, particularly among Students and Working Professionals in metropolitan China and South Korea who prioritize delivery speed over supermarket browsing.
Regulatory Frame and Outlook
China's SAMR enforces GB standards for sodium content and additive labeling, while Indonesia's BPOM and India's FSSAI impose parallel fortification and hygiene mandates that dictate reformulation investments for cross-border suppliers. EFSA's evolving nutrient profiling criteria and WHO sodium reduction targets are pressuring European and Middle Eastern export formulations toward cleaner labels. Stakeholders must monitor divergence between Asia-Pacific permissive additive regimes and tightening Western nutritional thresholds when allocating R&D budgets across regional product pipelines.
Market Dynamics
China's GB food safety standards and sodium reduction mandates are forcing wholesale reformulation across manufacturing hubs, compressing profit margins while accelerating clean-label R&D investment cycles throughout the supply chain.
Growth Catalysts
- Urban Working Professionals:Time-constrained consumption patterns in metropolitan China and South Korea sustain premium cup noodle demand through convenience channels and online retail platforms.
- Air-Drying Technology:Lower oil content and extended shelf stability attract health-conscious segments in Japan and South Korea, displacing traditional flash-fried formulations in premium tiers.
- FSSAI Fortification Mandates:India's mandatory micronutrient enrichment creates volume expansion in rural distribution networks while aligning with public health objectives.
Market Restraints
- Palm Oil Price Volatility:Flash-frying dependency exposes manufacturers to Southeast Asian palm oil supply shocks and sustainability certification costs.
- Wheat Flour Concentration:Black Sea and Australian wheat sourcing bottlenecks threaten production continuity across Indonesian and Vietnamese manufacturing bases.
- EFSA Nutrient Profiling:Evolving European thresholds restrict additive portfolios and sodium levels, complicating export formulation for Asian producers.
Strategic Opportunities
- Vietnam Rural Penetration:Underdeveloped distribution infrastructure in Mekong Delta provinces offers first-mover advantage for localized flavor development and micro-retail partnerships.
- Plant-Based Protein Convergence:Pea and mung bean protein integration with traditional wheat dough creates differentiated positioning for flexitarian consumers in urban South Korea.
- SAMR Clean-Label Incentives:China's reduced-additive certification pathways reward early reformulators with preferential shelf placement in state-owned retail channels.
Industry Challenges
- Food Technologist Scarcity:Specialized expertise in low-sodium flavor chemistry and alternative protein texturization commands premium compensation in competitive labor markets.
- Dual Certification Timelines:Parallel BPOM and FSSAI approval processes delay product launches across Indonesian and Indian markets by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Noodles Market |
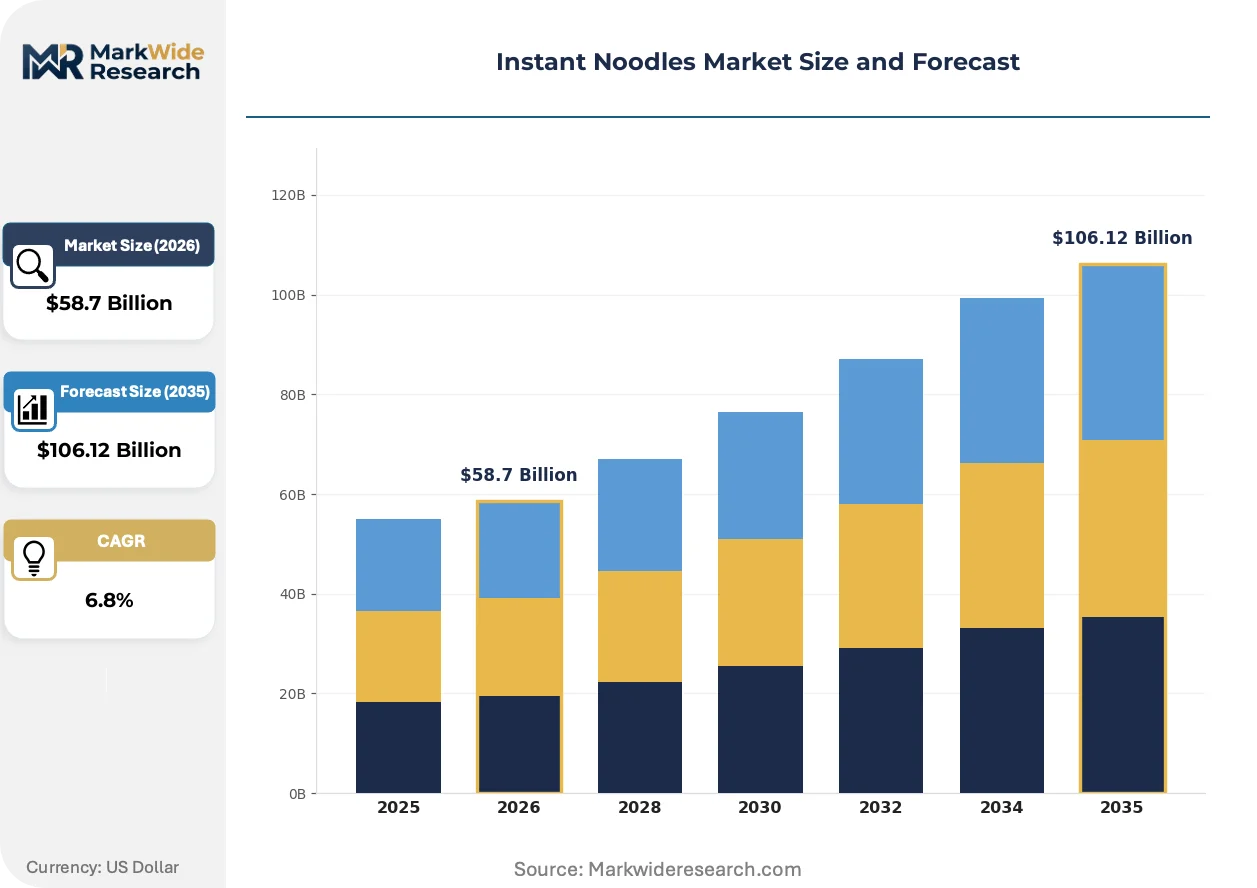
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried, Cup Noodles, Packaged Noodles, Instant Soup Flavor Profile: Spicy, Chicken, Beef, Seafood Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Stores End User: Students, Working Professionals, Families, Outdoor Enthusiasts |
| Companies Covered | Nissin Foods Holdings Co., Ltd., Indofood Sukses Makmur Tbk, Nestlé S.A., Unilever PLC, Nongshim Co., Ltd., Tingyi (Cayman Islands) Holding Corp., Samyang Foods Co., Ltd., Acecook Co., Ltd., Uni-President Enterprises Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Noodles Market Emerging Trajectories
Processing technology divergence and regulatory fragmentation are compressing product development cycles while opening whitespace for health-positioned formulations and direct-to-consumer channel experimentation.
Non-fried noodle production is virtualizing traditional manufacturing economics. Hot-air drying systems operating at 80-100°C eliminate palm oil dependency entirely. Nissin and domestic Chinese manufacturers are retrofitting facilities in Shanghai and Osaka metropolitan clusters. This capital shift is virtualizing the cost structure that previously tied margin performance to vegetable oil commodity cycles.
REACH chemical registration requirements and evolving EFSA sodium benchmarks are tightening additive permissibility for European-bound exports. Reformulation costs now consume disproportionate R&D budgets relative to volume potential. Southeast Asian producers serving Middle Eastern markets face parallel WHO sodium targets, forcing portfolio segmentation between regional and export-grade specifications.
Students and Working Professionals in Chinese tier-1 cities now prioritize delivery-platform purchasing over supermarket browsing. JD.com and Meituan instant fulfillment models displace traditional wholesale-distributor relationships. This channel migration concentrates demand forecasting risk with platform algorithms rather than manufacturer sales teams, compressing inventory visibility in Shenzhen and Beijing metropolitan zones.
Instant Noodles Market Segmentation
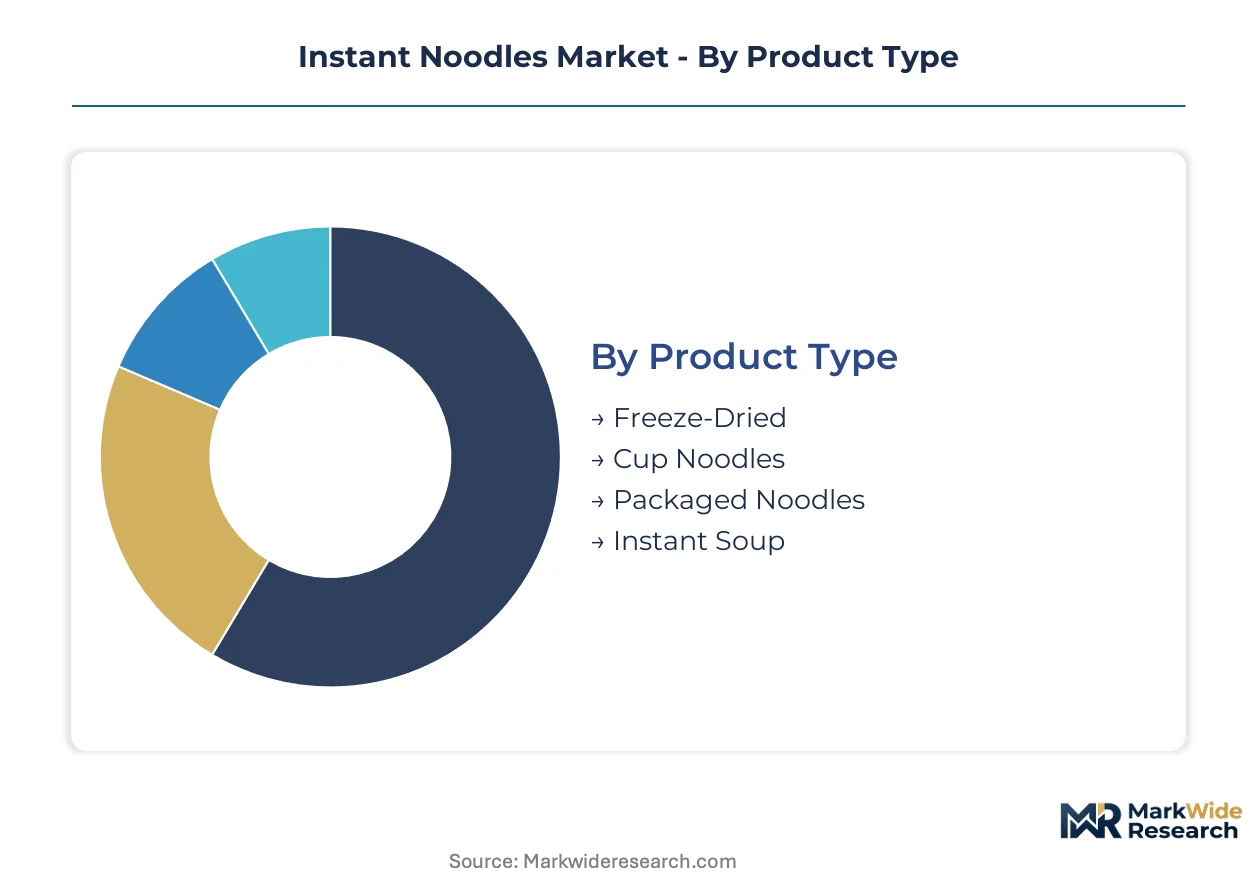
Instant noodles manufacturers navigate distinct demand rhythms across consumption occasions, packaging formats, and purchasing channels. Segmentation reveals where margin pools concentrate versus where volume velocity sustains factory utilization.
Product Type:
Cycle times vary dramatically: cup formats turn inventory weekly in urban convenience channels while bulk packs rotate monthly through rural wholesale networks.
- Cup Noodles:Pre-portioned servings in polystyrene or paper vessels with integrated lids, designed for immediate consumption without additional dishware. Metropolitan working professionals in Chinese tier-1 cities sustain demand through 24-hour convenience store channels and food-delivery platforms. SAMR container safety standards and sodium reduction mandates compress reformulation windows for this high-visibility format.
- Packaged Noodles:Compressed noodle blocks in flexible film packaging requiring separate preparation vessels, optimized for household stockpiling and institutional procurement. Rural Vietnamese and Indonesian families drive volume through traditional grocery and open-air market channels where unit economics favor bulk purchasing. Wheat flour cost exposure and palm oil price volatility squeeze margins at the economy tier.
- Freeze-Dried:Vacuum-dehydrated noodle and ingredient matrices reconstituting with hot water, preserving texture closer to fresh-cooked equivalents. Premium positioning targets health-conscious segments in Japanese and South Korean markets seeking reduced oil content.
- Instant Soup:Broth-concentrate and dehydrated vegetable combinations sold separately or bundled with plain noodles, capturing flavor customization demand.
Packaged Noodles anchors the volume base while Cup Noodles gains share at the steepest rate.
Flavor Profile:
Regional palate differentiation creates portfolio complexity: single-market dominance strategies fail where cross-border manufacturing centralization targets multiple taste regimes.
- Chicken:Universal acceptance across age demographics with formulation flexibility from mild bouillon to concentrated bone-extract bases. Indonesian and Vietnamese manufacturing hubs produce chicken variants at largest scale, leveraging localized seasoning supply chains. FSSAI fortification mandates in India accelerate micronutrient-enriched chicken broth development for school feeding programs.
- Spicy:Chili oil and capsicum-derived heat profiles calibrated to Scoville-equivalent intensity tiers, dominating South Korean and Sichuan provincial markets. MFDS additive labeling requirements and capsaicin extraction source documentation complicate export certification.
- Beef:Hydrolyzed soy protein and yeast extract-based savory profiles substituting for beef extract in price-sensitive segments, with premium tiers using actual bone broth reduction.
- Seafood:Dried shrimp, fish sauce, and kelp-derived umami formulations concentrated in coastal Chinese and Japanese consumption patterns, facing EFSA allergen labeling scrutiny for European-bound exports.
Chicken commands the broadest geographic penetration while Spicy climbs the fastest in per-capita consumption intensity.
Distribution Channel:
Channel economics diverge on working capital intensity: platform-dependent fulfillment concentrates demand forecasting risk with algorithmic inventory management.
- Online Retailers:JD.com, Meituan, and regional e-commerce platforms enabling sub-hour delivery in Chinese metropolitan zones, displacing traditional distributor relationships. Students and working professionals prioritize speed over supermarket browsing, compressing manufacturer visibility into platform data silos.
- Convenience Stores:7-Eleven, Lawson, and domestic chains providing immediate gratification for impulse and emergency consumption occasions.
- Supermarkets:Hypermarket and supermarket chains sustaining family stockpiling behavior with promotional multi-pack pricing, dominant in Indian and Southeast Asian urban peripheries.
- Specialty Stores:Asian grocery importers and ethnic food retailers serving diaspora populations in North American and European metropolitan clusters with premium import-tier positioning.
Supermarkets retain the volume foundation while Online Retailers expands most quickly in revenue contribution.
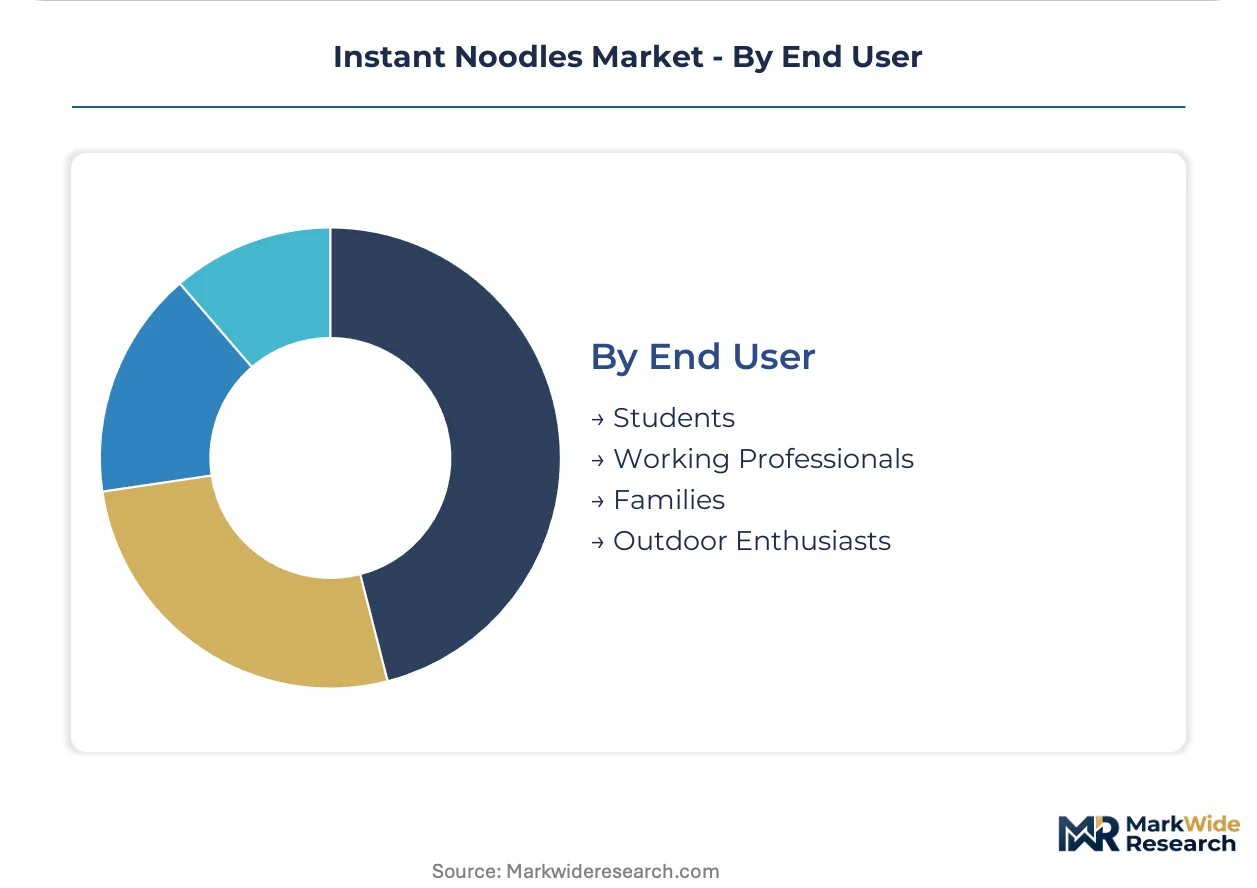
End User:
Occasion-based usage patterns segment preparation time tolerance and price sensitivity thresholds.
- Working Professionals:Time-constrained consumption in office and transit contexts, sustaining premium cup noodle and delivery-platform demand through convenience prioritization.
- Students:Budget-constrained bulk purchasing with flavor experimentation openness, concentrated in university-adjacent retail clusters across China and South Korea.
- Families:Multi-serving preparation with nutritional scrutiny, responding to sodium reduction messaging and clean-label positioning in Japanese and South Korean households.
- Outdoor Enthusiasts:Camping and expedition use cases prioritizing shelf stability and pack weight, niche but margin-accretive in specialized retail channels.
Families represent the largest absolute consumption base while Working Professionals shows the steepest per-capita spending trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian manufacturing clusters supply Southeast Asian markets while Chinese exporters navigate EFSA sodium thresholds for European-bound shipments. Wheat flour procurement from Black Sea and Australian sources shapes production economics across Vietnamese and Indonesian factory networks.
China
Working professionals in Shanghai and Beijing metropolitan zones sustain premium cup noodle demand through JD.com and Meituan delivery platforms. SAMR enforces GB standards for sodium content and additive labeling that compress reformulation windows. Yangtze River Delta manufacturing clusters near Shanghai retrofit facilities toward hot-air drying systems to eliminate palm oil dependency.
Indonesia
Rural households in Java and Sumatra drive packaged noodle volume through traditional grocery and open-air market channels. BPOM fortification and hygiene mandates dictate reformulation investments for cross-border suppliers. Manufacturing concentrates in West Java industrial zones where Indofood Sukses Makmur Tbk maintains backward integration into wheat milling and seasoning production.
Vietnam
Per-capita consumption rates in the Mekong Delta and Red River Delta exceed regional averages. The country's national food safety regulator imposes parallel standards that align with ASEAN harmonization frameworks. Ho Chi Minh City and Hanoi metropolitan areas anchor distribution infrastructure while underdeveloped rural provinces offer first-mover advantage for localized flavor development.
South Korea
Students and working professionals in Seoul Capital Area prioritize delivery-platform purchasing over supermarket browsing. MFDS additive labeling requirements and capsaicin extraction source documentation complicate export certification for spicy variants. Busan-Ulsan industrial corridors host manufacturing facilities serving domestic premium-tier demand and Japanese export markets.
India
Families in Maharashtra and Gujarat respond to sodium reduction messaging while rural distribution networks expand under FSSAI fortification mandates. School feeding programs accelerate micronutrient-enriched chicken broth development. Manufacturing clusters in Haryana and Telangana face wheat sourcing bottlenecks from Black Sea supply disruptions.
Instant Noodles Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated wheat processors and seasoning specialists with captive distribution networks. Three strategic archetypes dominate: diversified multinational food conglomerates with localized flavor portfolios, Asian specialists leveraging R&D heritage for premium positioning, and domestic champions controlling upstream milling operations. Competitive moves concentrate on backward integration into wheat supply and regulatory pre-certification for clean-label export tiers.
Within the Asian specialist tier, Nissin Foods Holdings Co., Ltd. and Nongshim Co., Ltd. occupy positions that exemplify R&D-driven premium segmentation. Among diversified conglomerates, Nestlé S.A. and Unilever PLC represent the archetype of multinational scale with localized formulation adaptation. Indofood Sukses Makmur Tbk anchors the domestic champion category through upstream control over Indonesian wheat milling and seasoning production.
| Leading Market Players |
|---|
| Nissin Foods Holdings Co., Ltd. |
| Indofood Sukses Makmur Tbk |
| Nestlé S.A. |
| Unilever PLC |
| Nongshim Co., Ltd. |
| Tingyi (Cayman Islands) Holding Corp. |
| Samyang Foods Co., Ltd. |
| Acecook Co., Ltd. |
| Uni-President Enterprises Corp. |
| Others |
Supply Flow & Price Mechanics
West Java industrial zones anchor Southeast Asian instant noodle production capacity, where Indofood Sukses Makmur Tbk's captive wheat milling operations translate upstream control into pricing power across Indonesian domestic channels. This concentration of integrated manufacturing creates margin buffers that independent processors in Vietnam and the Philippines struggle to replicate.
Pricing Analysis
Flash-fried versus hot-air drying technology-generation pricing gaps now exceed ingredient cost differentials, with non-fried premium tiers commanding shelf placement premiums in Japanese and South Korean convenience channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by sodium certification grade and palm oil content disclosure. Pricing pressure stems from SAMR clean-label compliance costs compressing mid-tier margins. Students represent the most price-sensitive buyer archetype, while working professionals in Chinese tier-1 cities exhibit lowest elasticity.
Supply Chain Analysis
Extended payment terms from Indonesian and Vietnamese distributors to wheat flour suppliers now stretch 90-120 days, straining working capital for smaller seasoning producers. Manufacturing concentrates in Indonesia, Vietnam, and China, with Black Sea and Australian wheat sourcing creating geographic dependency. Palm oil from Malaysian and Indonesian estates, wheat flour from Black Sea ports, and seasoning extracts from Chinese processors constitute critical input tiers. Single-source vulnerability in Black Sea wheat corridors threatens production continuity. Distribution runs through platform-dependent fulfillment in Chinese metropolitan zones and traditional wholesale networks in rural Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a structural moat, where early compliance with China's GB sodium standards and Indonesia's BPOM fortification mandates creates switching costs for retail channel access.
For Market Incumbents: Build regulatory certification moats by pre-positioning clean-label formulations ahead of FSSAI and EFSA tightening timelines. Deepen backward integration into wheat milling in Indonesian and Vietnamese manufacturing clusters to offset Black Sea supply volatility. Secure preferential shelf placement in state-owned Chinese retail channels through SAMR reduced-additive certification.
For New Entrants and Emerging Players: Establish a beachhead in Vietnam's Mekong Delta rural provinces where distribution infrastructure remains underdeveloped and localized flavor partnerships offer first-mover positioning. Target plant-based protein convergence segments in South Korean metropolitan markets where flexitarian demand outpaces incumbent R&D cycles. Deploy direct-to-consumer subscription models bypassing entrenched wholesale-distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with captive seasoning production and backward wheat integration, generating stable cash flows across commodity cycles. Acquisition targets should demonstrate BPOM or FSSAI pre-certification pipelines and established platform relationships with JD.com or Meituan. Watch for palm oil sustainability certification mandates as an inflection indicator that would accelerate consolidation around integrated processors.
| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Air Drying Facility Retrofit | Eliminates palm oil dependency and positions for EFSA sodium compliance in European export tiers. |
| Backward Wheat Milling Integration | Captures margin pools in Indonesian and Vietnamese manufacturing clusters while insulating Black Sea supply risk. |
| Clean-Label Certification Investment | Unlocks preferential shelf placement in SAMR-regulated Chinese state-owned retail channels. |
| Platform-Direct Fulfillment Partnership | Concentrates demand forecasting with JD.com and Meituan algorithms in tier-1 Chinese metropolitan zones. |
| Localized Flavor Development | Creates differentiation in Vietnam's Mekong Delta rural penetration where distribution infrastructure remains fragmented. |
Methodological Framework
A standing panel of instant noodle brand managers, wheat procurement directors at Indonesian and Vietnamese manufacturers, retail category buyers at Chinese platform operators, and FSSAI regulatory compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from SAMR GB standard filings, BPOM fortification compliance databases, Indonesian customs trade records, and Nielsen retail audit data for Southeast Asian convenience channels. Bottom-up facility capacity assessments and top-down consumption expenditure models were triangulated to anchor volume estimates.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, flavor profile, distribution channel, and end-user occasion. Modeled variables included wheat flour cost trajectories, palm oil price volatility bands, and regulatory compliance timeline assumptions. CAGRs were derived from slope-consensus convergence across demand-side elasticity estimates and supply-side capacity expansion schedules.
Sensitivities concentrate around Black Sea wheat supply disruptions, EFSA sodium threshold accelerations, and platform algorithm changes affecting Chinese metropolitan demand forecasting. Forecasts reflect documented assumptions on regulatory implementation pacing and commodity cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Instant Rice Market
Packaged Foods
North America Pasta Market
Packaged Foods
Dried Honey Market
Packaged Foods
Packaged Rice Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Global Food Spread Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Canned Food Market
Packaged Foods
Alginate Casings Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market