
 Organic Energy Bar Market | 2026-2036
Organic Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Energy Bar Market Outlook
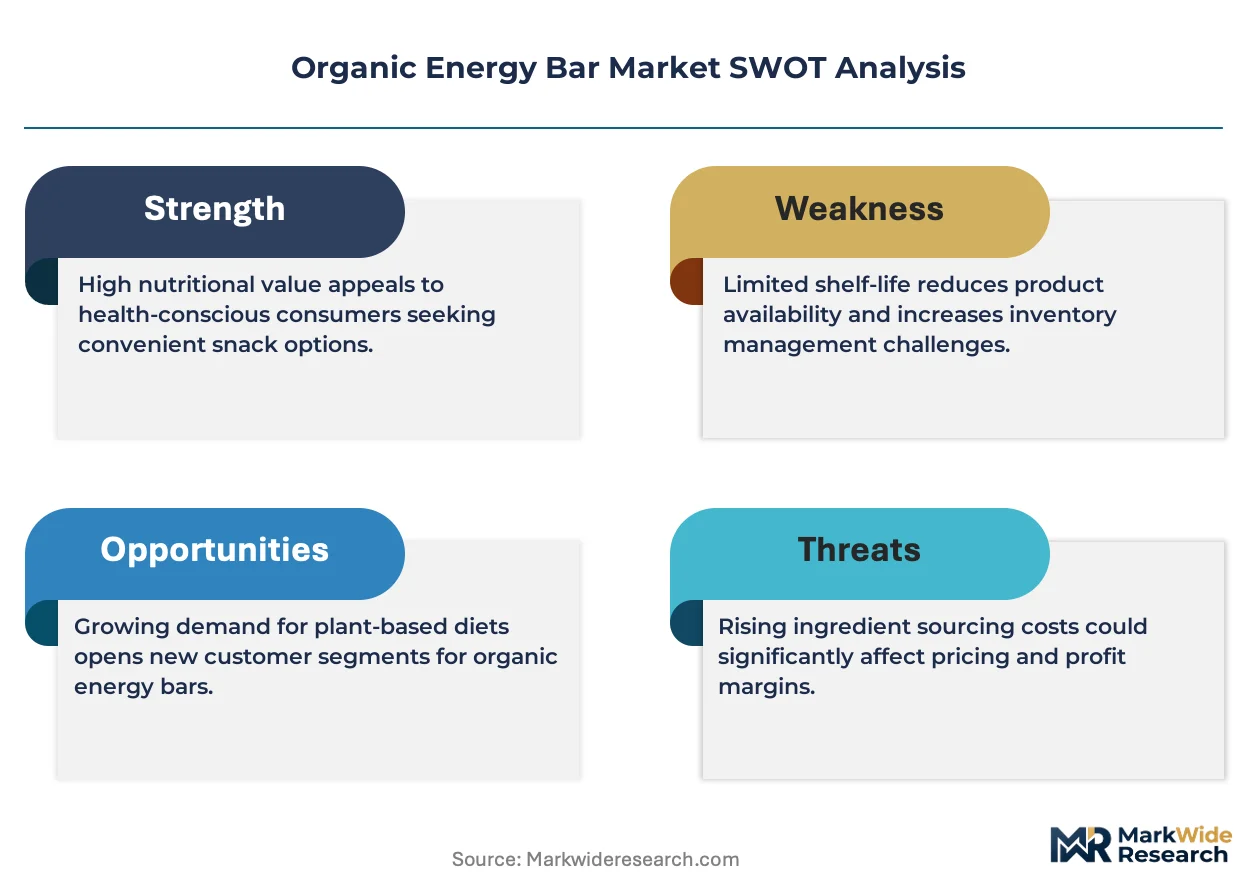
The organic energy bar category is pivoting between premium single-origin ingredient positioning and commodity-level private-label competition. Clif Bar & Company leverages its long-standing USDA Organic supply chain to sustain premium shelf placement across natural grocery channels. RXBAR competes through minimalist ingredient transparency, while GoMacro anchors its growth in allergen-free formulations that command higher unit economics.
An organic energy bar is a shelf-stable, nutrient-dense food product composed of certified organic ingredients such as nuts, dried fruits, seeds, and plant proteins, manufactured through cold-pressed or baked extrusion processes to preserve enzymatic activity and meet USDA or EU organic standards. Protein bars lead product type segmentation due to their alignment with post-workout recovery protocols and higher per-unit margins. Online retail channels represent the fastest-growing distribution vector, driven by subscription models and direct-to-consumer fulfillment infrastructure that bypasses traditional slotting fees.
The USDA Organic seal and EU Organic Regulation 2018/848 govern ingredient provenance and processing integrity, while the FDA and EFSA set labeling and nutritional claim boundaries that shape permissible marketing language. Compliance with these frameworks determines market access velocity and retail authorization timelines. Stakeholders must monitor evolving definitions of regenerative organic certification and their potential to create new tiered supply requirements.
Market Dynamics
Clean-label ingredient transparency is compressing formulation cycles across the organic energy bar supply chain, forcing manufacturers to rebuild supplier relationships around regenerative sourcing protocols rather than commodity procurement.
Growth Catalysts
- Athletic Recovery Protocols:Post-workout nutrition science has elevated protein bars from convenience snacks to prescribed recovery tools, embedding them in team nutritionist recommendations across collegiate and professional sports programs.
- EU Organic Regulation 2018/848:The updated certification framework tightens traceability requirements, creating competitive moats for producers with established audit-ready supply chains that smaller competitors cannot replicate.
- Cold-Pressed Extrusion:This processing technology preserves heat-sensitive enzymes and micronutrients, enabling premium positioning based on bioavailability claims that baked alternatives cannot match.
Market Restraints
- Organic Nut Price Volatility:Almond and cashew costs swing with California water allocation cycles and Vietnamese harvest variability, compressing gross margins unpredictably.
- USDA Certification Bottlenecks:Three-year transition periods for conventional farmland and inspector shortages delay new ingredient source qualification, throttling geographic expansion.
- Whole Food Substitutes:Fresh fruit and homemade trail mix retain cost and perceived freshness advantages for non-athlete consumers, limiting category penetration in price-sensitive households.
Strategic Opportunities
- German Clean-Label Maturity:Sustained purchasing behavior in this market signals readiness for next-tier regenerative organic certification that commands additional shelf price premiums.
- Subscription Direct-to-Consumer:Bypassing slotting fees and retailer margin stacks enables margin recovery and first-party data collection for personalized nutrition cross-selling.
- Allergen-Free Formulation Convergence:Combining vegan, gluten-free, and top-nine allergen exclusion creates defensible niche positioning with limited direct competition.
Industry Challenges
- Regenerative Organic Certification Timeline:The new ROC standard requires additional soil health and animal welfare audits, extending qualification timelines by 12-18 months for existing USDA Organic suppliers.
- Co-Manufacturer Capacity Constraints:Qualified organic contract manufacturers operate at utilization rates above 85%, forcing brands to commit to volume minimums that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Energy Bar Market |
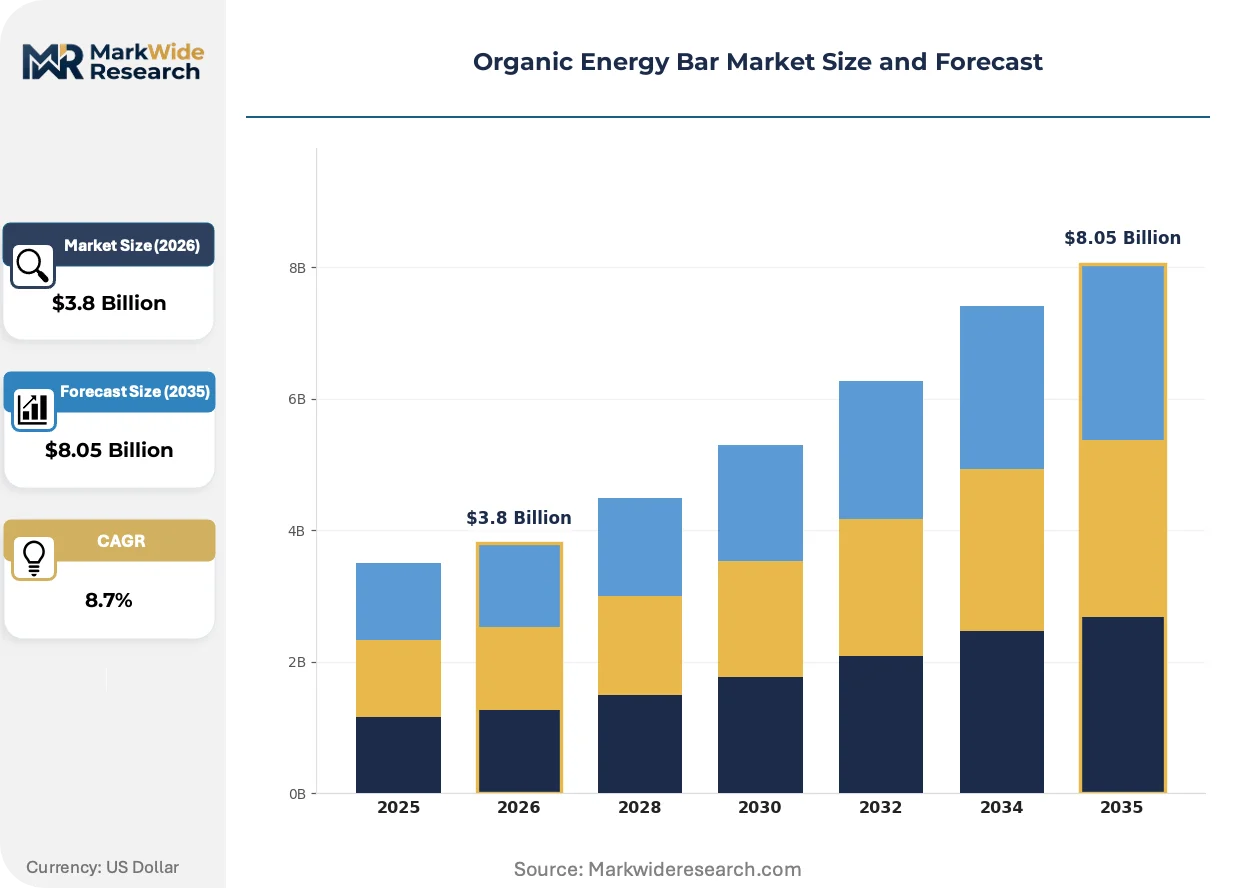
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Based Bars, Fruit-Based Bars, Protein Bars, Granola Bars Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Fitness Centers End Use: Health Enthusiasts, Athletes, Busy Professionals, Students Flavor Profile: Chocolate, Berry, Coconut, Peanut Butter |
| Companies Covered | Clif Bar & Company, General Mills Inc., Kind LLC, Probar LLC, McKee Foods Corporation, NuGo Nutrition, Kellanova, RXBAR, GoMacro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Energy Bar Market Strategic Shifts
Formulation science and distribution infrastructure are converging to reshape how organic energy bars reach consumers and justify price positioning.
Upcycled ingredient streams are unifying sustainability messaging with cost management. Spent grain from craft breweries and fruit pulp from juice processing now supply fiber and micronutrient content at below-commodity input costs. Marathon runners and CrossFit affiliates have adopted these products fastest, normalizing the taste profile. This technology is unifying environmental claims with margin preservation in a category where organic premiums face pressure.
Regenerative Organic Certification is tightening supply chain documentation requirements beyond baseline USDA Organic standards. The ROC framework mandates soil carbon monitoring and living wage verification, adding audit layers that favor vertically integrated producers. German retailers and natural grocery chains in the Pacific Northwest are prioritizing ROC-labeled SKUs, forcing reformulation and supplier requalification across tier-one brands.
Direct subscription fulfillment is displacing traditional natural channel dependence. Athletes and fitness enthusiasts now expect personalized flavor rotations and delivery timing, shifting volume from Whole Foods and Sprouts shelves to brand-owned warehouses. This behavioral pivot concentrates customer lifetime value data with manufacturers rather than retailers, most visible in California and Colorado metropolitan markets where gym density supports localized distribution nodes.
Organic Energy Bar Market Segmentation
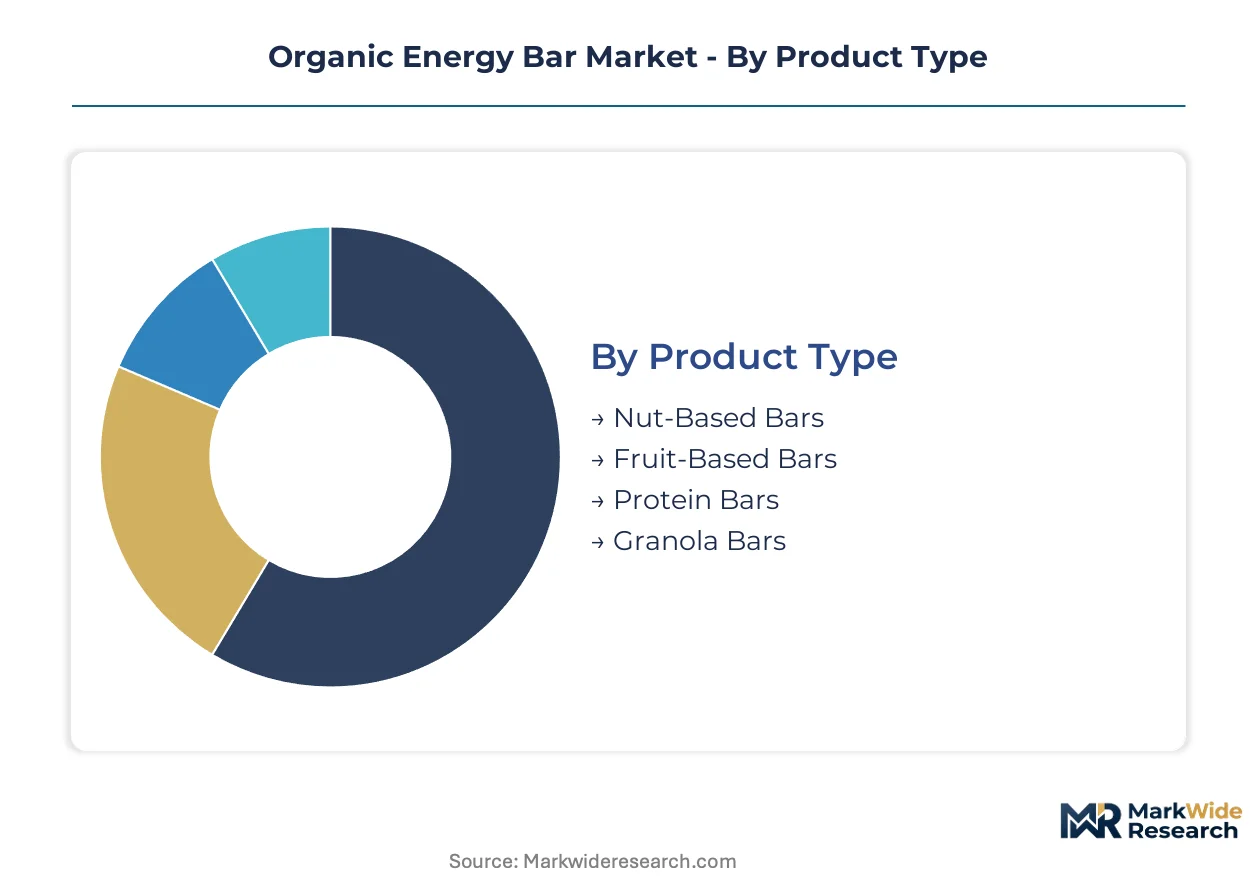
Organic energy bar manufacturers align product architecture with distinct certification burdens and channel requirements. Segmentation strategy determines which USDA Organic audit trails, cold-chain specifications, and shelf-life protocols apply to each SKU.
Product Type:
USDA Organic certification demands vary by base ingredient composition, with protein concentrates triggering additional amino acid sourcing documentation and nut-based formulations requiring pesticide residue testing at lower thresholds than fruit bases.
- Protein Bars:These formulations incorporate plant protein isolates from organic pea, rice, or hemp sources, requiring amino acid profile verification under USDA Organic livestock feed derivative rules. Athletes drive demand concentration here, with collegiate sports programs mandating third-party NSF Certified for Sport approval alongside organic certification. Cold-pressed processing preserves enzymatic activity that baked alternatives degrade.
- Nut-Based Bars:Almond, cashew, and walnut bases dominate this segment, sourced primarily from California orchards subject to three-year organic transition timelines. German retailers prioritize these SKUs for their clean-label density and satiety signaling. Water allocation volatility in California's Central Valley creates supply intermittency that compresses margin predictability.
- Fruit-Based Bars:Date and dried fruit binders with lower protein content.
- Granola Bars:Oat and seed clusters with higher carbohydrate ratios targeting hiking and outdoor recreation.
Protein bars sit at the top of the volume ranking, with nut-based bars climbing the fastest.
Distribution Channel:
Channel selection dictates margin recovery potential and data ownership, with direct fulfillment capturing customer lifetime value that retailer intermediation obscures.
- Online Retail:Subscription models bypass slotting fees and enable personalized flavor rotation algorithms. California and Colorado metropolitan markets support localized distribution nodes tied to gym density. First-party data collection enables cross-selling into adjacent nutrition categories.
- Fitness Centers:Proximity to consumption occasion drives impulse purchase velocity. CrossFit affiliates and boutique studios command premium placement fees. Post-workout timing captures consumers when protein synthesis signaling peaks.
- Supermarkets:Conventional grocery chains with expanding natural sets.
- Health Food Stores:Independent retailers with educated staff and regenerative organic prioritization.
Online retail commands the steepest expansion trajectory, while fitness centers deliver the highest per-square-foot velocity.
End Use:
Usage occasion segmentation determines formulation density, packaging format, and price positioning elasticity.
- Athletes:Team nutritionists prescribe specific macronutrient ratios for recovery windows. Collegiate and professional programs embed these products in protocol-driven consumption. Higher per-unit margins justify premium ingredient sourcing.
- Busy Professionals:Meal replacement occasions prioritize shelf stability and desk-drawer format compatibility. Convenience commands price tolerance that recreational users resist.
- Health Enthusiasts:Wellness-focused consumers with discretionary spending flexibility.
- Students:Price-sensitive demand concentrated in exam-period stress consumption.
Athletes anchor the revenue base, with busy professionals gaining share fastest.
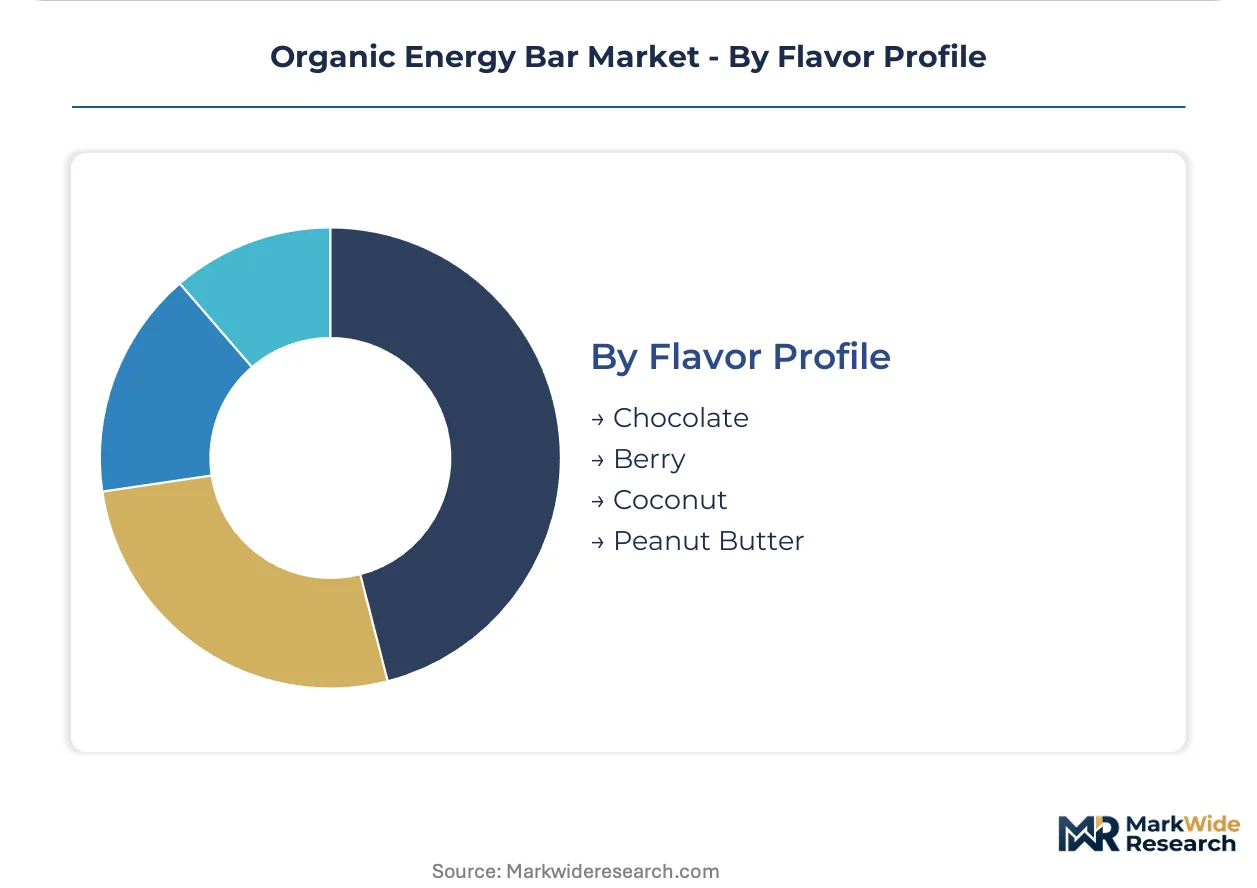
Flavor Profile:
Flavor architecture balances palatability validation with ingredient cost curves and supply security.
- Chocolate:Organic cacao sourcing from Ecuador and Peru requires deforestation-free supply chain documentation under emerging EU regulation. German consumers demonstrate sustained preference for dark chocolate variants with minimal added sweeteners. Cacao price volatility tracks West African harvest cycles and currency fluctuation.
- Peanut Butter:Domestic U.S. sourcing from Georgia and Alabama reduces transportation emissions and import documentation burden. Allergen labeling requirements create formulation constraints that limit co-manufacturer flexibility. Marathon runner communities normalize this taste profile through training ritual embedding.
- Berry:Cranberry and blueberry concentrates with antioxidant marketing claims.
- Coconut:MCT oil positioning for ketogenic diet alignment.
Chocolate dominates absolute volume, with peanut butter expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's clean-label maturity contrasts with the United States' athletic-recovery dominance, while emerging markets in Asia-Pacific demonstrate divergent certification readiness. National regulatory frameworks and consumption patterns create distinct competitive environments across major economies.
United States
Collegiate sports programs and CrossFit affiliates drive protein bar consumption through protocol-driven nutrition mandates. The USDA Organic certification framework governs ingredient sourcing with three-year farmland transition requirements. California's Central Valley anchors almond and cashew supply chains, though water allocation volatility compresses margin predictability for nut-based formulations.
Germany
Retailers prioritize regenerative organic certification as consumer willingness-to-pay for clean-label density sustains premium shelf positioning. The EU Organic Regulation 2018/848 tightens traceability requirements, favoring producers with audit-ready supply chains. Berlin and Hamburg metropolitan clusters support specialized natural grocery channels that command ROC-labeled SKU prioritization.
United Kingdom
Busy professionals in London and Southeast England sustain meal-replacement occasions with desk-drawer format compatibility. EFSA labeling boundaries shape permissible marketing language for nutritional claims. Manchester and Birmingham distribution nodes enable localized fulfillment infrastructure for subscription direct-to-consumer models.
Canada
Health Canada and the PMRA set pesticide residue thresholds that align with USDA Organic equivalency agreements. Ontario and British Columbia concentrate fitness center density and natural retail expansion. Toronto and Vancouver metropolitan markets demonstrate early adoption of personalized flavor rotation algorithms through brand-owned warehouses.
Australia
The TGA oversees complementary medicine claims that intersect with protein bar positioning for athletic recovery. New South Wales and Victoria host marathon runner communities that normalize specific taste profiles through training ritual embedding. Sydney and Melbourne support gym-density-aligned distribution nodes for proximity-to-consumption-occasion fulfillment.
Organic Energy Bar Market Competitive Environment
Top-tier vendors anchor premium organic certification tiers, while mid-scale specialists and private-label competitors populate commodity segments. The vendor base distributes across vertically integrated producers, co-manufacturer-dependent brands, and retailer-owned labels with divergent margin recovery potential. Strategic archetypes include USDA Organic supply chain veterans, minimalist ingredient transparency advocates, and allergen-free formulation specialists. Dominant competitive moves center on regenerative sourcing protocol adoption and direct-to-consumer subscription infrastructure buildout.
Within the established organic certification tier, Clif Bar & Company and RXBAR exemplify divergent positioning strategies, while GoMacro occupies a specialist position in allergen-free convergence. General Mills Inc. and Kellanova represent diversified food conglomerates with portfolio breadth spanning conventional and organic segments. These anchors illustrate how supply chain control, ingredient transparency, and niche formulation each command distinct consumer loyalty vectors and retail authorization timelines.
| Leading Market Players |
|---|
| Clif Bar & Company |
| General Mills Inc. |
| Kind LLC |
| Probar LLC |
| McKee Foods Corporation |
| NuGo Nutrition |
| Kellanova |
| RXBAR |
| GoMacro |
| Others |
Value Chain & Pricing Dynamics
Regenerative Organic Certification gates both qualified supply and premium-tier pricing access in the organic energy bar market, as the ROC framework's soil carbon monitoring and living wage verification requirements restrict supplier pools to vertically integrated producers capable of absorbing extended audit timelines. This environmental mandate compresses commodity-grade margins while amplifying price premiums for compliant SKUs, particularly in German and Pacific Northwest retail channels where ROC-labeled products command prioritized shelf placement.
Pricing Analysis
Capacity additions in Vietnam and California are reshaping price floors for nut-based formulations, though water allocation volatility in the Central Valley sustains unpredictability. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and cold-pressed processing method. Price differentiation hinges on USDA Organic versus ROC tier and brand heritage in athletic channels. Cost compression in private-label tiers is intensifying because co-manufacturer utilization rates above 85% force volume minimum commitments. Students represent the most price-sensitive buyer archetype, while collegiate sports programs demonstrate minimal elasticity due to protocol-driven procurement mandates.
Supply Chain Analysis
Inspector shortages across California, Vietnam, and Ecuador constrain qualified organic supplier onboarding, extending lead times for new ingredient source qualification. The supply chain draws from California almonds and cashews, Vietnamese cashew processing, and Ecuadorian organic cacao, with each node tethered to distinct environmental and labor audit requirements. Single-source vulnerability concentrates in California's Central Valley water-dependent orchards, where drought cycles trigger supply intermittency. Distribution runs through direct-to-consumer subscription infrastructure, natural grocery chains, and fitness center proximity nodes, with channel selection determining margin recovery and data ownership outcomes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the organic energy bar market rests on subscription infrastructure buildout and regenerative certification tier migration, as direct fulfillment bypasses retailer margin stacks while ROC compliance unlocks premium shelf pricing in clean-label mature markets.
For Market Incumbents: Deploy backward integration into almond and cashew orchards to secure supply continuity against California water volatility and Vietnamese harvest variability. Consolidate co-manufacturer relationships through volume commitments that lock capacity, while accelerating ROC qualification to preempt German retailer prioritization shifts. Threats from upcycled ingredient startups and minimalist transparency entrants require defensive formulation patenting around cold-pressed enzyme preservation protocols. For New Entrants and Emerging Players: Boutique fitness studios and CrossFit affiliates offer the most penetrable channel white-space, as these proximity-to-consumption nodes capture impulse velocity at post-workout timing peaks. Allergen-free formulation convergence—combining vegan, gluten-free, and top-nine exclusion—presents undefended niche positioning with limited direct competition. Go-to-market execution should anchor in localized subscription fulfillment tied to gym density clusters in Colorado and California metropolitan markets. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale ROC-compliant specialists because certification moats and extended audit timelines prevent rapid competitive replication. Long-term viability over the five-to-ten-year window favors vertically integrated producers with captive ingredient supply and established direct-to-consumer infrastructure. The signal to watch is German retailer ROC prioritization velocity, as shelf authorization shifts there will cascade to North American natural grocery chains.| Strategic Initiative | Industry Significance |
|---|---|
| Regenerative Organic Certification Investment | ROC compliance unlocks German retailer prioritization and Pacific Northwest shelf premiums. |
| Direct-to-Consumer Subscription Launch | Brand-owned fulfillment bypasses slotting fees and captures first-party data for cross-selling. |
| Backward Integration into Orchard Assets | Captive almond and cashew supply insulates margins from California water allocation volatility. |
| Allergen-Free Formulation Convergence | Vegan-gluten-free-top-nine exclusion creates defensible positioning with limited competition. |
| Cold-Pressed Processing Capacity Expansion | Enzyme preservation technology enables bioavailability claims that baked alternatives cannot match. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers, category buyers at natural grocery chains, supply planners at co-manufacturers, and sports nutritionists at collegiate athletic programs with secondary validation against USDA Organic certification databases, EU Organic Regulation 2018/848 implementation records, and Nielsen retail audit data. Bottom-up SKU-level volume modeling and top-down category sizing triangulated market estimates across protein bar, nut-based, fruit-based, and granola bar segments.
Segment-weighting approaches applied differential growth assumptions by distribution channel, with online retail and fitness center velocity receiving distinct trajectory parameters against supermarket and health food store baselines. The analytical framework modeled product type, certification tier, flavor profile, and end-use occasion dimensions across the projection horizon. CAGRs derived from historical organic certification penetration curves, subscription adoption patterns in adjacent nutrition categories, and athlete protocol embedding rates in collegiate and professional sports programs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regenerative organic certification timeline extensions, California water policy shifts, and EU traceability requirement amendments. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Europe Food Spread Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Ready Meal Trays Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
Alginate Casings Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
Packaged Rice Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Man-Made Sausage Casing Market