
 North America Hormone Replacement Therapy Market | 2026-2036
North America Hormone Replacement Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hormone Replacement Therapy Market Intelligence
North American pharmaceutical manufacturers is pivoting toward bioidentical hormone formulations and patient-centric delivery systems. Pfizer Inc. leverages its established manufacturing infrastructure to sustain broad distribution across retail and institutional channels. AbbVie Inc. anchors its position through specialized endocrinology partnerships and focused therapeutic development. Novo Nordisk A/S competes on peptide-based hormone innovation and diabetes-endocrinology crossover expertise.
Hormone Replacement Therapy comprises the clinical administration of synthetic or bioidentical hormones—primarily estrogen, progesterone, and testosterone—to restore endocrine balance in patients with deficient or declining natural production, typically formulated at standard concentrations ranging from 0.3 mg to 2.5 mg for oral estrogen equivalents depending on indication and patient profile. The therapy serves to alleviate vasomotor symptoms, prevent bone mineral density loss, and manage metabolic and urogenital complications associated with menopause, hypogonadism, and related endocrine disorders. Estrogen-based regimens dominate current prescription volumes, reflecting established clinical protocols and broad reimbursement coverage, while combination therapy segments capture expanding margin pools as personalized dosing protocols gain traction among endocrinology specialists. Transdermal patches and gels represent the fastest-growing delivery mode categories, driven by patient preference for steady-state plasma levels and reduced hepatic first-pass metabolism.
FDA oversight of hormone therapy safety labeling, combined with Health Canada/PMRA vigilance on thromboembolic risk profiles, shapes product development priorities and post-market surveillance obligations across the continent. State-level pharmacy compounding regulations in the U.S. and provincial formularies in Canada create fragmented access conditions that manufacturers must navigate for market penetration. Stakeholders should monitor evolving FDA guidance on bioidentical hormone categorization and reimbursement parity between synthetic and compounded formulations as determinants of competitive positioning.
Market Dynamics
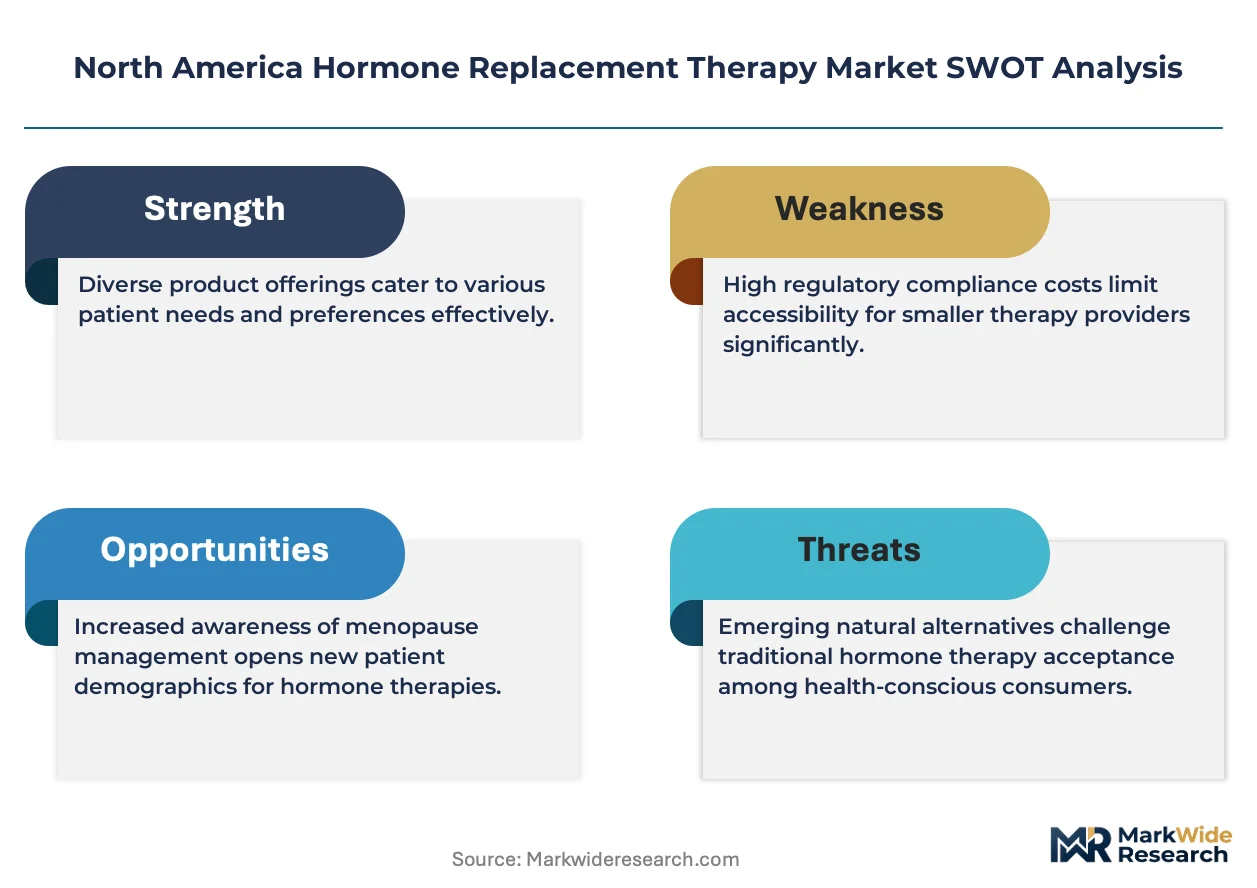
FDA labeling updates for transdermal estrogen products are compressing physician prescribing windows and accelerating formulation switches toward bioidentical alternatives. This regulatory pressure is reshaping competitive positioning across the North American pharmaceutical landscape.
Growth Catalysts
- Bioidentical Formulation Demand:Patient preference for molecularly identical hormones is expanding prescription volumes at specialized gynecology clinics across the U.S. Northeast corridor.
- Transdermal Delivery Innovation:Steady-state plasma level advantages are displacing oral regimens in endocrinology practices seeking reduced hepatic first-pass metabolism.
- Provincial Formulary Expansion:Health Canada/PMRA reimbursement adjustments in Ontario and British Columbia are unlocking institutional channel access for combination therapy segments.
Market Restraints
- Thromboembolic Risk Profiling:FDA black-box warnings on systemic estrogen products constrain prescribing latitude for patients with cardiovascular comorbidities.
- Active Pharmaceutical Ingredient Concentration:Bulk hormone precursor supply concentrates among three specialty chemical manufacturers, creating input cost volatility.
- State Compounding Fragmentation:Inconsistent pharmacy board regulations across U.S. states generate compliance overhead for multi-jurisdictional distribution.
Strategic Opportunities
- Peptide-Based Hormone Convergence:Diabetes-endocrinology crossover expertise enables novel therapeutic positioning for metabolic syndrome patient populations.
- Patient-Centric Delivery Systems:Wearable patch technologies with smartphone-integrated dosing reminders open direct-to-consumer channel possibilities.
- Reimbursement Parity Advocacy:Synthetic versus compounded formulation equivalence campaigns at CMS and provincial health authorities could unlock margin expansion.
Industry Challenges
- Specialized Endocrinology Talent Scarcity:Fellowship-trained hormone therapy practitioners cluster in metropolitan corridors, leaving rural and exurban markets underserved.
- Post-Market Surveillance Infrastructure:FDA-mandated thromboembolic event reporting systems require significant pharmacovigilance investment relative to product revenue thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hormone Replacement Therapy Market |
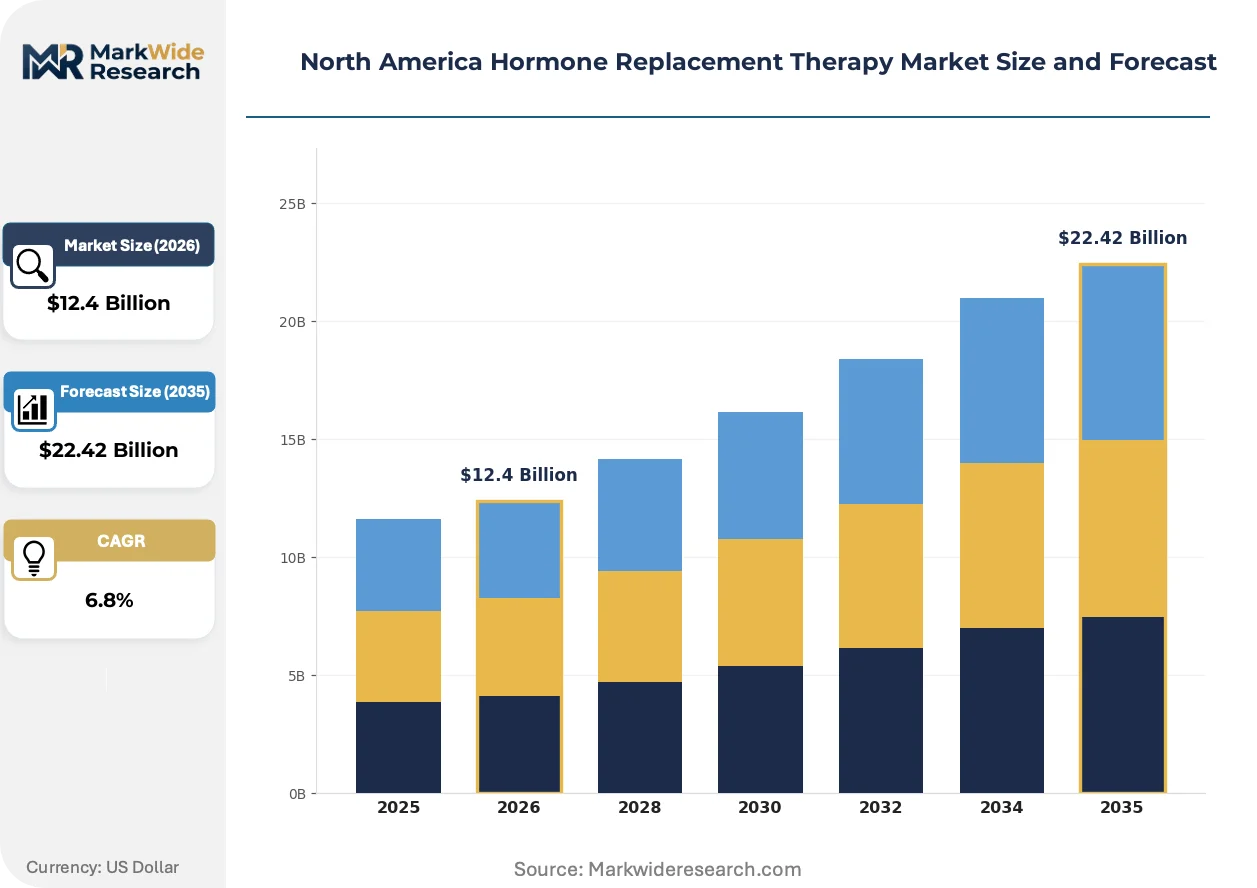
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Estrogen, Progesterone, Testosterone, Combination Therapy Delivery Mode: Pills, Injections, Patches, Gels End User: Hospitals, Clinics, Homecare, Ambulatory Surgical Centers Application: MENAP, Postmenopausal Symptoms, Osteoporosis, Hypogonadism |
| Companies Covered | Pfizer Inc., AbbVie Inc., Novo Nordisk A/S, Bayer AG, Eli Lilly and Company, F. Hoffmann-La Roche Ltd, Merck & Co., Inc., Amgen Inc., Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hormone Replacement Therapy Market Strategic Shifts & Innovations
Continuous glucose monitoring hardware architectures are migrating into hormone delivery systems, enabling closed-loop feedback mechanisms for personalized dosing. This convergence is compressing development timelines for next-generation therapeutic platforms.
Micro-needle array patches are integrating ceramic reservoir technologies for 7-day estradiol release profiles. Academic medical centers in Massachusetts and California are piloting these platforms for surgical menopause patients. The technology is integrating patient-reported outcome data streams directly into electronic health record systems, compressing the feedback loop between dosing adjustment and symptom resolution.
FDA guidance on bioidentical hormone categorization remains under development, creating provisional compliance frameworks for manufacturers. Health Canada/PMRA has advanced its own parallel consultation, generating divergent labeling requirements. Transdermal product developers are responding with dual-track regulatory submissions to maintain market access across both jurisdictions.
Direct-to-patient subscription models are displacing traditional retail pharmacy fulfillment for maintenance therapies. Specialized telehealth platforms serving perimenopausal populations in Texas and Florida are bundling diagnostic testing with automated refill logistics. This channel shift is most visible in Sun Belt states where specialist density lags behind patient demand.
North America Hormone Replacement Therapy Market Segmentation
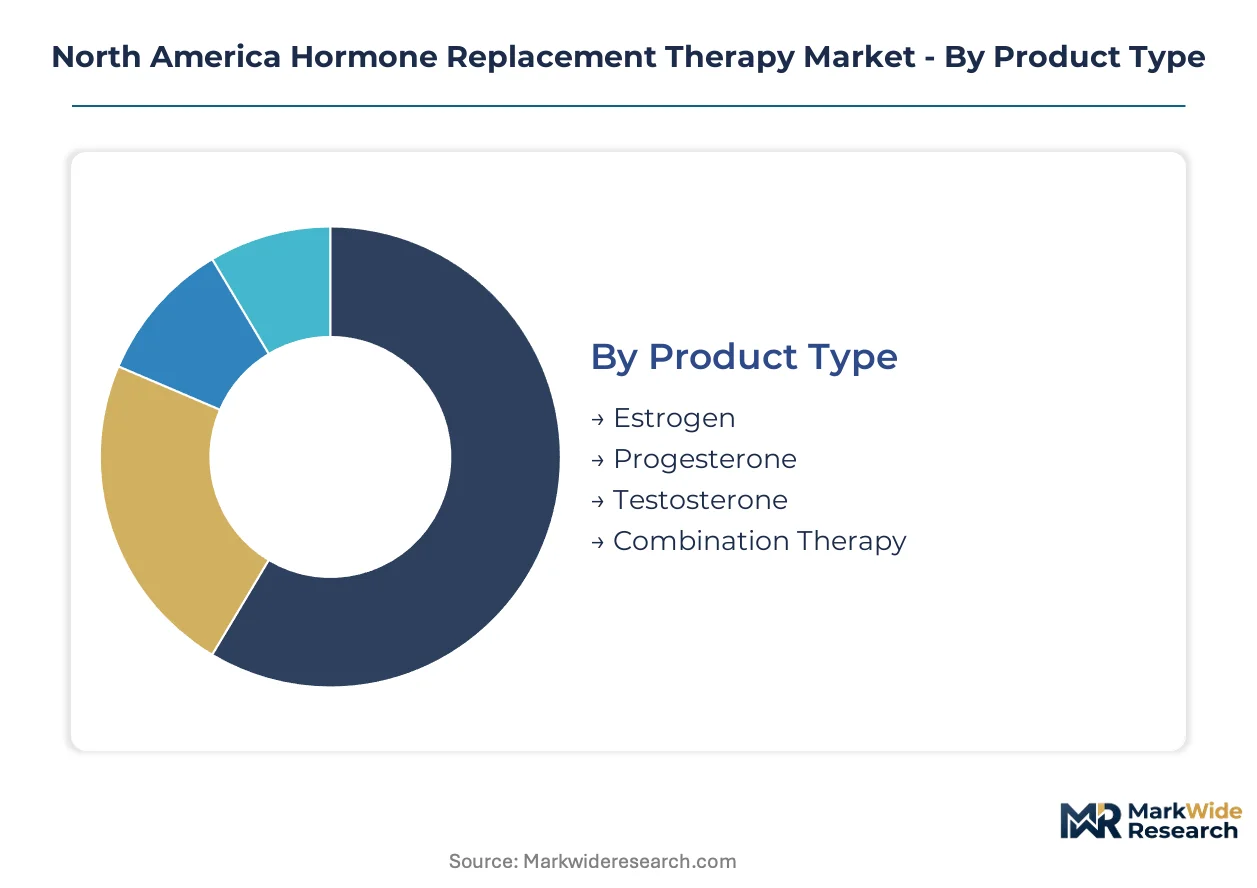
Hormone replacement therapy segmentation reveals distinct commercial architectures across product chemistry, delivery physics, and care setting economics. Each dimension carries specific reimbursement logic and prescriber specialization requirements that determine competitive access.
Product Type:
Integration depth varies sharply across hormonal chemistries, with standalone estrogen regimens dominating outpatient protocols while combination therapies embed into specialized metabolic management.
- Estrogen:Synthetic and bioidentical estradiol formulations at 0.3 mg to 2.5 mg oral equivalents constitute the foundational prescribing category across gynecology practices. Demand concentrates in the U.S. Northeast corridor where specialist density supports complex titration protocols; FDA labeling updates on transdermal products are compressing physician windows toward bioidentical alternatives.
- Combination Therapy:Estrogen-progesterone and multi-hormone regimens capture expanding margin pools as personalized dosing protocols gain traction among endocrinology specialists. Massachusetts and California academic medical centers pilot these platforms for surgical menopause patients, integrating patient-reported outcomes into electronic health record feedback loops.
- Progesterone:Micronized and synthetic progestin formulations serve uterine protection requirements in estrogen-opposed regimens, with prescription volumes tied to combination therapy adoption curves.
- Testosterone:Androgen replacement for female sexual dysfunction and male hypogonadism occupies a narrower prescriber base, concentrated in urology and specialized endocrinology practices with off-label protocol flexibility.
Volume placements concentrate in Estrogen; the faster expansion belongs to Combination Therapy.
Delivery Mode:
Cost tier stratification separates premium steady-state systems from economy oral generics, with reimbursement parity driving channel selection across Medicare and commercial formularies.
- Patches:Transdermal estradiol patches with 7-day release profiles command premium positioning through reduced hepatic first-pass metabolism and improved cardiovascular risk profiles. Texas and Florida telehealth platforms bundle diagnostic testing with automated refill logistics for maintenance patch therapies.
- Gels:Metered-dose transdermal testosterone and estrogen gels enable patient-controlled application with flexible dosing adjustment, displacing injectable regimens in endocrinology practices seeking outpatient convenience.
- Pills:Oral conjugated estrogens and synthetic progestins retain economy-tier dominance through broad generic availability and established CMS reimbursement codes, though prescribing is compressing under thromboembolic risk profiling.
- Injections:Depot formulations concentrate in institutional settings and specialized clinics with nursing support, serving patients with adherence challenges or gastrointestinal contraindications to oral routes.
Prescription volumes peak in Pills; the steepest expansion trajectory belongs to Patches.
End User:
Customer type segmentation maps to care intensity, with standalone homecare emerging against embedded hospital-based initiation protocols.
- Clinics:Gynecology and endocrinology specialty clinics anchor prescription origination across the U.S. Northeast corridor, with Massachusetts and California academic centers piloting micro-needle array patches and closed-loop dosing systems.
- Homecare:Direct-to-patient subscription models are displacing traditional retail pharmacy fulfillment for maintenance therapies, most visible in Sun Belt states where specialist density lags behind patient demand.
- Hospitals:Inpatient initiation concentrates in surgical menopause cases and oncology-related ovarian failure, with formulary committees prioritizing thromboembolic risk profiles in product selection.
- Ambulatory Surgical Centers:Limited hormone therapy presence concentrates in pre-operative optimization and post-surgical transition protocols, with reimbursement constraints limiting expansion.
Volume concentrates in Clinics; the channel gaining share fastest is Homecare.
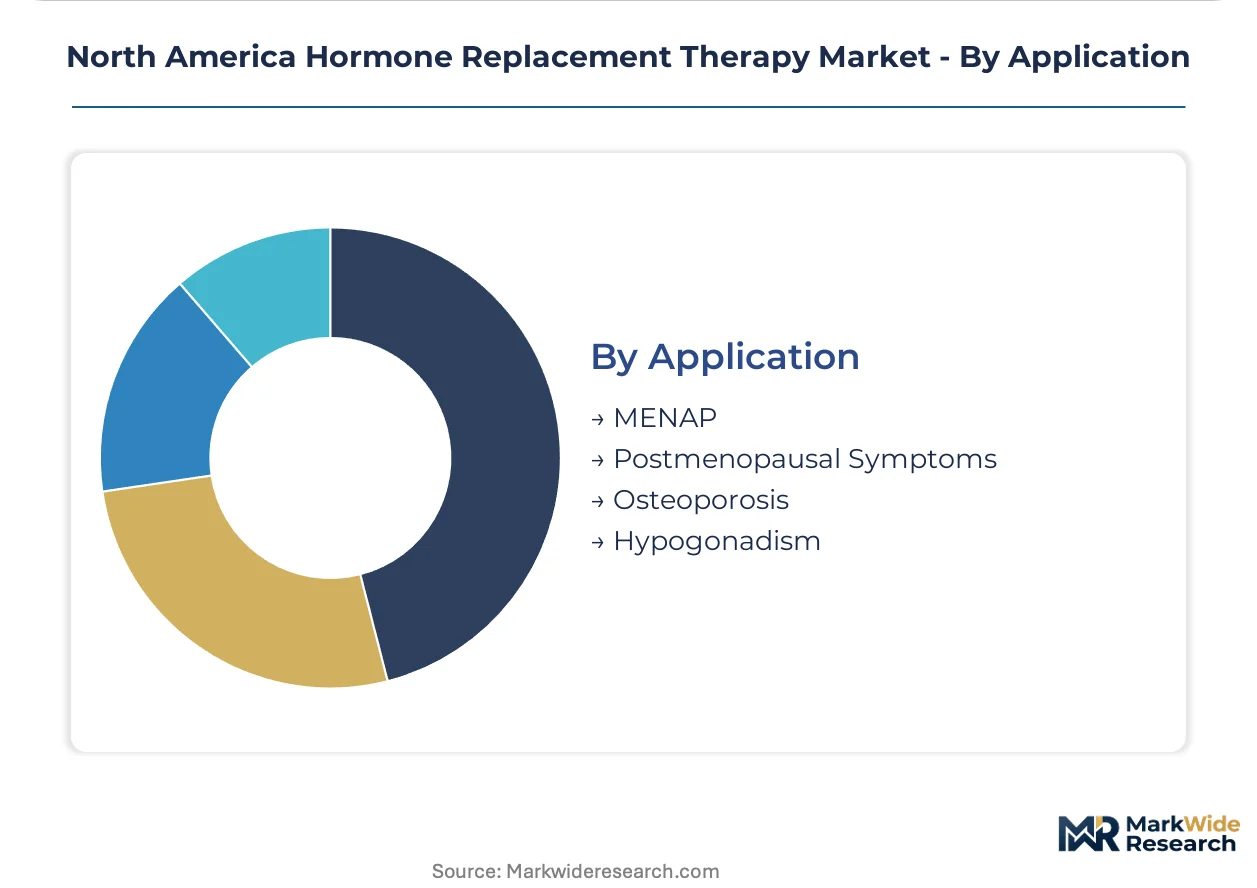
Application:
Maturity gradients separate established menopausal symptom management from emerging metabolic and bone density indications with evolving evidence bases.
- Postmenopausal Symptoms:Vasomotor symptom management represents the established clinical foundation with broad reimbursement coverage and established FDA-approved labeling, though prescribing latitude is compressing under cardiovascular risk profiling requirements.
- Osteoporosis:Bone mineral density preservation indications occupy a narrower prescriber base with competing bisphosphonate and monoclonal antibody alternatives, requiring endocrinology specialist engagement for hormone-based protocols.
- MENAP:Menopause-associated metabolic syndrome management is converging with diabetes-endocrinology crossover expertise, enabling novel therapeutic positioning for peptide-based hormone innovation.
- Hypogonadism:Primary and secondary gonadal failure indications span male and female populations with distinct prescriber specializations, concentrated in urology, reproductive endocrinology, and academic medical center protocols.
Volume placements concentrate in Postmenopausal Symptoms; the application climbing the fastest is MENAP.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical precursors for hormone synthesis concentrate in the U.S. Gulf Coast and Atlantic Canada petrochemical corridors, with downstream formulation and distribution networks radiating from these feedstock anchors into metropolitan clinical clusters.
United States
FDA labeling updates on transdermal estrogen products are compressing physician prescribing windows toward bioidentical alternatives. Massachusetts and California academic medical centers pilot micro-needle array patches with 7-day estradiol release profiles. The U.S. Northeast corridor maintains the highest specialist density, with gynecology clinics in Greater Boston and New York Metro expanding prescription volumes as patient awareness rises.
Canada
Health Canada/PMRA reimbursement adjustments in Ontario and British Columbia are unlocking institutional channel access for combination therapy segments. Provincial formulary expansion in these provinces is accelerating uptake of transdermal delivery systems. Toronto and Vancouver anchor the clinical trial infrastructure for bioidentical hormone categorization studies.
Mexico
Pharmaceutical manufacturing investment in Nuevo León and Jalisco is building regional capacity for hormone precursor synthesis. COFEPRIS regulatory alignment initiatives with FDA standards are streamlining cross-border product registration. Mexico City Metro concentrates specialist endocrinology practice, with private hospital networks driving premium-tier therapy adoption.
North America Hormone Replacement Therapy Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue peptide-based hormone convergence and wearable delivery system integration. The market exhibits moderate consolidation, with incumbent pharmaceutical manufacturers leveraging manufacturing infrastructure against specialized biotechnology developers. Three archetypes dominate: diversified pharmaceutical conglomerates with broad distribution networks, endocrinology-focused specialists with therapeutic development pipelines, and diabetes-endocrinology crossover innovators with metabolic syndrome positioning. Competitive dynamics center on strategic partnerships with academic medical centers and portfolio diversification into patient-centric delivery technologies.
Within the diversified pharmaceutical tier, Pfizer Inc. and AbbVie Inc. represent established manufacturing infrastructure archetypes, while Novo Nordisk A/S exemplifies the diabetes-endocrinology crossover specialist positioning. These three entities anchor distinct competitive vectors: broad retail and institutional channel coverage, specialized endocrinology partnerships, and peptide-based hormone innovation respectively. Their collective presence shapes prescription origination patterns across gynecology clinics, homecare subscription models, and academic medical center protocols.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Novo Nordisk A/S |
| Bayer AG |
| Eli Lilly and Company |
| F. Hoffmann-La Roche Ltd |
| Merck & Co., Inc. |
| Amgen Inc. |
| Viatris Inc. |
| Others |
Cost & Logistics Intelligence
Specialized gynecology clinics and academic medical centers anchor procurement volumes for bioidentical hormone formulations, concentrating purchasing power among prescriber networks that negotiate value-based contracts with manufacturers. This buyer concentration supports subscription-based pricing for maintenance therapies while transactional spot purchasing persists for oral generics in retail pharmacy channels.
Pricing Analysis
Warranty and service bundling separates premium transdermal delivery systems from unbundled oral tablet offerings, with patch manufacturers including patient support programs and smartphone-integrated dosing reminders in contracted pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by cardiovascular risk profile and delivery sophistication, with FDA black-box warnings on systemic estrogen compressing margins in the oral tier. Cost compression in economy oral generics is intensifying because of thromboembolic risk profiling and generic substitution mandates. Price-sensitive Medicare Part D formularies drive volume in the economy tier, while least-sensitive cash-pay patients in direct-to-consumer channels absorb premium patch pricing.
Supply Chain Analysis
FDA and Health Canada/PMRA certification requirements gate active pharmaceutical ingredient sourcing, with estradiol and testosterone precursors drawing from U.S. Gulf Coast petrochemical corridors, Atlantic Canada specialty chemical manufacturers, and Mexican synthesis facilities in Nuevo León. Bulk hormone precursor supply rests on three specialty chemical manufacturers, creating single-source vulnerability for estrone and micronized progesterone feedstocks. Tariff exposure on Chinese-sourced chemical intermediates compounds input cost volatility. Distribution runs through wholesale pharmaceutical distributors into retail pharmacy, institutional formulary, and direct-to-patient subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA-mandated thromboembolic event reporting systems and evolving bioidentical hormone categorization guidance erect compliance barriers that favor established manufacturers with dedicated pharmacovigilance infrastructure over capital-constrained entrants.
For Market Incumbents: Deploy pharmacovigilance automation to reduce per-unit compliance overhead as FDA post-market surveillance obligations expand. Secure backward integration into active pharmaceutical ingredient synthesis to buffer specialty chemical precursor cost volatility from Gulf Coast suppliers. Consolidate endocrinology specialist partnerships in the U.S. Northeast corridor before telehealth platforms disintermediate traditional prescriber relationships. For New Entrants and Emerging Players: Capture Sun Belt states where specialist density lags patient demand and direct-to-patient subscription models face lighter regulatory scrutiny than institutional formulary access. Target Texas and Florida homecare channels with bundled diagnostic testing and automated refill logistics as the most penetrable geography. Pursue peptide-based hormone convergence for metabolic syndrome populations as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors diabetes-endocrinology crossover specialists with existing FDA rapport and manufacturing infrastructure transferable to hormone therapy production. Long-term viability hinges on reimbursement parity advocacy capabilities and wearable delivery system integration. Watch Health Canada/PMRA bioidentical hormone categorization rulings as the inflection indicator for margin expansion across North American jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Dual-track FDA and Health Canada/PMRA submissions maintain cross-border market access amid divergent labeling requirements. |
| Manufacturing Scale-Up | Micro-needle array patch production expansion in Massachusetts and California academic medical centers accelerates 7-day estradiol release commercialization. |
| Pipeline Diversification | Peptide-based hormone innovation leverages Novo Nordisk's diabetes-endocrinology crossover expertise for metabolic syndrome positioning. |
| Strategic Partnership | Specialized telehealth platform alliances in Texas and Florida bundle diagnostic testing with automated refill logistics for maintenance therapies. |
| Reimbursement Strategy | CMS and provincial health authority equivalence campaigns for synthetic versus compounded formulations unlock margin expansion in combination therapy segments. |
Research Approach
Multi-period observation of FDA labeling update impacts, Health Canada/PMRA reimbursement adjustments, and prescription volume trajectories anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from FDA filings, Health Canada/PMRA submissions, ClinicalTrials.gov, and provincial formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing provided triangulation across data sources.
Input-output matrices connected active pharmaceutical ingredient supply concentrations in U.S. Gulf Coast and Atlantic Canada corridors to downstream formulation capacity and distribution network economics across the analysis window. Segmentation dimensions modeled included product chemistry, delivery physics, care setting economics, and regional regulatory cluster. CAGRs derived from patient demographic projections, specialist density mapping, and reimbursement policy scenario analysis informed volume and value outputs.
The model holds under stable FDA and Health Canada/PMRA regulatory trajectories; deviation in bioidentical hormone categorization rulings or thromboembolic risk profiling stringency would shift competitive positioning and margin structures. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nicotine Replacement Therapy (NRT) Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Calcimimetic Market
Pharmaceuticals
Saudi Arabia Diabetes Drugs Market
Pharmaceuticals
Botulinum Toxin Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Global Shingles Vaccine Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
Global Loratadine Market
Pharmaceuticals
Global Autism Spectrum Disorder Therapeutics Market
Pharmaceuticals
North America SGLT2 Inhibitors Market
Pharmaceuticals
Global Androgen Deprivation Therapy Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market