
 Musculoskeletal Disorders Drugs Market | 2026-2036
Musculoskeletal Disorders Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Musculoskeletal Disorders Drugs Market Analysis
Hospital procurement of musculoskeletal therapies is collapsing toward centralized infusion networks that capture specialty pharmacy margins previously retained by physician offices. AbbVie leverages its immunology manufacturing scale to sustain Humira-era infrastructure amid biosimilar erosion. Pfizer competes through vertically integrated sterile injectable capacity that anchors hospital contract positioning.
Musculoskeletal disorders drugs comprise pharmacological agents targeting inflammation, bone metabolism, and pain signaling in conditions affecting joints, muscles, and connective tissue, typically formulated as small molecules, monoclonal antibodies, or peptide conjugates requiring cold-chain distribution. These agents serve to modify disease progression, manage acute flares, or restore structural integrity in degenerative and autoimmune conditions. Biologics command the dominant margin pool despite patent cliffs, while NSAIDs occupy high-volume, low-price positioning across retail pharmacy channels. Injectable delivery modes attract investment as home-infusion capabilities expand, though oral formulations retain share in osteoporosis maintenance therapy where patient self-administration drives adherence.
The FDA biosimilar framework and EMA's scientific advice pathways shape development timelines and interchangeability standards for biologic entrants seeking reference product market access. REACH compliance and ECHA substance evaluations constrain excipient sourcing for European formulation supply chains, while India's CDSCO accelerates local trial requirements for imported musculoskeletal agents. Stakeholders must monitor biosimilar substitution legislation at state level in the US and hospital formulary consolidation trends that determine commercial access for novel mechanisms.
Market Dynamics
Hospital systems are consolidating musculoskeletal therapy administration into captive infusion networks, capturing specialty pharmacy margins that previously flowed to independent rheumatology and orthopedics practices.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage for home infusion services accelerates patient migration from clinic-based to residential biologic administration.
- EMA biosimilar scientific advice pathways:Streamlined European development timelines compress regulatory uncertainty for follow-on biologics targeting TNF-alpha and IL-6 mechanisms.
- Cold-chain infrastructure densification:Third-party logistics networks in the United States now support same-day temperature-controlled delivery to suburban markets previously deemed unreachable.
Market Restraints
- Reference biologic price erosion:Interchangeable biosimilar substitution laws in multiple US states compress net realized prices for originator molecules.
- Active pharmaceutical ingredient concentration:Mammalian cell culture capacity clusters in Ireland, Singapore, and Puerto Rico, creating geographic vulnerability to single-site disruption.
- Biologic-to-small-molecule switching:JAK inhibitors for rheumatoid arthritis capture patients who would otherwise escalate to injectable therapy.
Strategic Opportunities
- Subcutaneous formulation development:Self-administered biologics bypass infusion center dependency and expand addressable populations in rural geographies.
- India CDSCO accelerated approval:Local trial waivers for reference products already approved in ICH jurisdictions open faster market entry for imported agents.
- Digital therapeutic adjuvants:Software-based exercise and pain management protocols bundled with pharmacotherapy create differentiated reimbursement codes.
Industry Challenges
- Cell line development expertise scarcity:Mammalian expression system optimization requires specialized talent pools concentrated in Boston and Basel metropolitan clusters.
- Serialization compliance timelines:EU MDR and US DSCSA track-and-trace mandates force packaging line retrofits that disrupt supply continuity.
- Legacy EHR integration friction:Hospital formulary decision support systems resist real-time biosimilar interchangeability flags, delaying substitution at the point of prescribing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Musculoskeletal Disorders Drugs Market |
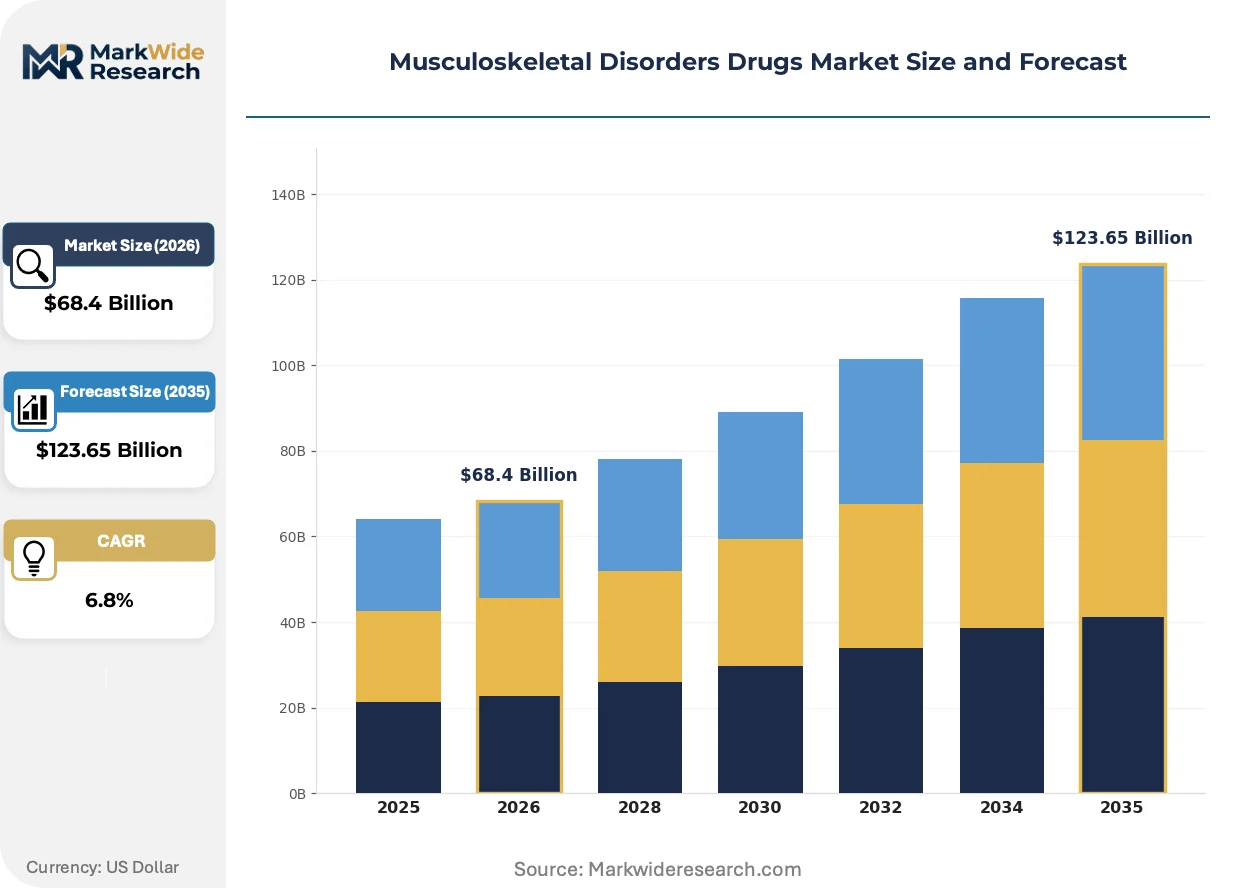
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, Corticosteroids, DMARDs, Biologics Delivery Mode: Injectable, Oral, Transdermal, Intravenous End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Rheumatoid Arthritis, Osteoporosis, Pain Management, Inflammatory Disorders |
| Companies Covered | Amgen Inc., Merck & Co. Inc., AbbVie Inc., Sanofi S.A., Eli Lilly and Company, Pfizer Inc., Johnson & Johnson Services Inc., Roche Holding AG, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Musculoskeletal Disorders Drugs Market Emerging Trajectories
Injectable delivery systems are converging with connected health infrastructure, enabling remote monitoring of adherence and adverse events while compressing the role of traditional infusion nursing.
Wearable injection devices now integrate Bluetooth-enabled dose tracking and temperature logging. Rheumatology practices in the United States are piloting these systems for patient cohorts with demonstrated adherence gaps. The technology is miniaturizing the clinical footprint required for biologic therapy initiation, allowing earlier-stage patients to begin treatment in primary care settings.
REACH substance evaluation under ECHA is restricting phthalate-based plasticizers in pre-filled syringe components. European formulation suppliers are accelerating migration to bio-based alternatives ahead of 2026 sunset dates. Injectable drug-device combination products face reformulation timelines that compress competitive windows for products nearing patent expiry.
Hospital pharmacy directors are unbundling drug acquisition from administration services, negotiating separate contracts for biologic molecules and infusion labor. Specialty pharmacy benefit managers are capturing these disaggregated contracts through 340B-eligible entities. The shift is most visible in Medicare Advantage populations where capitated payments incentivize site-of-care migration to lower-cost settings.
Musculoskeletal Disorders Drugs Market Segmentation
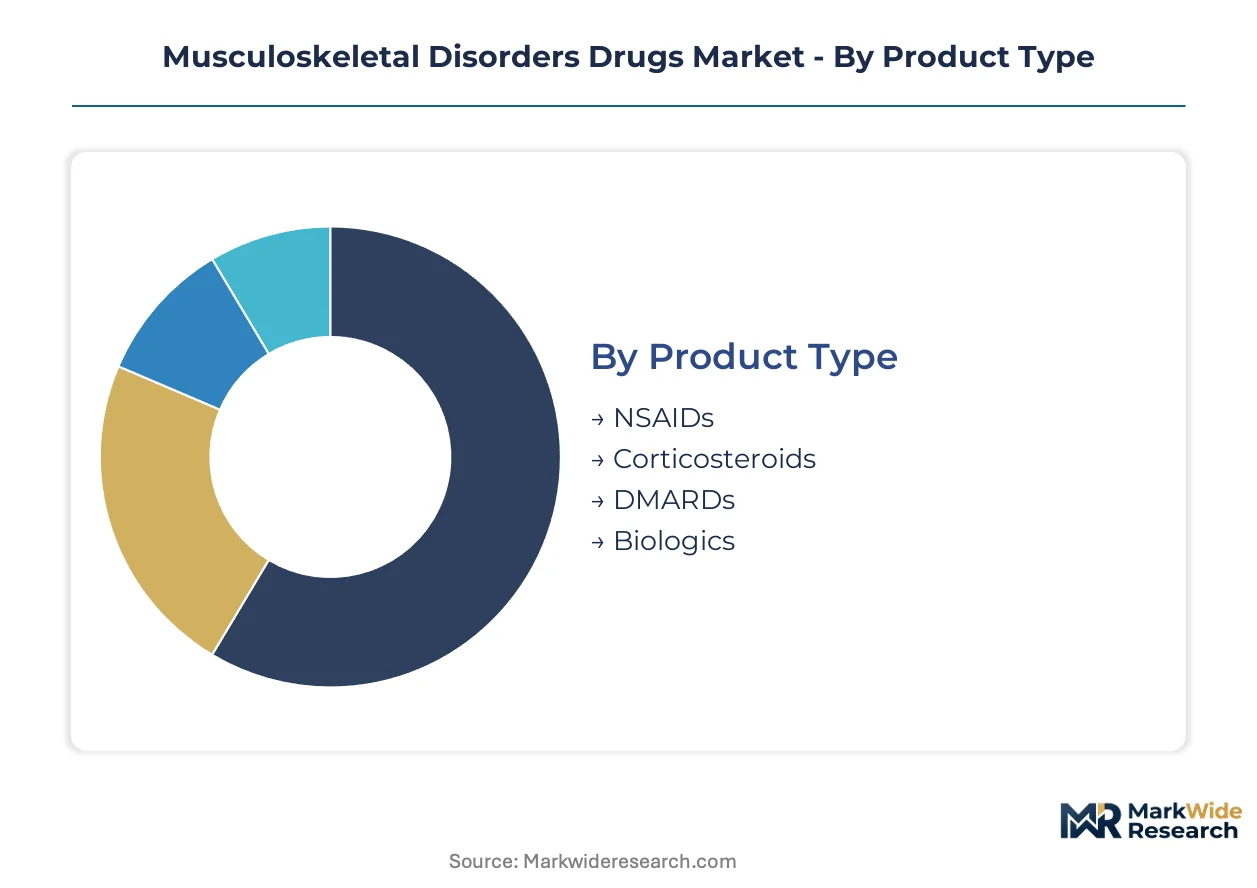
Channel mix determines margin capture across musculoskeletal therapy distribution. Hospital infusion networks, retail pharmacy, and direct-to-patient channels each favor distinct formulation types and administration modes.
Product Type:
Biologics and DMARDs flow predominantly through hospital specialty pharmacy and captive infusion centers, while NSAIDs and corticosteroids saturate retail and ambulatory channels.
- Biologics:Monoclonal antibodies and fusion proteins targeting TNF-alpha, IL-6, and IL-17 pathways require cold-chain distribution and refrigerated storage at infusion sites. Demand concentrates in Medicare Advantage populations where hospital systems capture administration margins through vertically integrated specialty pharmacies.
- DMARDs:Conventional synthetic agents including methotrexate and hydroxychloroquine serve as first-line therapy in rheumatoid arthritis, with prescribing concentrated in rheumatology practices migrating toward hospital employment. These molecules anchor step-therapy protocols that gate biologic access.
- NSAIDs:High-volume oral and topical formulations distributed through retail pharmacy chains with minimal clinical oversight.
- Corticosteroids:Injectable and oral formulations bridging acute flares and maintenance therapy across ambulatory settings.
By volume, NSAIDs lead. By growth pace, biologics are expanding most quickly.
Delivery Mode:
Cost tier stratification separates hospital-administered intravenous biologics from self-administered subcutaneous alternatives and commodity oral tablets.
- Injectable:Pre-filled syringes and auto-injectors for subcutaneous biologic administration enable home-based therapy initiation. Patient self-administration reduces infusion center dependency and expands rural access where rheumatology specialists are scarce.
- Intravenous:Hospital and ambulatory infusion center administration of infliximab and other biologics captures higher reimbursement rates under Medicare Part B. Site-of-care consolidation is compressing independent clinic volume toward hospital-owned networks.
- Oral:Small-molecule JAK inhibitors and traditional NSAIDs dominate retail pharmacy dispensing with generic substitution pressure.
- Transdermal:Topical NSAIDs and lidocaine patches serve localized pain management with lower systemic exposure.
By revenue concentration, intravenous leads. By patient preference shift, injectable subcutaneous formulations are gaining share fastest.
End User:
Customer type determines procurement authority and formulary control, with hospital systems exercising consolidated purchasing power over independent practices.
- Hospitals:Integrated delivery networks negotiate enterprise contracts for biologic molecules and infusion services, leveraging 340B eligibility to capture specialty pharmacy margins. Pharmacy and therapeutics committees gate access to novel mechanisms.
- Home Care:Home infusion agencies and visiting nurse services administer biologics to patients meeting stability criteria, with CMS reimbursement expansion accelerating site-of-care migration from clinic to residential settings.
- Clinics:Independent rheumatology and orthopedic practices retain oral therapy prescribing but lose biologic administration volume to hospital-affiliated infusion centers.
- Pharmacies:Retail and specialty pharmacy channels dispense oral maintenance therapies with limited clinical integration.
By prescription volume, pharmacies lead. By value capture, hospitals are climbing the fastest.
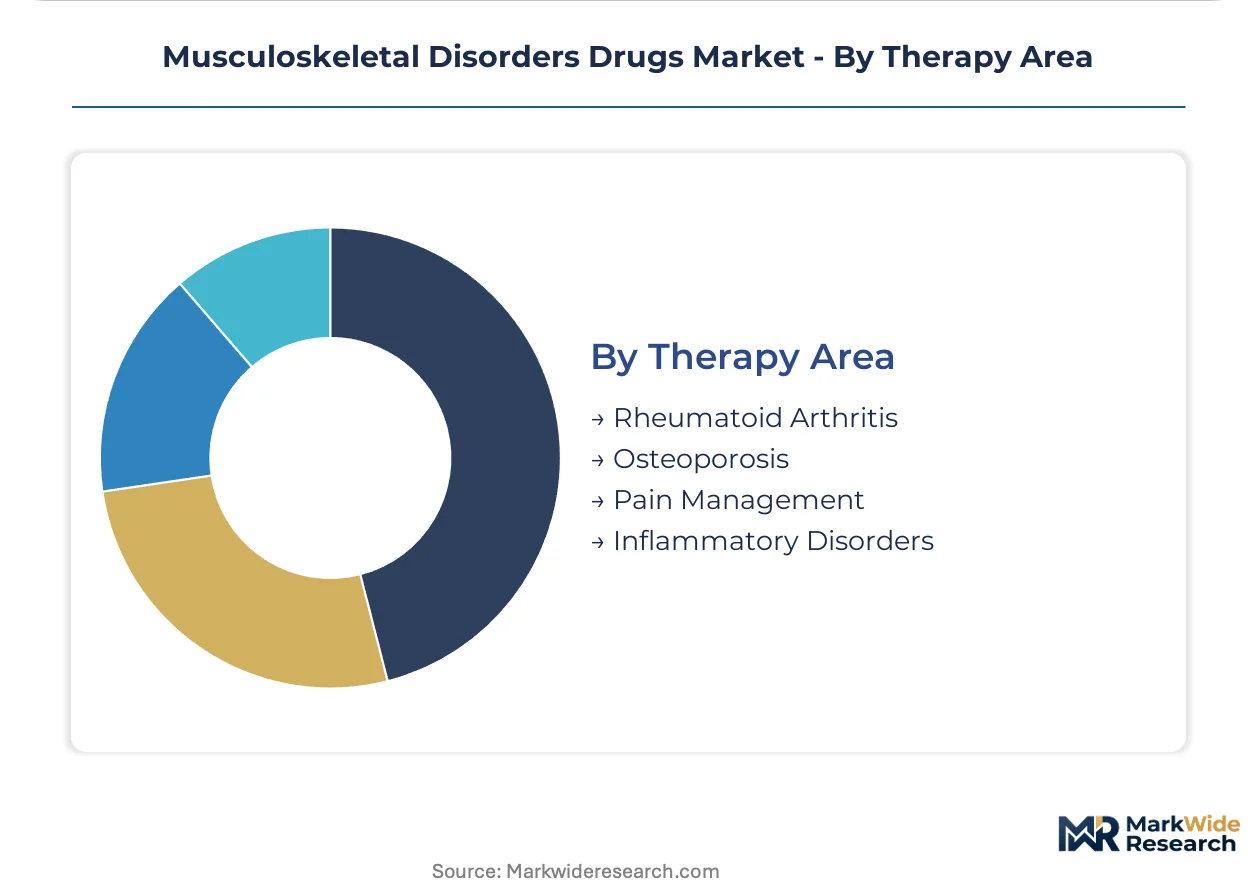
Therapy Area:
Maturity varies across indications, with rheumatoid arthritis exhibiting saturated biologic penetration and osteoporosis maintenance relying on oral bisphosphonate adherence programs.
- Rheumatoid Arthritis:TNF-alpha inhibitor biosimilar erosion is reshaping competitive dynamics, with interchangeable substitution laws in multiple US states accelerating price compression. JAK inhibitors are displacing some biologic-naive patients from injectable therapy paths.
- Pain Management:Opioid-sparing protocols are expanding NSAID and topical analgesic utilization in post-surgical and chronic low-back populations.
- Osteoporosis:Oral bisphosphonates dominate first-line therapy, with denosumab and anabolic agents reserved for high-fracture-risk patients.
- Inflammatory Disorders:Psoriatic arthritis and ankylosing spondylitis represent expansion indications for existing rheumatoid arthritis mechanisms.
By patient population size, pain management leads. By novel mechanism investment, rheumatoid arthritis shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Irish biologics manufacturing clusters export active pharmaceutical ingredients to United States hospital systems, anchoring transatlantic supply chains for monoclonal antibody therapies targeting rheumatoid arthritis and osteoporosis.
United States
Medicare Advantage enrollment growth drives site-of-care consolidation toward hospital-owned infusion networks. FDA interchangeability guidelines for biosimilars accelerate substitution at pharmacy level. Boston metropolitan clusters concentrate cell line development expertise serving contract manufacturing organizations supplying domestic biologic fill-finish capacity.
Germany
EMA centralized marketing authorizations streamline pan-European launch pathways for novel JAK inhibitors and IL-6 pathway biologics. REACH substance evaluations under ECHA force pre-filled syringe component reformulation ahead of 2026 compliance deadlines. Frankfurt-Rhine-Main logistics corridors densify cold-chain distribution infrastructure for temperature-sensitive musculoskeletal therapies.
Japan
Aging demographics expand addressable populations for osteoporosis anabolic agents and rheumatoid arthritis maintenance biologics. PMDA sakigake designation accelerates priority review timelines for first-in-class mechanisms. Tokyo-Osaka pharmaceutical manufacturing belts concentrate mammalian cell culture capacity serving domestic and Asia-Pacific export markets.
India
CDSCO accelerated approval pathways waive local trial requirements for reference products already approved in ICH jurisdictions, compressing market entry timelines for imported biologics. Government production-linked incentive schemes expand domestic fill-finish capacity. Hyderabad and Bengaluru biotech clusters attract contract development investments from multinational sponsors seeking cost-competitive manufacturing.
Switzerland
Swissmedic parallel scientific advice with EMA reduces regulatory redundancy for biologic developers maintaining European headquarters. Basel metropolitan area concentrates monoclonal antibody discovery infrastructure alongside legacy small-molecule chemistry expertise. Geneva-based logistics providers specialize in temperature-controlled distribution for high-value injectable therapies.
Musculoskeletal Disorders Drugs Market Vendor Landscape
Player mix skews toward vertically integrated biopharmaceutical conglomerates with captive manufacturing infrastructure. Market structure concentrates around entities controlling mammalian cell culture capacity and sterile injectable fill-finish networks. Three archetypes dominate: originator biologic developers defending patent-protected portfolios, biosimilar manufacturers exploiting FDA interchangeability pathways, and diversified pharmaceutical conglomerates leveraging hospital contract bundling. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with participants securing dedicated bioreactor suites and forming co-development alliances for subcutaneous formulation platforms.
Within the diversified conglomerate tier, Pfizer Inc. and Johnson & Johnson Services Inc. exemplify entities with vertically integrated sterile injectable capacity that anchors hospital formulary positioning. AbbVie Inc. occupies a position representing originator biologic developers managing infrastructure transition amid biosimilar erosion. Roche Holding AG and Novartis AG sit within the European-headquartered archetype, leveraging Basel-region manufacturing density and EMA regulatory proximity to compress development timelines for follow-on biologics.
| Leading Market Players |
|---|
| Amgen Inc. |
| Merck & Co. Inc. |
| AbbVie Inc. |
| Sanofi S.A. |
| Eli Lilly and Company |
| Pfizer Inc. |
| Johnson & Johnson Services Inc. |
| Roche Holding AG |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Biosimilar substitution for reference TNF-alpha inhibitors is compressing originator pricing premiums while simultaneously shifting procurement authority toward hospital systems with captive 340B-eligible specialty pharmacies. This substitution dynamic redistributes margin capture from manufacturer to administrator and concentrates fill-finish demand in Irish and Puerto Rican mammalian cell culture clusters.
Pricing Analysis
Next-generation subcutaneous biologics command premium positioning against intravenous predecessors, while oral JAK inhibitors undercut both on convenience and total cost of care. Three-tier pricing structure across originator biologics, interchangeable biosimilars, and small-molecule alternatives reflects patent status and administration complexity. Cost compression in the biosimilar tier is intensifying because state-level interchangeability laws accelerate pharmacy-level substitution. Medicare Advantage plans exhibit highest price sensitivity due to capitated reimbursement structures, while self-pay patients in emerging markets face the steepest access barriers.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore is extending lead times for temperature-controlled containers moving active pharmaceutical ingredients from Ireland to United States fill-finish sites. Mammalian cell culture capacity draws from Ireland, Singapore, and Puerto Rico, with monoclonal antibody production resting on CHO cell line availability and single-use bioreactor supply. Single-source vulnerability concentrates in proprietary cell line development expertise clustered around Boston and Basel. Distribution runs through hospital-owned specialty pharmacy networks that capture 340B pricing advantages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The musculoskeletal disorders drugs market is recovering from biosimilar-induced margin compression as novel IL-6 and IL-17 pathway biologics refresh patent-protected portfolios. Medicare reimbursement expansion for home infusion services provides the cyclical uplift.
For Market Incumbents: Consolidate manufacturing scale in Puerto Rico and Ireland to defend against biosimilar volume erosion. Lock in hospital system contracts through bundled molecule-plus-administration pricing that leverages 340B eligibility. Cell line development expertise scarcity in Boston and Basel metropolitan clusters represents a defendable moat.
For New Entrants and Emerging Players: Anchor in subcutaneous formulation development for rural markets where rheumatology specialist scarcity creates adherence gaps. Target India CDSCO accelerated approval pathways for reference products already approved in ICH jurisdictions. Partner with third-party logistics networks offering same-day cold-chain delivery to bypass hospital infusion center dependency.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations holding dedicated bioreactor suites in Singapore and Ireland. Five-to-ten year viability hinges on mammalian cell culture capacity expansion outpacing biosimilar demand. Monitor FDA interchangeability designation velocity as the inflection signal for originator portfolio erosion rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Self-administered biologics bypass hospital infusion center capture and expand rural patient access. |
| Biosimilar Interchangeability Pathway | FDA designation accelerates pharmacy-level substitution and compresses originator net realized prices. |
| 340B-Eligible Specialty Pharmacy Expansion | Hospital systems capture specialty pharmacy margins previously retained by independent rheumatology practices. |
| CDSCO Accelerated Approval | Local trial waivers compress market entry timelines for imported biologics into Indian commercial channels. |
| Digital Therapeutic Adjuvant Bundling | Software-based exercise protocols create differentiated reimbursement codes alongside pharmacotherapy. |
Methodological Framework
A standing panel of formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists provided ongoing calibration against secondary validation from FDA biosimilar approval databases, EMA scientific advice records, CMS Medicare reimbursement schedules, and hospital 340B program reports. Bottom-up patient population estimates and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs before finalization. The analytical framework modeled therapy area, delivery mode, end-user channel, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from segment-level growth trajectories incorporated biosimilar erosion curves, Medicare Advantage enrollment shifts, and subcutaneous formulation adoption rates.
Material uncertainties — biosimilar interchangeability legislation velocity, mammalian cell culture single-site disruption, JAK inhibitor safety profile revisions — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
North America Biguanide Market
Pharmaceuticals
Second Generation Cephalosporins Market
Pharmaceuticals
Immunoglobulin Market
Pharmaceuticals
China Human Papillomavirus Vaccine Market
Pharmaceuticals
Preeclampsia Therapeutics Market
Pharmaceuticals
Global Preventive Vaccines Market
Pharmaceuticals
Endocarditis Drugs Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Advanced Therapy Medicinal Products CDMO Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market